
 Pyrolysis Gasoline Market | 2026-2036
Pyrolysis Gasoline Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrolysis Gasoline Market Analytics
REACH compliance in Europe is repositioning the cost-of-entry calculus for pyrolysis gasoline traders seeking EU market access. Chevron Phillips Chemical Company leverages its Gulf Coast infrastructure to sustain high-volume exports across multiple regulatory jurisdictions. Shell anchors its competitive stance through integrated refining-petrochemical complexes that internalize pygas upgrading costs. Dow differentiates via specialized hydrogenation capabilities that yield polymer-grade benzene from raw pyrolysis gasoline streams.
Pyrolysis gasoline denotes the C5-plus liquid fraction produced during steam cracking of naphtha or gas feedstocks, containing aromatics such as benzene, toluene, and xylenes alongside olefinic and diolefinic components that require hydrotreating before downstream use. The material serves primarily as a refinery blending component and as a chemical industry feedstock for BTX extraction and subsequent polymer synthesis. Conventional pyrolysis gasoline dominates current trade volumes owing to established refinery offtake agreements and lower processing overhead, while high-octane pyrolysis gasoline captures expanding margin pools as fuel specifications tighten in Asian markets. Chemical synthesis applications represent the fastest-growing demand channel as petrochemical plants prioritize aromatics recovery over direct fuel blending.
EPA fuel standards in the United States, REACH registration requirements in Europe, and China's GB standards for aromatic content collectively shape product specifications, testing protocols, and cross-border shipment eligibility for pyrolysis gasoline. These frameworks compel producers to maintain dual-certification capabilities or accept geographic market restrictions. Stakeholders must monitor regulatory divergence between jurisdictions to optimize processing investments and offtake contracting structures.
Market Dynamics
EU Green Deal carbon intensity benchmarks are forcing refiners to requalify pyrolysis gasoline feedstocks, compressing the viable supplier base while elevating hydrogenated grades in contract negotiations.
Growth Catalysts
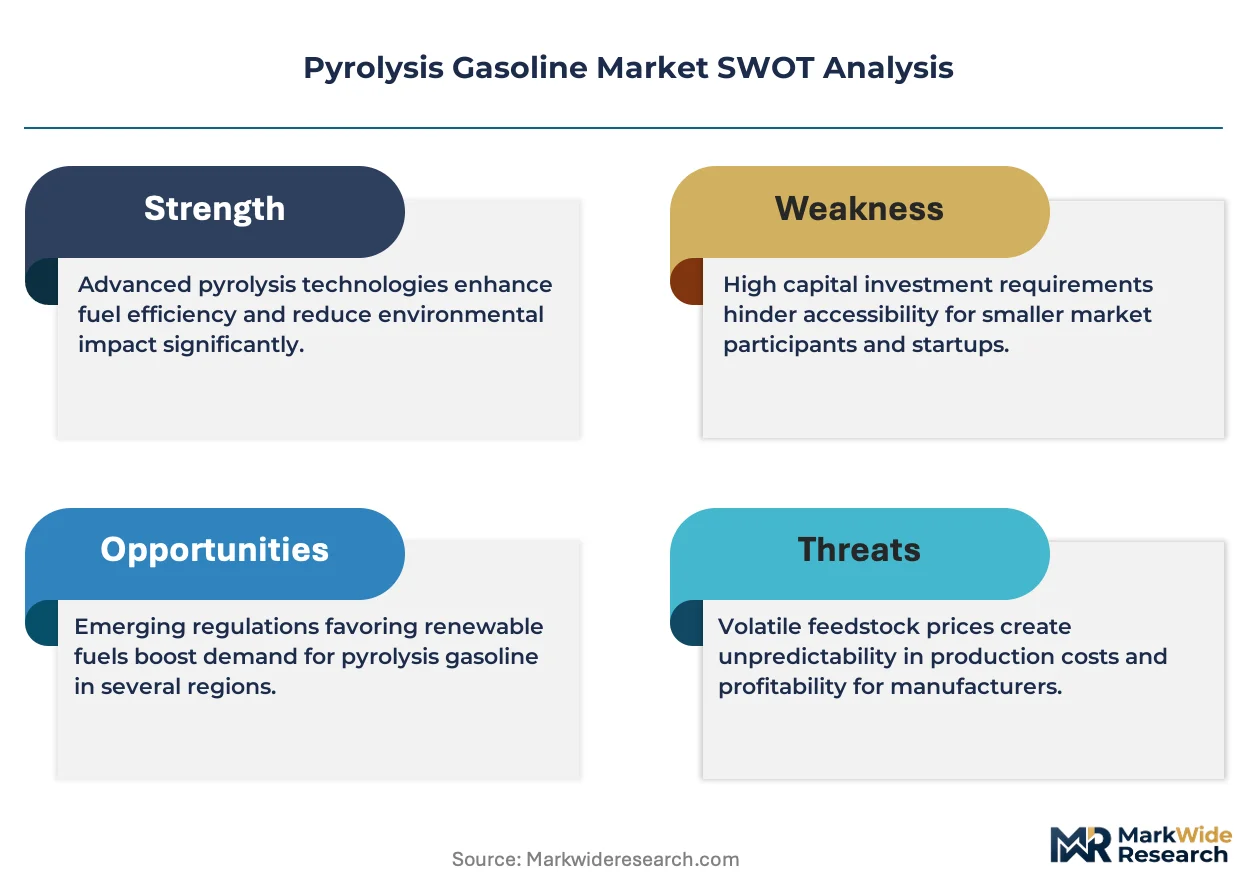
- BTX extraction demand:Chemical manufacturers prioritize aromatics recovery from pygas streams over direct fuel blending, pulling volumes into higher-margin chemical synthesis channels.
- REACH compliance:Registration requirements for hazardous substance imports are filtering out non-compliant traders, consolidating market access for certified suppliers.
- India domestic supply expansion:ONGC Petro additions Limited and Haldia Petrochemicals Limited capacity additions are reducing import dependence and anchoring regional demand growth.
Market Restraints
- Naphtha feedstock volatility:Crude-linked naphtha pricing transmits cost instability directly into pygas production economics, compressing margin predictability for non-integrated producers.
- Hydrogen supply concentration:Steam crackers in the US Gulf Coast and Middle East dominate merchant hydrogen availability, creating geographic dependency for hydrotreating capacity.
- Diolefin saturation limits:Conventional selective hydrogenation cannot fully stabilize highly unsaturated pygas fractions without octane loss, constraining direct gasoline blending ratios.
Strategic Opportunities
- Circular feedstock integration:Chemical recyclers are piloting pyrolysis gasoline co-processing with plastic-derived oils, opening new raw material sourcing channels for crackers.
- Polymer-grade benzene premiums:Dow's specialized hydrogenation pathway demonstrates technical feasibility for capturing value spreads between fuel-grade and chemical-grade specifications.
- Digital assay contracting:Real-time BTX composition monitoring via inline spectroscopy is enabling quality-adjusted pricing mechanisms in long-term offtake agreements.
Industry Challenges
- Hydrotreater catalyst expertise:Specialized knowledge in noble-metal catalyst management for pygas upgrading is concentrated among aging technical workforces in European and US refining centers.
- Dual-certification complexity:Maintaining simultaneous EPA fuel standard compliance and REACH registration requires parallel quality systems that extend product release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrolysis Gasoline Market |
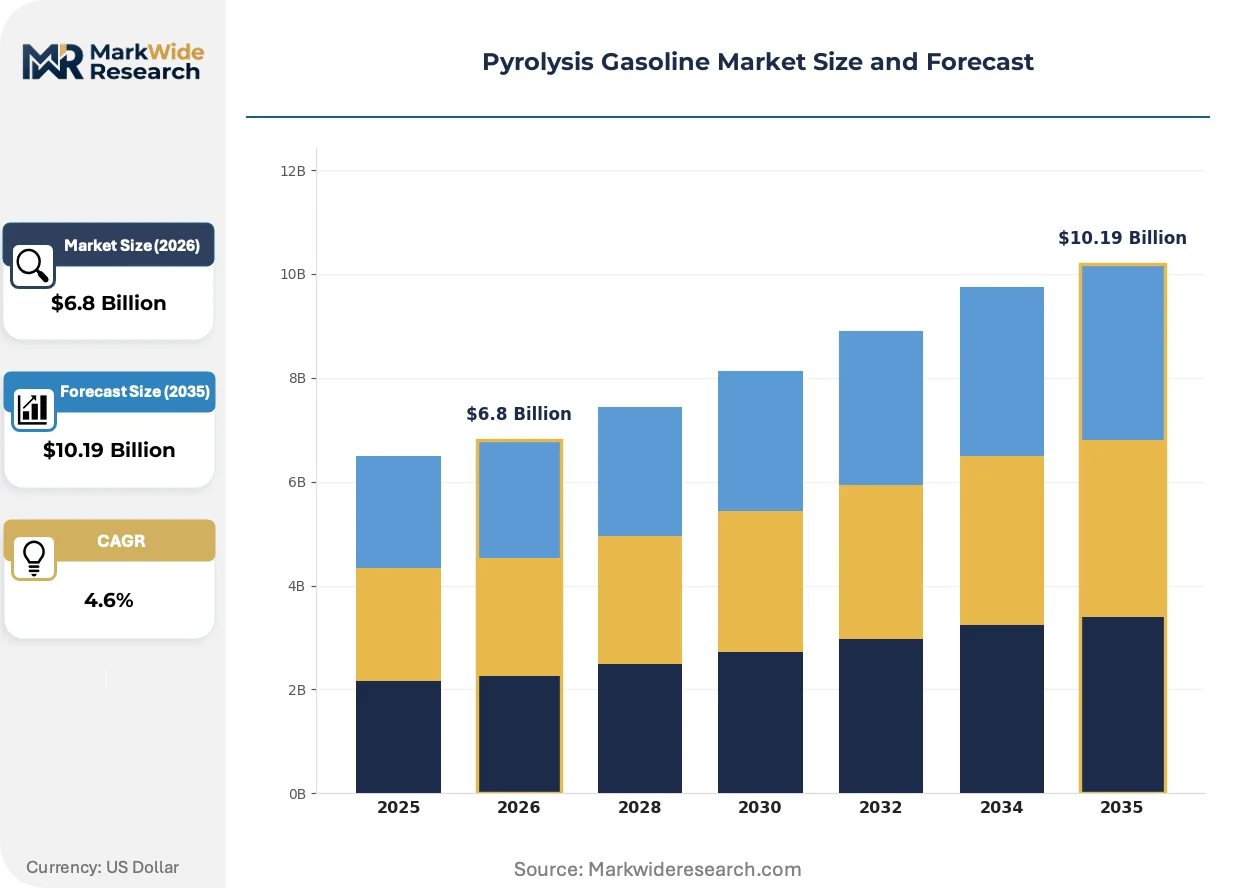
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Pyrolysis Gasoline, High-Octane Pyrolysis Gasoline, Light Pyrolysis Oil, Heavy Pyrolysis Oil End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Fuel Blending Facilities Distribution Channel: Wholesale, Retail, Direct Sales, Online Platforms Application: Fuel Production, Chemical Synthesis, Solvent Applications, Additives |
| Companies Covered | Haldia Petrochemicals Limited, Chevron Phillips Chemical Company, Shell, Ras Laffan Olefins Company Limited, Dow, Exxon Mobil Corporation, ONGC Petro additions Limited, Jam Petrochemical Company, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrolysis Gasoline Market Evolving Landscape
Process intensification and regulatory digitization are converging to redefine how pyrolysis gasoline quality is assured, contracted, and traced across multi-jurisdictional supply chains.
Advanced membrane separation for aromatics extraction is electrifying the conventional hydrotreating-BTX recovery sequence. Petrochemical integrators in South Korea and Germany are piloting hybrid membrane-distillation configurations that cut hydrogen consumption by half. This technology is compressing the capital intensity gap between fuel-blending and chemical-grade pygas upgrading, enabling smaller crackers to capture chemical synthesis premiums.
REACH Article 33 supply chain communication obligations now mandate granular substance disclosure for pygas shipments above threshold concentrations. ECHA enforcement actions against incomplete safety data sheets are triggering contractual penalty clauses in EU offtake agreements. Aromatics traders are responding by embedding third-party assay verification into standard delivery terms, shifting compliance liability upstream to producers.
Buyers are consolidating procurement around integrated refinery-petrochemical complexes capable of certifying cradle-to-gate carbon intensity. Shell's internalized upgrading cost model is displacing merchant pygas spot purchases among European polymer producers. This concentration is most visible in the Rhine-Ruhr industrial cluster, where long-term framework agreements now specify maximum allowable Scope 3 emissions per ton of benzene equivalent delivered.
Pyrolysis Gasoline Market Segmentation
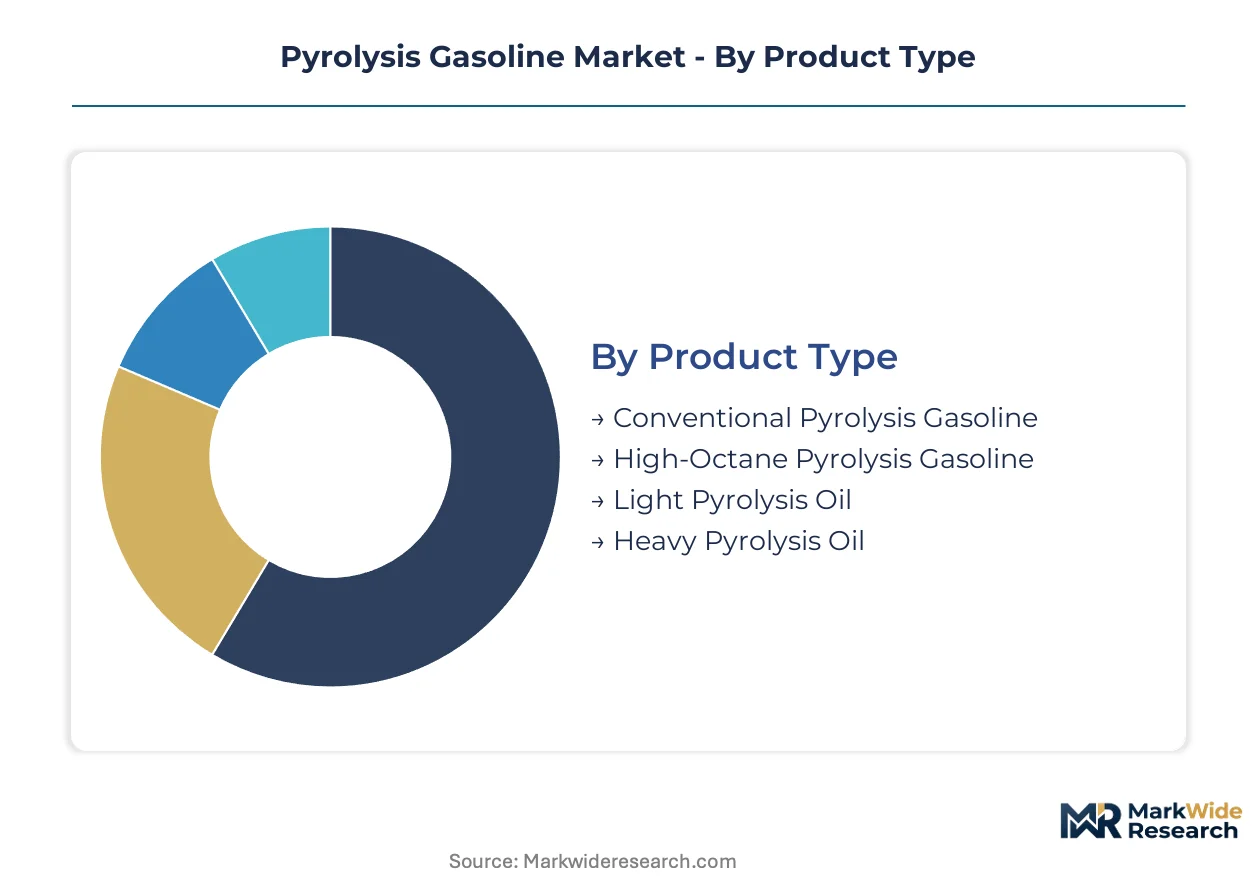
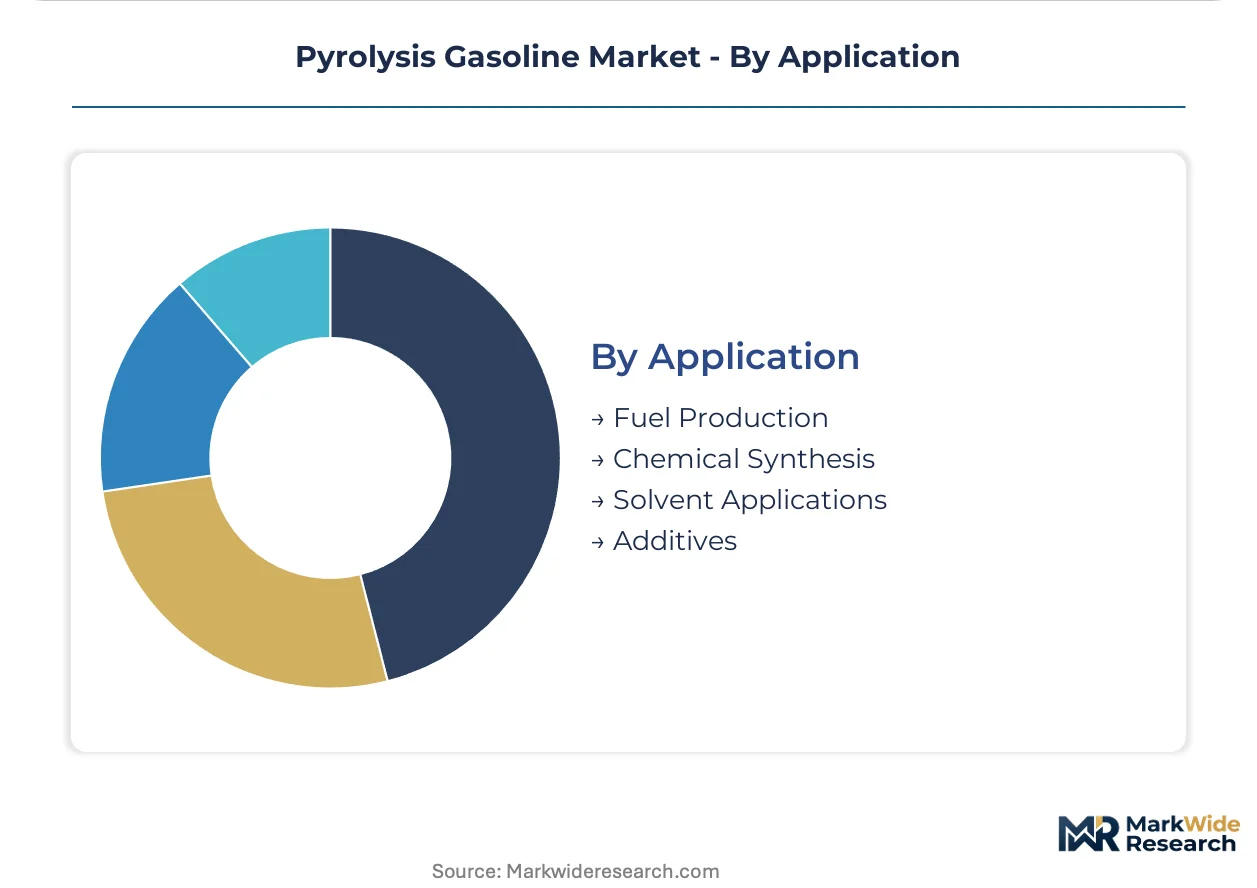
Segmentation in pyrolysis gasoline markets reveals how product specifications, customer integration depth, and channel economics fragment value capture. Traders, integrated refiners, and specialty chemical buyers each operate under distinct procurement logics that reshape contract structures and pricing mechanisms.
Product Type:
The customization-standardization spectrum runs from commodity fuel blending stocks to precision chemical feedstocks requiring hydrotreater certification.
- Conventional Pyrolysis Gasoline:Contains unhydrogenated C5-C12 aromatics and olefins at 30-50% diolefin content, requiring downstream stabilization before refinery blending. Demand concentrates in US Gulf Coast refineries under EPA fuel standards, constrained by hydrogen supply bottlenecks for saturation treatment.
- High-Octane Pyrolysis Gasoline:Achieves 95+ RON through selective hydrogenation that preserves aromatics while saturating diolefins. Expansion concentrates in India where ONGC Petro additions Limited and Haldia Petrochemicals Limited anchor domestic supply for tightening fuel specifications.
- Light Pyrolysis Oil:C5-C8 fraction rich in benzene and toluene precursors, routed primarily to BTX extraction units.
- Heavy Pyrolysis Oil:C9-plus fraction with higher xylene and indene content, favoring chemical synthesis over fuel applications.
Most installed capacity flows through Conventional Pyrolysis Gasoline. Expansion is steepest in High-Octane Pyrolysis Gasoline.
End User:
Customer type determines whether pygas flows into captive upgrading or merchant market arbitrage.
- Refineries:Absorb raw pygas as gasoline pool extenders, leveraging existing hydrotreating capacity for diolefin saturation. Gulf Coast refiners under EPA Tier 3 sulfur standards drive specification tightening.
- Petrochemical Plants:Prioritize aromatics recovery over fuel value, pulling pygas into BTX extraction sequences. Rhine-Ruhr clusters under EU Green Deal carbon benchmarks are consolidating procurement around integrated suppliers.
- Chemical Manufacturers:Source hydrotreated grades for polymer-grade benzene production, constrained by REACH registration requirements for hazardous substance handling.
- Fuel Blending Facilities:Purchase spot volumes for octane enhancement, exposed to naphtha feedstock volatility.
Refineries command the largest volume offtake. Petrochemical Plants are climbing the fastest as aromatics recovery margins widen.
Distribution Channel:
Channel selection tracks customer scale and certification burden.
- Wholesale:Aggregates volumes from multiple crackers for resale to non-integrated refiners, dominating cross-border trade.
- Retail:Serves small fuel blenders with drum and tote shipments, fragmented across regional distributors.
- Direct Sales:Long-term framework agreements between integrated producers and polymer manufacturers, embedding carbon intensity clauses.
- Online Platforms:Emerging for spot assay-verified transactions, constrained by REACH Article 33 documentation requirements.
Wholesale channels handle the majority of traded volume. Direct Sales are expanding most quickly as procurement consolidates around integrated suppliers.
Application:
Application segmentation splits pygas between combustion value and molecular reconstruction pathways.
- Fuel Production:Blends into gasoline pools for octane enhancement, constrained by diolefin saturation limits that affect storage stability.
- Chemical Synthesis:BTX extraction for polymer feedstocks, gaining share as steam crackers prioritize aromatics over fuel blending.
- Solvent Applications:Toluene and xylene fractions diverted to industrial cleaning and coatings, exposed to VOC regulations.
- Additives:Specialized indene and dicyclopentadiene derivatives for rubber processing and adhesive formulations.
Fuel Production absorbs the greatest volume. Chemical Synthesis shows the steepest expansion trajectory as petrochemical margins favor aromatics recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrotreater engineers and catalyst specialists concentrate along the US Gulf Coast, the Rhine-Ruhr corridor, and India's eastern refining belt, anchoring pyrolysis gasoline processing expertise in these three geographies.
United States
EPA Tier 3 sulfur standards drive specification tightening for refinery blending applications. Chevron Phillips Chemical Company leverages Gulf Coast infrastructure to sustain high-volume exports across multiple regulatory jurisdictions. Houston-area crackers supply merchant pygas to domestic refiners constrained by hydrogen supply bottlenecks.
Germany
REACH Article 33 supply chain communication obligations mandate granular substance disclosure for pygas shipments above threshold concentrations. ECHA enforcement actions against incomplete safety data sheets trigger contractual penalty clauses in EU offtake agreements. The Rhine-Ruhr industrial cluster consolidates procurement around integrated suppliers certifying cradle-to-gate carbon intensity.
India
ONGC Petro additions Limited and Haldia Petrochemicals Limited anchor domestic supply expansion, reducing import dependence. BIS standards for aromatic content shape product specifications and testing protocols. Haldia and Paradip industrial corridors host capacity additions that pull regional demand growth.
China
GB standards for aromatic content regulate domestic pygas quality and cross-border shipment eligibility. MIIT guidelines on dual carbon goals compress the viable supplier base for high-carbon intensity feedstocks. Yangtze River Delta petrochemical integrators pilot hybrid membrane-distillation configurations for aromatics extraction.
Saudi Arabia
SABIC's integrated refining-petrochemical complexes internalize pygas upgrading costs across the Kingdom's eastern province. The country's national industrial regulator enforces product quality benchmarks for downstream chemical synthesis applications. Ras Laffan industrial city concentrates olefins production that generates pygas as a co-product stream.
Pyrolysis Gasoline Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across pyrolysis gasoline value capture. The market structure shows moderate consolidation around integrated refinery-petrochemical complexes and regional chemical manufacturers with captive steam cracking capacity. Three archetypes dominate: Gulf Coast export-oriented majors, European REACH-certified integrators, and India-based domestic suppliers. Competitive moves concentrate on backward integration into naphtha feedstock sourcing and technology licensing for specialized hydrogenation capabilities.
Among US-based chemical majors, Chevron Phillips Chemical Company and Dow exemplify divergent strategic positions—one optimizing Gulf Coast export infrastructure, the other capturing polymer-grade benzene premiums through specialized hydrogenation pathways. Shell anchors the European integrated tier through internalized upgrading cost models that displace merchant spot purchases. SABIC represents Middle Eastern scale advantages in olefins co-production economics.
| Leading Market Players |
|---|
| Haldia Petrochemicals Limited |
| Chevron Phillips Chemical Company |
| Shell |
| Ras Laffan Olefins Company Limited |
| Dow |
| Exxon Mobil Corporation |
| ONGC Petro additions Limited |
| Jam Petrochemical Company |
| SABIC |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon intensity benchmarks gate qualified supply for premium-tier pyrolysis gasoline, restricting contract eligibility to hydrogenated grades that command measurable premiums over conventional fuel-blending stocks. Buyers in the Rhine-Ruhr cluster now embed maximum Scope 3 emissions clauses into long-term offtake agreements, compressing the viable supplier base while elevating certified producers in contract negotiations.
Pricing Analysis
Commodity spot contracting dominates raw pygas transactions, while chemical-grade premiums attach to hydrotreated streams with REACH registration and polymer-grade benzene certification. Price differentiation rests on hydrogenation depth and carbon intensity disclosure, with integrated refiners capturing spreads that merchant traders forfeit to compliance costs. Pricing pressure stems from naphtha feedstock volatility transmitting crude-linked instability into margin predictability. Fuel blenders exhibit highest price sensitivity, while polymer manufacturers absorb premiums for supply security.
Supply Chain Analysis
India's domestic-content mandates under PLI scheme incentives are reshaping sourcing patterns, pulling capacity additions toward Haldia and Paradip industrial corridors. Geographic supply concentrates in the United States, Germany, and India, with merchant hydrogen availability tethered to Gulf Coast and Middle East steam cracker complexes. Raw material dependencies include naphtha feedstocks, noble-metal catalysts, and specialized hydrotreater engineering expertise. Single-source vulnerability runs through concentrated catalyst supply channels. Distribution runs through wholesale aggregators for cross-border trade and direct sales frameworks for integrated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pyrolysis gasoline hinges on hydrogenation capability premiums and carbon-intensity certification, with chemical-grade benzene recovery offering the clearest cost-down pathway through value-added upgrading.
For Market Incumbents: Acquire hydrotreater catalyst management expertise to defend against merchant trader displacement as REACH compliance filters non-certified suppliers. Consolidate procurement relationships in the Rhine-Ruhr cluster through cradle-to-gate carbon disclosure. Expand selective hydrogenation capacity to capture polymer-grade benzene premiums that Dow's specialized pathway has demonstrated.
For New Entrants and Emerging Players: Digital assay verification platforms offer the lowest-friction entry vector, enabling quality-adjusted contracting without legacy infrastructure burdens. Target India's eastern refining belt where ONGC Petro additions and Haldia Petrochemicals capacity expansion creates merchant supply gaps. Lead with inline spectroscopy partnerships that embed real-time BTX monitoring into standard delivery terms.
For Investors and Strategic Acquirers: Roll-up economics work for regional hydrogenation specialists because EU Green Deal compliance is compressing the certified supplier base faster than organic capacity expansion. Five-to-ten year viability favors integrated refinery-petrochemical complexes with captive naphtha sourcing and internalized upgrading cost models. Watch membrane-distillation pilot outcomes in South Korea and Germany as inflection signals for technology-driven margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Sourcing | Chevron Phillips and Shell internalize feedstock costs across Gulf Coast and Rhine-Ruhr infrastructure. |
| Specialized Hydrogenation Capacity Expansion | Dow's polymer-grade benzene pathway demonstrates technical feasibility for capturing chemical synthesis premiums. |
| REACH Certification Investment | ECHA enforcement actions against incomplete safety data sheets trigger contractual penalties that filter non-compliant traders. |
| Digital Assay Verification Partnerships | Real-time BTX composition monitoring via inline spectroscopy enables quality-adjusted pricing in long-term offtake agreements. |
| Circular Feedstock Co-Processing Pilots | Chemical recyclers pilot pygas co-processing with plastic-derived oils, opening alternative raw material channels for crackers. |
Research Methodology
Coverage spans the United States, Germany, India, China, and Saudi Arabia, with primary inputs from each region combined with secondary validation. Interviews engaged plant managers at steam cracking facilities, procurement leads at downstream petrochemical integrators, distribution channel partners in wholesale pygas trading, and technical R&D directors specializing in hydrotreater catalyst systems. Secondary sources included customs and trade flow databases, American Chemistry Council and Cefic industry reports, SEC 10-K filings from disclosed chemical majors, ECHA registration dossiers, and BIS standard documentation. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Granularity extended to product type splits across conventional, high-octane, light, and heavy pyrolysis gasoline fractions, end-user segmentation among refineries, petrochemical plants, chemical manufacturers, and fuel blending facilities, and distribution channel differentiation between wholesale, retail, direct sales, and emerging online platforms. CAGRs were derived from segment-level growth trajectories applied across the projection horizon. Industry-specific inputs incorporated naphtha-naphtha spread forecasting, hydrogen supply availability curves, and regulatory compliance cost indexing for REACH and EPA Tier 3 standards.
The model assumes a particular technology adoption path for membrane-distillation hybrid configurations; alternative pathways for electrified aromatics extraction would alter the outlook for hydrogen consumption and capital intensity assumptions. Forecasts reflect documented assumptions regarding carbon intensity benchmark stringency, feedstock substitution elasticity, and cracker operating rate recovery patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Base Oil Market