
 Oil and Gas Refinery Maintenance Services Market | 2026-2036
Oil and Gas Refinery Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Refinery Maintenance Services Market Outlook
Aftermarket service revenue is tilting from reactive repairs toward predictive and condition-based contracts. Schlumberger leverages its digital subsurface expertise to embed sensor diagnostics into refinery turnaround planning. Baker Hughes Company sustains long-term service agreements across the Middle East and North American downstream corridors. KBR Inc. anchors its position through proprietary modular maintenance methodologies for complex catalytic reformer units.
Oil and gas refinery maintenance services encompass the inspection, repair, replacement, and optimization of process equipment, piping systems, and instrumentation within crude oil processing facilities, typically operating under pressure ratings from 150 to 2,500 psi and temperature regimes exceeding 450°C. These services preserve throughput reliability, emissions compliance, and worker safety across fluid catalytic cracking, hydrocracking, and coking operations. Predictive maintenance commands expanding capital allocation as IoT sensors and CMMS platforms enable real-time vibration and corrosion monitoring that preempt catastrophic failures. Shutdown services retain the highest absolute spend pool given the specialized labor, scaffolding, and catalyst handling required during planned turnarounds. Preventive maintenance remains mature but essential for rotating equipment and fired heater tube bundles where failure costs dwarf inspection outlays.
OSHA process safety management standards and EPA refinery sector rules in the United States mandate systematic mechanical integrity programs that directly expand third-party inspection and repair demand. The EU F-Gas Regulation and REACH compliance frameworks in Europe compel leak detection investments and material specification upgrades for sealing systems. Stakeholders must weigh captive maintenance teams against outsourced specialists as regulatory complexity and digital tooling requirements reshape workforce economics.
Market Dynamics
Refinery maintenance economics are pivoting toward predictive asset management as IoT-enabled condition monitoring compresses turnaround intervals and restructures labor deployment across downstream corridors.
Growth Catalysts
- EPA Refinery Sector Rules:Mandatory mechanical integrity programs under the US Environmental Protection Agency's emission standards are expanding third-party inspection demand for pressure vessels and flare systems.
- Digital Twin Deployment:Virtual replication of catalytic reformer and hydrocracker units enables pre-turnaround simulation that reduces actual shutdown duration by optimizing scaffolding and catalyst replacement sequencing.
- US Gulf Coast Cluster Aging:Infrastructure exceeding forty years of service life in Texas and Louisiana refining corridors elevates corrosion monitoring and tube bundle replacement frequency.
Market Restraints
- Specialized Welder Supply Concentration:Certified API 1104 and ASME Section IX welders concentrate in the US Gulf Coast and Rotterdam corridors, creating labor bottlenecks during concurrent turnaround seasons.
- High-Nickel Alloy Price Volatility:Inconel and Hastelloy procurement for high-temperature reactor internals exposes maintenance contractors to raw material cost swings that compress fixed-price contract margins.
- REACH Compliance Friction:The European Chemicals Agency's substance authorization requirements delay sealing system upgrades and catalyst replacement material approvals.
Strategic Opportunities
- India Refining Capacity Expansion:Reliance Industries and Indian Oil Corporation are adding coker and alkylation units that lack mature captive maintenance capabilities, opening outsourced service contracts.
- Carbon Capture Retrofit Integration:Amine-based post-combustion capture system installation on existing fired heaters creates bundled maintenance scope combining heat transfer and emissions control expertise.
- EU F-Gas Regulation Phase-Down:Refrigerant leak detection mandates for LNG recovery units are accelerating infrared camera inspection service adoption across North Sea and Mediterranean terminals.
Industry Challenges
- Industrial Cybersecurity Skill Gap:Protecting connected vibration sensors and distributed control systems from intrusion requires maintenance technicians to acquire network security competencies beyond traditional mechanical training.
- Legacy DCS Integration Complexity:Modern predictive analytics platforms must interface with proprietary Honeywell TDC 3000 and Yokogawa CENTUM systems installed in refineries during the 1990s, delaying sensor deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Refinery Maintenance Services Market |
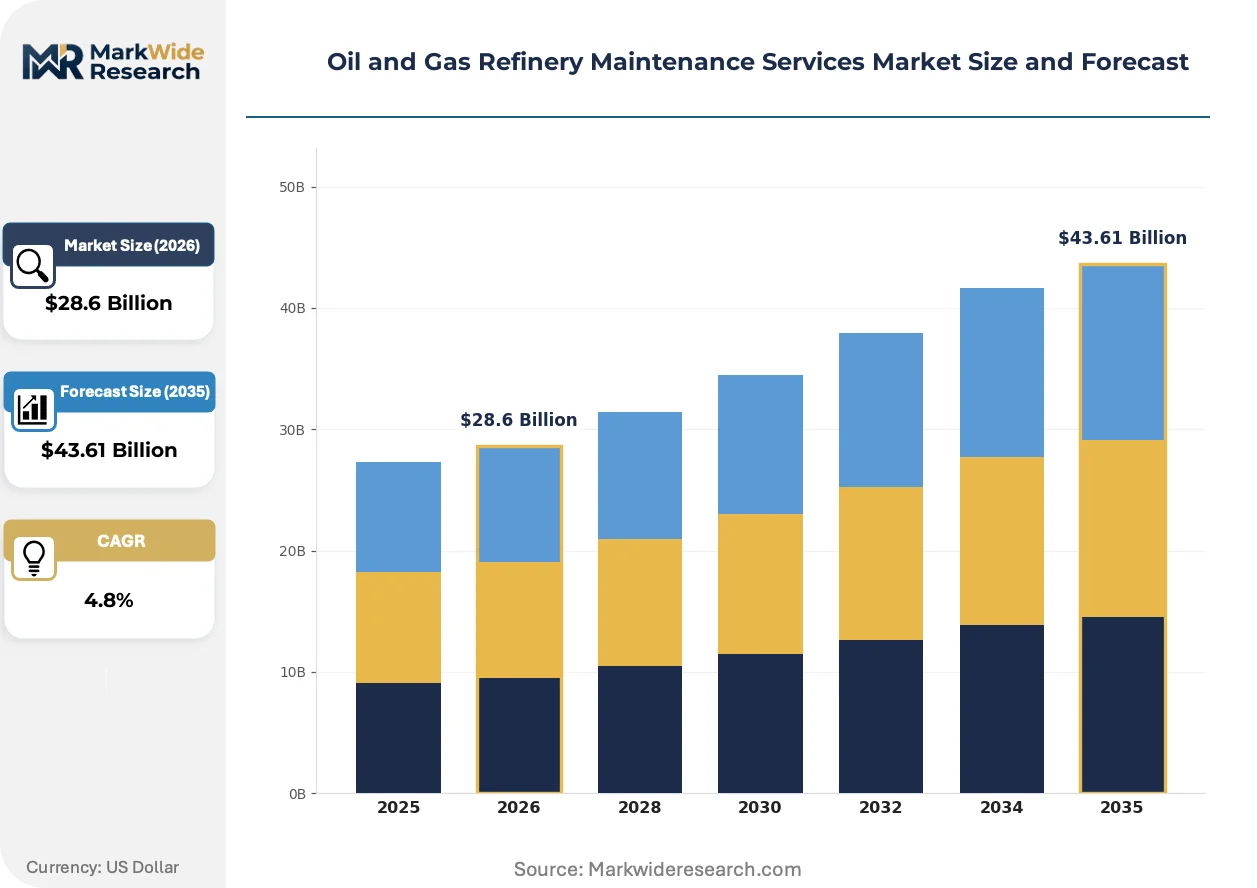
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Predictive Maintenance, Corrective Maintenance, Shutdown Services Maintenance Level: On-site Maintenance, Off-site Maintenance, Emergency Repairs, Routine Services Client Type: Refinery Operators, Equipment Manufacturers, Government Agencies, Third-party Service Providers Technology Used: CMMS, IoT Sensors, Automated Robotics, Drones |
| Companies Covered | Schlumberger, Halliburton, Fluor Corporation, Weatherford International, NOV Inc., Aecom, Baker Hughes Company, ChampionX Corporation, KBR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Refinery Maintenance Services Market Strategic Shifts
Maintenance service delivery is fragmenting into specialized digital and physical capability layers as predictive platforms displace routine inspection rounds and modular execution methods compress turnaround windows.
Digital twin technology is virtualizing refinery asset management by creating physics-based simulations of fluid catalytic cracking units and hydrocracker reactors. Major downstream operators in the US Gulf Coast and Rotterdam corridors are deploying these replicas to rehearse catalyst unloading sequences and identify pressure boundary risks before physical shutdown. This virtualization is compressing the planning phase of turnarounds from months to weeks while reducing on-site labor requirements.
The EU F-Gas Regulation is tightening leak detection mandates for fluorinated greenhouse gases used in refinery refrigeration and LNG recovery systems. Industrial consequence includes mandatory annual inspection frequency for systems above fifty kilograms charge and material specification upgrades for sealing technologies. European downstream corridors, particularly the Antwerp-Rotterdam-Amsterdam cluster, are responding by retrofitting infrared imaging diagnostics and accelerating contract transitions to service providers with certified refrigerant handling capabilities.
Service contract unbundling is separating predictive diagnostics from physical execution across the maintenance value chain. Integrated refinery operators in the Middle East are disaggregating long-term framework agreements to source vibration monitoring and corrosion analytics from digital specialists while retaining mechanical turnaround execution with established contractors. Saudi Aramco's downstream affiliates exemplify this bifurcation, awarding condition-based monitoring separately from catalyst handling and vessel inspection scopes.
Oil and Gas Refinery Maintenance Services Market Segmentation
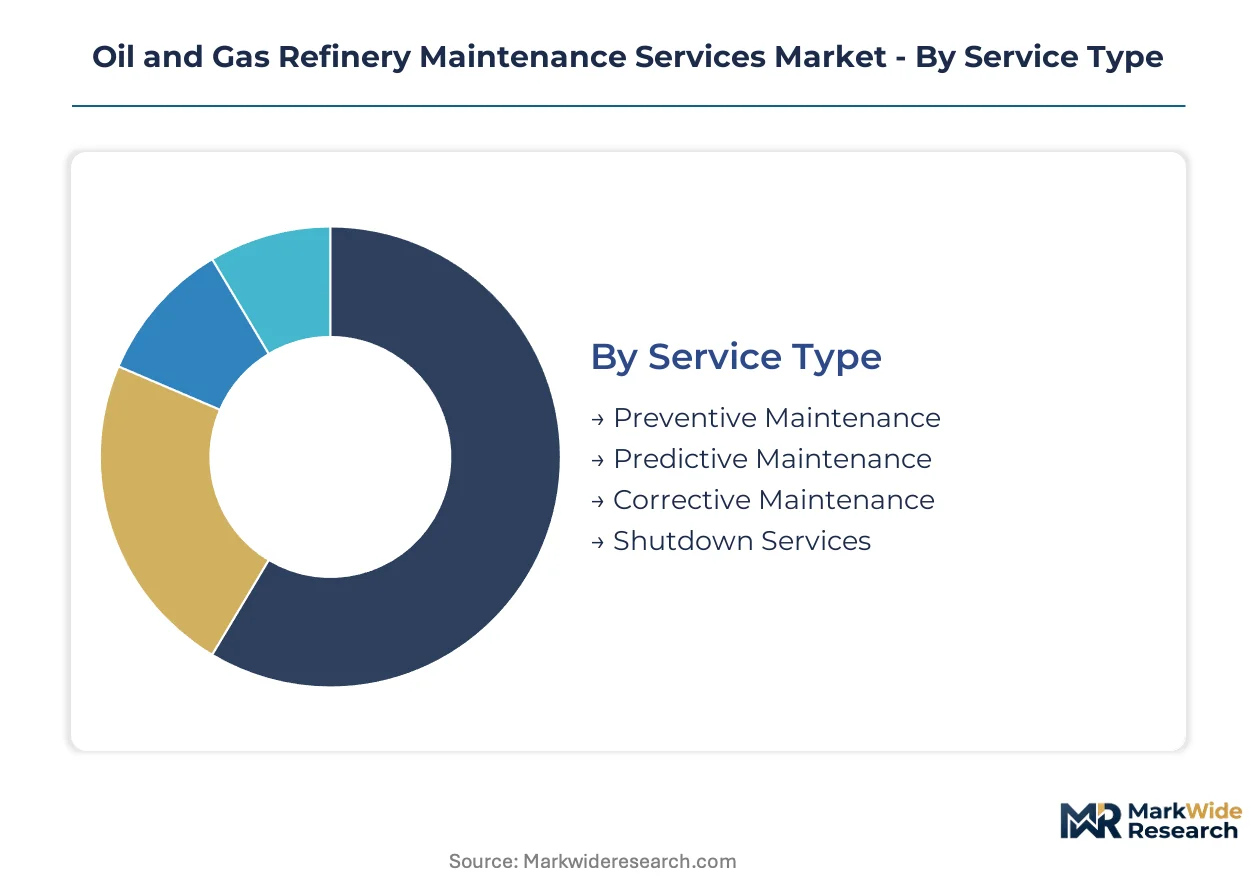
Refinery maintenance procurement fragments across service delivery modes, urgency tiers, and technology integration levels. Understanding these partitions exposes where predictive platforms displace conventional inspection and where labor bottlenecks concentrate.
Service Type:
Cost tier stratification separates scheduled, data-driven, and reactive intervention modes across downstream facilities.
- Preventive Maintenance:Scheduled inspection and component replacement based on run-hour thresholds or calendar intervals. Rotating equipment and fired heater tube bundles in Texas and Louisiana refineries consume the bulk of this spend category.
- Predictive Maintenance:Condition-based intervention triggered by real-time vibration, temperature, and corrosion telemetry. IoT sensor networks and CMMS platforms are compressing turnaround planning cycles across US Gulf Coast catalytic reformer units.
- Corrective Maintenance:Unplanned repair of failed equipment including pump seal replacement and piping leak remediation. Demand spikes during hurricane season stress contractor availability in coastal corridors.
- Shutdown Services:Comprehensive turnaround execution encompassing catalyst handling, vessel entry, and regulatory inspection. Specialized scaffolding and certified welding labor command premium pricing during concurrent outage windows.
Shutdown services hold installed capacity. Predictive maintenance is rotating up the share rankings.
Maintenance Level:
Geography of execution distinguishes captive facility teams from mobilized specialist crews and crisis-response deployments.
- On-site Maintenance:Permanent or semi-permanent contractor presence within refinery fence lines. Saudi Aramco downstream affiliates and Reliance Industries facilities in India favor this model for high-frequency rotating equipment care.
- Off-site Maintenance:Component removal and refurbishment at dedicated service centers. Turbine rotor balancing and valve actuation system rebuilds concentrate in Rotterdam and Houston corridor workshops.
- Emergency Repairs:Rapid mobilization for pressure boundary failures or safety system trips. API 1104 certified welder availability constrains response capacity during regional turnaround seasons.
- Routine Services:Recurring low-skill tasks including filter replacement and lubrication. This tier faces margin compression as digital platforms automate condition monitoring and work order generation.
On-site maintenance holds installed capacity. Emergency repairs are climbing the fastest.
Client Type:
Customer maturity and captive capability determine outsourcing depth across the value chain.
- Refinery Operators:Integrated downstream companies with varying degrees of in-house maintenance capability. Aging US Gulf Coast infrastructure and new Indian coker units drive divergent outsourcing strategies.
- Equipment Manufacturers:OEM service arms providing warranty support and upgrade pathways. Compressor and pump OEMs leverage proprietary telemetry for remote diagnostics.
- Government Agencies:Regulatory inspection and compliance enforcement functions. EPA refinery sector rules and OSHA process safety mandates expand third-party inspection scope.
- Third-party Service Providers:Independent contractors specializing in catalyst handling, vessel inspection, or digital twin deployment. These entities capture share as predictive analytics requirements outstrip captive technical capacity.
Refinery operators hold installed capacity. Third-party service providers are gaining share fastest.
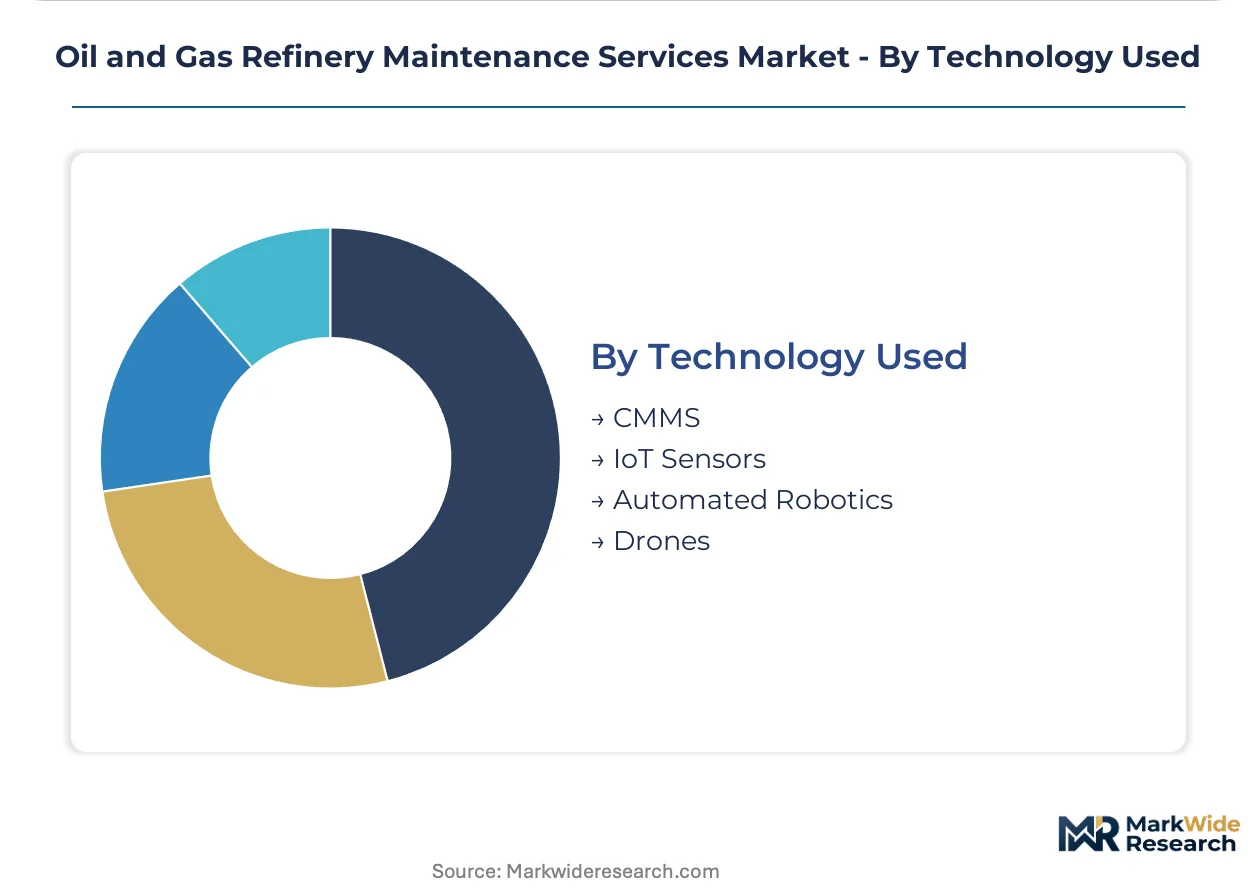
Technology Used:
Digital tooling intensity segments providers by data infrastructure investment and cybersecurity posture.
- CMMS:Computerized maintenance management systems governing work order flow, spare parts inventory, and labor scheduling. Legacy DCS integration complexity delays deployment in refineries with 1990s-vintage control systems.
- IoT Sensors:Wireless vibration, temperature, and corrosion monitoring devices. Real-time telemetry from fluid catalytic cracking units enables pre-failure intervention.
- Automated Robotics:Crawlers and manipulators for vessel inspection and catalyst unloading. These systems reduce confined space entry and accelerate turnaround timelines.
- Drones:Aerial platforms for flare stack inspection, tank roof assessment, and emissions monitoring. FAA Part 107 compliance and refinery airspace coordination govern deployment.
CMMS holds installed capacity. IoT sensors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding labor and specialized turnaround contractors concentrate along the US Gulf Coast, Rotterdam-Antwerp corridor, and Middle Eastern downstream hubs. This geographic clustering creates procurement leverage for refiners while exposing maintenance schedules to regional labor bottlenecks during concurrent outage seasons. Each major refining corridor exhibits distinct regulatory pressures and infrastructure maturity profiles.
United States
Texas and Louisiana host over forty percent of domestic refining capacity, with aging catalytic reformer units driving tube bundle replacement demand. EPA refinery sector rules mandate mechanical integrity programs that expand third-party inspection scope for pressure vessels and flare systems. The Houston Ship Channel refining cluster exhibits the highest maintenance intensity as hurricane exposure accelerates corrosion monitoring investments.
Netherlands
The Rotterdam port complex anchors European downstream maintenance demand as Europe's largest refined product export hub. EU F-Gas Regulation mandates tighten leak detection frequency for refrigeration systems above fifty kilograms charge, accelerating infrared camera inspection adoption. The Antwerp-Rotterdam-Amsterdam cluster faces REACH compliance friction that delays sealing system material approvals for catalytic cracker units.
Saudi Arabia
Jubail and Yanbu industrial cities host massive downstream complexes operated by Saudi Aramco affiliates with expanding predictive maintenance programs. SFDA and SASO compliance frameworks govern equipment integrity documentation for export-oriented refining operations. The Eastern Province refining corridor is disaggregating long-term framework agreements to source digital diagnostics separately from mechanical execution.
India
Reliance Industries' Jamnagar complex and Indian Oil Corporation's expanding coker units lack mature captive maintenance capabilities, opening outsourced service contracts. CEA electrical safety mandates and Petroleum Rules under the Ministry of Petroleum and Natural Gas tighten turnaround scheduling compliance. Gujarat's refining corridor is importing predictive maintenance expertise as domestic digital infrastructure matures.
United Kingdom
Grangemouth and Fawley refineries operate under tightening HSE process safety management standards post-Piper Alpha regulatory evolution. The Health and Safety Executive's COMAH regulations mandate systematic mechanical integrity programs that sustain third-party inspection demand. North Sea terminal maintenance integrates with offshore platform service logistics, creating specialized bundling opportunities for integrated contractors.
Oil and Gas Refinery Maintenance Services Market Competitive Environment
Integrated energy service conglomerates and specialized turnaround contractors split the market across digital and physical capability layers. The vendor base exhibits moderate concentration at the top tier, with Schlumberger and Baker Hughes commanding predictive analytics platforms while KBR Inc. and Fluor Corporation anchor complex shutdown execution. Two strategic archetypes dominate: subsurface-to-surface technology integrators leveraging digital twin deployment, and modular execution specialists compressing turnaround windows through proprietary methodologies. Competitive dynamics center on M&A activity targeting IoT sensor networks and strategic partnerships bridging legacy DCS integration gaps.
Within the technology-integrator tier, Schlumberger and Baker Hughes Company represent the archetype of digital subsurface expertise extending into refinery asset management. Halliburton occupies a position among North American-based service conglomerates with downstream maintenance capabilities. KBR Inc. exemplifies the modular execution specialist archetype through proprietary methodologies for complex catalytic reformer units. These entities capture expanding share as predictive analytics requirements outstrip captive technical capacity across aging US Gulf Coast and new Indian refining corridors.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Fluor Corporation |
| Weatherford International |
| NOV Inc. |
| Aecom |
| Baker Hughes Company |
| ChampionX Corporation |
| KBR Inc. |
| Others |
Value Chain & Pricing Dynamics
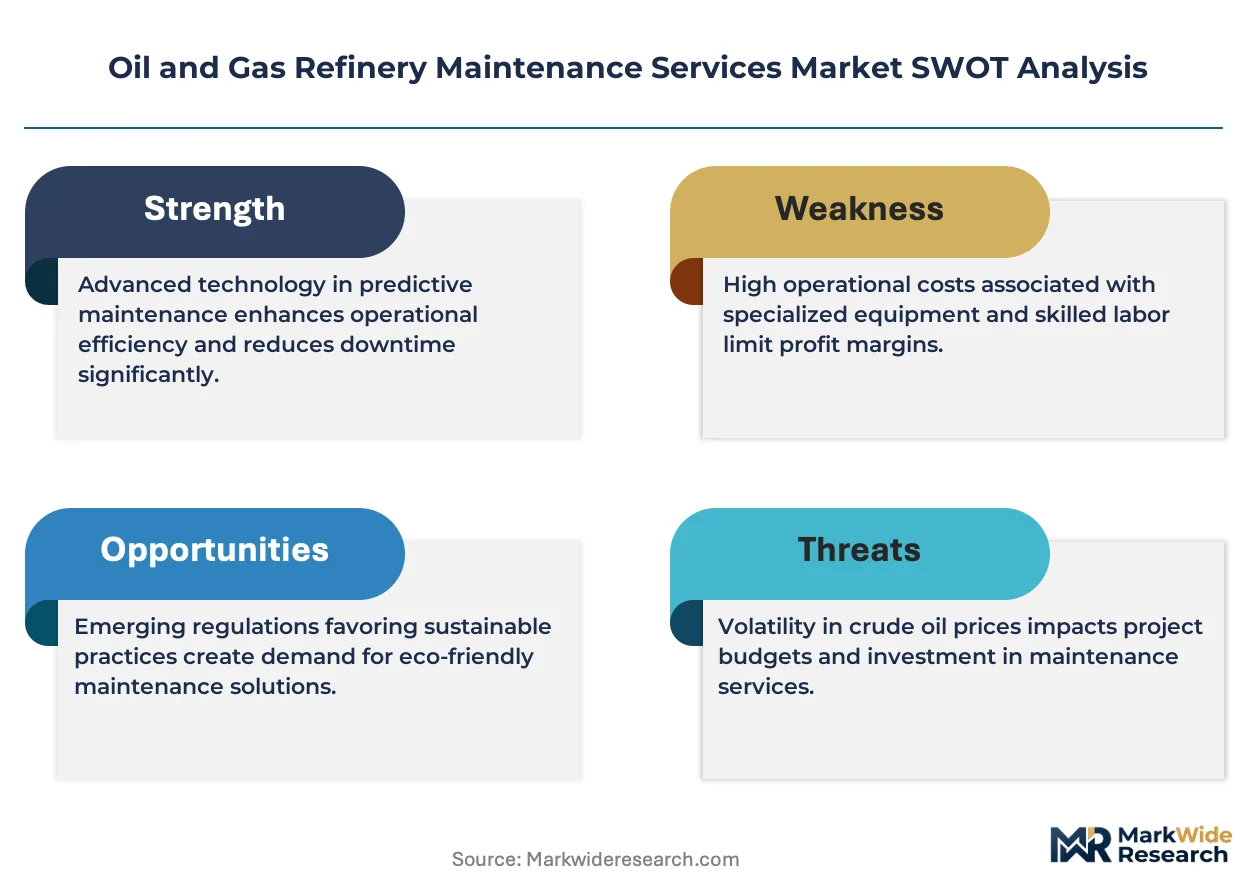
Specialized welder certification programs in the US Gulf Coast and Rotterdam corridors anchor the labor cost structure that dictates maintenance contract premiums across downstream corridors. API 1104 and ASME Section IX credential scarcity concentrates pricing power with certified contractors during concurrent turnaround seasons, compressing margins for fixed-price service agreements.
Pricing Analysis
OSHA process safety management standards dictate the pricing tier structure across refinery maintenance services. Three-tier pricing structure across premium, standard, and economy levels separates emergency response contracts with guaranteed welder availability from routine preventive maintenance slots and commodity inspection rounds. Cost compression in the emergency repair tier is intensifying because certified labor bottlenecks during hurricane season and regional turnaround windows. National oil companies with captive maintenance capabilities exhibit lowest price sensitivity; independent refiners in the US Gulf Coast cluster face acute cost pressure during concurrent outage periods.
Supply Chain Analysis
High-nickel alloy feedstock draws from mining operations in Indonesia, Russia, and Canada before processing into Inconel and Hastelloy reactor internals. Inconel 625 and Hastelloy C-276 procurement rests on aerospace and power generation demand competition that amplifies price volatility for maintenance contractors. Single-source vulnerability concentrates in specialty alloy distributors serving the Houston Ship Channel and Rotterdam port complexes. Distribution runs through long-term framework agreements with integrated energy service conglomerates that bundle digital diagnostics with physical execution capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated downstream operators that consolidate maintenance procurement across multiple refinery sites, squeezing contractor margins and favoring framework agreements over spot contracting.
For Market Incumbents: Insulate recurring revenue streams by embedding IoT sensor diagnostics into multi-year predictive maintenance contracts before digital specialists capture standalone analytics scopes. Deepen backward integration into certified welding training programs to reduce labor cost exposure during peak turnaround seasons. Anchor retention through proprietary modular methodologies for catalytic reformer and hydrocracker turnarounds that compress client shutdown windows. For New Entrants and Emerging Players: Build out predictive analytics capabilities targeting Indian refining corridors where Reliance Industries and Indian Oil Corporation lack mature captive maintenance infrastructure. Capture share in carbon capture retrofit integration by bundling amine system expertise with existing heat transfer maintenance relationships. Lead with digital twin deployment as a wedge against established mechanical execution contractors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed turnaround specialists that consolidated during the last decade of refinery margin compression. Long-term viability hinges on exposure to US Gulf Coast aging infrastructure and Indian capacity expansion rather than European refinery closures. Watch for inflection when national oil companies begin disaggregating framework agreements to source digital diagnostics separately from mechanical execution.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Deployment | Virtual replication of FCCU and hydrocracker units reduces turnaround planning from months to weeks. |
| Backward Integration into Welder Training | Captive API 1104 certification programs insulate against Gulf Coast labor bottlenecks during hurricane season. |
| Carbon Capture Retrofit Bundling | Amine system expertise combined with fired heater maintenance captures emerging emissions compliance scope. |
| IoT Sensor Network Acquisition | Real-time vibration telemetry displaces routine inspection rounds and locks in recurring analytics revenue. |
| Modular Turnaround Methodology Licensing | Proprietary catalyst handling sequences compress client shutdown duration and justify premium pricing tiers. |
Study Parameters
Operator-level perspectives from refinery maintenance directors, turnaround planners, and procurement leads at integrated downstream companies anchored the qualitative base. Primary fieldwork with scaffolding contractors, certified welding supervisors, and digital twin deployment specialists combined with secondary validation from EPA refinery sector rule filings, OSHA process safety management directives, and trade data from the US Energy Information Administration. Bottom-up service contract value estimates triangulated against top-down refinery capacity and maintenance intensity benchmarks.
Scenario-bracketing framed the analytical approach across the analysis window, modeling service type segmentation by preventive, predictive, corrective, and shutdown tiers alongside maintenance level differentiation and technology integration intensity. CAGRs derived from historical maintenance spend patterns correlated with regulatory compliance cost escalations and infrastructure age profiles. Forecast inputs incorporated IoT sensor penetration rates and certified welder supply elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native predictive analytics specialists or private equity-backed turnaround consolidators would shift outcomes. Cross-checking against refinery utilization rates and regional turnaround scheduling data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Asia- Pacific Drilling Market