
 Nuclear Turbine Generators Market | 2026-2036
Nuclear Turbine Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Turbine Generators Market Analysis
State-owned utilities are redrawing procurement priorities toward extended-life turbine retrofits and new-build generator packages. General Electric leverages its heavy-duty frame manufacturing base in the United States to anchor utility relationships across North America. Siemens Energy competes through integrated service contracts that bundle rotor refurbishment with digital monitoring systems. Mitsubishi Heavy Industries specializes in high-speed turbine designs for advanced boiling water reactor platforms.
Nuclear turbine generators convert thermal energy from nuclear fission into electrical power through steam-driven turbine rotors coupled to synchronous generators, typically operating at 1,500 or 3,000 RPM depending on grid frequency. Steam turbines dominate installed capacity due to their established pairing with pressurized and boiling water reactors, while small modular reactor applications are driving fresh demand for compact generator sets with enhanced load-following capability. Conventional nuclear technology still occupies the largest revenue share, though advanced nuclear and hybrid systems represent the fastest-expanding margin pools as developers seek certification for non-light-water designs.
The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 50 and Part 52 quality standards that govern turbine-generator set certification for commercial reactors, while the International Atomic Energy Agency's safety standards shape procurement specifications across member states. China's National Nuclear Safety Administration and the State Administration for Market Regulation coordinate domestic type-approval processes that favor locally manufactured generator components. Stakeholders must monitor how divergent national certification timelines for advanced reactor designs affect cross-border equipment sourcing strategies.
Market Dynamics
State-backed reactor construction programs are compressing procurement cycles for turbine-generator packages while certification requirements for advanced reactor compatibility fragment supplier qualification pathways across jurisdictions.
Growth Catalysts
- China's reactor buildout:State-owned utilities are mandating domestic generator supply chains for new pressurized water reactor units, creating captive demand for locally manufactured turbine components.
- 10 CFR Part 50 compliance upgrades:U.S. license renewal applications require turbine blade material recertification, forcing utilities to source replacement rotors from qualified vendors.
- Small modular reactor platforms:Developers are procuring compact generator sets with load-following capability to pair with non-light-water reactor designs.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloy production for turbine blades concentrates among a limited set of European and Japanese metallurgical suppliers.
- Extended certification timelines:IAEA safety standards and national type-approval processes stretch equipment qualification periods beyond typical capital planning horizons.
- Gas turbine peaker substitution:Grid operators are deploying combined-cycle gas plants for mid-merit flexibility, reducing baseload nuclear dispatch hours in competitive markets.
Strategic Opportunities
- India's PHWR expansion:The Department of Atomic Energy's pressurized heavy water reactor program requires indigenous turbine-generator manufacturing partnerships.
- EU taxonomy alignment:The EU Green Deal's sustainable finance classification is channeling institutional capital toward nuclear life-extension projects requiring turbine retrofits.
- Digital twin integration:Predictive maintenance platforms are converging with rotor refurbishment contracts to create recurring revenue streams beyond equipment sales.
Industry Challenges
- Specialized welding technician scarcity:Rotor repair facilities face shortages of certified welders qualified for nickel alloy turbine blade attachment processes.
- Legacy generator synchronization:Grid-forming inverter requirements for advanced reactors create integration friction with existing synchronous machine standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Turbine Generators Market |
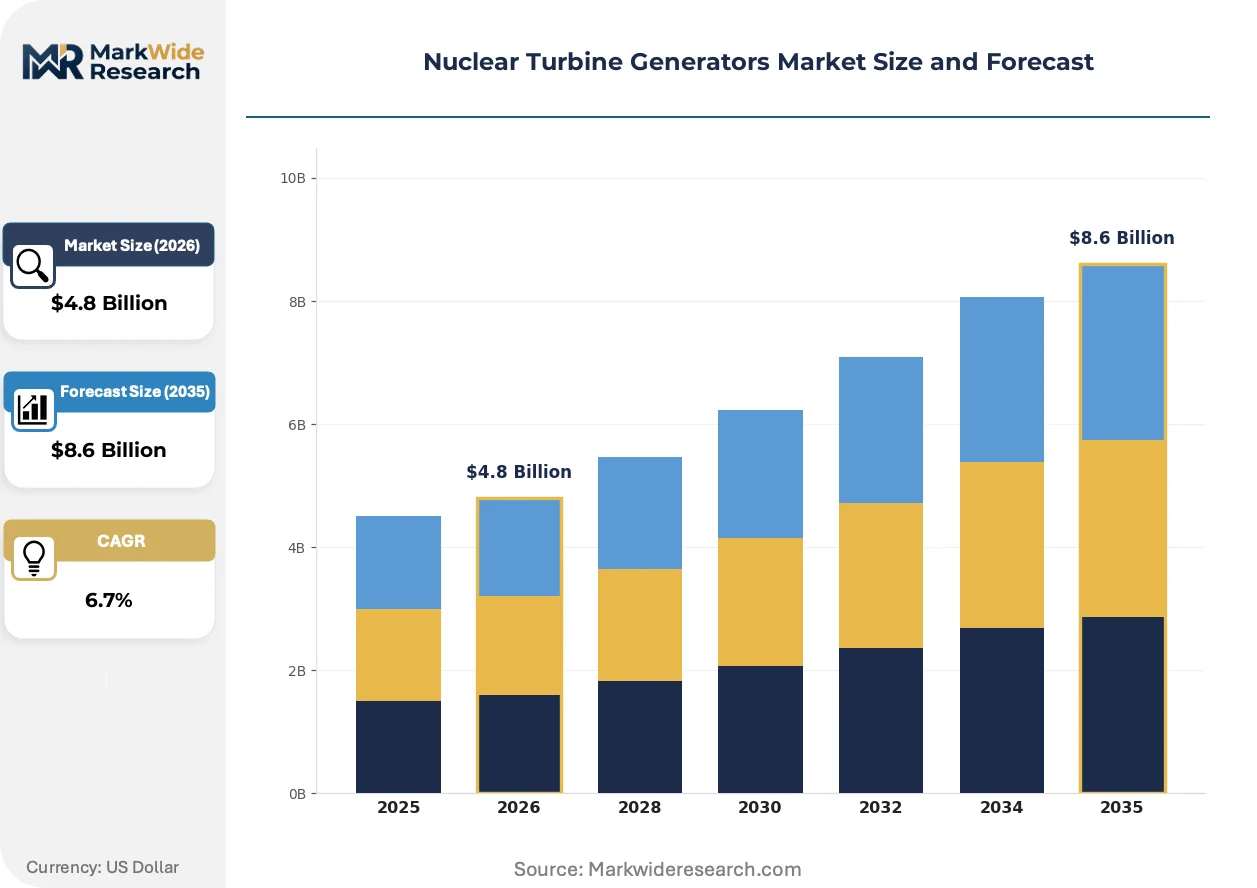
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbines, Gas Turbines, Combined Cycle Turbines, Generator Sets Application: Electricity Generation, Industrial Power Supply, District Heating, Backup Power End User: Utilities, Industrial Facilities, Government Agencies, Research Institutions Technology: Conventional Nuclear, Advanced Nuclear, Small Modular Reactors, Hybrid Systems |
| Companies Covered | General Electric, Siemens Energy, Mitsubishi Heavy Industries, Westinghouse Electric Company, Toshiba Corporation, Doosan Enerbility, Framatome, Shanghai Electric Group, Rosatom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Turbine Generators Market Emerging Trajectories
Equipment suppliers are reconfiguring product architectures around modular generator designs while regulatory divergence across jurisdictions fragments certification pathways for advanced reactor compatibility.
Additive manufacturing of nickel superalloy turbine blade roots is decomposing traditional forging supply chains for replacement rotor components. U.S. utilities undergoing license renewal are piloting printed blade attachments for non-critical applications. This technology is decomposing lead times for obsolete part reproduction from months to weeks.
REACH regulation amendments on nickel compound classification are tightening material disclosure requirements for turbine blade coatings imported into European Union member states. Manufacturers must now document full substance composition across their supply tiers. Advanced boiling water reactor platforms with extended maintenance intervals face the steepest compliance cost escalation.
After-sales service unbundling is separating rotor refurbishment from original equipment supply in utility procurement evaluations. Independent service providers are capturing overhaul contracts previously retained by frame manufacturers. This pattern is most visible in North American merchant nuclear fleets operating outside regulated cost-recovery frameworks.
Nuclear Turbine Generators Market Segmentation
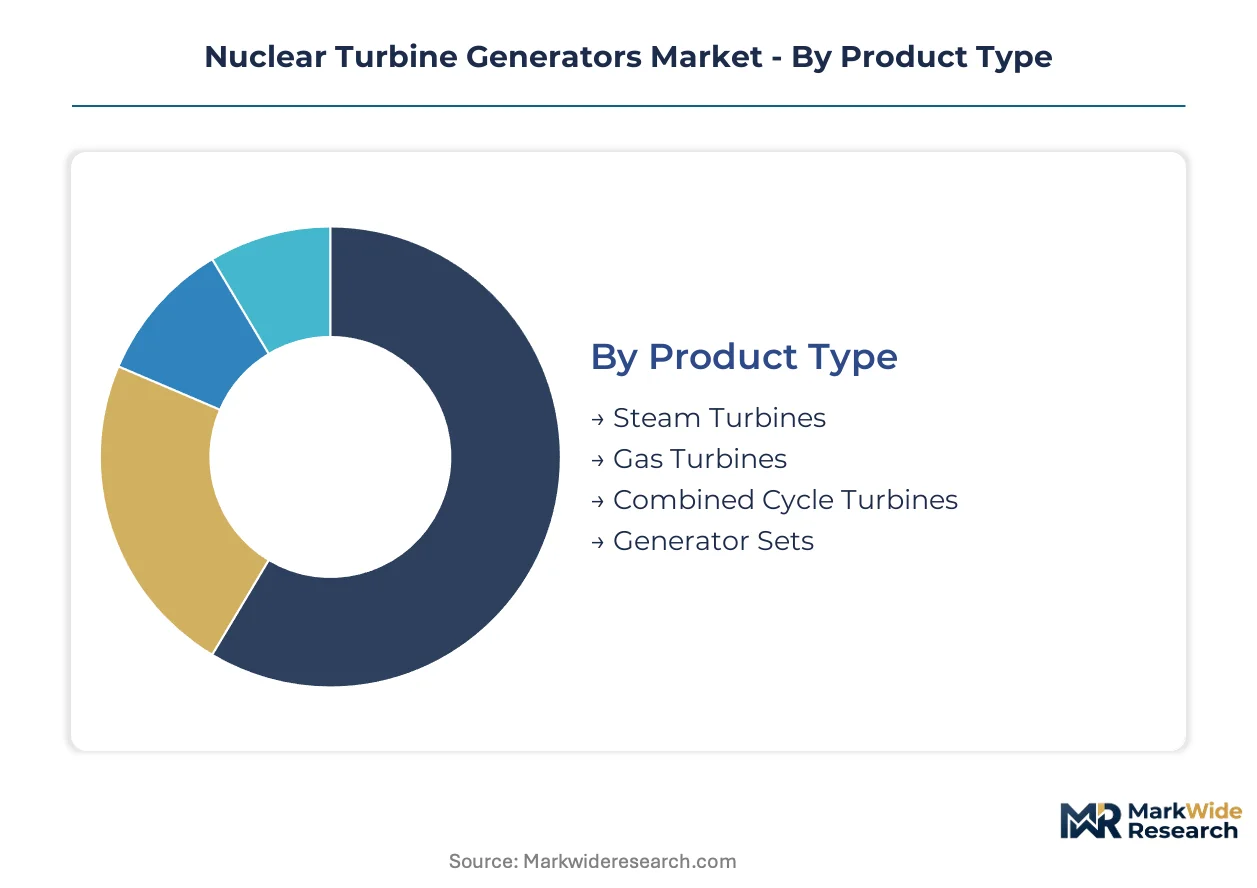
Nuclear turbine generator procurement patterns diverge sharply across product architectures and reactor technologies. Equipment specifications cascade differently through utility fleets, industrial cogeneration sites, and emerging small modular reactor deployments.
Product Type:
Steam turbine configurations face intensifying substitution pressure from compact generator sets designed for small modular reactor integration, while combined cycle architectures struggle to penetrate nuclear-specific procurement channels.
- Steam Turbines:These units couple directly to pressurized and boiling water reactor steam loops, operating at fixed synchronous speeds of 1,500 or 3,000 RPM to match grid frequency requirements. Chinese state-owned utilities anchor procurement volume for large-capacity units in new pressurized water reactor builds.
- Generator Sets:Compact synchronous machines with enhanced load-following capability are attracting developers of non-light-water reactor platforms. Small modular reactor certification programs in the United States and Canada are compressing lead times for these integrated packages.
- Gas Turbines:Direct-drive configurations for high-temperature gas-cooled reactor applications remain niche.
- Combined Cycle Turbines:Heat recovery integration with nuclear steam systems faces thermodynamic efficiency constraints in baseload operation.
Steam turbines retain volume leadership; generator sets hold the steepest expansion curve.
Application:
Cost tier stratification separates baseload electricity generation from backup power applications, with district heating emerging as a margin-intensive middle layer in Nordic and Eastern European markets.
- Electricity Generation:Baseload grid supply commands the largest equipment scale, with single turbine-generator sets exceeding 1,000 MW capacity in evolutionary pressurized water reactor configurations. U.S. license renewal applications under 10 CFR Part 50 are sustaining replacement demand for blade and rotor components.
- District Heating:Cogeneration configurations extract low-pressure steam after high-pressure turbine stages, delivering thermal output to municipal heating networks. Finland and the Czech Republic host operational deployments with extended maintenance intervals.
- Industrial Power Supply:Captive generation for energy-intensive process industries remains limited by nuclear licensing complexity.
- Backup Power:Grid-forming synchronous machines for islanded operation attract specialized safety-grade certification requirements.
Electricity generation dominates installed base value; district heating is climbing fastest on policy support for decarbonized thermal networks.
End User:
Customer type concentration centers on regulated utilities with cost-recovery frameworks, while industrial facilities face steeper qualification barriers for nuclear site licensing.
- Utilities:State-owned and investor-owned power companies drive procurement of large turbine-generator packages through long-term power purchase agreements. China's National Nuclear Safety Administration coordinates type-approval processes that favor domestic generator component suppliers.
- Government Agencies:National laboratory and naval propulsion programs sustain demand for specialized high-speed turbine designs with enhanced shock resistance specifications.
- Industrial Facilities:Process industry adoption remains constrained by nuclear liability and emergency planning requirements.
- Research Institutions:University reactor programs generate limited but steady demand for compact generator sets with educational instrumentation packages.
Utilities command procurement volume; government agencies maintain the most specialized specification requirements.
Technology:
Technology maturity curves separate certified conventional nuclear platforms from advanced reactor designs still navigating fragmented national approval pathways.
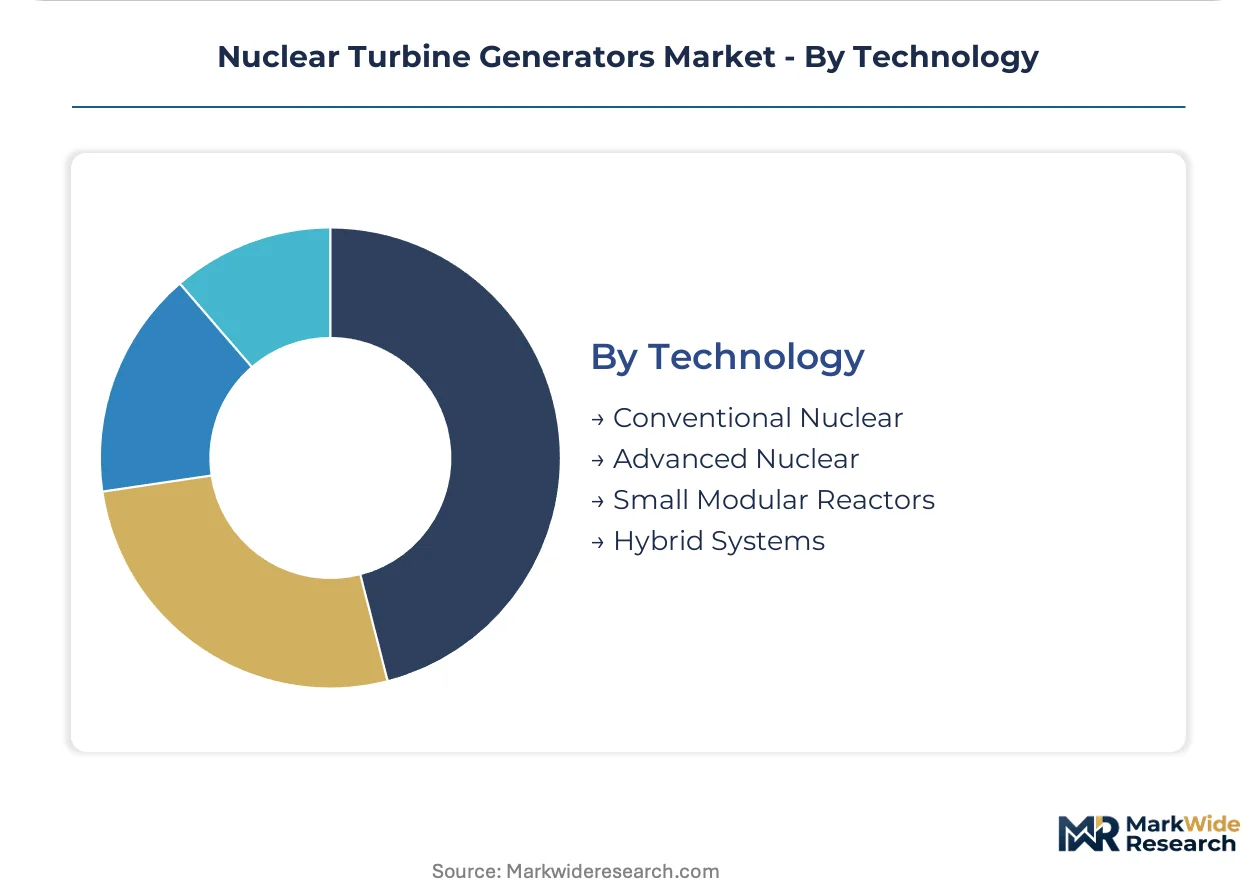
- Conventional Nuclear:Pressurized and boiling water reactor turbine-generator sets operate within established regulatory frameworks, with blade material certification under ASME and RCC-M standards enabling cross-border component sourcing. EASA in Europe and the U.S. Nuclear Regulatory Commission enforce convergent quality standards for forged rotor discs.
- Small Modular Reactors:Factory-fabricated turbine-generator packages aim for modular deployment with reduced site construction schedules. Developers in the United States, Canada, and the United Kingdom are pursuing distinct certification timelines that fragment equipment qualification pathways.
- Advanced Nuclear:Non-light-water designs including sodium-cooled fast reactors and high-temperature gas reactors require turbine materials compatible with alternative working fluids and temperature profiles.
- Hybrid Systems:Nuclear-renewable integration configurations with thermal storage are driving prototype generator specifications for flexible dispatch operation.
Conventional nuclear technology anchors current revenue; small modular reactors are gaining share fastest as certification programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision forging houses export nickel superalloy turbine blade components to Chinese reactor construction sites, establishing a critical west-east supply corridor that underpins equipment procurement for state-backed nuclear programs.
United States
License renewal applications under 10 CFR Part 50 are sustaining replacement demand for turbine blade material recertification. The U.S. Nuclear Regulatory Commission enforces quality standards that govern turbine-generator set certification for commercial reactors. Manufacturing clusters in South Carolina and Pennsylvania host rotor refurbishment facilities serving merchant nuclear fleets.
China
State-owned utilities are mandating domestic generator supply chains for new pressurized water reactor units. The National Nuclear Safety Administration coordinates type-approval processes that favor locally manufactured generator components. Shanghai Electric Group anchors production capacity in the Yangtze River Delta for turbine-generator packages.
France
Life-extension projects for existing pressurized water reactor fleets are driving turbine retrofit procurement. EASA enforces tightening turbine blade material certification standards across European member states. The Auvergne-Rhône-Alpes region concentrates specialized welding technician training for rotor repair facilities.
Japan
Advanced boiling water reactor platforms require high-speed turbine designs with extended maintenance intervals. METI coordinates domestic certification pathways for post-Fukushima safety upgrades. Mitsubishi Heavy Industries maintains engineering concentration in the Nagoya industrial corridor for specialized turbine configurations.
India
The Department of Atomic Energy's pressurized heavy water reactor program requires indigenous turbine-generator manufacturing partnerships. BIS standards govern equipment qualification for nuclear power plant components. Gujarat and Tamil Nadu host emerging fabrication clusters for domestic rotor component production.
Nuclear Turbine Generators Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive forging and precision machining capabilities. The competitive structure concentrates among heavy electrical equipment manufacturers with established nuclear quality certifications. Three strategic archetypes dominate: integrated turbine-generator packagers, specialized rotor refurbishment service providers, and state-backed national champions with captive domestic markets. Dominant competitive moves include vertical integration into nickel superalloy supply chains and technology licensing partnerships for small modular reactor compatibility.
Among U.S.-based industrial conglomerates, General Electric anchors the integrated packager archetype through heavy-duty frame manufacturing relationships. Siemens Energy exemplifies the service-integrated model, while Mitsubishi Heavy Industries occupies a specialist position in high-speed turbine configurations. Shanghai Electric Group and Doosan Enerbility represent state-linked national champions with protected domestic procurement channels.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Westinghouse Electric Company |
| Toshiba Corporation |
| Doosan Enerbility |
| Framatome |
| Shanghai Electric Group |
| Rosatom |
| Others |
Supply Flow & Price Mechanics
Twenty-four-month lead times for nickel superalloy turbine blade forgings concentrate pricing power among German and Japanese metallurgical suppliers, compressing margins for generator packagers while amplifying cost pass-through to state-owned utilities in captive procurement markets.
Pricing Analysis
Technology-generation pricing gaps separate conventional pressurized water reactor turbine-generator sets from advanced non-light-water designs and small modular reactor packages. Three-tier pricing structure across ASME-certified premium, RCC-M standard, and economy-grade components reflects divergent certification investment and material traceability requirements. Pricing pressure stems from China's domestic supply chain mandates forcing foreign packagers to absorb localization costs. Merchant nuclear fleets in North America exhibit highest price sensitivity due to deregulated cost-recovery frameworks, while state-backed utilities in Asia accept premium pricing for technology transfer provisions.
Supply Chain Analysis
Strategic stockpiling of nickel superalloy ingots dominates inventory strategy among European forging houses, buffering against South African and Indonesian ore supply volatility. Germany, Japan, and China anchor precision forging capacity for turbine blade roots, with raw material dependencies centering on nickel, cobalt, and chromium feedstocks. Single-source vulnerability concentrates in vacuum induction melting furnaces qualified to ASME and RCC-M standards. Distribution runs through long-term framework agreements linking forging houses to turbine packagers, bypassing spot market exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nuclear turbine generator procurement is shifting toward platform economics as small modular reactor developers demand standardized, interoperable generator packages compatible across multiple reactor vendors, collapsing traditional equipment-specification silos.
For Market Incumbents: Shield installed base relationships by embedding digital monitoring systems into rotor refurbishment contracts, creating switching costs against independent service providers. Deepen backward integration into nickel superalloy supply through offtake agreements with German forging houses, securing blade material allocation before China's reactor buildout absorbs regional capacity. Prioritize ASME N-stamp certification investments to maintain qualification pathways for U.S. license renewal applications under 10 CFR Part 50. For New Entrants and Emerging Players: U.S. Nuclear Regulatory Commission certification fast-tracks for small modular reactor generator packages open procurement channels outside established utility relationships. Target India's pressurized heavy water reactor program, where indigenous manufacturing partnerships face less entrenched incumbent presence than Chinese markets. Pursue joint development agreements with advanced reactor developers seeking load-following generator specifications, using technical collaboration as market entry mechanism. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming nuclear turbine divisions amid energy transition portfolio rebalancing. Long-term viability hinges on exposure to small modular reactor certification timelines rather than conventional reactor life-extension dependency. Monitor U.S. Department of Energy loan guarantee announcements for advanced reactor deployments as inflection signal for generator package demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Superalloy Supply | Secures blade material allocation against China's reactor buildout absorbing German and Japanese forging capacity. |
| Digital Twin Integration for Rotor Refurbishment | Converts equipment sales into recurring predictive maintenance revenue streams with utility customers. |
| Small Modular Reactor Certification Partnership | Positions generator packages for factory-fabricated deployment models compressing site construction schedules. |
| Indigenous Manufacturing Joint Ventures in India | Aligns with Department of Atomic Energy's pressurized heavy water reactor localization requirements. |
| EU Taxonomy-Aligned Life Extension Services | Channels institutional capital toward nuclear turbine retrofits under Green Deal sustainable finance classification. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IAEA safety standards documentation, U.S. Nuclear Regulatory Commission 10 CFR filings, EASA certification records, and customs trade data for nickel superalloy component flows. Utility planning officers, nuclear quality assurance managers, forging house technical directors, and aftermarket service heads provided operational perspective on procurement cycles and certification timelines. Bottom-up equipment shipment tracking triangulates against top-down reactor construction pipeline assessments across China, the United States, France, and India.
Segmentation dimensions modeled span reactor technology type, generator capacity tier, application configuration, and regional regulatory framework cluster throughout the forecast period. CAGRs derive from installed base replacement schedules, new-build reactor commissioning timelines, and small modular reactor certification progressions. Forecast inputs incorporate nickel alloy price indices, welding technician training pipeline capacity, and divergent national type-approval process durations for advanced reactor designs.
Decision-makers should treat outputs as directional under assumptions of sustained state-backed reactor construction in China and progressive small modular reactor certification advancement in North America; material deviation would warrant model refresh. Revision becomes warranted when small modular reactor deployment timelines cross commercial viability thresholds or when nickel superalloy supply concentration triggers qualification pathway disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
China Diesel Generator Market
Generators
Residential Generators Market
Generators
Europe Portable Generator Market
Generators
Europe Generator Sets Market
Generators
South Africa Diesel Generator Market
Generators
Containerized Solar Generators Market
Generators
Wind Turbine Alternator Market
Generators
Wind Power Generators Market
Generators
Portugal Gas Generator Market
Generators
East Africa Diesel Generator Market
Generators
Dual-Fuel Generator Market
Generators
Middle East Portable Generator Market
Generators
Heat Recovery System Generator Market
Generators
Mobile Generators Market
Generators
Global Portable Generator Market
Generators
Asia Pacific Electric Generators Market