
 North America Natural Gas Liquids Market | 2026-2036
North America Natural Gas Liquids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Natural Gas Liquids Market Analytics
The premium NGL fractionation segment is consolidating around cryogenic processing capacity while commodity-grade bulk sales fragment across midstream aggregators. ExxonMobil Corporation leverages its integrated Permian-to-Gulf Coast pipeline network to capture margin at every transfer point. Enterprise Products Partners LP anchors its position through Mont Belvieu storage and export terminal dominance. ONEOK, Inc. competes by extending its Bakken and Mid-Continent gathering systems into fractionation and pipeline takeaway.
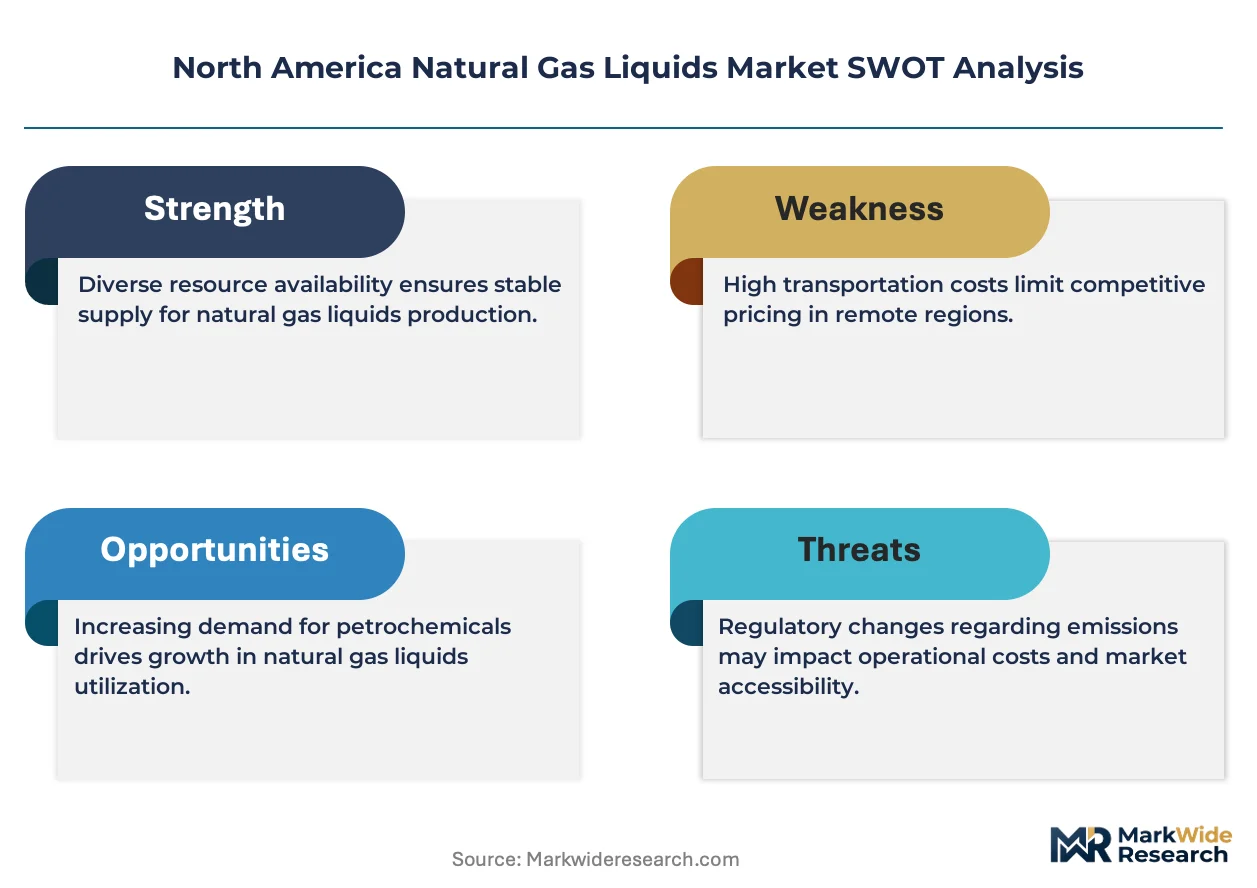
North America natural gas liquids are hydrocarbon components—including ethane, propane, normal and isobutane, and natural gasoline—recovered from natural gas streams through cryogenic turboexpander or absorption processes, typically separated at temperatures below minus 120 degrees Fahrenheit and pressures calibrated to component vapor pressures. These liquids serve primarily as petrochemical feedstocks, residential and commercial heating fuels, and gasoline blendstocks. Ethane dominates product type volumes as cracker feedstock demand absorbs nearly every available molecule from expanding Permian and Appalachian gas production. Petrochemical feedstocks lead application segment value capture, while fuel applications face structural pressure from electrification mandates in residential and commercial end user categories. Pipelines command delivery mode preference for cost efficiency at scale, though rail and barge alternatives retain flexibility premiums for stranded production basins.
FERC interstate pipeline rate regulation, EPA methane performance standards under the Clean Air Act, and Texas Railroad Commission flaring rules collectively shape capital deployment timelines and facility siting decisions across the value chain. State environmental agencies in Colorado and New Mexico impose additional air quality constraints on NGL extraction and processing operations. Stakeholders must monitor the pace of petrochemical capacity additions against midstream infrastructure buildout to avoid mismatched fractionation and pipeline commitments.
Market Dynamics
Permian Basin ethane extraction yields are forcing midstream operators to accelerate cryogenic fractionation capacity additions, compressing project timelines and reshaping capital allocation across the value chain.
Growth Catalysts
- EPA methane performance standards:Stricter emissions protocols under the Clean Air Act are driving investment in leak detection and repair technologies across extraction facilities.
- Petrochemical feedstock demand:Gulf Coast cracker expansions are absorbing record ethane volumes, tightening regional supply-demand balances and supporting infrastructure commitments.
- Mont Belvieu pricing hub concentration:The Texas Gulf Coast trading center anchors continental NGL price discovery, attracting storage and export terminal investments.
Market Restraints
- Natural gas processing margin volatility:Input cost swings at the wellhead compress operator economics and delay greenfield facility commitments.
- Permian supply concentration risk:Overreliance on West Texas production basins exposes the value chain to localized disruptions and takeaway bottlenecks.
- Electrification substitution pressure:Residential and commercial heating fuel demand faces structural displacement from building electrification mandates in multiple states.
Strategic Opportunities
- Appalachian Basin expansion:Underdeveloped NGL infrastructure in Pennsylvania and Ohio offers gathering system and fractionation greenfield potential.
- Rail and barge distribution channels:Stranded production basins without pipeline access create multimodal logistics opportunities for flexible delivery.
- Texas Railroad Commission flaring restrictions:Regulatory limits on waste gas burning incentivize capture and processing investments with favorable permitting timelines.
Industry Challenges
- Cryogenic process engineering talent scarcity:Specialized technicians for sub-minus-120-degree Fahrenheit operations remain in short supply across the region.
- FERC interstate pipeline certification delays:Extended environmental review timelines for new cross-border infrastructure compress project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Natural Gas Liquids Market |
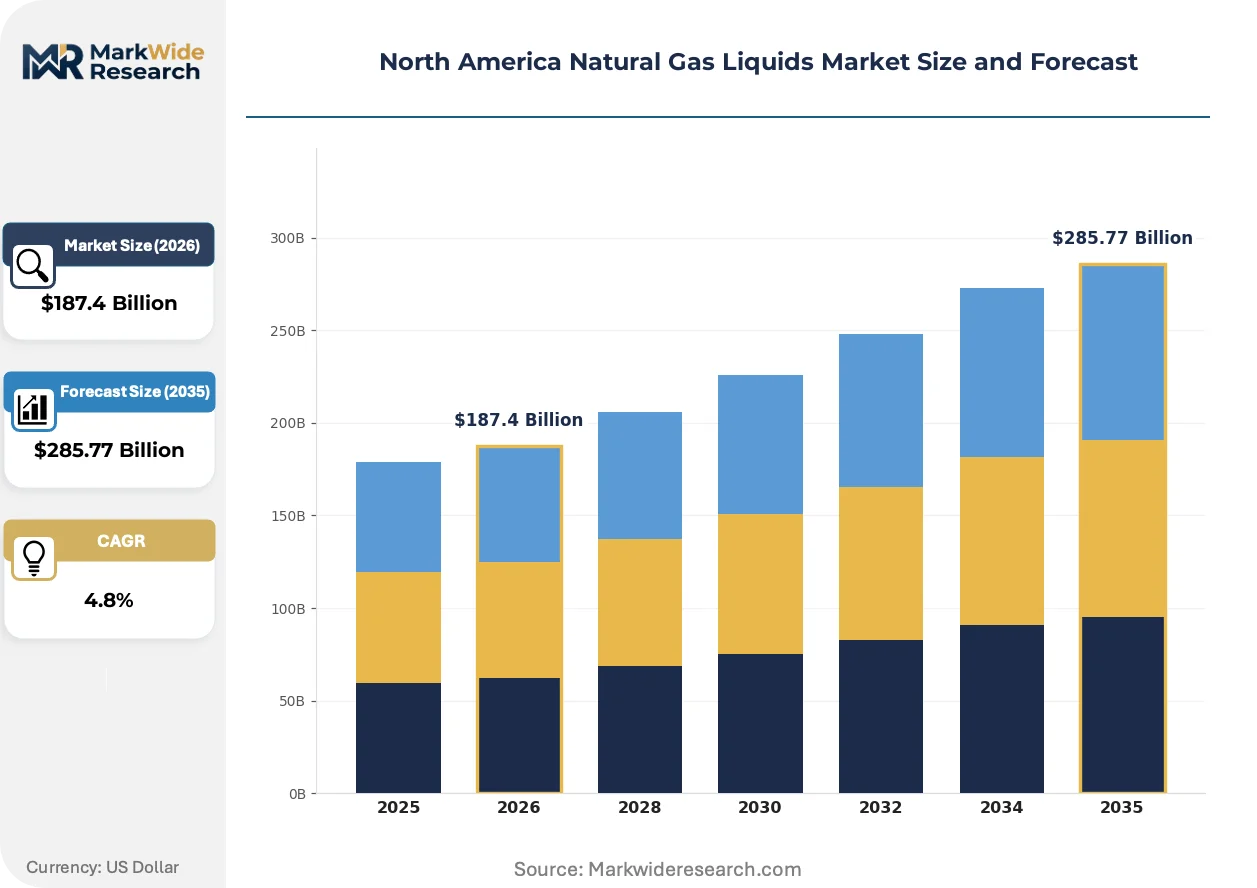
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethane, Propane, Butane, Natural Gasoline Application: Petrochemical Feedstocks, Fuel, Liquefaction, Industrial Feedstock Delivery Mode: Pipelines, Truck Transport, Rail Transport, Barges End User: Chemical Industry, Energy Sector, Residential, Commercial |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, ConocoPhillips, Enterprise Products Partners LP, Targa Resources Corp, ONEOK, Inc., Phillips 66, Occidental Petroleum Corporation, Devon Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Natural Gas Liquids Market Evolving Landscape
Modular cryogenic processing units are disrupting traditional centralized fractionation economics, enabling smaller operators to capture value without billion-dollar facility commitments.
Small-scale turboexpander packages with containerized compression trains are decentralizing NGL recovery at the wellpad level. Independent producers in the Delaware sub-basin are deploying these systems to bypass gathering line constraints. This distributed architecture is decentralizing the historical midstream monopoly over fractionation services.
EPA methane performance standards under the Clean Air Act are tightening leak detection protocols across extraction and processing stages. Operators must install continuous monitoring systems with quarterly reporting obligations. Appalachian Basin facilities face the steepest compliance curves due to older infrastructure vintages and fragmented ownership structures.
Buyers are consolidating procurement through long-term offtake agreements tied to Mont Belvieu index pricing. Petrochemical purchasers are bypassing merchant market exposure in favor of direct producer relationships with volume commitments. This contracting evolution is most pronounced along the Texas Gulf Coast, where cracker proximity enables pipeline-direct supply arrangements.
North America Natural Gas Liquids Market Segmentation
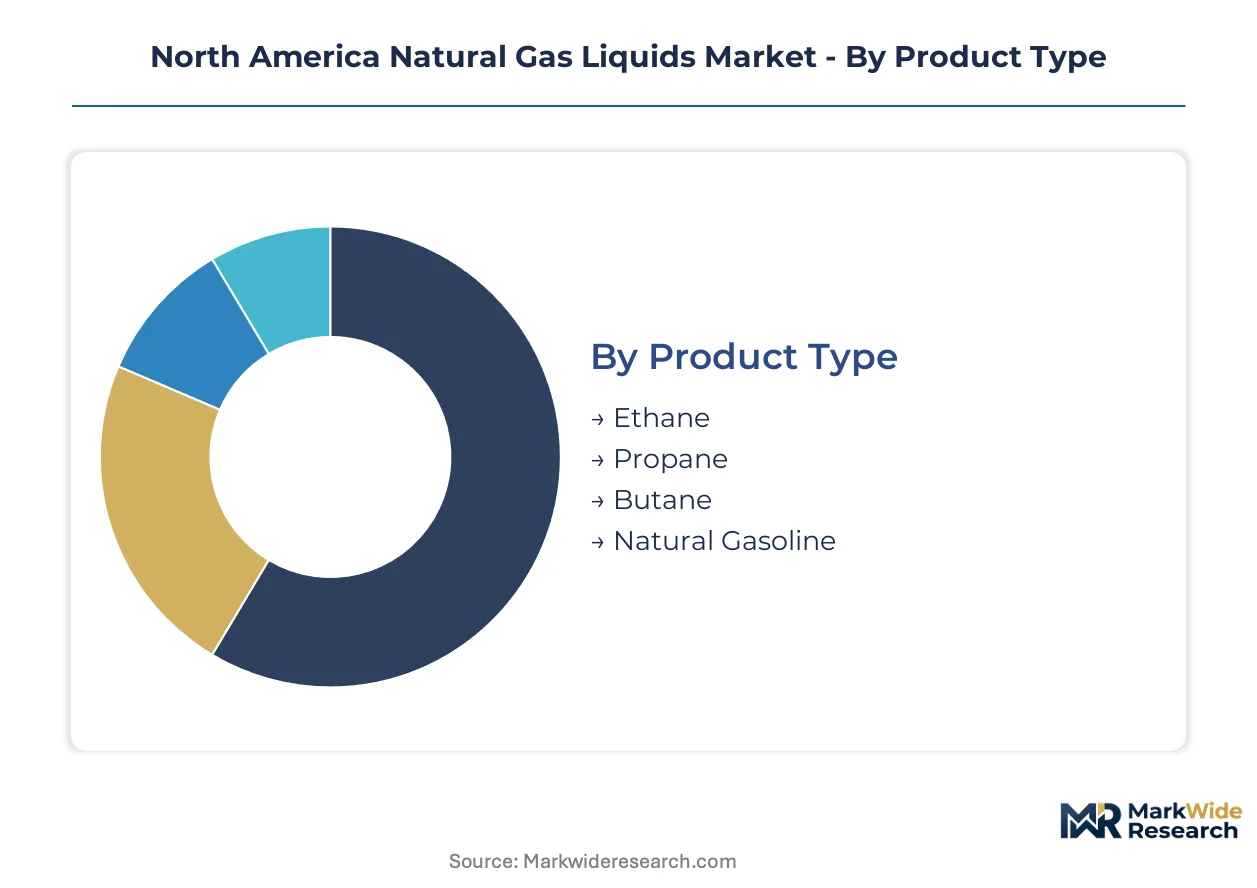
Segmentation in the North America natural gas liquids market reveals how product chemistry, delivery economics, and end-use specifications drive procurement decisions. Buyers prioritize feedstock purity and logistics reliability over price alone.
Product Type:
Buyers select NGL components based on cracker compatibility and vapor pressure specifications for their specific processes.
- Ethane:The lightest NGL fraction with methane rejection requirements below 5 percent by volume. Gulf Coast steam crackers in Texas and Louisiana absorb nearly every available molecule, with Mont Belvieu pricing serving as the continental benchmark for contract indexing.
- Propane:A two-carbon alkane with distinct seasonal demand curves between petrochemical feedstock and residential heating applications. Winter heating loads in the Midwest and Northeast create price spikes that disrupt year-ahead procurement planning for chemical buyers.
- Butane:Normal and isobutane isomers blended into gasoline for vapor pressure management. Refiners along the Texas Gulf Coast and in California's South Coast Air Basin dominate offtake.
- Natural Gasoline:Pentanes-plus mixture used as diluent for heavy crude transport and light naphtha feedstock. Alberta oil sands operators and Permian midstream companies represent the core demand base.
Ethane leads on scale; propane leads on momentum as export terminal capacity expands.
Application:
End-use specifications determine fractionation depth and contaminant tolerances across the value chain.
- Petrochemical Feedstocks:Ethane and propane destined for steam cracking to ethylene and propylene. Gulf Coast facilities from Corpus Christi to Port Arthur anchor continental demand, with EPA methane regulations tightening supply chain emissions accountability.
- Fuel:Propane and butane combusted for space heating, cooking, and agricultural drying. Rural residential markets in Kansas, Oklahoma, and northern Texas maintain infrastructure despite electrification mandates in coastal states.
- Liquefaction:NGLs cooled to cryogenic temperatures for export via specialized carriers. Cheniere and Venture Global facilities on the Louisiana and Texas coasts drive this application.
- Industrial Feedstock:Natural gasoline and butane as solvents, diluents, and chemical intermediates. Alberta's oil sands and Texas refineries represent concentrated demand pockets.
Petrochemical feedstocks dominate value capture; liquefaction is expanding most quickly as export capacity comes online.
Delivery Mode:
Transport selection hinges on basin pipeline density versus destination flexibility requirements.
- Pipelines:The lowest unit cost option at scale, requiring dedicated right-of-way and compressor stations. Enterprise Products and Energy Transfer operate the dominant systems connecting Permian and Appalachian production to Mont Belvieu.
- Truck Transport:Flexible last-mile delivery for stranded production and small-volume end users. Bakken operators rely on trucking where pipeline buildout lags behind drilling activity.
- Rail Transport:Unit trains of pressurized tank cars serving markets without pipeline access. Canadian propane moves via rail to Midwest and Northeast terminals.
- Barges:Waterborne movement along the Gulf Intracoastal Waterway and Mississippi River system. Houston Ship Channel and Port of New Orleans anchor this mode.
Pipelines lead on scale; barges lead on momentum as waterborne export capacity multiplies.
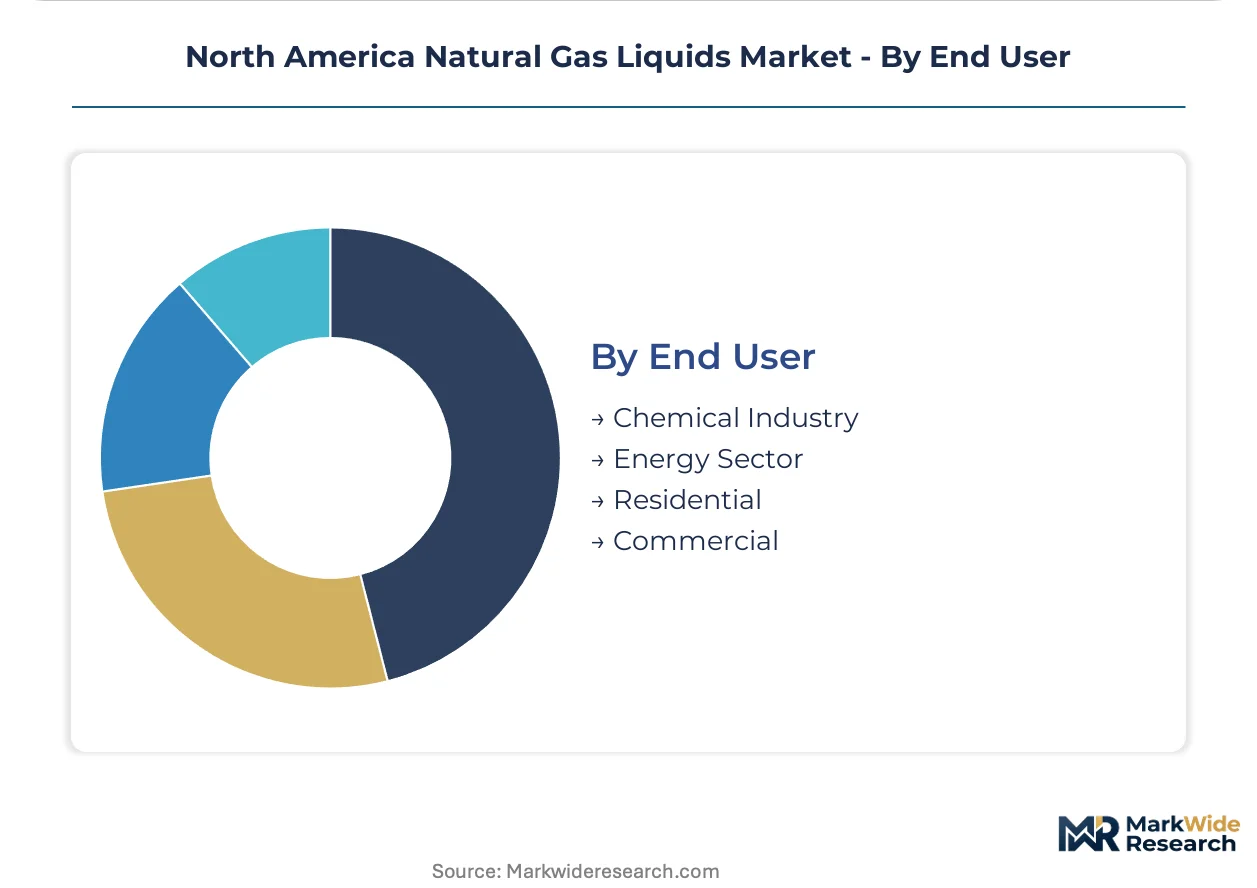
End User:
Customer scale and specification tolerance create tiered service requirements across segments.
- Chemical Industry:Large-volume purchasers with strict purity standards and long-term offtake contracts. Dow, ExxonMobil, and LyondellBasell facilities along the Texas Gulf Coast represent the most sophisticated demand.
- Energy Sector:Refiners and power generators using NGLs for blending and peaking fuel. California and Texas regulators impose distinct emissions constraints on this segment.
- Residential:Distributed propane consumers in rural areas without natural gas distribution. New York and Massachusetts electrification mandates are compressing this segment's long-term trajectory.
- Commercial:Restaurants, warehouses, and agricultural operations with moderate volume requirements. Seasonal price exposure remains a persistent pain point.
Chemical industry leads on scale; energy sector leads on momentum as power sector demand diversifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's NGL production infrastructure trails the United States in fractionation density, yet both countries face similar EPA and Environment Canada methane compliance curves that reshape capital deployment timelines.
United States
Permian Basin ethane extraction yields are forcing midstream operators to accelerate cryogenic fractionation capacity additions in West Texas. EPA methane performance standards under the Clean Air Act tighten leak detection protocols across extraction facilities. Mont Belvieu anchors continental NGL price discovery and attracts storage investments from Gulf Coast petrochemical buyers.
Canada
Alberta oil sands operators consume natural gasoline as diluent for heavy crude transport, creating steady demand for pentanes-plus mixtures. Environment Canada methane regulations align with EPA standards and drive investment in emissions monitoring systems. Stranded production in northern Alberta and British Columbia creates rail-dependent logistics challenges for NGL takeaway.
Mexico
Pemex refining system and emerging private petrochemical projects absorb propane and butane volumes from US Gulf Coast exporters. Energy regulatory reforms under CRE open midstream infrastructure to foreign investment and joint venture structures. Northeastern industrial corridors around Monterrey represent the primary demand concentration for imported NGL feedstocks.
North America Natural Gas Liquids Market Competitive Landscape
Top-tier vendors anchor integrated Permian-to-Gulf Coast pipeline networks, while mid-tier fractionation specialists compete on cryogenic processing efficiency and Mont Belvieu storage access. The vendor base stratifies across three archetypes: supermajors with captive production and downstream integration, pure-play midstream operators with hub-and-spoke logistics dominance, and independent producers deploying modular wellpad recovery systems. Capacity expansion and strategic pipeline interconnects constitute the dominant competitive moves, with operators racing to capture ethane volumes ahead of cracker commissioning timelines.
Among US-based integrated operators, ExxonMobil Corporation and Chevron Corporation exemplify the supermajor archetype through combined upstream production control and Gulf Coast petrochemical offtake relationships. Enterprise Products Partners LP occupies a position within the midstream tier, anchoring fractionation and export terminal capacity at Mont Belvieu. ONEOK, Inc. represents the gathering-system-to-fractionation extension model, linking Bakken and Mid-Continent production basins to downstream markets.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| Enterprise Products Partners LP |
| Targa Resources Corp |
| ONEOK, Inc. |
| Phillips 66 |
| Occidental Petroleum Corporation |
| Devon Energy |
| Others |
Value Network & Pricing Analysis
EPA methane performance standards under the Clean Air Act gate both qualified supply and premium-tier pricing access for cryogenic fractionation services, as compliance-certified operators capture margin premiums while non-compliant facilities face exclusion from long-term offtake contracts with Gulf Coast petrochemical buyers.
Pricing Analysis
Capacity additions in the Permian Basin are reshaping price floors for ethane and propane at Mont Belvieu, where contract-based long-term offtake agreements dominate over spot market exposure. Price differentiation rests on cryogenic processing purity grades and FERC interstate pipeline access tiers, with certified low-methane-emission supply commanding premiums. Cost compression in commodity-grade bulk sales is intensifying because midstream aggregators fragment market share. Small independent producers exhibit highest price sensitivity, while integrated supermajors with captive cracker demand show least.
Supply Chain Analysis
Remanufacturing flows for cryogenic turboexpander components and modular processing units create secondary supply channels that extend equipment lifecycles and compress capital requirements for independent operators. Geographic supply concentrates in the United States, Canada, and Mexico, with the Permian and Appalachian basins anchoring upstream extraction. Raw material dependencies include specialized alloy steels for sub-minus-120-degree Fahrenheit operations, compression train packages, and cryogenic insulation systems. Single-source vulnerability around Chinese-manufactured turboexpander components poses structural risk. Distribution runs through hub-and-spoke pipeline networks terminating at Mont Belvieu storage and export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America natural gas liquids market functions as a stable compounder, with petrochemical feedstock demand from Gulf Coast crackers providing steady volume absorption regardless of residential heating fuel displacement.
For Market Incumbents: Deploy cryogenic fractionation capacity additions in the Delaware sub-basin to capture ethane volumes ahead of cracker commissioning timelines. Deepen backward integration into wellpad gathering systems to defend against modular turboexpander disruption from independent producers. EPA methane performance standards threaten margin compression for non-compliant legacy facilities. For New Entrants and Emerging Players: Modular cryogenic processing technology offers a technology-first wedge into stranded production basins lacking pipeline takeaway. Target Appalachian Basin greenfield fractionation opportunities where infrastructure lags behind Marcellus and Utica drilling activity. Pursue rail-dependent logistics channels for Canadian and northern Rockies propane as the most penetrable distribution gap. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier fractionation specialists because cryogenic process engineering talent scarcity and FERC certification barriers protect incumbent returns. Platform consolidation around Mont Belvieu storage access and pipeline interconnects offers five-to-ten year viability. Monitor the pace of Gulf Coast cracker commissioning against midstream infrastructure buildout for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Fractionation Capacity Buildout | Permian Basin additions capture ethane molecules ahead of cracker demand absorption. |
| Backward Integration into Gathering Systems | Wellpad control secures feedstock supply against modular processor competition. |
| Long-term Supply Agreement with Petrochemical Buyers | Mont Belvieu-indexed contracts reduce merchant market price volatility exposure. |
| Green Certification Program for Methane Compliance | EPA performance standards differentiate premium-tier supply for Gulf Coast offtake. |
| Joint Venture for Appalachian Basin Infrastructure | Underdeveloped Pennsylvania and Ohio NGL processing offers first-mover returns. |
Research Methodology
Bottom-up petrochemical feedstock demand modeling reconciled against top-down cryogenic fractionation capacity tracking forms the analytical core of this study. Primary interviews with midstream infrastructure planners, cryogenic process engineers, petrochemical procurement directors, and FERC regulatory specialists combined with secondary validation from EIA production data, FERC interstate pipeline filings, EPA emissions inventories, and Texas Railroad Commission flaring reports. Triangulation between upstream extraction forecasts and downstream cracker capacity announcements ensures consistency across supply-demand balances.
Historical trendline analysis of ethane recovery rates and Mont Belvieu price spreads established baseline growth patterns across the projection horizon. The analytical framework segments by product type, application, delivery mode, and end user, with additional modeling of regional regulatory framework variations between US, Canadian, and Mexican jurisdictions. CAGRs derive from elasticity-adjusted demand projections and infrastructure commissioning timelines. Forecast inputs include Permian Basin wellhead gas composition trends and Gulf Coast petrochemical capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrification substitution rates in residential heating and potential Appalachian Basin infrastructure acceleration. Practitioners should monitor EPA methane rule enforcement intensity and Texas Railroad Commission flaring restriction tightening for early signals of supply-side constraint or compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Oil Refinery Market
Petroleum Products
Balanos Oil Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Natural Gas Liquid Market