
 Wind Turbine Decommissioning Market | 2026-2036
Wind Turbine Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Decommissioning Market Analytics
Blade material separation technology is fragmenting into thermochemical, mechanical, and cement co-processing pathways, creating divergent equipment footprints and contractor skill requirements. DEME NV anchors its North Sea position through integrated marine lift and transport logistics. Ramboll Group AS leverages multidisciplinary engineering capabilities across environmental permitting and structural dismantling. EOS Engineering and Service Co. Ltd. competes on specialized blade shredding systems tailored to Asian fiberglass compositions.
Wind turbine decommissioning encompasses the systematic removal, transport, and material recovery of utility-scale wind energy assets at end-of-design-life, typically involving 40-80 meter blade segments, steel tower sections exceeding 80 tonnes, and nacelle assemblies containing rare-earth generators. The process requires mobile hydraulic shears, strand jack systems, and controlled demolition sequencing to manage composite waste streams and foundation recovery. Disassembly services currently command the largest revenue share due to labor-intensive offshore marine operations and crane vessel day rates. Recycling of blade composites through pyrolysis and mechanical pulverization represents the fastest-expanding technology segment, driven by landfill diversion mandates and emerging cement kiln co-processing partnerships. Gearbox and nacelle recovery sustains secondary margin pools through remanufacturing channels for bearing assemblies and generator components.
The EPA oversees hazardous material handling and site remediation standards for US decommissioning projects, while the EU Waste Framework Directive and national landfill restrictions on fiber-reinforced polymers mandate minimum recycling recovery rates across member states. These frameworks elevate compliance costs but create licensed-service scarcity that protects established operators. Stakeholders must evaluate technology partnerships based on blade resin chemistry compatibility and emerging thermoplastic blade designs that promise future closed-loop recyclability.
Market Dynamics
The EU Waste Framework Directive's landfill prohibitions on fiber-reinforced polymers are forcing immediate capital deployment into blade shredding infrastructure, while Round 1 offshore installations in the United Kingdom create synchronized demand waves for marine heavy-lift capacity.
Growth Catalysts
- German utility fleet aging:Onshore turbines installed during the 2000s expansion now require systematic removal under end-of-design-life protocols, concentrating contractor demand in Lower Saxony and Schleswig-Holstein.
- Mechanical recycling mandates:National blade landfill bans across Denmark, the Netherlands, and Germany establish minimum recovery thresholds that license-equipped processors capture exclusively.
- Pyrolysis technology maturation:Thermochemical decomposition of epoxy resin matrices now yields recoverable glass fiber and syngas streams, enabling cement kiln co-processing partnerships with infrastructure operators.
Market Restraints
- Specialized vessel scarcity:Jack-up barge availability for offshore nacelle removal concentrates among North Sea marine contractors, creating booking bottlenecks during seasonal weather windows.
- Composite chemistry heterogeneity:Blade resin systems vary across manufacturer vintages, forcing shredding operators to maintain multiple process lines or reject incompatible waste streams.
- Foundation recovery economics:Reinforced concrete base removal requires hydraulic pulverization and transport logistics that often exceed scrap steel recovery value, depressing project margins.
Strategic Opportunities
- Taiwan offshore pipeline:The Changhua and Yunlin zone developments will generate decommissioning demand from 2035 onward, creating early-mover positioning for marine logistics specialists.
- Thermoplastic blade designs:Vestas and Siemens Gamesa R&D programs target recyclable thermoplastic resins that promise closed-loop material recovery, shifting equipment requirements toward melt-reprocessing systems.
- Generator remanufacturing channels:Rare-earth permanent magnet recovery from direct-drive nacelles enables secondary supply to electric vehicle motor manufacturers, extending value capture beyond scrap pricing.
Industry Challenges
- Offshore technician certification gaps:GWO BST and blade repair qualifications do not cover marine demolition sequencing, forcing contractors to develop proprietary training programs.
- Strand jack system mobilization:Tower section lowering requires specialized hydraulic equipment with limited rental availability, compressing project timelines during peak demand periods.
- Cross-border waste shipment compliance:Basel Convention notifications for blade composite transport between EU member states introduce documentation delays that extend inventory holding costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Decommissioning Market |
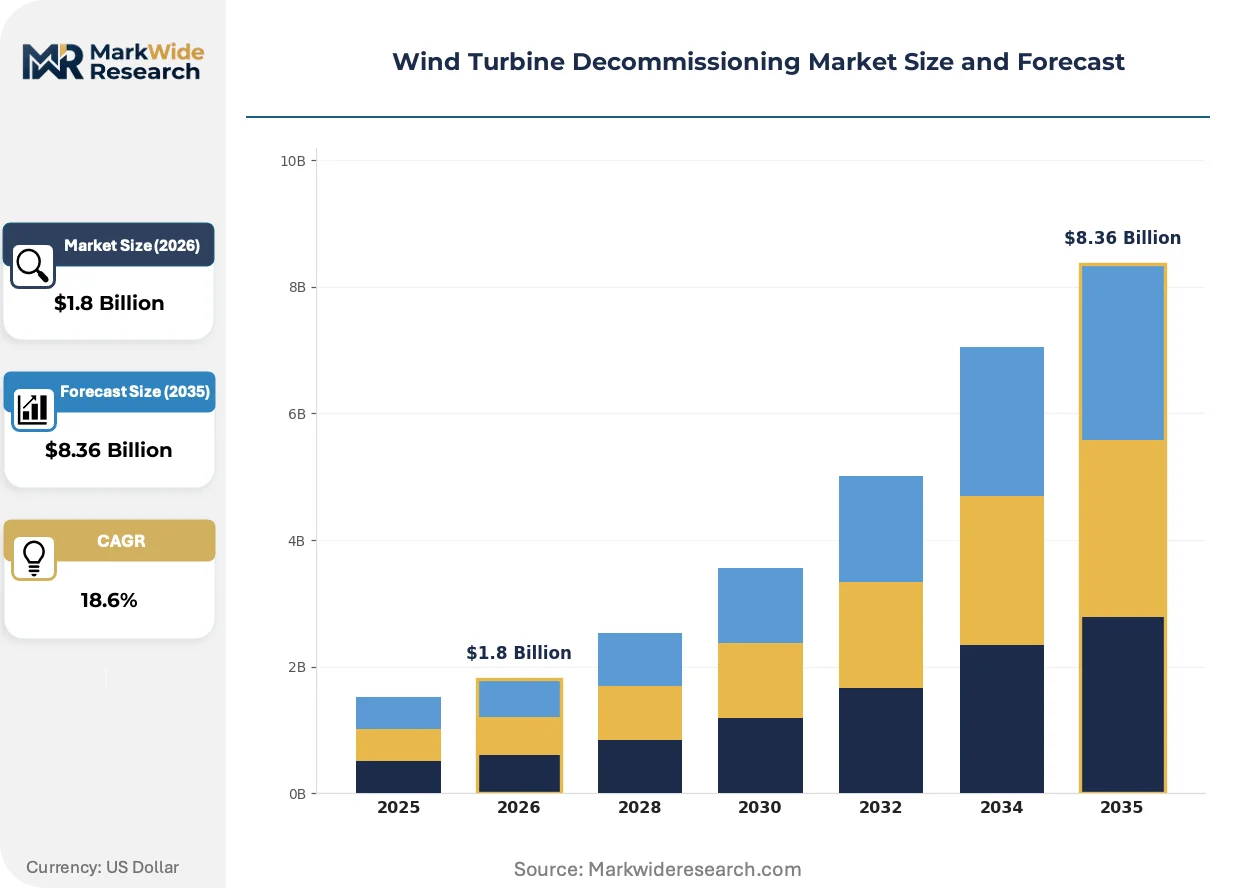
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Disassembly, Recycling, Transport, Disposal Technology: Separator Systems, Shredders, Crushers, Compacting Equipment End User: Utility Companies, Renewable Energy Firms, Environmental Agencies, Contractors Component: Towers, Blades, Gearboxes, Nacelles |
| Companies Covered | Oceaneering International Inc., Intertek Group Plc, DEME NV, Ramboll Group AS, EOS Engineering and Service Co. Ltd., General Electric Co., Aggreko Plc, Secure Energy Services, Cadeler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Decommissioning Market Evolving Landscape
Digital twin technology is compressing project planning cycles for complex offshore removals, while regulatory pressure on composite waste streams accelerates process innovation across thermochemical and mechanical pathways.
Pyrolysis reactor systems are virtualizing blade waste processing by enabling remote monitoring of temperature profiles and syngas composition. Industrial cement producers in Germany and Poland now operate captive pyrolysis units to secure alternative fuel streams. This distributed processing model is virtualizing the traditional centralized shredding facility economics, compressing transport radius requirements and enabling smaller-batch operations.
REACH authorization requirements for epoxy resin constituents are tightening chemical registration obligations for blade manufacturers operating across EU member states. The European Chemicals Agency's 2024 substance evaluation roadmap specifically targets bisphenol-A derivatives common in legacy turbine blades. Equipment suppliers now prioritize shredding systems capable of handling pre-2010 resin chemistries that face restricted disposal pathways.
Utility procurement departments are unbundling decommissioning contracts from original equipment manufacturer service agreements, creating direct tender opportunities for specialized contractors. This disintermediation is most visible in the United Kingdom, where Ørsted and RWE now issue separate marine logistics and onshore recycling lots. Danish and German utilities are following this pattern, fragmenting what were previously single-source OEM relationships.
Wind Turbine Decommissioning Market Segmentation
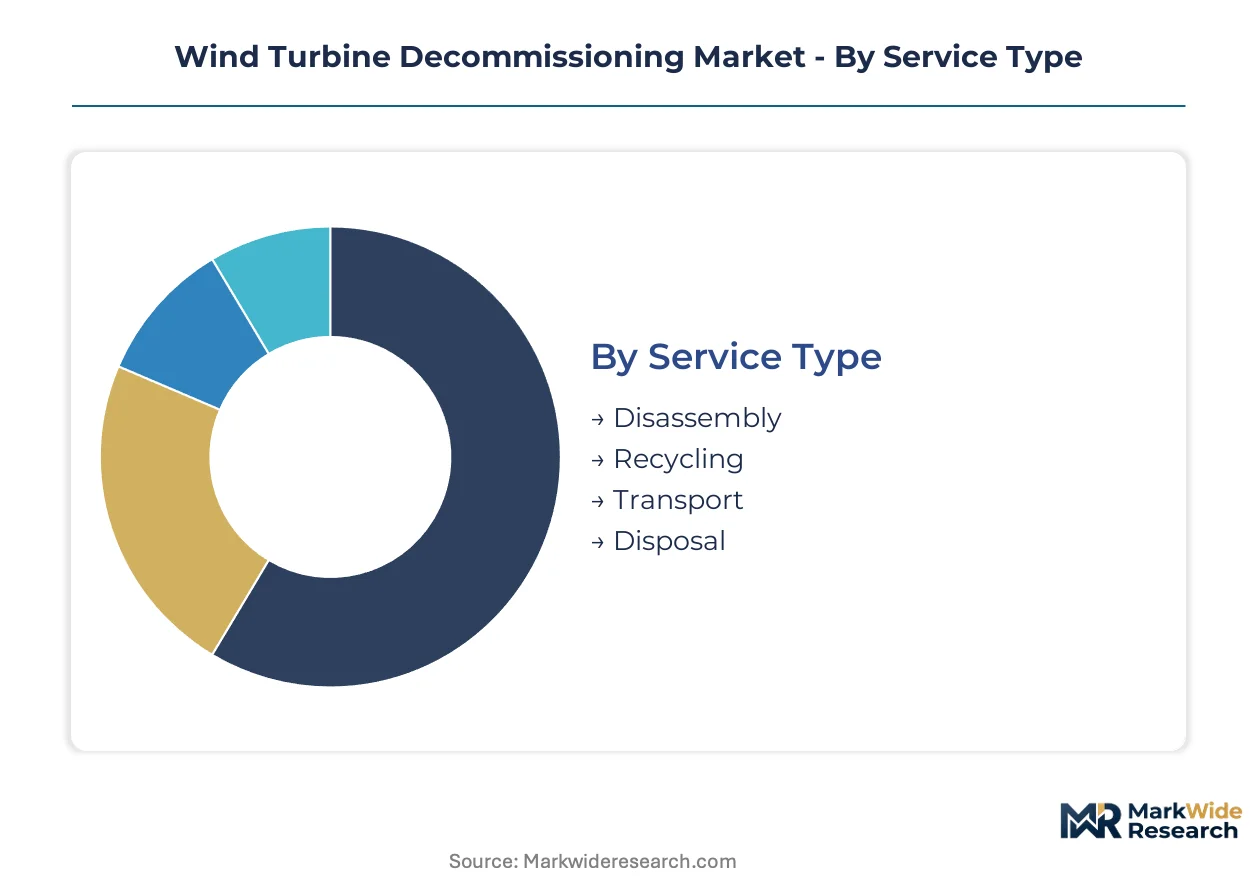
Decommissioning contractors configure service portfolios around four distinct value layers, each demanding specialized equipment footprints and regulatory certifications. Technology selection and end-user procurement patterns fragment the addressable market into discrete bidding pools with divergent margin profiles.
Service Type:
After-sales service intensity peaks during disassembly operations, where marine weather windows and crane vessel scheduling create 24/7 operational tempo requirements.
- Disassembly:Systematic dismantling of tower sections, nacelle removal, and blade detachment using mobile hydraulic shears and strand jack systems. Offshore marine operations in the United Kingdom's Round 1 zones command premium day rates due to jack-up barge scarcity during seasonal weather windows.
- Recycling:Material recovery through pyrolysis reactors, mechanical pulverization, and cement kiln co-processing partnerships. German and Polish cement producers now operate captive pyrolysis units, compressing transport radius requirements for blade composite waste streams.
- Transport:Specialized heavy-haul logistics for 40-80 meter blade segments and 80+ tonne tower sections, including cross-border Basel Convention documentation for EU member state shipments.
- Disposal:Landfill diversion and hazardous material handling under EPA and EU Waste Framework Directive compliance protocols, with national blade landfill bans restricting permissible pathways.
By volume, Disassembly leads. By growth pace, Recycling is ahead.
Technology:
Equipment procurement decisions track composite chemistry heterogeneity across manufacturer vintages, forcing operators to maintain multiple process lines.
- Separator Systems:Resin-matrix separation technology for fiber recovery, including thermochemical and mechanical pathways. DEME NV integrates marine lift systems with onshore separation logistics across North Sea installations.
- Shredders:Blade size reduction equipment tailored to fiberglass compositions, with Asian-market specialists developing distinct rotor configurations for regional resin chemistries.
- Crushers:Foundation pulverization systems for reinforced concrete base removal, often exceeding scrap steel recovery value in project economics.
- Compacting Equipment:Volume reduction systems for transport efficiency, deployed where pyrolysis preprocessing occurs at distributed cement plant sites.
Separator Systems capture the highest capital intensity per installation. Shredders deploy most widely across contractor fleets.
End User:
Procurement unbundling from OEM service agreements is redirecting contract flow toward specialized contractors with licensed processing capabilities.
- Utility Companies:German utilities in Lower Saxony and Schleswig-Holstein are expanding decommissioning contracts as aging onshore fleets reach end-of-design-life, with Ørsted and RWE issuing separate marine logistics and recycling lots.
- Renewable Energy Firms:Developers of Taiwan's Changhua and Yunlin offshore zones positioning for decommissioning demand from 2035 onward.
- Environmental Agencies:Regulatory enforcement and site remediation oversight, particularly EPA hazardous material handling standards in US markets.
- Contractors:Specialized demolition firms developing proprietary training programs for marine demolition sequencing beyond standard GWO BST qualifications.
Utility Companies dominate current contract value. Renewable Energy Firms represent the steepest expansion trajectory as offshore pipelines mature.
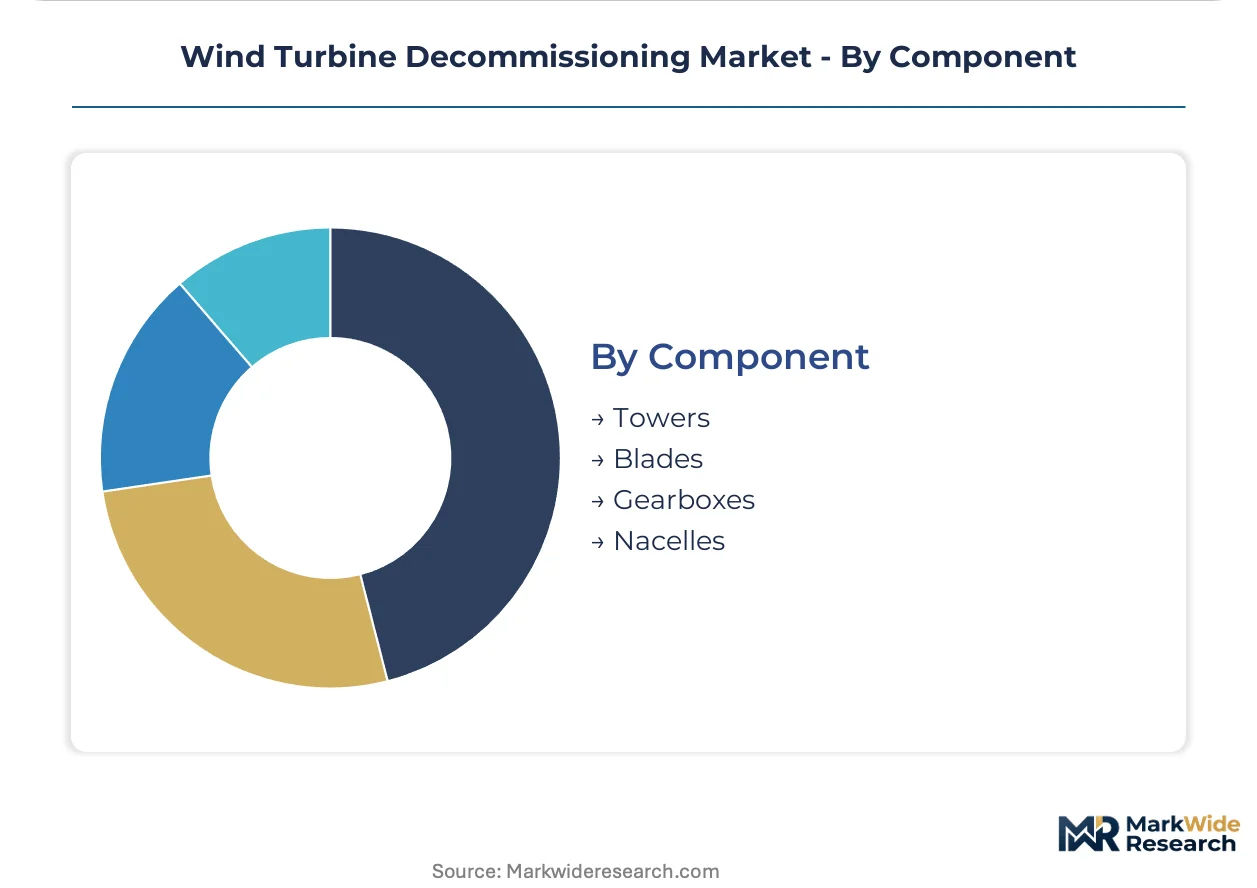
Component:
Material recovery economics vary sharply by component type, with rare-earth content driving secondary value capture in generator assemblies.
- Towers:Steel sections exceeding 80 tonnes requiring strand jack lowering and heavy-haul transport, with scrap steel pricing determining project margin floors.
- Blades:Fiber-reinforced polymer segments driving landfill diversion mandates and pyrolysis infrastructure investment across Denmark, the Netherlands, and Germany.
- Gearboxes:Bearing assembly remanufacturing channels sustaining secondary margin pools through component recovery.
- Nacelles:Rare-earth permanent magnet recovery from direct-drive units enabling supply to electric vehicle motor manufacturers.
Blades generate the most complex regulatory compliance burden. Nacelles offer the highest unit value recovery through magnet extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contractors export decommissioning services to North Sea offshore zones, while Danish recycling technology flows into Polish cement co-processing partnerships. Trade corridors concentrate equipment and marine logistics expertise across Northern European wind clusters.
Germany
Utility fleets installed during the 2000s expansion now require systematic removal across Lower Saxony and Schleswig-Holstein. The EU Waste Framework Directive and national blade landfill bans mandate minimum recycling recovery rates. DEME NV anchors North Sea operations through integrated marine lift and transport logistics serving German offshore zones.
United Kingdom
Round 1 offshore installations now require systematic removal, synchronizing demand waves for marine heavy-lift capacity. Ørsted and RWE unbundle decommissioning contracts from OEM service agreements, issuing separate marine logistics and recycling lots. Scottish and English North Sea zones concentrate jack-up barge deployment during seasonal weather windows.
Denmark
Mechanical recycling mandates establish minimum recovery thresholds that license-equipped processors capture exclusively. Vestas R&D programs target recyclable thermoplastic resins for future closed-loop material recovery. Copenhagen and Aarhus clusters develop proprietary training programs for marine demolition sequencing beyond standard GWO BST qualifications.
Poland
Industrial cement producers operate captive pyrolysis units to secure alternative fuel streams from blade composite waste. REACH authorization requirements for epoxy resin constituents tighten chemical registration obligations across EU member states. Silesian and Greater Poland cement clusters compress transport radius requirements through distributed processing models.
Taiwan
The Changhua and Yunlin zone developments will generate decommissioning demand from 2035 onward. Environmental agencies enforce site remediation standards for offshore infrastructure removal. Kaohsiung marine logistics specialists position for early-mover advantage as the offshore pipeline matures.
Wind Turbine Decommissioning Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented bidding pools. Marine logistics contractors capture premium day rates through jack-up barge scarcity, while shredding equipment vendors differentiate on resin chemistry compatibility. Three archetypes dominate: integrated marine-heavy-lift operators, multidisciplinary engineering consultancies, and specialized blade processing equipment fabricators. Capacity expansion and technology licensing represent the dominant competitive moves.
Among integrated marine service providers, Oceaneering International Inc. and Cadeler occupy positions spanning subsea engineering and offshore vessel operations. DEME NV exemplifies the channel-controlling archetype through Belgian-based marine construction capabilities. Ramboll Group AS represents the multidisciplinary engineering tier, while EOS Engineering and Service Co. Ltd. anchors specialized equipment fabrication. Intertek Group Plc sits within testing and certification services, and Aggreko Plc exemplifies temporary power solutions for remote decommissioning sites.
| Leading Market Players |
|---|
| Oceaneering International Inc. |
| Intertek Group Plc |
| DEME NV |
| Ramboll Group AS |
| EOS Engineering and Service Co. Ltd. |
| General Electric Co. |
| Aggreko Plc |
| Secure Energy Services |
| Cadeler |
| Others |
Value Network & Pricing Analysis
Jack-up barge concentration among North Sea marine contractors anchors premium day-rate capture for offshore nacelle removal, compressing margin pools toward vessel operators and licensed blade processors while squeezing project developers on seasonal booking windows.
Pricing Analysis
Current-generation pyrolysis reactor systems command substantial premiums over mechanical shredding equipment, while next-generation thermoplastic blade designs promise future closed-loop recovery economics that reshape equipment depreciation models. Project-based contracting dominates, with price differentiation tracking marine logistics bundling and Basel Convention documentation compliance tiers. Pricing pressure stems from foundation recovery economics that often exceed scrap steel recovery value, eroding project margins. Small regional contractors exhibit highest price sensitivity due to stranded asset risk in single-fleet configurations, while integrated marine operators maintain pricing discipline through vessel scarcity.
Supply Chain Analysis
Export-control regimes on strand jack hydraulic systems and rare-earth magnet recovery technology limit equipment flows from Germany and Denmark into Asian markets, constraining contractor capability buildout in Taiwan and Japan. Supply concentration centers on Belgium for marine heavy-lift vessel fabrication, Germany for pyrolysis reactor engineering, and China for blade shredding rotor components. Raw material dependencies include high-strength steel for tower section handling, specialized hydraulic fluids for strand jack systems, and refractory materials for pyrolysis furnace linings. Single-source vulnerability concentrates in jack-up barge availability during North Sea seasonal windows. Distribution runs through utility procurement departments now unbundling contracts from OEM service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine demolition sequencing expertise and Basel Convention licensing constitute scarce, defensible capabilities that concentrate competitive advantage among incumbent operators with established North Sea track records.
For Market Incumbents: Entrench market position through captive pyrolysis unit deployment at cement plant partnerships in Germany and Poland, securing alternative fuel stream offtake agreements that lock out competing blade processors. Deepen backward integration into strand jack system maintenance and proprietary technician training programs beyond standard GWO BST qualifications, creating switching costs against emerging marine contractors. The threat of thermoplastic blade designs displacing current shredding infrastructure demands R&D partnership positioning with Vestas and Siemens Gamesa. For New Entrants and Emerging Players: Build out specialized blade processing capabilities targeting Asian fiberglass compositions distinct from European epoxy resin matrices, leveraging regional chemistry knowledge gaps among incumbent operators. Taiwan's Changhua and Yunlin offshore zones represent the most penetrable geography, with decommissioning demand emerging from 2035 onward and limited established contractor presence. A go-to-market angle anchored in Kaohsiung marine logistics positioning with early environmental agency relationship development captures first-mover advantage. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine construction specialists holding jack-up barge fleets but lacking integrated blade processing capabilities. Long-term viability over the five-to-ten year horizon rests on technology licensing breadth across thermochemical and mechanical recycling pathways. Acquisition targets should demonstrate REACH authorization compliance for epoxy resin constituent handling. The signal to watch is utility procurement unbundling velocity in Denmark and Germany as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pyrolysis Unit Deployment | Cement producers in Germany secure alternative fuel streams while locking blade waste supply. |
| Proprietary Marine Technician Training | Contractors develop demolition sequencing capabilities beyond GWO BST standard qualifications. |
| Technology Licensing Partnerships | Equipment vendors expand resin chemistry compatibility across Vestas and Siemens Gamesa blade vintages. |
| Basel Convention Documentation Systems | Cross-border waste shipment compliance creates licensed-service scarcity protecting established operators. |
| Generator Remanufacturing Channel Development | Rare-earth magnet recovery supplies electric vehicle motor manufacturers beyond scrap pricing. |
Research Methodology
A standing panel of marine logistics directors, utility procurement officers, cement plant fuel sourcing managers, and blade shredding equipment engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Waste Framework Directive implementation reports, EPA hazardous material handling guidance, Basel Convention notification databases, and North Sea offshore project development records. Bottom-up contractor capacity assessments triangulated against top-down utility decommissioning obligation schedules.
Scenario-bracketing around regulatory enforcement intensity and vessel availability shocks anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology pathway, end-user procurement pattern, and component material recovery economics. CAGRs derived from utility fleet age profiles and landfill ban implementation timelines. Industry-specific forecast inputs incorporated Round 1 offshore removal schedules and pyrolysis reactor deployment pipelines.
Sensitivities concentrate around jack-up barge booking bottlenecks during seasonal weather windows and thermoplastic blade design adoption curves that reshape equipment requirements. Forecasts reflect documented assumptions on regulatory enforcement consistency and composite chemistry standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Japan Wind Energy Market