
 Dual Rotor Wind Turbine Market | 2026-2036
Dual Rotor Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Rotor Wind Turbine Market Foresight
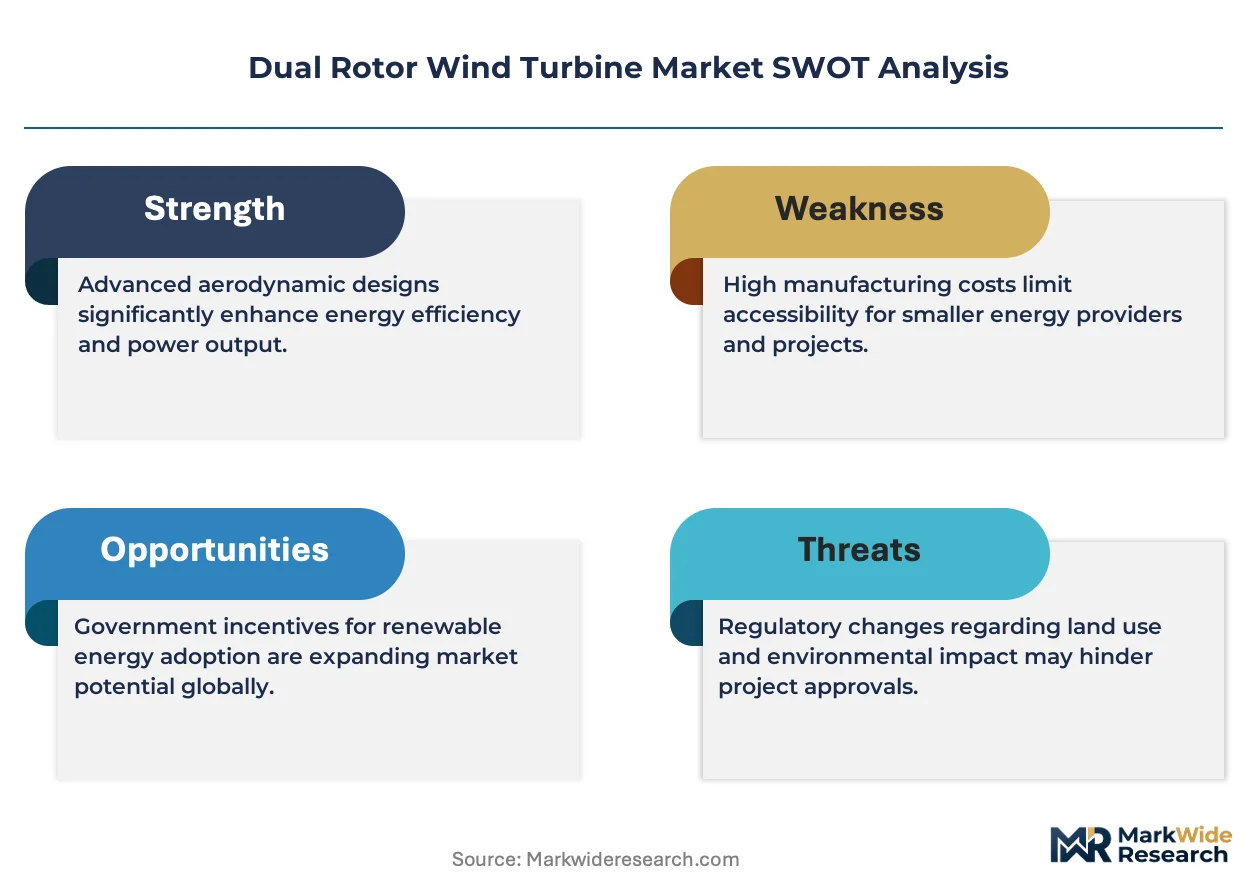
Project finance structures with long-term power purchase agreements is rewriting competitive access for dual rotor turbine suppliers. Siemens Gamesa leverages its offshore installation fleet to anchor large-scale deployments in European waters. GE Renewable Energy sustains R&D intensity across direct drive architectures that reduce gearbox maintenance burdens. Xinjiang Goldwind Science & Technology dominates manufacturing scale through captive supply of permanent magnet components.
A dual rotor wind turbine employs two counter-rotating rotors on a single nacelle, typically achieving tip speed ratios above six and power coefficients approaching the Betz limit through enhanced wake recovery. Horizontal axis configurations lead commercial deployments due to mature blade aerodynamics and established supply chains, while offshore installations represent the fastest-growing application segment driven by higher capacity factors and reduced land-use constraints. Gearless direct drive technology captures expanding margin pools as operators prioritize reliability in remote marine environments.
The EU Green Deal and F-Gas Regulation shape turbine cooling system standards across European markets, while China's MIIT enforces GB standards for grid synchronization that affect generator selection. The US FAA reviews aviation lighting and marking protocols for tall structures exceeding 200 meters, influencing tower design. Stakeholders must monitor evolving certification timelines for floating installation methods before committing capital to deep-water projects.
Market Dynamics
Counter-rotating rotor architectures are compressing wake losses and expanding recoverable energy density per unit of swept area, forcing incumbent suppliers to reconfigure nacelle designs around dual-drive power electronics and advanced pitch control systems.
Growth Catalysts
- EU Green Deal certification pathways:Streamlined type-approval frameworks for next-generation turbine architectures accelerate deployment timelines in German and Danish waters.
- Floating foundation penetration:Water depths exceeding 60 meters unlock previously inaccessible wind resources across Portugal's Atlantic coast and Scotland's Outer Hebrides.
- Permanent magnet supply chain maturation:Rare-earth processing capacity expansion in Inner Mongolia and Shandong provinces secures generator component availability for multi-megawatt builds.
Market Restraints
- Neodymium price volatility:Permanent magnet cost swings expose generator manufacturers to margin compression when rare-earth oxide markets tighten.
- Specialized vessel scarcity:Heavy-lift jack-up fleet concentration among North Sea operators creates installation bottleneck risk for large-diameter dual rotor assemblies.
- F-Gas Regulation compliance costs:EU-mandated transition to low-global-warming-potential coolants forces redesign of thermal management systems in existing nacelle platforms.
Strategic Opportunities
- US IRA production tax credit extensions:Domestic content bonuses incentivize assembly localization along Gulf Coast ports with existing heavy-industry infrastructure.
- Hybrid renewable-plus-storage configurations:Co-location with battery systems enables grid-forming inverters that stabilize output from variable wind regimes.
- Digital twin predictive maintenance:Sensor fusion across dual rotor drivetrains extends mean time between failures and reduces offshore service vessel calls.
Industry Challenges
- Multi-body aerodynamics simulation talent:Computational fluid dynamics expertise for counter-rotating wake interaction modeling remains concentrated among academic research consortia.
- Floating platform certification timelines:DNV and Bureau Veritas have yet to finalize unified standards for dual rotor load cases on semi-submersible foundations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Rotor Wind Turbine Market |
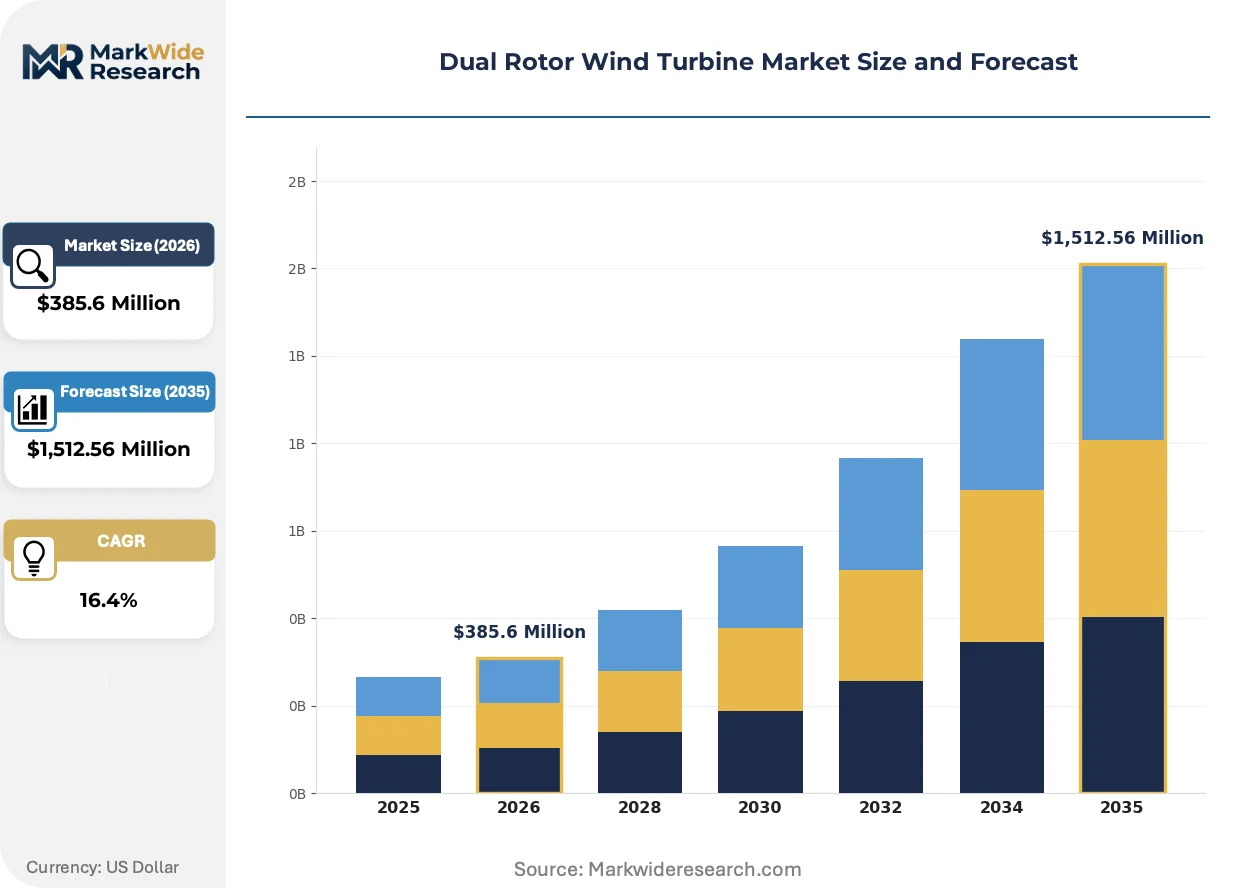
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,512.56 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore, Small Scale Technology: Gearless, Direct Drive, Induction Generator, Synchronous Generator End User: Utility, Industrial, Commercial, Residential Installation: Ground Mounted, Rooftop, Floating, Integrated Systems |
| Companies Covered | Siemens Gamesa, MHI Vestas Offshore Wind, GE Renewable Energy, Enercon GmbH, Nordex SE, Senvion S.A., Xinjiang Goldwind Science & Technology, Sinovel Wind Group, Suzlon Energy Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Rotor Wind Turbine Market Shifts & Advancements
Wake recovery optimization and modular drivetrain architectures are compressing levelized cost of energy benchmarks while opening new water depth categories to commercial development.
Direct drive permanent magnet generators are rendering obsolete multi-stage gearbox designs in offshore installations. Developers in the German Bight and Scottish North Sea corridors specify gearless configurations for 12+ MW dual rotor platforms. The elimination of high-speed mechanical stages reduces unplanned maintenance events by removing failure-prone bearing and lubrication systems from the nacelle.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon-based cooling systems in electrical equipment above 1 MW rated capacity. Turbine OEMs are retrofitting thermal management with CO2 or propane loop architectures. Offshore units above 200 meters hub height face the steepest compliance deadlines, with Danish and Dutch certification bodies issuing conditional type certificates contingent on coolant transition timelines.
Utility procurement departments now unbundle long-term service agreements from initial equipment supply contracts. Independent service providers with drone-based blade inspection capabilities and predictive analytics platforms capture aftermarket revenue previously retained by manufacturers. This disintermediation is most advanced in UK Round 4 lease areas, where project finance structures favor competitive O&M tendering to reduce operational expenditure projections.
Dual Rotor Wind Turbine Market Segmentation
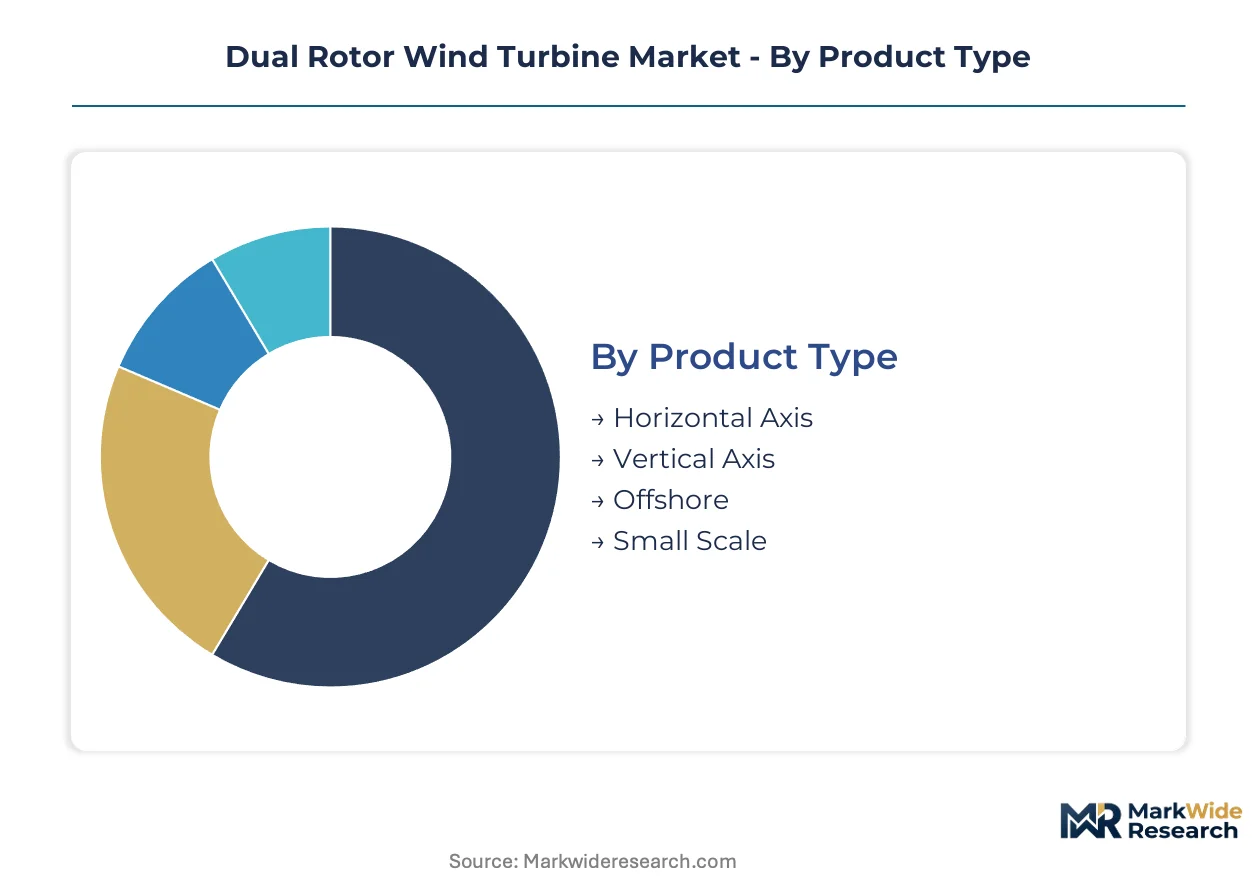
Dual rotor wind turbine architectures demand granular segmentation to capture divergent technical requirements across marine and terrestrial environments. Product configurations vary sharply in aerodynamic complexity, drivetrain topology, and foundation engineering, each commanding distinct supply chain competencies and certification pathways.
Product Type:
Mature horizontal axis designs dominate commercial deployments while emerging vertical axis variants target distributed generation niches.
- Horizontal Axis:Counter-rotating blade pairs mounted on parallel shafts achieve tip speed ratios above six through advanced pitch coordination. German North Sea developers specify these configurations for 12+ MW platforms where wake recovery maximizes energy density per square kilometer of lease area.
- Vertical Axis:Darrieus and H-rotor geometries eliminate yaw mechanisms and reduce nacelle complexity. Urban planners in Copenhagen and Rotterdam specify compact vertical axis units for building-integrated installations where omni-directional wind capture offsets lower peak efficiency.
- Offshore:Salt-resistant coatings and sealed drivetrains address corrosive marine atmospheres.
- Small Scale:Sub-100 kW units serve agricultural and remote industrial loads.
Horizontal Axis retains volume leadership; Offshore holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium gearless architectures from conventional induction systems.
- Gearless:Direct drive permanent magnet generators eliminate multi-stage gearboxes and their lubrication maintenance burdens. Scottish North Sea operators specify gearless configurations for floating platforms where service vessel access is constrained by weather windows.
- Direct Drive:Synchronous generators with full-power converters enable grid-forming capabilities. Danish grid codes now mandate direct drive inverters for new offshore interconnects to stabilize weak transmission networks.
- Induction Generator:Squirrel-cage designs persist in onshore repowering projects.
- Synchronous Generator:Wound rotor variants offer variable speed control without rare-earth dependencies.
Gearless systems command premium pricing; Direct Drive is gaining share fastest in new installations.
End User:
Customer type determines financing structure and operational risk allocation.
- Utility:Vertically integrated power producers deploy dual rotor fleets under regulated return frameworks. Iberdrola and Ørsted procure 15-20 year service agreements bundled with equipment supply to de-risk offshore operational expenditure.
- Industrial:Energy-intensive manufacturers pursue corporate power purchase agreements. Aluminum smelters in Norway and steel producers in Sweden co-locate dual rotor arrays to hedge against Nordic spot market volatility.
- Commercial:Retail and logistics chains target renewable energy certificates.
- Residential:Prosumer installations remain marginal due to acoustic and visual impact constraints.
Utility segment anchors procurement volume; Industrial buyers are expanding most quickly behind corporate sustainability commitments.
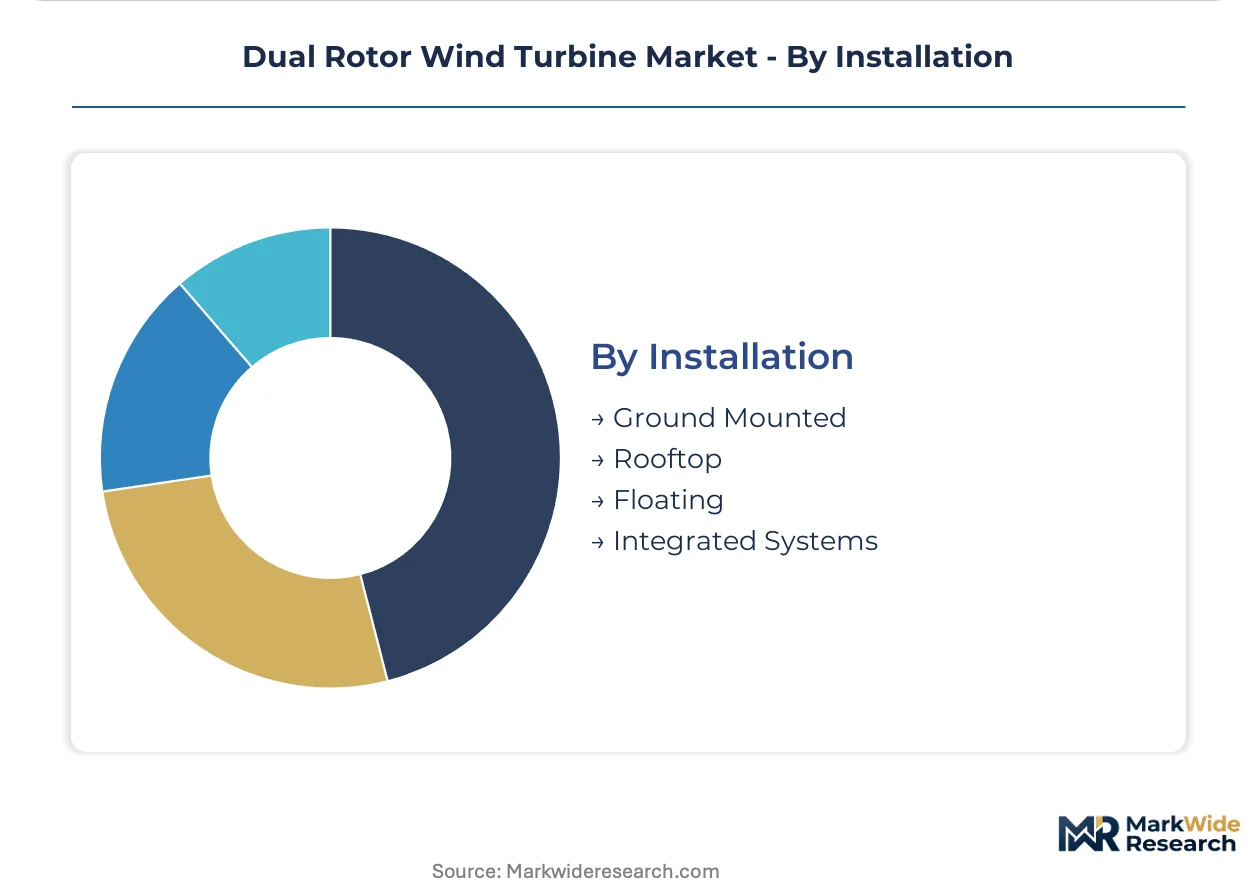
Installation:
Foundation topology dictates supply chain geography and vessel requirements.
- Ground Mounted:Fixed monopile and jacket foundations dominate water depths below 60 meters. Installation contractors in Esbjerg and Cuxhaven maintain dedicated fleets for heavy-lift operations in the German Bight.
- Floating:Semi-submersible and tension leg platforms unlock deep-water resources. Portugal's WindFloat Atlantic and Scotland's Kincardine demonstrators prove dual rotor compatibility with dynamic cable systems.
- Rooftop:Structural load constraints limit dual rotor deployment.
- Integrated Systems:Hybrid wind-solar-storage configurations optimize land use.
Ground Mounted retains deployment dominance; Floating platforms represent the steepest expansion trajectory as water depths increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in dual rotor wind turbine components concentrate manufacturing in Germany and China while installation demand clusters in North Sea and Baltic Sea corridors. Component trade flows from Inner Mongolia and Shandong provinces supply permanent magnet generators to European assembly facilities. Water depth gradients and grid infrastructure availability determine regional deployment sequencing.
Germany
Offshore lease auctions in the German Bight and Baltic Sea drive procurement of 12+ MW platforms. The EU Green Deal streamlines type-approval frameworks for next-generation turbine architectures. Installation contractors in Cuxhaven and Bremerhaven maintain heavy-lift fleets for monopile and jacket foundation deployments.
United Kingdom
Round 4 lease areas and ScotWind allocations expand floating platform demonstration capacity. The UK Marine Management Organisation coordinates seabed licensing with Crown Estate lease rounds. Aberdeen and Peterhead anchor supply chain clusters for dynamic cable systems and semi-submersible foundation integration.
China
Provincial renewable energy quotas in Shandong and Jiangsu accelerate domestic dual rotor adoption. MIIT enforces GB standards for grid synchronization that affect generator selection. Manufacturing concentration in Inner Mongolia and Xinjiang secures rare-earth processing capacity for permanent magnet component supply.
Denmark
Danish grid codes mandate direct drive inverters for new offshore interconnects to stabilize weak transmission networks. The Danish Energy Agency coordinates nearshore deployment zones with harbor expansion in Esbjerg. Test facilities at Østerild support prototype certification for floating installation methods.
United States
IRA production tax credit extensions with domestic content bonuses incentivize assembly localization along Gulf Coast ports. The FAA reviews aviation lighting protocols for structures exceeding 200 meters, influencing tower design specifications. Corpus Christi and New Orleans leverage existing heavy-industry infrastructure for nacelle integration facilities.
Dual Rotor Wind Turbine Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated turbine OEMs with captive offshore installation capabilities. Tiered competitive positioning separates full-stack providers from component specialists and regional licensees. Two strategic archetypes dominate: European engineering-intensive developers with floating platform expertise, and Chinese scale manufacturers with upstream magnet supply control. Competitive moves center on strategic partnerships for floating foundation certification and geographic expansion through domestic content compliance in incentive markets.
Among European engineering-intensive developers, Siemens Gamesa and MHI Vestas Offshore Wind occupy positions anchored by North Sea installation fleet control and floating platform load case expertise. GE Renewable Energy represents the diversified industrial conglomerate archetype with direct drive architecture specialization. Xinjiang Goldwind Science & Technology exemplifies the vertically integrated Chinese manufacturer model with captive permanent magnet supply chain positioning.
| Leading Market Players |
|---|
| Siemens Gamesa |
| MHI Vestas Offshore Wind |
| GE Renewable Energy |
| Enercon GmbH |
| Nordex SE |
| Senvion S.A. |
| Xinjiang Goldwind Science & Technology |
| Sinovel Wind Group |
| Suzlon Energy Limited |
| Others |
Supply & Pricing Matrix
The North Sea heavy-lift corridor from Esbjerg to Cuxhaven transmits freight cost volatility directly into nacelle assembly pricing, concentrating supplier power among German and Danish installation contractors while forcing OEMs to differentiate offshore platforms through certification grade and service bundling.
Pricing Analysis
Industrial OEM buyers anchor project-based long-term offtake structures across dual rotor turbine procurement. Three-tier pricing stratifies across premium gearless direct drive, standard induction generator, and economy repowering configurations. Cost compression in the economy tier is intensifying because Chinese permanent magnet suppliers are expanding rare-earth processing capacity. Utilities with regulated return frameworks exhibit lowest price sensitivity, while independent power developers face acute margin pressure from vessel charter rate spikes.
Supply Chain Analysis
Rare-earth oxide feedstock from Inner Mongolia and Shandong provinces feeds permanent magnet generator manufacturing, with neodymium-praseodymium alloy supply drawing from Chinese separation facilities. Blade composites hinge on carbon fiber imports from Japan and Germany, while power electronics assemblies source IGBT modules from Japanese and European semiconductor foundries. Single-source vulnerability concentrates in heavy-lift jack-up vessel availability across North Sea operators. Distribution runs through EPC contractors with captive offshore installation fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a capital equipment replacement wave as fixed-foundation offshore installations reach end-of-design-life, with lease auction timelines in German and UK waters driving procurement visibility.
For Market Incumbents: Insulate service revenue streams from equipment supply disintermediation by capturing predictive maintenance data through sensor fusion across dual rotor drivetrains. Deepen backward integration into permanent magnet recycling to offset neodymium price volatility exposure. Secure floating platform certification timelines with DNV and Bureau Veritas before capital commits to deep-water projects. For New Entrants and Emerging Players: The US Gulf Coast assembly corridor offers white-space expansion as IRA domestic content bonuses incentivize localization away from European supply chain chokepoints. Target hybrid renewable-plus-storage configurations where grid-forming inverter capabilities differentiate new market entrants. Pursue technology licensing partnerships with established drivetrain OEMs to bypass capital-intensive nacelle development cycles. For Investors and Strategic Acquirers: Engineering-intensive floating platform specialists with semi-submersible load case expertise represent the most defensible acquisition archetype as water depths exceed 60 meters. Monitor DNV certification issuance timelines for dual rotor floating installations as the inflection signal for capital deployment acceleration. Long-term viability rests on supply chain control over rare-earth processing and heavy-lift vessel access rather than pure manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Certification | DNV and Bureau Veritas unified standards unlock deep-water project finance in Scottish and Portuguese waters. |
| Permanent Magnet Supply Agreement | Long-term rare-earth offtake contracts with Inner Mongolia processors secure generator component availability. |
| Domestic Content Localization | Gulf Coast assembly facilities capture IRA production tax credit bonuses for US offshore lease areas. |
| Digital Twin Deployment | Predictive maintenance platforms extend mean time between failures and reduce offshore service vessel calls. |
| Hybrid Storage Integration | Battery co-location enables grid-forming inverters that stabilize output from variable North Sea wind regimes. |
Research Methodology
Operator-level perspectives from offshore wind farm developers, EPC contractors, utility planning officers, and heavy-lift vessel operators anchored the qualitative base. Primary interviews combined with secondary validation from EIA project databases, IEA renewable energy reports, FERC interconnection filings, and EU Green Deal implementation trackers. Bottom-up installation forecasts triangulated against top-down capacity targets across national renewable energy action plans.
Scenario-bracketing framed the analytical approach across the analysis window, modeling deployment trajectories by foundation type, water depth category, drivetrain topology, and regional grid infrastructure maturity. CAGRs derived from least-squares fitting of annual installation volumes against policy milestone timelines. Forecast inputs incorporated floating platform cost learning curves and rare-earth oxide price elasticity assumptions for permanent magnet generators.
Practitioners should monitor EU F-Gas Regulation compliance deadlines, neodymium oxide spot market volatility, and heavy-lift vessel orderbook expansion for early signals of forecast revision. Cross-checking against IEA offshore wind capacity announcements and national auction round outcomes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
Peru Wind Energy Market