
 Taiwan Wind Energy Market | 2026-2036
Taiwan Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Wind Energy Market Analytics
Offshore utilities procurement is pivoting toward larger turbine classes as Taiwan Power Company anchors domestic grid integration planning. Ørsted A/S leverages European offshore expertise to sustain project development momentum across the Taiwan Strait. Siemens Gamesa Renewable Energy SA dominates turbine supply negotiations while Vestas Wind Systems A/S competes through onshore repowering capabilities in western Taiwan counties.
Taiwan wind energy encompasses the conversion of kinetic wind resources into electrical power through aerodynamic rotor systems, with offshore installations now routinely exceeding 8 MW per unit and fixed-bottom substructures penetrating seabeds at 30-50 meter depths. The technology segment splits sharply between maturing onshore sites and rapidly scaling fixed-bottom offshore arrays where margin pools concentrate. Component demand clusters around blades and turbines as local content rules tighten, while gearbox and generator sourcing remains concentrated among established European and East Asian suppliers.
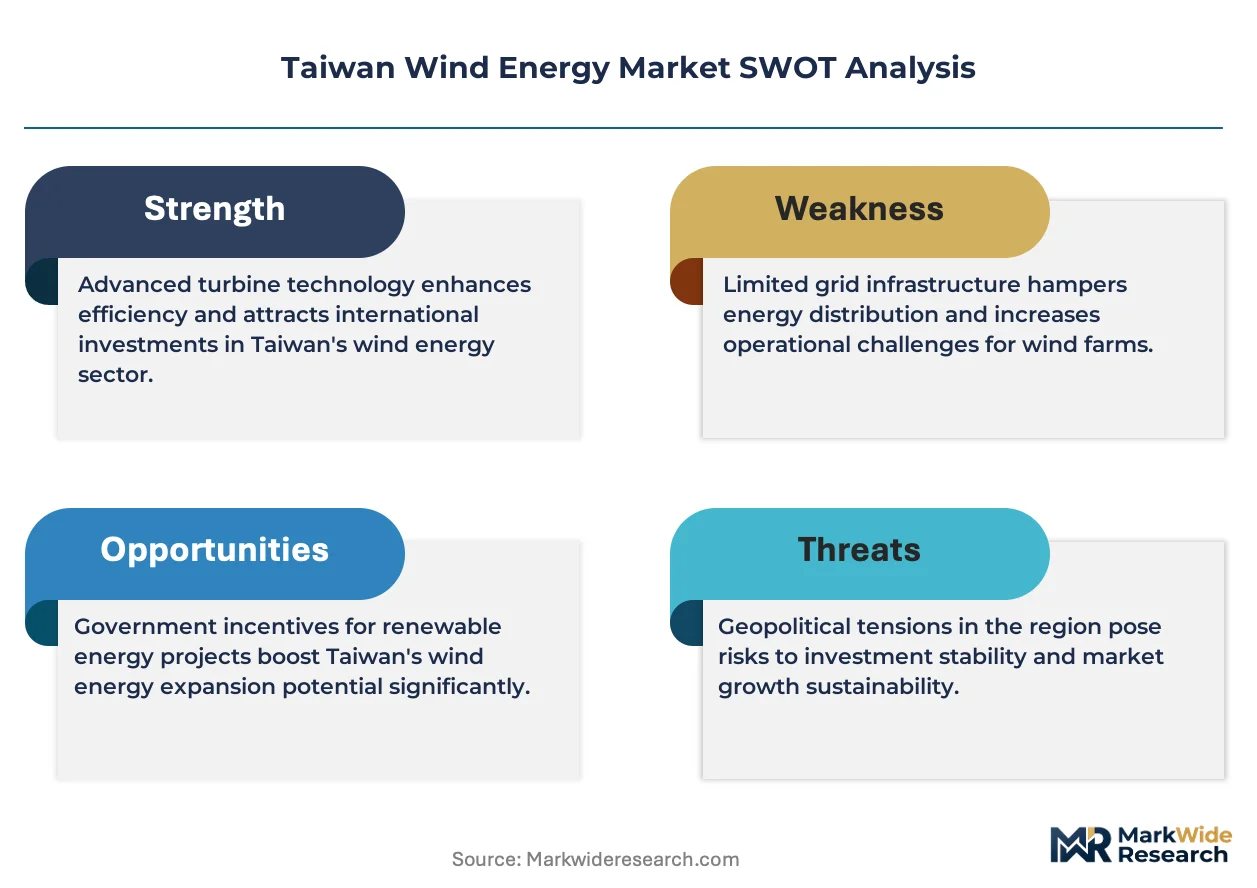
Taiwan's Bureau of Energy administers feed-in tariff mechanisms under the Renewable Energy Development Act, while the Ministry of Economic Affairs enforces local content requirements that reshape supplier qualification pathways. International Electrotechnical Commission standards and Taiwan's own CNS certifications govern grid interconnection and equipment safety protocols. Stakeholders must monitor permitting timelines for the Changhua and Yunlin offshore zones alongside evolving domestic supply chain qualification rules.
Market Dynamics
Taiwan's offshore wind buildout pivots on monopile fabrication capacity concentration in Taichung and Kaohsiung, where local content rules under the Renewable Energy Development Act amendments force supply chain reconfiguration. This geographic clustering creates procurement bottlenecks that reshape competitive positioning among developers.
Growth Catalysts
- Feed-in Tariff Mechanisms:Taiwan's Bureau of Energy administers guaranteed pricing structures that de-risk developer returns and accelerate project financing commitments.
- Fixed-Bottom Technology Maturation:Turbine classes exceeding 8 MW per unit now penetrate seabeds at 30-50 meter depths, unlocking previously inaccessible wind resources.
- Changhua Zone Permitting:Streamlined environmental review processes for this western coastal cluster concentrate near-term capacity additions.
Market Restraints
- Steel Input Volatility:Monopile fabrication depends on heavy plate steel subject to commodity price swings that compress fabricator margins.
- European Component Concentration:Gearbox and generator sourcing remains captive to established suppliers in Denmark and Germany, creating single-source exposure.
- Grid Interconnection Queues:Taiwan Power Company's transmission upgrade timelines lag behind generation capacity deployment schedules.
Strategic Opportunities
- Yunlin Offshore Expansion:The southern zone offers underdeveloped seabed leases with favorable wind shear profiles for next-generation arrays.
- Onshore Repowering:Western Taiwan counties host aging turbines eligible for blade and drivetrain replacement with higher-yield units.
- CNS Certification Alignment:Domestic equipment safety standards now parallel IEC protocols, reducing dual-testing burdens for local manufacturers.
Industry Challenges
- Marine Construction Specialist Shortage:Jack-up vessel operators and offshore installation crews command premium wages amid regional competition.
- Environmental Impact Assessment Delays:Coastal ecology reviews for seabed cable routing extend permitting timelines unpredictably.
- Legacy Grid Infrastructure:Existing substations require substantial reinforcement to absorb intermittent offshore generation at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Wind Energy Market |
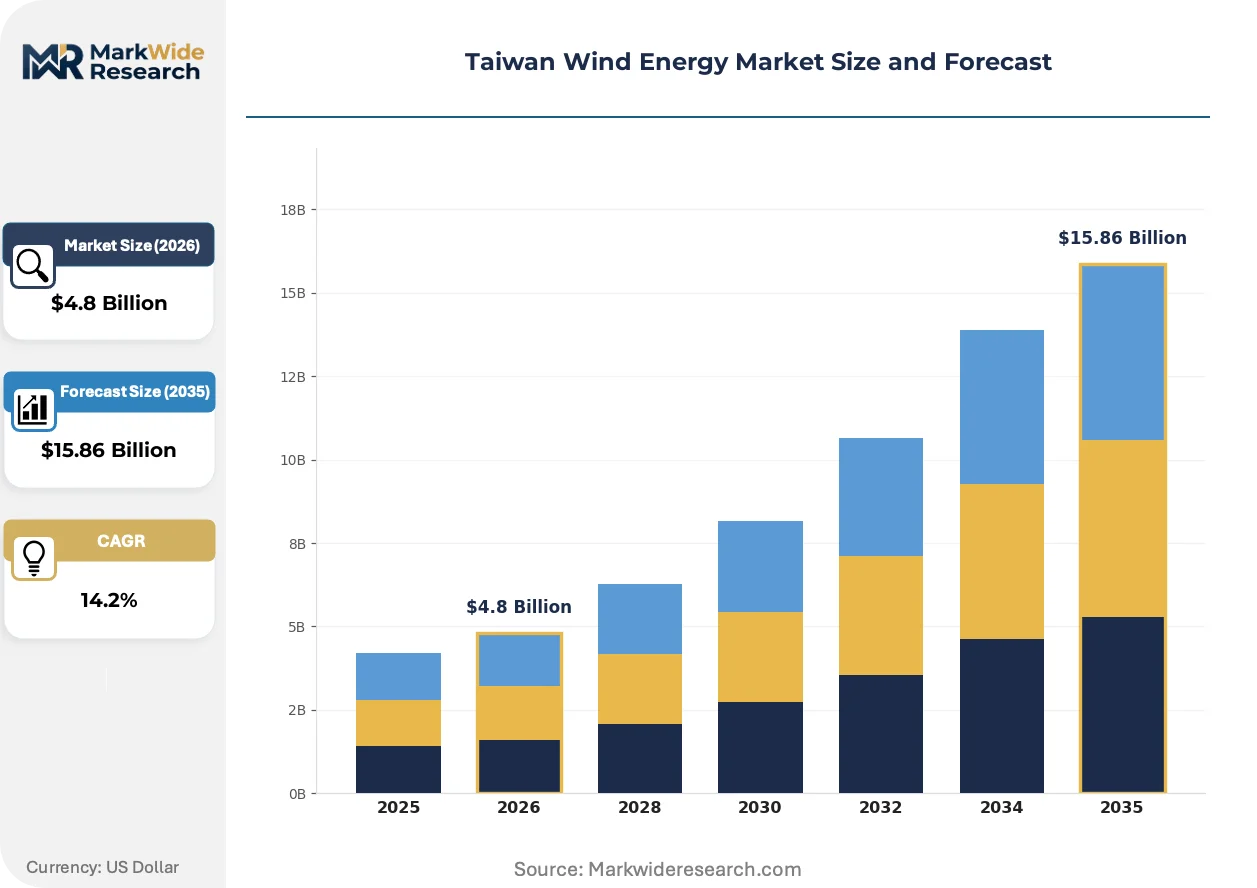
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Floating, Fixed-bottom Component: Turbines, Blades, Gearbox, Generator End User: Utilities, Independent Power Producers, Commercial, Residential Deployment: Greenfield, Brownfield, Retrofit, Repowering |
| Companies Covered | Taiwan Power Company, Northland Power Inc., Ørsted A/S, WPD Onshore GmbH & Co KG, Yushan Energy Co, Siemens Gamesa Renewable Energy SA, Copenhagen Infrastructure Partners K/S, GEV Wind Power, Vestas Wind Systems A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Wind Energy Market Evolving Landscape
Digitalization and scale economics are compressing project development cycles while regulatory pressure tightens equipment qualification pathways. These forces converge to reshape how developers structure procurement and how suppliers compete for qualification status.
Advanced blade inspection drones equipped with thermographic sensors are automating defect detection across turbine fleets. Ørsted A/S and domestic operators deploy these systems quarterly to identify delamination before structural failure. This predictive capability is automating maintenance scheduling and reducing unplanned downtime across Taiwan Strait installations.
Taiwan's Ministry of Economic Affairs has tightened local content requirements that now mandate 60% domestic value-add for offshore projects. Fabricators in Taichung Port must certify steel sourcing and welding labor through Bureau of Energy audits. Developers respond by joint-venturing with Taiwanese shipyards to secure qualification status.
Utility buyers now unbundle turbine supply contracts from installation and long-term service agreements. Taiwan Power Company and private offtakers negotiate component-only pricing, then tender marine logistics separately. This disaggregation is most pronounced in Changhua zone projects, where developers optimize capex allocation across specialized contractors.
Taiwan Wind Energy Market Segmentation
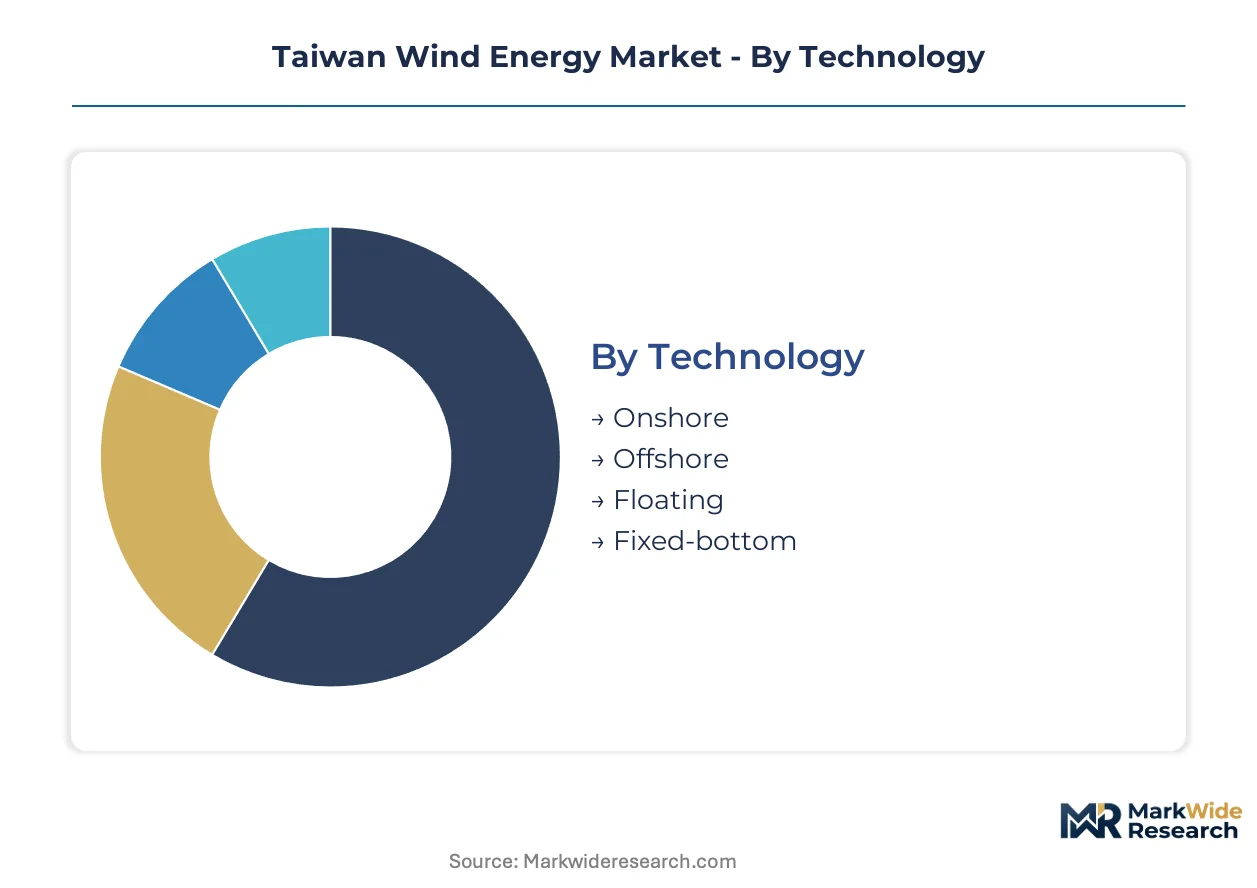
Taiwan's wind energy segmentation reflects distinct procurement logics across technology classes, component supply tiers, and deployment modes. Each category channels capital toward different margin pools and regulatory qualification pathways under the Renewable Energy Development Act.
Technology:
Standardization dominates fixed-bottom offshore arrays while floating platforms demand bespoke engineering for deeper Taiwan Strait waters.
- Onshore:Mature turbine classes populate western Taiwan counties where grid interconnection infrastructure exists. Changhua and Yunlin onshore clusters attract repowering investments as aging units face blade replacement cycles.
- Offshore:Fixed-bottom arrays exceeding 8 MW per unit now penetrate seabeds at 30-50 meter depths across Changhua and Yunlin zones. Taipower anchors procurement through guaranteed offtake structures that de-risk developer capital commitments.
- Floating:Prototype platforms target depths beyond 50 meters where fixed-bottom economics deteriorate. Demonstration projects near Penghu test mooring systems adapted from North Sea designs.
- Fixed-bottom:Monopile substructures fabricated in Taichung and Kaohsiung yards anchor near-term capacity additions. Bureau of Energy local content audits now mandate domestic steel sourcing and welding labor certification.
Most installed capacity flows through Fixed-bottom. Expansion is steepest in Offshore.
Component:
Margin concentration shifts downstream from commodity steel toward precision-manufactured rotating equipment and aerodynamic surfaces.
- Turbines:Nacelle assembly integrates drivetrain, generator, and control systems into single units exceeding 100 tonnes. Siemens Gamesa and Vestas compete for Taiwan Power Company procurement tenders with 8-15 MW platform offerings.
- Blades:Glass fiber and carbon fiber composite structures exceeding 80 meters in length dominate material specifications. Taichung Port fabricators invest in mold tooling to satisfy 60% domestic value-add requirements under Ministry of Economic Affairs rules.
- Gearbox:Planetary and parallel shaft configurations transmit rotor torque to generator input speeds. European suppliers in Denmark and Germany retain design leadership despite local content pressure.
- Generator:Permanent magnet synchronous and doubly-fed induction architectures compete for efficiency optimization. Winding and lamination sourcing remains concentrated among established East Asian and European manufacturers.
Turbines capture the largest share of project capex. Blades are climbing the fastest as local content rules reshape supplier qualification.
End User:
Procurement scale and offtake certainty separate utility buyers from fragmented commercial and residential segments.
- Utilities:Taiwan Power Company administers grid integration planning and transmission upgrade scheduling for utility-scale arrays. State-backed procurement provides revenue certainty that accelerates project financing.
- Independent Power Producers:Private developers bid into feed-in tariff auctions and negotiate corporate power purchase agreements. Ørsted A/S leverages European offshore expertise to sustain development momentum across Taiwan Strait lease blocks.
- Commercial:On-site generation targets manufacturing facilities and data centers seeking renewable energy certificates. Rooftop and small-scale installations cluster in industrial parks with favorable wind shear profiles.
- Residential:Distributed systems remain marginal due to land constraints and urban density in western Taiwan. Rural townships in mountainous eastern counties host limited small-turbine deployments.
Utilities dominate capacity procurement. Independent Power Producers are gaining share fastest as auction mechanisms expand.
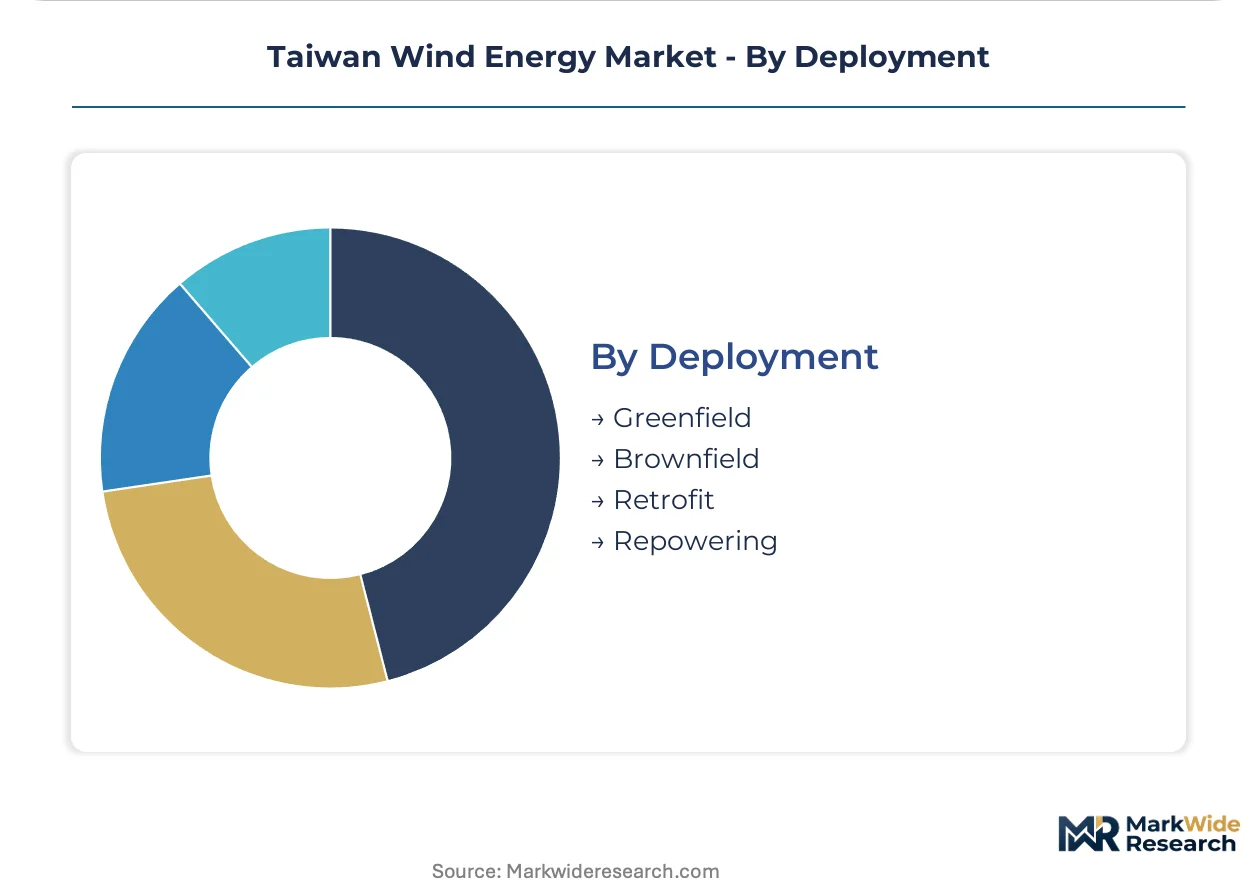
Deployment:
Capital efficiency favors brownfield expansion where permitting pathways are pre-cleared over greenfield development with uncertain timelines.
- Greenfield:New site development requires environmental impact assessment, seabed lease auction, and grid interconnection queue positioning. Changhua zone projects demonstrate streamlined approval for pre-identified lease blocks.
- Brownfield:Existing permitted sites allow capacity expansion through additional turbine rows or larger unit swaps. Yunlin offshore zone developers pursue serial site optimization to amortize fixed marine logistics costs.
- Retrofit:Control system and sensor upgrades extend operational life of mid-life turbines without structural replacement. Blade leading edge erosion repair and pitch bearing replacement dominate maintenance capital allocation.
- Repowering:Complete turbine replacement with higher-yield units transforms aging onshore sites in western Taiwan counties. Vestas competes for repowering contracts through tailored drivetrain and blade upgrade packages.
Brownfield deployment channels near-term investment. Greenfield is expanding most quickly as auction rounds release new seabed leases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redirecting fabrication investment toward jurisdictions with streamlined certification pathways. Taiwan's Bureau of Energy local content mandates have concentrated monopile production in Taichung and Kaohsiung, drawing European fabricators into joint ventures with domestic yards. This migration pattern reflects a broader regional dynamic where project economics hinge on qualification speed.
Changhua County
Changhua anchors Taiwan's near-term offshore deployment with pre-cleared lease blocks and streamlined environmental review processes. The zone hosts the densest concentration of 8 MW-plus fixed-bottom arrays penetrating seabeds at 30-50 meter depths. Taichung Port fabricators supply monopile substructures under Bureau of Energy audits that mandate domestic steel sourcing and welding labor certification.
Yunlin County
Yunlin's southern offshore zone offers underdeveloped seabed leases with favorable wind shear profiles for next-generation turbine classes. Developers pursue serial site optimization here to amortize fixed marine logistics costs across brownfield expansions. The Yunlin Industrial Park clusters blade mold tooling investments driven by 60% domestic value-add requirements under Ministry of Economic Affairs rules.
Kaohsiung City
Kaohsiung's deepwater port infrastructure supports heavy-lift vessel staging for jack-up operations across the Taiwan Strait. The city's fabrication yards compete with Taichung for monopile contracts under tightening local content thresholds. Grid interconnection upgrades from Taiwan Power Company lag behind generation deployment, creating transmission bottlenecks that reshape project sequencing.
Penghu Islands
Penghu hosts prototype floating platform demonstrations targeting depths beyond 50 meters where fixed-bottom economics deteriorate. Mooring systems adapted from North Sea designs undergo validation here under CNS certification protocols aligned with IEC standards. The island chain's isolation necessitates dedicated marine logistics chains that inflate development costs relative to western Taiwan clusters.
Western Taiwan Onshore Belt
Changhua and Yunlin onshore counties attract repowering investments as aging turbines face blade replacement cycles. Vestas competes for retrofit contracts through tailored drivetrain and blade upgrade packages targeting mid-life units. Distributed systems remain marginal due to land constraints, though rural townships in mountainous eastern counties host limited small-turbine deployments.
Taiwan Wind Energy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with turbine OEMs capturing concentrated capex allocation while fabrication yards compete on qualification speed. The market structures around three tiers: European developers leveraging offshore expertise, domestic utilities anchoring procurement scale, and component specialists navigating local content compliance. Strategic moves center on joint ventures for qualification status and disaggregated contracting that unbundles supply from installation.
Among European developers active in Taiwan Strait lease blocks, Ørsted A/S and Copenhagen Infrastructure Partners K/S occupy positions that exemplify the offshore expertise archetype. Within the turbine supply tier, Siemens Gamesa Renewable Energy SA and Vestas Wind Systems A/S represent contrasting approaches to the market. Domestic utility Taiwan Power Company anchors procurement through state-backed offtake structures that de-risk developer financing.
| Leading Market Players |
|---|
| Taiwan Power Company |
| Northland Power Inc. |
| Ørsted A/S |
| WPD Onshore GmbH & Co KG |
| Yushan Energy Co |
| Siemens Gamesa Renewable Energy SA |
| Copenhagen Infrastructure Partners K/S |
| GEV Wind Power |
| Vestas Wind Systems A/S |
| Others |
Value Network & Pricing Analysis
Fixed-bottom turbine scaling above 8 MW per unit is compressing capex per megawatt while concentrating procurement leverage among developers with multi-gigawatt pipelines. Taiwan's Bureau of Energy feed-in tariffs stabilize revenue streams, but monopile fabrication bottlenecks in Taichung and Kaohsiung yards are reshaping how suppliers compete on qualification speed versus pure price.
Pricing Analysis
Direct-to-utility contracting eliminates distributor margins that inflate equipment costs in fragmented markets. Three-tier pricing structure across premium, standard, and economy levels separates Siemens Gamesa and Vestas turbine offerings from regional Asian suppliers, with price differentiation driven by local content certification status and bundled long-term service agreements. Pricing pressure stems from steel input volatility in heavy plate markets, with fabricators absorbing margin compression to maintain Bureau of Energy qualification. Independent power producers exhibit highest price sensitivity due to project financing constraints, while Taiwan Power Company procurement tolerates premium pricing for grid integration certainty.
Supply Chain Analysis
Marine freight costs from European component hubs to Taichung Port add 8-12% to landed nacelle expenses, incentivizing domestic blade mold tooling investments. Supply concentrates in Denmark and Germany for precision gearbox and generator assemblies, while steel plate feeds from South Korea and Japan anchor monopile fabrication. Raw material dependencies on heavy plate steel, rare-earth permanent magnets, and glass fiber composites create single-source exposure in generator winding supply. Tariff exposure runs through potential trade friction in steel inputs. Distribution runs through Taiwan Power Company central procurement for utility-scale arrays, with private offtakers negotiating directly through corporate power purchase agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan wind energy has entered a late-cycle quality phase where turbine reliability and local content compliance outweigh pure capex minimization. Developer procurement is shifting toward 15 MW-plus platform specifications that demand proven offshore track records.
For Market Incumbents: Cement qualification status through joint ventures with Taichung and Kaohsiung fabrication yards before local content thresholds tighten further. Expand nacelle assembly footprints in Taiwan to capture margin pools currently flowing to European logistics channels. Defensive positioning requires pre-emptive certification investment against emerging Chinese turbine OEMs bidding on Yunlin zone leases.
For New Entrants and Emerging Players: Launch via marine construction specialist partnerships rather than capital-intensive turbine manufacturing, targeting jack-up vessel charter and offshore installation niches where European operators command scarcity premiums. The most penetrable white-space sits in predictive maintenance software for existing Changhua zone arrays, with drone-based blade inspection as the go-to-market wedge.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale independent power producers because Taiwan Power Company offtake structures provide revenue visibility that supports leveraged acquisition structures. Five-to-ten year viability hinges on Bureau of Energy auction schedule continuity. Watch permitting timeline compression for Penghu floating demonstrations as the inflection signal for next-technology-cycle deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Monopile Fabrication Joint Venture | Secures Bureau of Energy local content qualification for Changhua zone developers. |
| Feed-in Tariff Auction Participation | De-risks project financing through Taiwan Power Company guaranteed offtake structures. |
| Blade Mold Tooling Investment | Satisfies 60% domestic value-add rules under Ministry of Economic Affairs enforcement. |
| Jack-up Vessel Charter Agreement | Locks marine construction capacity amid regional competition for offshore installation crews. |
| Floating Platform Demonstration | Validates mooring systems for Penghu depths beyond fixed-bottom economic limits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, independent power producer project developers, EPC contractors, and Bureau of Energy regulatory leads with secondary validation from FERC-style filings, IEA offshore wind reports, and project development databases. Bottom-up capacity addition modeling and top-down macroeconomic scenario triangulation anchored market size estimates.
Comparable-period anchoring linked forward projections to historical installation trajectories across the analysis window, with segmentation modeling across technology class, component tier, end-user category, and deployment mode. CAGRs derived from unit economics analysis incorporating turbine scaling curves, steel price indices, and local content compliance cost structures. Forecast inputs included seabed lease auction schedules and Taiwan Power Company transmission upgrade timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under permitting delays or marine construction specialist wage spirals. Forecasts reflect documented assumptions about Bureau of Energy local content enforcement continuity and European component supplier pricing discipline. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Asia-Pacific Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Vertical Axis Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market