
 Wind Turbine Tower Market | 2026-2036
Wind Turbine Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Tower Market Outlook
Lifecycle service contracts encompassing predictive maintenance and digital monitoring is rebalancing how tower suppliers monetize hardware deployments. CS Wind Corporation leverages its Korean and Vietnamese manufacturing footprint to anchor supply for Asian offshore pipelines. Arcosa Wind Towers Inc. competes through domestic US fabrication capacity, while EEW Group dominates European offshore tower production with purpose-built facilities in Germany and Portugal.
A wind turbine tower is a steel or concrete structural column that supports the nacelle and rotor assembly, typically manufactured in tapered tubular sections through automated submerged-arc welding and rolled-plate forming, with hub heights now exceeding 150 meters for onshore units and 130 meters for offshore installations to access higher wind speeds. Steel towers retain the largest share of installed capacity due to established supply chains and transportability, though hybrid towers combining steel and concrete base sections are gaining share in markets where hub height constraints and local content rules intersect. Offshore fixed-bottom technology commands premium fabrication standards, while floating platform towers represent an emerging segment where specialized engineering creates distinct margin pools.
The EU Green Deal and F-Gas Regulation shape European tower demand by mandating circular material use and low-carbon steel procurement, while China's MIIT enforces GB standards on structural welding and fatigue resistance for domestic installations. The US FAA coordinates lighting and marking requirements that affect tower design above certain heights, and OSHA mandates climb-assist and fall-protection integration during fabrication. Stakeholders must weigh port infrastructure commitments against evolving nacelle mass trajectories when siting future tower capacity.
Market Dynamics
Offshore wind developers are forcing tower fabricators to retool for 15+ MW nacelle loads and 150-meter hub heights, compressing lead times while EU Green Deal carbon-accounting rules rewrite steel procurement specifications.
Growth Catalysts
- EU Green Deal circular material mandates:Low-carbon steel procurement requirements are redirecting tower fabrication toward electric-arc furnace supply chains and certified recycled content quotas.
- Floating offshore wind platforms:Deep-water installations beyond fixed-bottom economic limits are creating specialized engineering demand for tension-leg and semi-submersible tower configurations.
- German-Dutch-Danish auction corridors:Clustered offshore lease rounds are concentrating fabrication capacity along North Sea port zones with heavy-lift vessel access.
Market Restraints
- Steel plate price volatility:Hot-rolled coil input costs swing with energy-intensive smelting economics, squeezing tower margins on fixed-price EPC contracts.
- Asian supply concentration:Korean and Vietnamese rolling mills dominate thick-plate production for monopile transition pieces, creating single-source vulnerability.
- Transport diameter limits:Road and rail clearances cap onshore tower base sections at 4.5 meters, constraining hub height scaling without field-assembly hybrid designs.
Strategic Opportunities
- US Inflation Reduction Act domestic content bonuses:Section 45X manufacturing credits are incentivizing greenfield tower fabrication investment in Gulf Coast and Great Lakes port zones.
- Concrete-steel hybrid tower bases:In-situ concrete lower sections bypass transport constraints while meeting local content rules in Brazil and India.
- Digital twin predictive maintenance:Sensor-integrated towers enabling fatigue monitoring contracts are opening recurring revenue streams beyond hardware sales.
Industry Challenges
- Welding inspector certification bottlenecks:EN ISO 9606 and AWS D1.1 qualified welder shortages are extending fabrication QA timelines at European yards.
- Floating platform mooring integration:Tower-to-platform load transfer engineering lacks standardized interfaces, forcing project-specific design cycles.
- Port infrastructure capex coordination:Heavy-lift quayside investments require decade-long offtake commitments that predate final investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Tower Market |
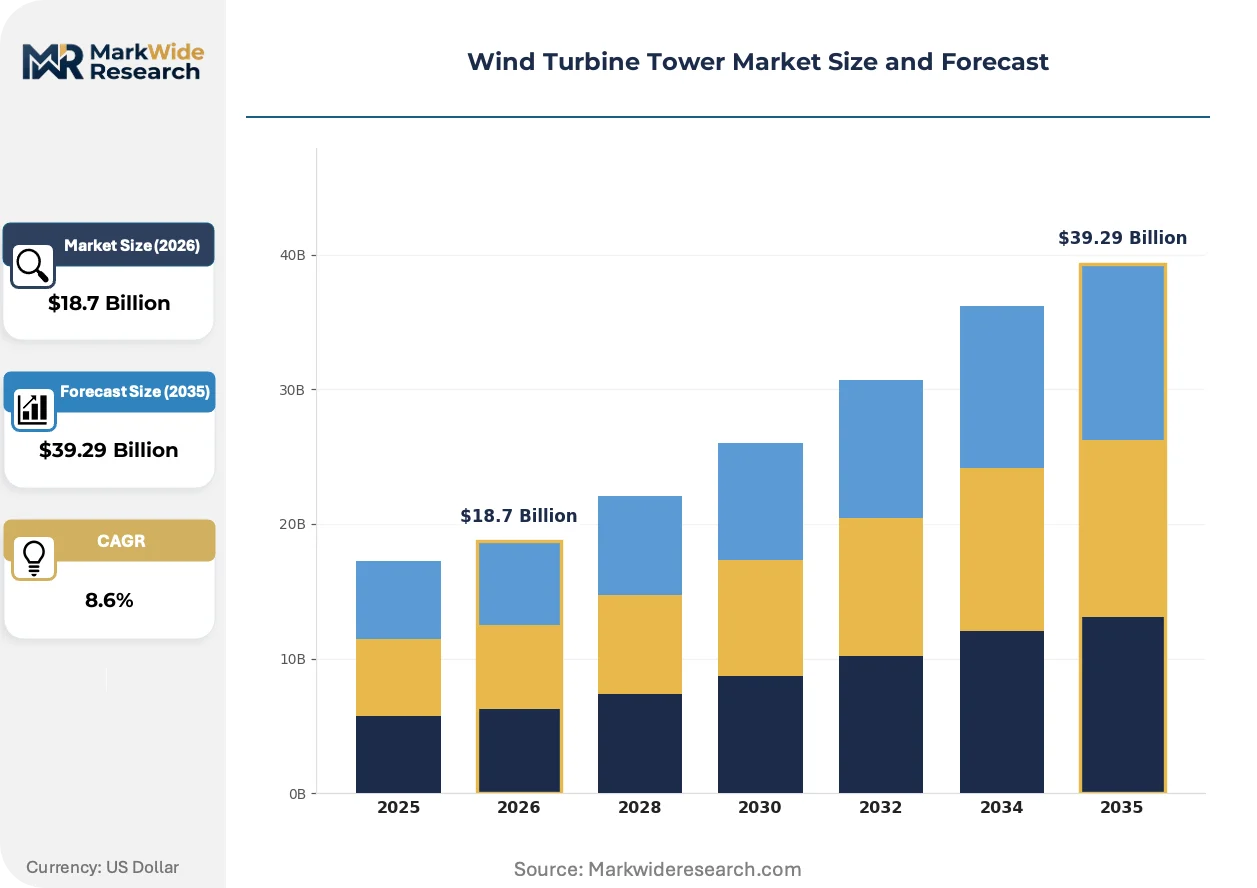
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Towers, Concrete Towers, Hybrid Towers, Tower Sections Technology: Onshore, Offshore, Floating, Fixed-Bottom End User: Utilities, Independent Power Producers, Government Agencies, Corporations Installation Type: New Installation, Retrofit, Upgrades, Maintenance |
| Companies Covered | CS Wind Corporation, Arcosa Wind Towers Inc., Trinity Structural Towers, Marmen, Broadwind Energy Inc., Valmont Industries Inc., EEW Group, GRI Renewable Industries, Modvion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Tower Market Strategic Shifts
Steel-concrete hybrid tower architectures and automated fabrication robotics are compressing unit economics while regulatory carbon-accounting rules reshape material sourcing.
Automated submerged-arc welding with real-time ultrasonic testing is expanding into offshore monopile production lines. CS Wind Corporation and EEW Group have deployed robotic seam-tracking systems at Korean and German facilities, cutting defect rates and enabling single-shift completion of 80-meter sections. This automation is expanding into onshore tower plants as labor costs rise and quality consistency becomes non-negotiable for 25-year design-life certifications.
EU F-Gas Regulation amendments and the Carbon Border Adjustment Mechanism are tightening embodied-carbon disclosure requirements for imported steel. Tower fabricators must now document Scope 3 emissions from ore extraction through rolling, with non-compliant imports facing tariff penalties from 2026. Offshore projects in German and Danish waters are responding by specifying electric-arc furnace plate and demanding mill-specific EPDs.
Lifecycle service contracting is displacing transactional hardware sales among major developers. Ørsted and Equinor now bundle tower structural health monitoring with foundation installation, locking suppliers into 15-year performance guarantees. This bundling is most visible in North Sea markets where OPEX optimization outweighs upfront CAPEX minimization in project finance models.
Wind Turbine Tower Market Segmentation
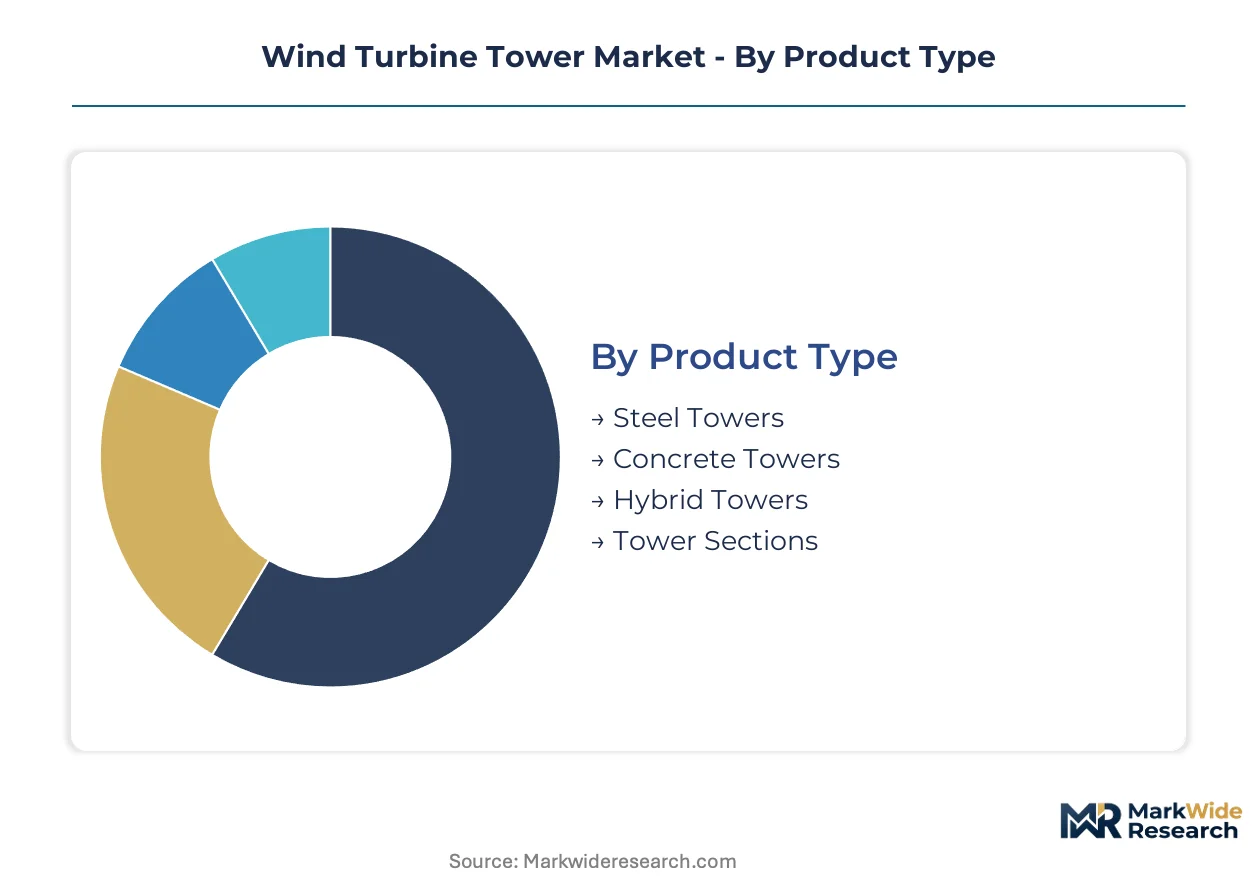
Tower segmentation determines fabrication strategy, transport logistics, and margin structure across the wind value chain. Product material choices and installation environment dictate capital intensity, while end-user procurement patterns shape contract duration and service bundling requirements.
Product Type:
Steel towers operate as standalone manufactured systems with established supply chains, while hybrid and concrete variants embed localized construction processes into project delivery.
- Steel Towers:Rolled-plate tubular sections joined through submerged-arc welding dominate installed capacity due to factory-controlled quality and modular transport. Demand concentrates in North Sea offshore corridors where EEW Group and CS Wind Corporation anchor fabrication near heavy-lift ports, though EU Green Deal carbon-accounting rules are redirecting procurement toward electric-arc furnace supply chains.
- Hybrid Towers:Steel upper sections atop in-situ concrete bases bypass road transport diameter constraints while satisfying local content mandates in Brazil and India. German and Danish auction winners increasingly specify hybrid configurations for 150-meter hub heights where pure steel designs face logistics barriers.
- Concrete Towers:Precast or cast-in-place reinforced concrete segments eliminate steel price volatility exposure but require on-site curing infrastructure and specialized formwork.
- Tower Sections:Flanged or bolted sub-assemblies enable field-assembly of hub heights exceeding transport limits, common in US Great Plains and Australian interior projects.
Steel towers lead volumes today; hybrid configurations are gaining share fastest as hub height requirements outpace road clearance limits.
Technology:
Technology segmentation maps to water depth economics, with fixed-bottom systems saturating shallow developments and floating platforms unlocking deep-water frontiers.
- Onshore:Land-based installations account for the majority of annual tower deployments, with hub heights climbing toward 150 meters to access higher wind speeds. US IRA domestic content bonuses and Indian PLI schemes are accelerating greenfield manufacturing investment in Texas and Gujarat.
- Offshore:Fixed-bottom monopile and jacket structures command premium fabrication standards for 15+ MW nacelle loads, concentrating demand along German, Dutch, and Danish North Sea lease zones.
- Floating:Semi-submersible and tension-leg platform towers enable installations beyond 60-meter water depths, creating specialized engineering demand in Portuguese and Norwegian demonstration projects.
- Fixed-Bottom:Monopile and jacket foundation-tower interfaces dominate shallow-water economics, with fabrication yards in Germany and Portugal purpose-built for 80-meter section production.
Fixed-bottom technology captures current offshore volumes; floating platforms show steepest expansion trajectory as deep-water sites enter development pipelines.
End User:
Procurement patterns diverge between integrated utilities with captive engineering capabilities and independent developers relying on turnkey EPC contracts.
- Utilities:Vertically integrated power companies bundle tower procurement with long-term service contracts, favoring suppliers with predictive maintenance platforms. Ørsted and Equinor exemplify this model in North Sea markets.
- Independent Power Producers:Project finance-dependent developers prioritize upfront CAPEX minimization, accepting shorter warranty terms and transactional hardware relationships.
- Government Agencies:State-owned renewable energy corporations in China and India drive volume through centralized procurement with domestic content requirements.
- Corporations:Corporate power purchase agreement offtakers indirectly influence tower specifications through sustainability criteria and carbon disclosure demands.
Utilities dominate procurement value today; corporate offtakers are expanding fastest as virtual PPAs reshape project sponsorship.
Installation Type:
Revenue streams bifurcate between capital-intensive new build activity and recurring maintenance services with divergent margin profiles.
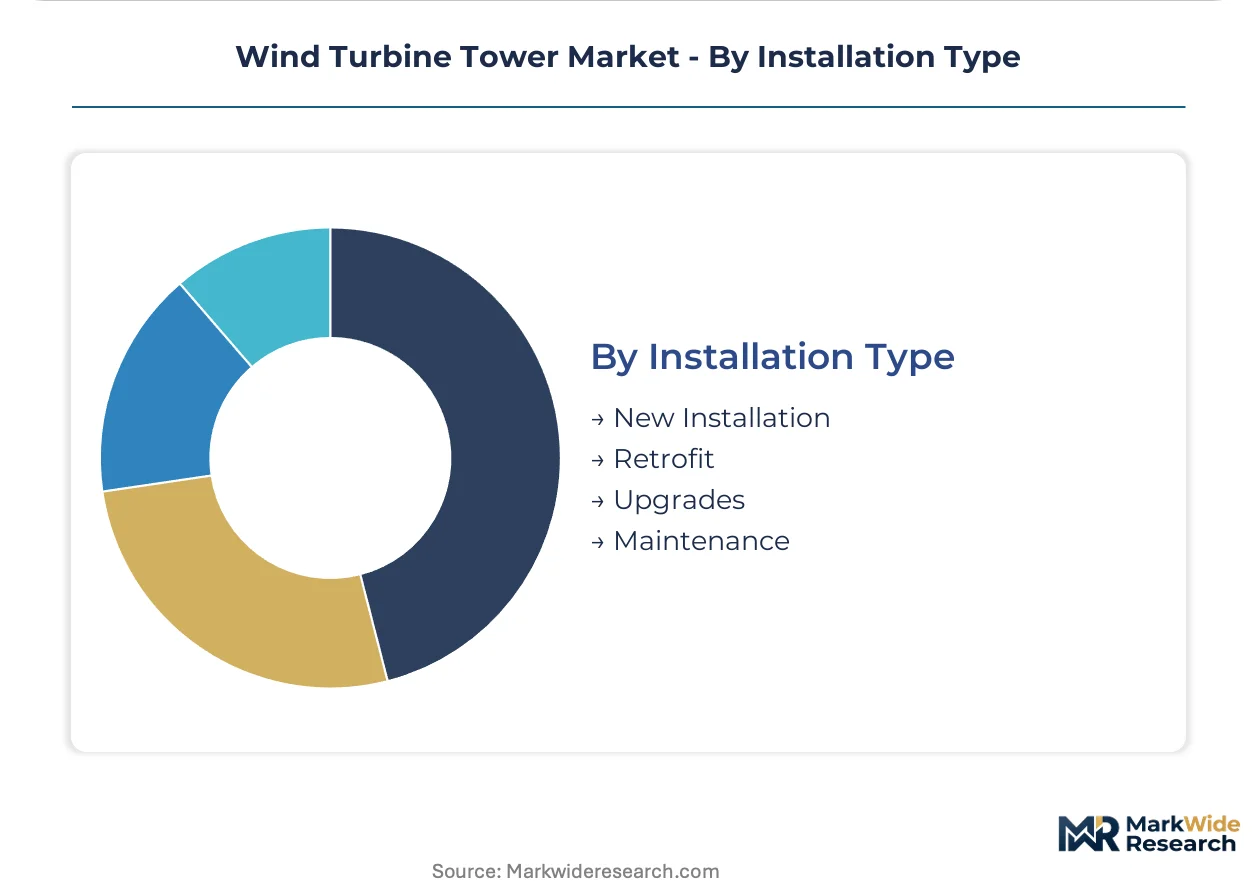
- New Installation:Greenfield tower supply captures the majority of manufacturer revenue, with 25-year design-life certifications requiring EN ISO 9606 welding compliance and full fatigue analysis.
- Retrofit:Hub height extension and nacelle upgrade projects demand tower load reassessment and structural reinforcement, common in German and Spanish aging fleets.
- Upgrades:Control system and sensor integration for digital twin deployment represents emerging hardware-software bundling opportunity.
- Maintenance:Climb-assist system refurbishment and corrosion protection cycles generate recurring revenue, with OSHA and EU machinery directives governing service protocols.
New installation drives absolute revenue today; maintenance contracts are expanding most quickly as installed base ages and service bundling proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China approach tower procurement through fundamentally different regulatory lenses, with the former prioritizing embodied-carbon accountability and the latter emphasizing domestic manufacturing scale. These divergent frameworks are reshaping where fabrication capacity locates and which steel supply chains gain preferential access.
Germany
Offshore auction winners in the North Sea and Baltic are specifying 150-meter hub heights for 15+ MW turbines, forcing fabricators toward electric-arc furnace steel to meet EU Green Deal carbon thresholds. The F-Gas Regulation and Carbon Border Adjustment Mechanism require mill-specific environmental product declarations from 2026. Cuxhaven and Rostock port zones concentrate heavy-lift fabrication, with EEW Group anchoring purpose-built monopile production.
China
Provincial wind bases in Inner Mongolia and Gansu are driving annual tower deployments exceeding 50 GW, with MIIT enforcing GB standards on structural welding and fatigue resistance. The dual carbon goals are tightening steel sector emissions caps, redirecting procurement toward integrated mills with captive renewable power. Yangtze River Delta fabricators dominate export supply for Southeast Asian offshore pipelines.
United States
IRA Section 45X manufacturing credits are accelerating greenfield investment in Gulf Coast and Great Lakes port zones, with Texas and Louisiana emerging as fabrication hubs for domestic content-compliant towers. FAA lighting and marking requirements shape design above 200 feet, while OSHA mandates climb-assist integration during fabrication. The Great Lakes corridor offers heavy-lift waterway access without Jones Act vessel constraints.
Vietnam
CS Wind Corporation's manufacturing footprint anchors supply for Asian offshore markets, with thick-plate rolling capacity concentrated near deepwater ports serving regional developers. The government's renewable energy development strategy is licensing coastal zones for fabrication yards, though welding inspector certification bottlenecks extend QA timelines. Ba Ria-Vung Tau province is emerging as the primary cluster for export-oriented tower production.
Denmark
Ørsted's bundled procurement model is locking suppliers into 15-year structural health monitoring contracts, shifting revenue from hardware sales to lifecycle services. The Danish Energy Agency's auction design prioritizes OPEX optimization over upfront CAPEX minimization in project finance. Esbjerg port infrastructure is expanding quayside heavy-lift capacity to accommodate 80-meter section handling.
Wind Turbine Tower Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated offshore fabricators commanding premium positioning against commoditized onshore suppliers. The vendor base concentrates around three strategic archetypes: Korean-Vietnamese rolling mill integrators, European purpose-built offshore specialists, and North American domestic-content-focused fabricators. Capacity expansion and backward integration into steel plate supply dominate competitive moves, with electric-arc furnace partnerships emerging as a differentiation vector under EU carbon-accounting rules.
Among Korean and Vietnamese fabricators, CS Wind Corporation exemplifies the integrated offshore archetype through its multi-country manufacturing footprint. European specialists anchor premium-tier positioning, with EEW Group representing purpose-built offshore production capabilities. North American fabricators occupy a distinct segment, with Arcosa Wind Towers Inc. exemplifying domestic-content-focused supply for IRA-incentivized projects.
| Leading Market Players |
|---|
| CS Wind Corporation |
| Arcosa Wind Towers Inc. |
| Trinity Structural Towers |
| Marmen |
| Broadwind Energy Inc. |
| Valmont Industries Inc. |
| EEW Group |
| GRI Renewable Industries |
| Modvion |
| Others |
Value Chain & Pricing Dynamics
Automated submerged-arc welding with robotic seam-tracking systems is compressing unit economics while concentrating fabrication capacity among suppliers with capital-intensive production lines. This technological transition simultaneously lowers per-ton processing costs and raises barriers to entry, reshaping how tower suppliers compete on price across European and Asian markets.
Pricing Analysis
Capacity additions in Vietnam and the US Gulf Coast are reshaping price floors for standard steel towers, while premium offshore monopile segments retain pricing power through EN ISO 9606 welding certification requirements. Pricing stratifies across certified electric-arc furnace supply, conventional blast-furnace plate, and hybrid concrete-steel configurations. Cost compression in onshore segments is intensifying because IRA domestic content bonuses are attracting new fabricators into Texas and Louisiana. Independent power producers exhibit highest price sensitivity, while integrated utilities bundling lifecycle services accept premium positioning.
Supply Chain Analysis
US IRA Section 45X credits and Indian PLI schemes are redirecting procurement toward domestic rolling mills, fragmenting what had been a Korea-Vietnam-China supply concentration. Thick-plate production draws from integrated steel mills in China, electric-arc furnace operators in Germany, and Korean export-oriented facilities. Single-source vulnerability persists in 80-meter monopile segments where only EEW Group and CS Wind Corporation operate purpose-built heavy-lift yards. Distribution runs through port-centric fabrication clusters with quayside heavy-lift capacity, not through traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wind turbine tower market functions as a stable compounder anchored by irreversible offshore wind buildouts along the North Sea corridor. EU Green Deal carbon-accounting rules and US domestic content mandates create durable demand visibility for compliant suppliers.
For Market Incumbents: Deepen electric-arc furnace partnerships to secure low-carbon steel supply chains before CBAM tariff penalties activate. Add in-house production of tower flanges and transition pieces to reduce exposure to Asian forging concentration. Defend against modular wooden tower entrants like Modvion by accelerating hybrid concrete-steel certification for 150-meter hub heights.
For New Entrants and Emerging Players: Digital twin predictive maintenance platforms offer the lowest competitive density among service bundling opportunities. Target US Great Lakes port zones where Jones Act exemptions reduce vessel cost disadvantages against Gulf Coast incumbents. Pursue corporate PPA offtakers with sustainability disclosure requirements as anchor customers for certified low-carbon tower supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among domestic-content-focused fabricators lacking offshore certification depth. The five-to-ten year viability window favors suppliers with captive port infrastructure and electric-arc furnace steel partnerships. Watch German-Dutch-Danish auction clearing prices as the signal for whether OPEX-optimized bundled procurement displaces transactional hardware margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Arc Furnace Steel Partnership | Secures CBAM-compliant supply chains for EU offshore projects requiring mill-specific EPDs. |
| Port Infrastructure Expansion | Enables handling of 80-meter monopile sections at Cuxhaven, Rostock, and Esbjerg quaysides. |
| Digital Twin Service Bundling | Captures 15-year structural health monitoring contracts from Ørsted and Equinor procurement models. |
| Hybrid Tower Certification | Unlocks 150-meter hub heights in markets with 4.5-meter road clearance constraints. |
| Domestic Content Compliance Investment | Qualifies for IRA Section 45X credits in Texas and Great Lakes manufacturing zones. |
Study Parameters
Coverage spans Germany, China, the United States, Vietnam, and Denmark, with primary inputs from each market collected through structured interviews with offshore project developers, EPC contractors, steel procurement directors, port infrastructure planners, and welding certification auditors. Secondary validation draws from EU auction results databases, FERC interconnection queues, MIIT production statistics, and customs trade records for thick-plate imports. Bottom-up project pipeline aggregation and top-down steel demand modeling were triangulated against disclosed fabrication capacity expansions.
Rate-of-change decomposition separates volume growth from value-per-unit trajectories across the projection horizon. Segmentation dimensions include material type, installation environment, end-user procurement pattern, and hub height tier. CAGRs were derived from capacity-weighted project commissioning schedules and steel input cost sensitivities. Forecast inputs incorporate nacelle mass trajectories from turbine OEM roadmaps and evolving EU carbon-border tariff schedules.
The model assumes a particular technology adoption path; alternative pathways for floating platform towers would alter the outlook if tension-leg designs displace semi-submersible configurations. Forecasts reflect assumptions about auction clearing prices, steel sector emissions caps, and welding inspector certification throughput. A small set of triggers warrants ongoing watch: German-Dutch-Danish auction design changes, US IRA credit modification proposals, and Korean-Vietnamese rolling mill consolidation activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market