
 Onshore Wind Turbine (above 2.5MW) Market | 2026-2036
Onshore Wind Turbine (above 2.5MW) Market Size, Share, and Industry Trends Forecast 2026-2036
Onshore Wind Turbine (above 2.5MW) Market Insights
Software-defined power curve optimization is shifting how turbine output gets contracted and monetized across fleet portfolios. Vestas leverages its predictive analytics platform to extend service revenue beyond hardware sales. Siemens Gamesa anchors its competitiveness in high-wind-site blade designs that sustain output efficiency across variable terrain. Goldwind dominates the gearless direct-drive segment through in-house production of permanent-magnet generators.
Onshore wind turbines above 2.5MW are horizontal-axis machines with rotor diameters typically spanning 120-170 meters and hub heights exceeding 130 meters, designed to capture low-speed wind resources at utility scale for grid-connected electricity generation. The gearless direct-drive technology segment leads installed capacity due to reduced mechanical complexity and lower maintenance burden in remote installations. Variable-speed turbine configurations represent the fastest-growing technology category as grid operators impose stricter frequency response requirements. The utility end-user segment occupies the dominant share of order intake, though corporate power purchase agreements are gaining traction among technology and manufacturing buyers seeking renewable energy certificates.
China's National Energy Administration and Ministry of Ecology and Environment enforce grid integration standards and carbon intensity targets that shape turbine sizing and siting decisions. The EU Green Deal and F-Gas Regulation restrict fluorinated gas use in switchgear components, forcing redesigns of electrical systems within nacelles. Stakeholders must monitor evolving grid code requirements in multiple jurisdictions as interconnection standards become the primary gate for project commissioning timelines.
Market Dynamics
Grid parity mandates and dual carbon targets in China are compressing turbine procurement cycles while forcing manufacturers to absorb cost compression through direct-drive technology standardization and in-house permanent-magnet generator production.
Growth Catalysts
- China's dual carbon goals:The National Energy Administration enforces carbon intensity targets that accelerate utility-scale deployment across Inner Mongolia and Xinjiang provinces.
- Corporate power purchase agreements:Technology and manufacturing buyers seek renewable energy certificates, expanding order intake beyond traditional utility offtakers.
- Variable-speed configurations:Grid operators impose stricter frequency response requirements, driving fastest-growing technology category adoption.
Market Restraints
- Rare earth supply concentration:Permanent-magnet generator production depends on concentrated rare earth processing capacity, creating input cost volatility and geopolitical exposure.
- F-Gas Regulation compliance:The EU Green Deal restricts fluorinated gas use in nacelle switchgear, forcing electrical system redesigns that extend development timelines.
- Interconnection standard fragmentation:Evolving grid code requirements across multiple jurisdictions create commissioning gate uncertainty and project delay risk.
Strategic Opportunities
- Software-defined power curves:Predictive analytics platforms enable output contracting and monetization beyond hardware sales, extending service revenue streams.
- Low-wind site capture:Rotor diameter expansion to 170 meters unlocks previously uneconomical wind resources in complex terrain regions.
- Corporate renewable procurement:Manufacturing and data center verticals accelerate direct contracting for grid-connected generation capacity.
Industry Challenges
- Grid integration certification:Multiple jurisdiction interconnection standards create timeline uncertainty and require parallel compliance pathways.
- Blade logistics complexity:170-meter rotor components exceed standard transport infrastructure capacity, demanding specialized handling and route planning.
- Frequency response engineering:Variable-speed turbine configurations require advanced power electronics expertise scarce in established technician pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onshore Wind Turbine (above 2.5MW) Market |
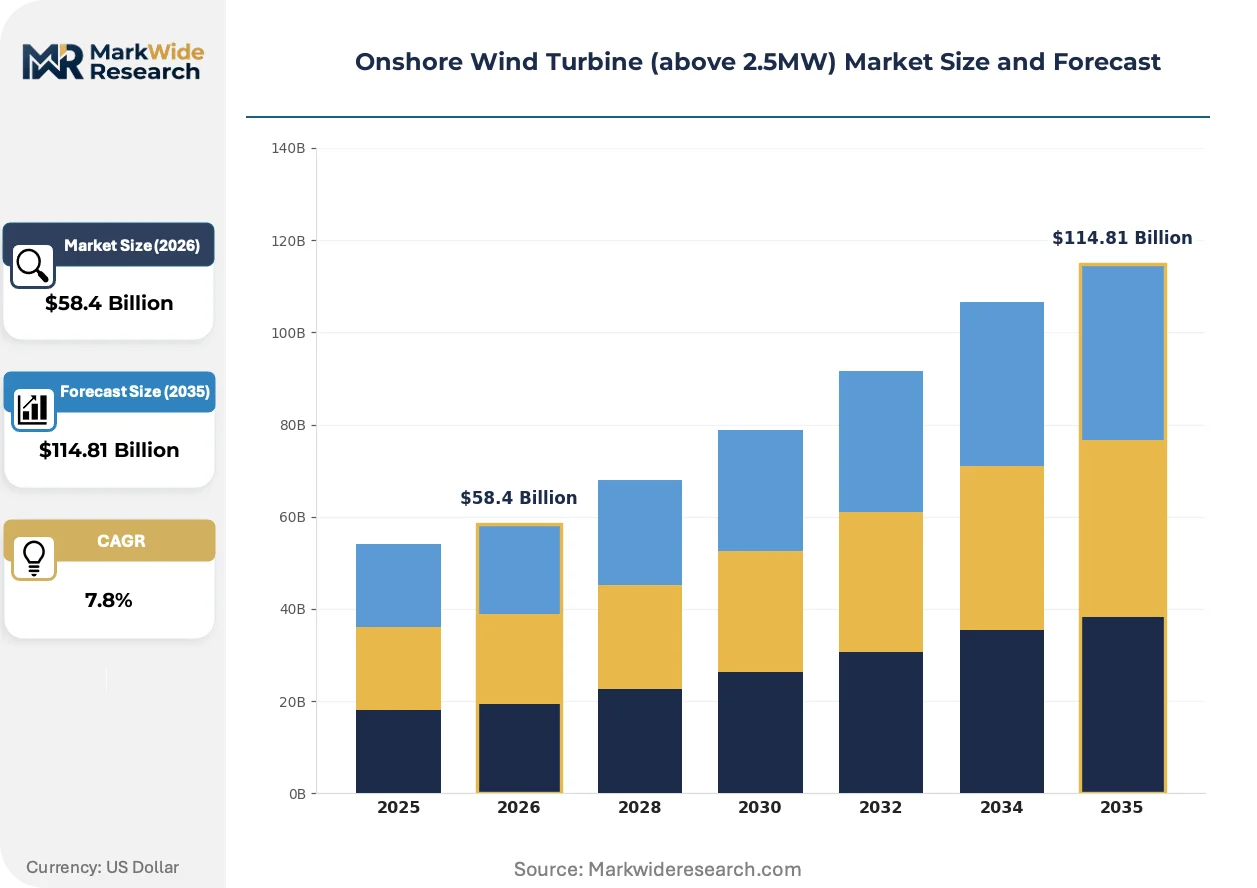
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $114.81 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Hybrid, Offshore Technology: Gearless, Geared, Direct Drive, Variable Speed End User: Utilities, Independent Power Producers, Government, Corporates Service Type: Maintenance, Installation, Consulting, Operation |
| Companies Covered | Vestas, Siemens Gamesa, GE Energy, Goldwind, Envision, Nordex, Ming Yang, Dongfang, CSSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onshore Wind Turbine (above 2.5MW) Market Trends and Innovations
Digitalization of turbine performance contracting and predictive maintenance platforms is restructuring how fleet operators monetize generation assets across multi-site portfolios.
Advanced blade aerodynamics incorporating carbon fiber spar caps and serrated trailing edges is rewriting efficiency benchmarks for low-speed wind resource capture. Utility-scale developers in China's northern provinces adopt these designs aggressively to maximize annual energy production per installed megawatt. The technology is compressing levelized cost thresholds and displacing conventional steel-glass hybrid configurations in new procurement specifications.
The EU F-Gas Regulation mandates phase-down of sulfur hexafluoride in high-voltage switchgear, forcing nacelle electrical architecture redesigns across European deployment pipelines. Manufacturers must certify vacuum interrupter and solid-insulation alternatives that meet arc-quenching performance standards. Offshore-ready turbine platforms face accelerated compliance timelines as the regulation extends to import equipment.
Power purchase agreement structures now unbundle hardware procurement from long-term service and energy yield guarantees. Corporate buyers in technology and manufacturing verticals negotiate direct contracts that transfer operational risk to turbine suppliers while retaining certificate ownership. This contracting evolution is most visible in China's deregulated generation markets and select US independent system operator territories.
Onshore Wind Turbine (above 2.5MW) Market Segmentation
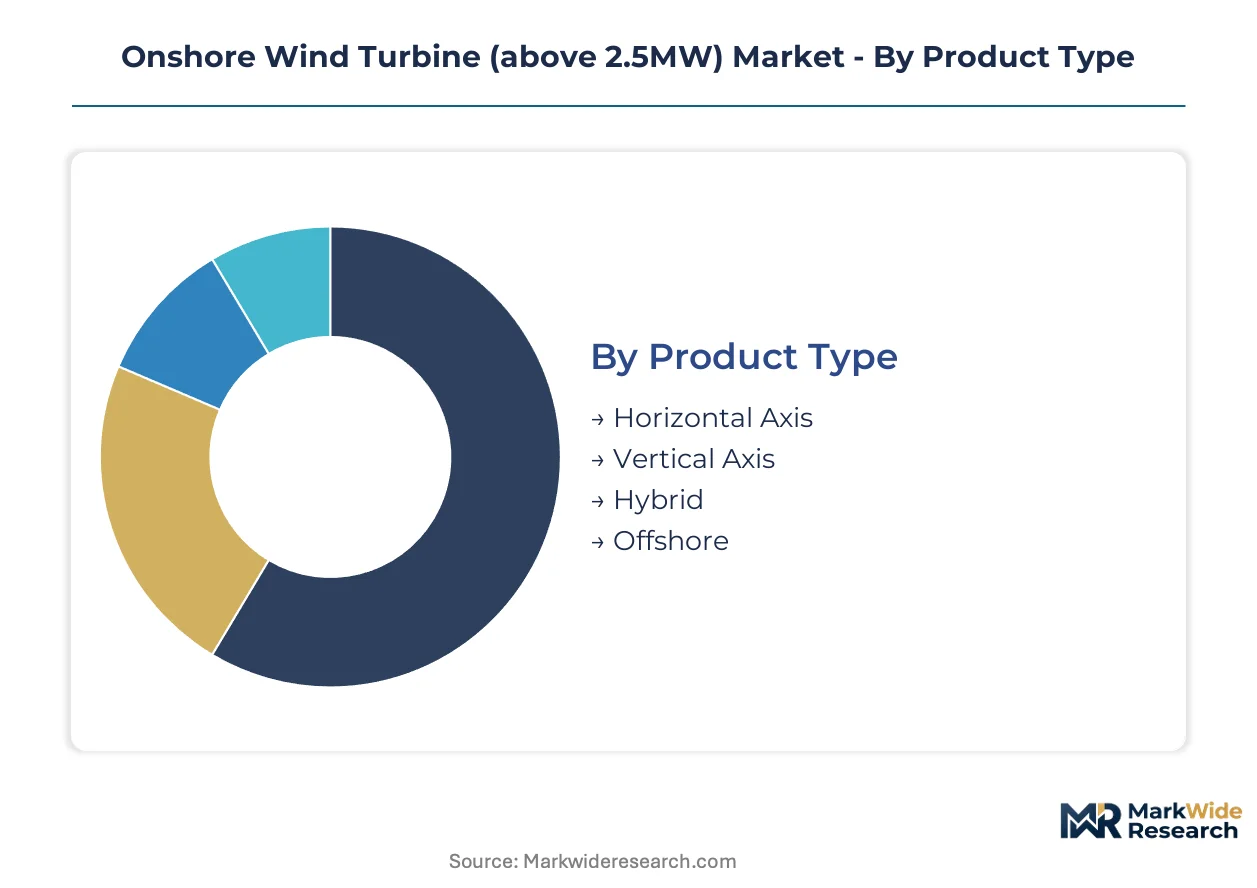
Turbine sizing and configuration choices directly determine which grid codes, environmental permits, and interconnection standards projects must satisfy. Segmentation reveals how certification pathways cluster around technology architectures and offtaker risk profiles.
Product Type:
Grid integration standards from IEC and national regulators impose distinct certification burdens depending on rotor orientation and platform design.
- Horizontal Axis:Dominant architecture with upwind rotor positioning and three-blade configurations. Hub heights exceeding 130 meters in Inner Mongolia and Xinjiang require aviation clearance protocols under China's Civil Aviation Administration alongside grid code compliance from the National Energy Administration.
- Vertical Axis:Darrieus and H-rotor designs eliminate yaw mechanisms and reduce nacelle complexity. Limited deployment concentrates in distributed generation pilots where simplified mechanical architectures offset lower aerodynamic efficiency.
- Hybrid:Combines horizontal-axis primary rotors with supplementary vertical-axis elements or solar co-location. Emerging configurations face dual certification pathways from electrical safety and renewable integration regulators.
- Offshore:Fixed-bottom and floating platforms engineered for marine environments. Not applicable to onshore market scope; excluded from subsequent analysis.
Leading the category by volume: Horizontal Axis. Growing fastest: Hybrid.
Technology:
Drive train architecture dictates maintenance scheduling, spare parts inventory, and technician certification requirements across fleet portfolios.
- Gearless:Direct-drive permanent-magnet generators eliminate gearbox failure modes. Goldwind's in-house rare earth supply chain in Baotou anchors cost competitiveness for utility-scale deployments across northern China.
- Geared:High-speed generators with multi-stage planetary gearboxes dominate legacy installed base. Replacement part availability and gearbox overhaul expertise concentrate in established European and Chinese service networks.
- Direct Drive:Synchronous generators with full converter interfaces enable variable-speed operation. Grid operators in deregulated markets mandate this capability for frequency response compliance.
- Variable Speed:Full power converter architectures optimize aerodynamic efficiency across wind speed ranges. Fastest-expanding category as interconnection standards harden reactive power and ride-through requirements.
Volume leadership rests with Gearless configurations. Variable Speed technology is climbing the fastest.
End User:
Counterparty credit quality and contract duration shape turbine supplier risk pricing and warranty terms.
- Utilities:State-owned and investor-owned grid operators with regulated cost recovery. Procurement in China's northern provinces concentrates under provincial grid company tendering with National Energy Administration oversight.
- Independent Power Producers:Merchant developers and project finance vehicles. Revenue exposure to wholesale power prices demands higher turbine availability guarantees and longer service contracts.
- Government:Public sector direct ownership for rural electrification and carbon target fulfillment. Budget cycle constraints compress procurement timelines and favor standardized equipment specifications.
- Corporates:Technology and manufacturing buyers securing renewable energy certificates through direct power purchase agreements. Contract structures unbundle hardware from energy yield guarantees, transferring operational risk to suppliers.
Utilities command the largest share of installed capacity. Corporates are gaining share fastest.
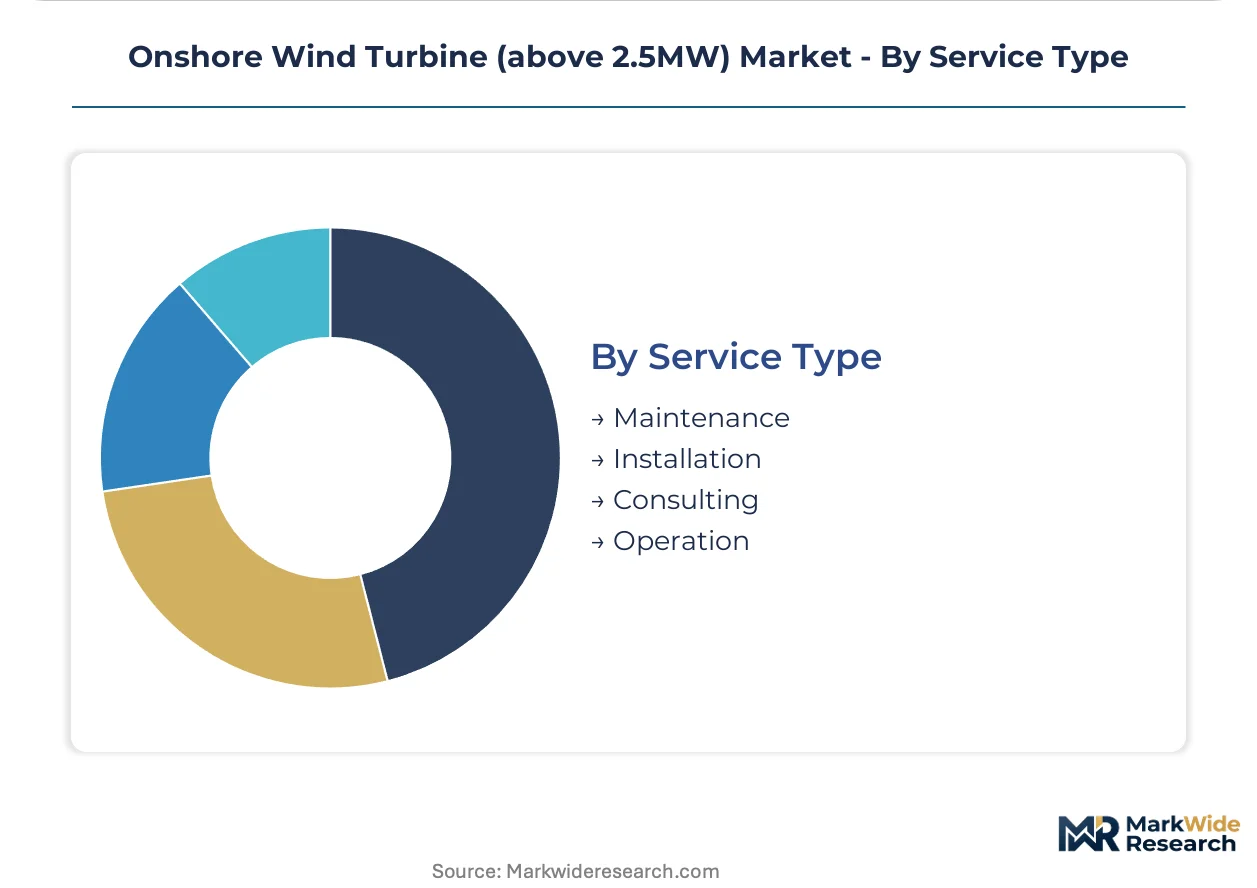
Service Type:
Revenue model evolution from equipment sales to performance contracting restructures supplier-customer relationships.
- Maintenance:Scheduled and corrective interventions including blade inspection, gearbox oil changes, and generator bearing replacement. Predictive analytics platforms from Vestas enable condition-based scheduling that extends component life.
- Installation:Civil works, turbine erection, and grid connection. 170-meter rotor components demand specialized heavy-lift equipment and route planning for blade logistics.
- Consulting:Site assessment, resource measurement, and project optimization. Micrositing algorithms integrate LiDAR data with terrain models to maximize annual energy production.
- Operation:Full asset management including dispatch compliance and revenue optimization. Corporate power purchase agreements increasingly bundle twenty-year operation contracts with equipment supply.
Maintenance generates the highest recurring revenue. Operation contracts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global onshore wind turbine capacity above 2.5MW while domestic deployment concentrates in northern provinces. Consumption patterns diverge between established European markets and rapidly expanding Asian installations.
China
Inner Mongolia and Xinjiang provinces host the largest utility-scale project pipelines under National Energy Administration grid parity mandates. The Ministry of Ecology and Environment enforces carbon intensity targets that accelerate turbine sizing above 3MW. Baotou's rare earth processing cluster anchors permanent-magnet generator supply chains for Goldwind and domestic competitors.
United States
Texas and Great Plains states drive order intake through independent power producers and utility procurement. The Federal Energy Regulatory Commission governs interconnection standards that delay project commissioning in congested transmission zones. Iowa and Oklahoma wind corridors concentrate repowering activity as aging fleets reach end-of-design-life.
Germany
Onshore capacity additions face permitting bottlenecks despite EU Green Deal renewable targets. The Federal Network Agency implements auction mechanisms that favor lowest-cost bids from direct-drive turbine configurations. Northern states including Lower Saxony and Schleswig-Holstein concentrate repowering projects replacing 20-year-old installations with 4MW-plus units.
India
Gujarat and Tamil Nadu lead state-level renewable purchase obligations driving utility-scale deployment. The Central Electricity Authority mandates grid code compliance that favors variable-speed turbine configurations for frequency response. Rajasthan's desert regions attract capacity additions targeting corporate power purchase agreements from manufacturing and data center buyers.
Brazil
Northeast wind corridors in Rio Grande do Norte and Bahia dominate capacity additions through auction-based procurement. The National Electric Energy Agency regulates transmission access that shapes project siting decisions. Ceará and Piauí states emerge as secondary development zones as grid expansion reaches previously isolated high-resource areas.
Onshore Wind Turbine (above 2.5MW) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across turbine architecture specialization. The market structure consolidates around integrated manufacturers with captive component supply and independent assemblers relying on outsourced drivetrains. Three archetypes dominate: rare-earth-integrated Chinese producers, European service-revenue maximizers, and Western technology licensors. Capacity expansion and backward integration into permanent-magnet supply chains represent the dominant competitive moves as input cost volatility reshapes procurement economics.
Among European-based manufacturers, Vestas anchors the predictive analytics and long-term service contracting archetype. Siemens Gamesa occupies a position within high-wind-site blade design specialization. Goldwind exemplifies the vertically integrated Chinese producer archetype with captive rare earth processing. These three entities represent distinct strategic postures without implying specific market share positions or financial performance.
| Leading Market Players |
|---|
| Vestas |
| Siemens Gamesa |
| GE Energy |
| Goldwind |
| Envision |
| Nordex |
| Ming Yang |
| Dongfang |
| CSSC |
| Others |
Pricing and Supply Chain Analysis
Utility procurement standardization around direct-drive permanent-magnet configurations is compressing supplier margins while forcing manufacturers to absorb rare earth price volatility through backward integration into generator production.
Pricing Analysis
Margin tightening in the gearless turbine tier reflects China's grid parity mandates and the National Energy Administration's pressure on state-owned utilities to minimize levelized cost. Three-tier pricing structure across premium, standard, and economy levels separates Vestas and Siemens Gamesa's service-bundled offerings from Goldwind's vertically integrated standard units and regional assemblers' economy configurations. Price differentiation hinges on certification grade for grid code compliance and after-sales service bundling duration. Corporate power purchase agreement buyers exhibit lowest price sensitivity due to renewable energy certificate premiums, while government tenders in northern provinces drive hardest bargain.
Supply Chain Analysis
Freight costs for 170-meter rotor blades now exceed component fabrication expense for projects beyond 500 kilometers from port or rail terminal. Manufacturing gravity centers on China, Germany, and Denmark, with Baotou's rare earth processing cluster feeding permanent-magnet generator production. The supply chain draws from carbon fiber spar caps, high-grade electrical steel, and rare earth neodymium-dysprosium alloys. Single-source vulnerability concentrates in China's rare earth refining capacity. Distribution runs through port-centric heavy-lift terminals serving Inner Mongolia and Xinjiang development zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's sulfur hexafluoride phase-down erects a compliance moat that rewards nacelle electrical system redesign capabilities while filtering out capital-constrained assemblers.
For Market Incumbents: Anchor service revenue expansion through predictive analytics platforms that lock in twenty-year operation contracts alongside hardware sales. Defend against Goldwind's rare earth cost advantage by accelerating vacuum interrupter certification for EU Green Deal compliance and building captive blade logistics networks for 170-meter component handling. For New Entrants and Emerging Players: Variable-speed power electronics specialization offers entry into grid frequency response procurement specifications where established technician scarcity creates execution gaps. Target corporate renewable procurement in Rajasthan and Texas where direct contracting bypasses utility tendering. Pursue licensing arrangements with European incumbents needing F-Gas Regulation-compliant electrical architectures. For Investors and Strategic Acquirers: The window for entry favors rare-earth-integrated Chinese producers and predictive analytics-enabled service platforms. Five-to-ten year viability rests on permanent-magnet supply chain control and software-defined power curve capabilities. Monitor grid code harmonization progress across multiple jurisdictions as inflection signal for commissioning timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Baotou-based supply chains insulate Goldwind from neodymium price volatility and geopolitical export restrictions. |
| Predictive Analytics Platform Deployment | Vestas extends revenue streams beyond hardware through condition-based maintenance and energy yield guarantees. |
| F-Gas Regulation Compliance Certification | Vacuum interrupter validation unlocks European auction participation and offshore-ready platform sales. |
| Corporate Power Purchase Agreement Structuring | Direct contracts with technology buyers transfer operational risk while retaining renewable energy certificate ownership. |
| 170-Meter Rotor Logistics Network Buildout | Specialized heavy-lift handling capabilities overcome transport infrastructure constraints for low-wind site capture. |
Research Methodology
Multi-period observation of turbine order intake, grid interconnection queues, and rare earth price indices anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Secondary validation drew from National Energy Administration deployment statistics, IEA renewable capacity reports, FERC interconnection filings, and project development databases. Bottom-up capacity aggregation and top-down policy impact modeling were triangulated against manufacturer production disclosures.
Segment-weighting across technology type, end-user category, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from installed capacity build rates and equipment replacement cycles. Forecast inputs incorporated grid parity mandate enforcement timelines and corporate renewable procurement acceleration curves.
Several conditions sit outside the modeled scope, including abrupt rare earth export restrictions, unanticipated grid code reversals, and breakthrough energy storage cost declines that could displace firm renewable capacity requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Japan Wind Energy Market