
 Offshore Wind Tower Market | 2026-2036
Offshore Wind Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Wind Tower Market Analysis
Utility developers are redrawing procurement priorities away from traditional oil and gas engineering firms toward dedicated offshore wind fabricators. Vestas leverages its nacelle-tower integration expertise to capture bundled project contracts. Siemens Gamesa anchors European demand through its blade-tower logistics coordination. Goldwind competes on cost-optimized monopile designs tailored to Asia-Pacific seabed conditions.
An offshore wind tower is a welded tubular steel structure, typically 80–120 meters in length and 6–10 meters in diameter at the base, that elevates the nacelle and rotor assembly above sea level while transferring aerodynamic and hydrodynamic loads to the foundation. Monopile towers dominate shallow-water deployments below 60 meters depth due to simpler installation logistics and lower capital intensity. Jacket structures command premium margins in deeper North Sea and Atlantic sites where lateral loading intensifies. Gravity-based foundations retain niche relevance in markets with favorable seabed geology and localized concrete supply chains.
The International Electrotechnical Commission's IEC 61400-3-2 standard governs design loads for offshore wind turbines, while China's GB/T 18451 series mandates tower fatigue-life verification for domestic projects. The EU Green Deal's domestic content thresholds and the F-Gas Regulation's embodied-carbon tracking are reshaping supplier qualification criteria. Stakeholders must monitor evolving vessel availability constraints and foundation technology transitions as project pipelines push into deeper waters.
Market Dynamics
Installation vessel scarcity and domestic content mandates are restructuring supplier qualification criteria faster than fabrication capacity can expand. Developers now pre-qualify tower fabricators based on vessel charter access and steel sourcing traceability rather than engineering credentials alone.
Growth Catalysts
- EU Green Deal domestic content thresholds:European developers must source specified shares of tower steel and assembly labor from within the bloc, redirecting procurement toward local fabricators.
- Floating foundation pilot pipelines:Demonstration projects in deeper Atlantic and Pacific waters are validating semi-submersible platforms that demand specialized tower-to-floater connection engineering.
- China's dual carbon goals:Provincial renewable energy targets under the national 2030 peak emissions commitment are accelerating offshore wind licensing in Jiangsu and Guangdong coastal zones.
Market Restraints
- Heavy-plate steel supply concentration:Specialized offshore-grade steel production clusters in China and South Korea create input cost volatility when regional mill capacity tightens.
- IEC 61400-3-2 certification timelines:Type certification for novel tower designs requires multi-year testing protocols that delay project financial close.
- Jacket structure fabrication bottlenecks:Complex tubular joint welding demands scarce certified welder labor pools concentrated in North Sea port zones.
Strategic Opportunities
- US Inflation Reduction Act offshore wind credits:Production tax credits for projects commencing construction before statutory deadlines are accelerating East Coast lease area development.
- Tower-nacelle pre-assembly integration:Port-side marriage of complete turbine systems reduces offshore lift operations and vessel day-rates.
- Recyclable steel tower design standards:Emerging circular economy protocols in the Netherlands and Denmark are creating first-mover advantage for demountable connection technologies.
Industry Challenges
- Offshore-certified welding labor scarcity:Multi-pass thick-section welding qualifications require 18-24 month training pipelines that lag demand expansion in emerging markets.
- GB/T 18451 fatigue verification complexity:Chinese domestic projects demand site-specific seismic and typhoon load case documentation that extends design cycles.
- Installation vessel reconfiguration lead times:Crane upgrades and jack-up leg extensions for next-generation 15MW+ turbines require 12-18 month yard stays that compress project scheduling windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Wind Tower Market |
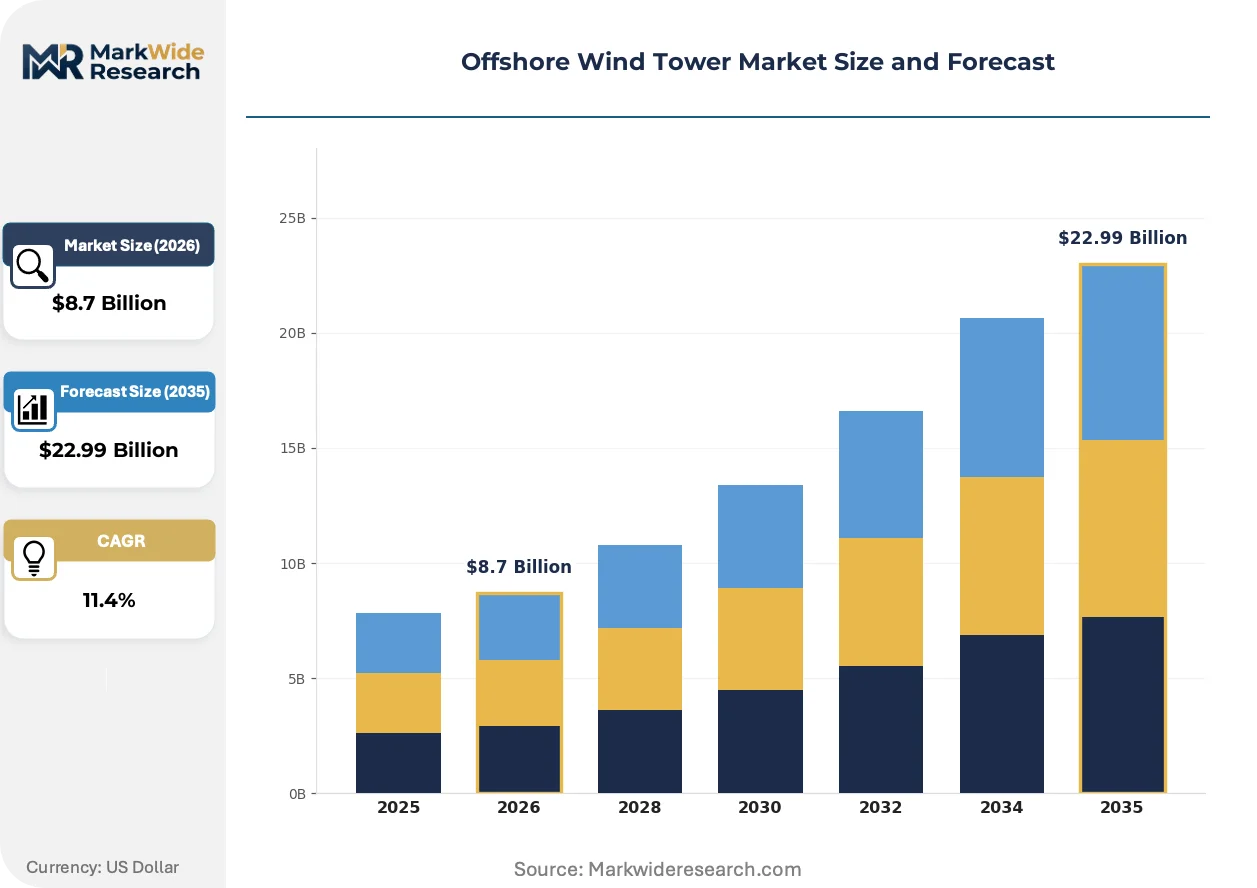
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Monopile, Jacket, Spar, Gravity Based Component: Tower, Turbine, Foundation, Substation End User: Utilities, Developers, OEMs, Contractors Installation Method: Float-Over, Bottom-Fixed, Installation Vessel, Dynamic Positioning |
| Companies Covered | GE Vernova, Nordex SE, RESIZE, Goldwind, US Forged Rings, Vestas, Ming Yang Smart Energy, Ørsted, Siemens Gamesa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Wind Tower Market Emerging Trajectories
Modular tower segment manufacturing is compressing logistics constraints while digital twin technologies rewrite quality assurance protocols. These shifts are redrawing the boundary between fabrication yard competence and offshore installation risk.
Roll-welded can production is decomposing the traditional monopile supply chain. Steel mills in South Korea and Japan are investing in continuous forming lines that eliminate discrete plate rolling and longitudinal seam welding. European developers are qualifying these processes for North Sea projects, enabling mill-direct supply that compresses fabrication steps and reduces port inventory requirements.
Europe's F-Gas Regulation embodied-carbon tracking is mandating lifecycle emissions disclosure for tower steel and coating systems. Fabricators must now document Scope 3 emissions from ore extraction through hot-rolling, with non-compliant suppliers excluded from public tender processes. Baltic Sea projects with near-term commissioning dates are experiencing the most acute compliance pressure due to retroactive qualification requirements.
Buyer consortiums are consolidating turbine procurement into multi-project framework agreements that bundle tower supply with installation vessel access. Danish and German utilities are pioneering this structure, locking in decade-long steel supply commitments in exchange for guaranteed vessel slots. The model is displacing project-specific competitive bidding in established European offshore wind zones where supply scarcity favors relationship-based contracting.
Offshore Wind Tower Market Segmentation
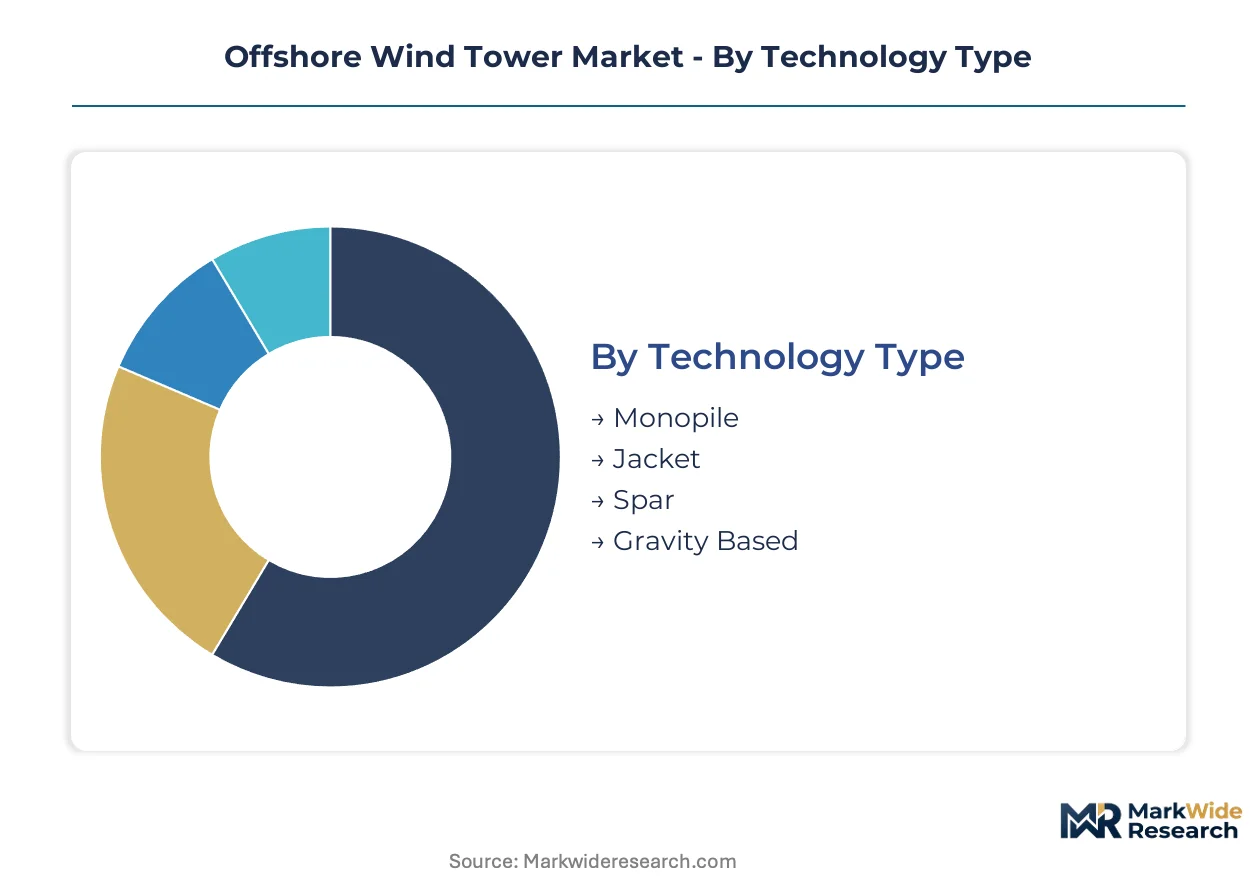
Tower foundation technology selection dictates fabrication methods, steel grades, and port infrastructure requirements across offshore wind developments. Segmentation clarity enables suppliers to align capacity investments with specific water depth regimes and installation constraints.
Technology Type:
Monopile towers anchor domestic European fabrication while jacket structures drive Asian export demand for deeper-water Atlantic projects.
- Monopile:Welded tubular steel structures typically 80-120 meters in length with 6-10 meter base diameters, engineered for shallow-water deployments below 60 meters depth. German and Danish fabricators concentrate output for North Sea projects where simpler installation logistics reduce capital intensity. IEC 61400-3-2 certification requirements and F-Gas Regulation embodied-carbon tracking are tightening supplier qualification timelines for this segment.
- Jacket:Lattice frameworks of interconnected tubular members designed to withstand intensified lateral loading in deeper waters beyond 60 meters. South Korean yards command export orders for North Sea and Atlantic sites where complex tubular joint welding demands scarce certified labor pools. The EU Green Deal domestic content thresholds are redirecting procurement toward European fabricators with vessel charter partnerships.
- Spar:Cylindrical floating platforms ballasted to maintain vertical stability in ultra-deep deployments.
- Gravity Based:Concrete or steel-concrete hybrid structures relying on mass rather than pile penetration for stability.
Monopile commands the established base. The steepest expansion runs through Jacket.
Component:
Component segmentation tracks cost concentration, with tower steel representing the largest single capital item and substation fabrication commanding premium margins.
- Tower:The primary load-bearing structure transferring aerodynamic and hydrodynamic forces to the foundation, typically fabricated from heavy-plate offshore-grade steel. Chinese and South Korean steel mills dominate input supply, creating cost volatility when regional capacity tightens. Roll-welded can production is compressing traditional fabrication steps.
- Turbine:The complete nacelle-rotor assembly including generator, gearbox, and blade attachment systems. Vestas and Siemens Gamesa anchor demand through bundled procurement contracts that integrate tower supply with turbine delivery.
- Foundation:The subsea interface structure—monopile, jacket, or gravity-based—securing the tower to the seabed.
- Substation:Offshore platforms housing transformers, switchgear, and power conversion equipment for grid connection.
Tower fabrication absorbs the largest capital share. Substation engineering delivers the highest margin expansion trajectory.
End User:
End user segmentation reveals divergent procurement strategies, with utilities consolidating multi-project frameworks while contractors compete on installation vessel access.
- Utilities:Vertically integrated power generators operating developed offshore wind assets under long-term offtake agreements. Danish and German utilities pioneered decade-long steel supply commitments in exchange for guaranteed vessel slots, displacing project-specific bidding in supply-scarce European zones.
- Developers:Project sponsors securing lease areas and financing prior to construction commencement. US East Coast developers are accelerating procurement timelines to capture Inflation Reduction Act production tax credits before statutory construction deadlines.
- OEMs:Original equipment manufacturers integrating tower supply with turbine system warranties.
- Contractors:Engineering-procurement-construction firms managing offshore installation logistics.
Utilities lock in volume through framework agreements. Developers are gaining share fastest through lease-area aggregation.
Installation Method:
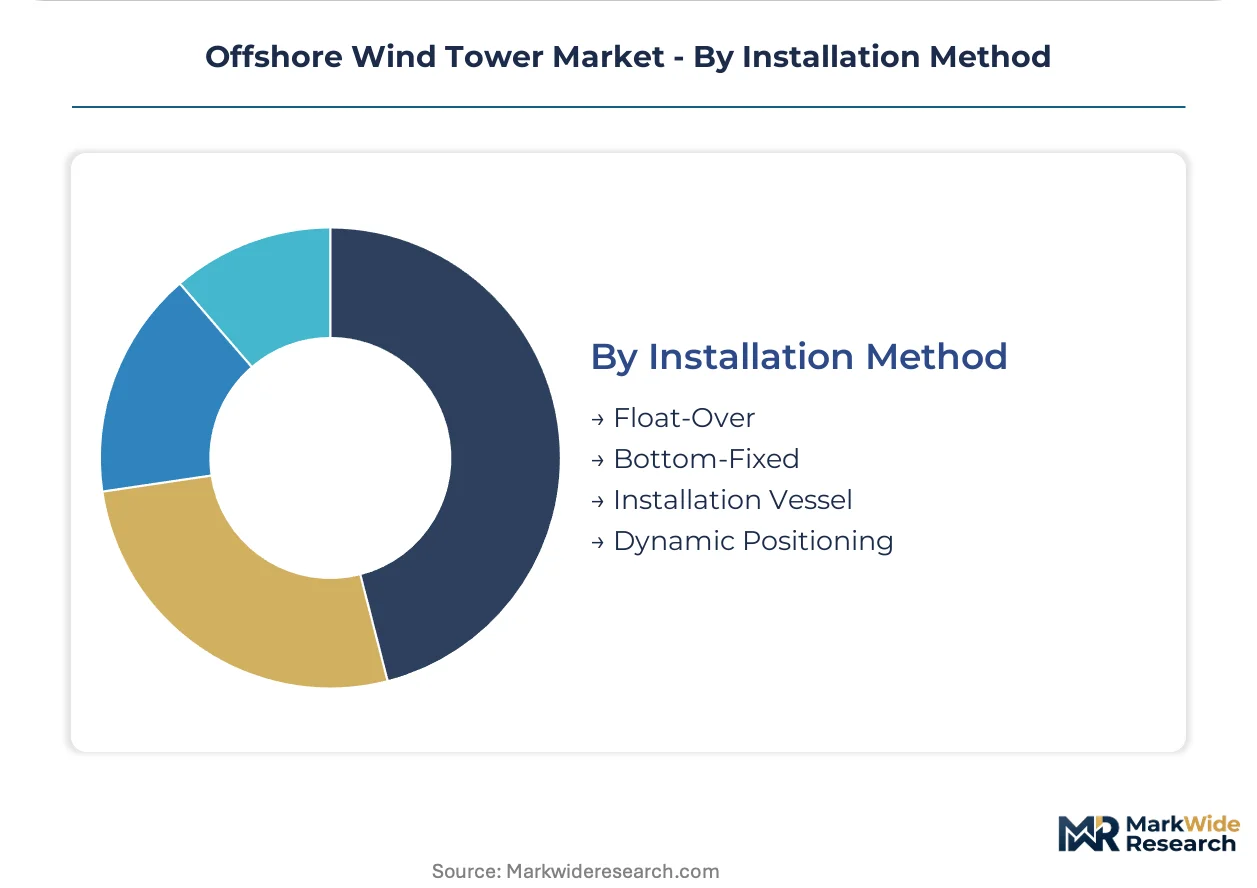
Installation segmentation tracks vessel specialization, with bottom-fixed methods dominating established markets and float-over techniques emerging for next-generation floating foundations.
- Bottom-Fixed:Conventional jack-up vessel operations driving piles or securing gravity structures directly to the seabed. Installation vessel scarcity and 12-18 month reconfiguration lead times for 15MW+ crane upgrades are compressing project scheduling windows across North Sea and Baltic developments.
- Float-Over:Heavy-lift operations assembling complete turbine systems on floating platforms for deep-water tow-out. Demonstration projects in Atlantic and Pacific waters are validating semi-submersible platforms demanding specialized tower-to-floater connection engineering.
- Installation Vessel:Purpose-built jack-up or heavy-lift vessels purpose-designed for offshore wind component handling.
- Dynamic Positioning:Computer-controlled thruster systems maintaining vessel station-keeping without anchor deployment.
Bottom-Fixed retains the installed base. Float-Over is climbing the fastest as floating foundation pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cuxhaven deepwater terminal anchors Germany's fabrication dominance, while Hull's Alexandra Dock expansions underwrite UK assembly scale. These port infrastructures concentrate tower supply chains across the North Sea basin.
China
Jiangsu and Guangdong provincial licensing accelerates coastal zone development under national dual carbon goals. GB/T 18451 fatigue verification mandates site-specific seismic documentation that extends domestic design cycles. The Yangtze River Delta cluster around Nantong and Qidong dominates heavy-plate rolling and monopile can production for Asia-Pacific export.
Germany
North Sea lease rounds and Baltic pipeline commitments sustain demand for 15MW+ tower specifications. The EU Green Deal domestic content thresholds redirect procurement toward fabricators with verified European steel sourcing. The Cuxhaven-Emshaven port corridor concentrates certified welder labor pools and jack-up vessel charter coordination.
United Kingdom
Round 4 and Round 5 lease awards drive procurement of extra-large monopile towers for deeper Dogger Bank waters. The F-Gas Regulation embodied-carbon tracking excludes non-compliant suppliers from Crown Estate tender processes. The Humber estuary fabrication zone around Hull and Immingham anchors Siemens Gamesa and Ørsted supply commitments.
United States
Inflation Reduction Act production tax credits accelerate East Coast lease area development before statutory construction deadlines. FERC interconnection queue reforms compress project scheduling windows for Massachusetts and New York procurement. The New Bedford Marine Commerce Terminal and Portsmouth offshore wind port anchor state-level infrastructure investments.
South Korea
Roll-welded can production investments at Posco and Hyundai Steel mills target North Sea export qualification. The government's renewable energy portfolio standards drive domestic offshore wind licensing in Jeolla coastal zones. The Busan-Ulsan heavy industry corridor concentrates continuous forming line capacity and marine coating specialization.
Offshore Wind Tower Market Vendor Landscape
Listed leaders compete with private specialists across vessel access and steel sourcing traceability rather than engineering credentials alone. The supplier base fragments across three tiers: integrated OEM-tower bundlers, dedicated monopile fabricators, and port-anchored installation contractors. Two strategic archetypes dominate competitive positioning: nacelle-tower integration specialists and mill-direct roll-welded can suppliers. Capacity expansion and strategic vessel charter partnerships represent the dominant competitive moves as installation scarcity restructures qualification criteria.
Among European-integrated OEMs, Vestas and Siemens Gamesa occupy positions as bundling anchors that combine turbine supply with tower logistics coordination. Goldwind exemplifies the Asia-Pacific cost-optimized archetype with monopile designs tailored to regional seabed conditions. These three entities represent divergent geographic and structural approaches to capturing project pipeline share.
| Leading Market Players |
|---|
| GE Vernova |
| Nordex SE |
| RESIZE |
| Goldwind |
| US Forged Rings |
| Vestas |
| Ming Yang Smart Energy |
| Ørsted |
| Siemens Gamesa |
| Others |
Supply Flow & Price Mechanics
Mill-scale economies at South Korean and Chinese heavy-plate facilities concentrate supply-side leverage among a handful of integrated steel producers, compressing price floors for European fabricators while amplifying volatility when regional capacity utilization tightens. This concentration forces project developers to accept longer-term offtake commitments or absorb spot-market premiums during vessel charter windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified European fabricators from Asian mill-direct suppliers and secondary port-assembly operations. Price differentiation hinges on F-Gas Regulation embodied-carbon compliance documentation and guaranteed installation vessel slot access. Cost compression in the standard tier is intensifying because buyer consortiums are consolidating multi-project frameworks that extract volume discounts. Independent developers exhibit highest price sensitivity due to single-project financing constraints, while Danish and German utilities demonstrate lowest sensitivity through decade-long supply lock-ins.
Supply Chain Analysis
China and South Korea anchor heavy-plate rolling and continuous forming line capacity for monopile can production, with Japan retaining niche ultra-thick plate specialization for jacket tubulars. Raw material dependencies draw from iron ore concentrates, offshore-grade heavy plate, and marine coating systems. Single-source vulnerability concentrates in certified welder labor pools clustered around North Sea port zones. Distribution runs through port-anchored fabrication yards that coordinate vessel charter access with steel delivery scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where F-Gas embodied-carbon tracking and EU Green Deal domestic content thresholds create irreversible supplier qualification barriers that compound over project development cycles.
For Market Incumbents: Compound vessel charter partnerships into exclusive multi-year slot agreements that freeze out competitors during installation scarcity windows. Deepen backward integration into heavy-plate supply through equity stakes in South Korean mill operations, neutralizing input cost volatility from Chinese capacity swings. Prioritize roll-welded can qualification investments to compress fabrication steps and defend margin position against port-assembly challengers.
For New Entrants and Emerging Players: Installation vessel reconfiguration service gaps expose incumbent blind spots where specialized marine engineering firms can capture premium margins. Target US East Coast port infrastructure development where Inflation Reduction Act credit deadlines compress procurement timelines and relax incumbent relationship advantages. Lead with tower-nacelle pre-assembly integration capabilities that reduce offshore lift operations for developers facing vessel day-rate inflation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mill-direct roll-welded can suppliers with F-Gas qualification pathways already initiated. Long-term viability centers on fabricators with demonstrated vessel charter coordination and European steel sourcing traceability. Monitor Baltic Sea project commissioning delays as the inflection signal for domestic content threshold enforcement stringency.
| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Charter Partnership Consolidation | Locks in installation capacity access through exclusive multi-year slot agreements with jack-up operators. |
| Roll-Welded Can Process Qualification | Enables mill-direct supply compression that eliminates discrete fabrication steps and port inventory requirements. |
| Domestic Content Compliance Investment | Secures EU Green Deal threshold adherence through verified European steel sourcing and assembly labor documentation. |
| Modular Tower Segment Manufacturing Scale-Up | Reduces logistics constraints for extra-large monopile transport to deeper-water deployment sites. |
| Tower-Nacelle Pre-Assembly Integration | Compresses offshore lift operations and vessel day-rates through port-side turbine system marriage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with offshore wind project developers, EPC contractors, and fabrication yard procurement leads, combined with secondary validation through FERC interconnection queue filings, IEA offshore wind project databases, and EU tender documentation. Bottom-up capacity utilization tracking at Nantong, Cuxhaven, and Busan fabrication clusters was triangulated against top-down vessel charter rate indices and heavy-plate import customs data.
Across the projection horizon, the analytical framework modeled technology type segmentation by water depth regime, component cost concentration by steel grade tier, and end-user procurement structure by utility framework versus developer spot contracting. CAGRs were derived from project pipeline aggregation across Round 4 and Round 5 lease awards, Baltic pipeline commitments, and provincial licensing trajectories under China's dual carbon goals. Forecast inputs incorporated installation vessel reconfiguration lead times and GB/T 18451 fatigue verification cycle extensions.
Underlying assumptions cover F-Gas Regulation retroactive qualification timelines and South Korean mill capacity expansion schedules, with deviation risk concentrated in heavy-plate trade flow disruptions and North Sea certified welder labor pool constraints. Recalibration cycles align with material shifts in vessel availability and domestic content threshold enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
Global Wind Automation Market