
 Wind Power Hubcap Market | 2026-2036
Wind Power Hubcap Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Hubcap Market Insights
Carbon fiber reinforced polymer is pivoting toward aluminum in mid-size onshore hubcap applications as resin cost volatility strains procurement budgets. Vestas Wind Systems leverages captive blade engineering expertise to extend design logic into nacelle exterior components including hubcap assemblies. GE Vernova anchors North American supply through integrated casting and finishing operations in South Carolina. Siemens competes on aerodynamic testing depth, operating dedicated wind tunnels that validate hubcap drag coefficients across turbulent inflow conditions.
Wind power hubcaps are protective enclosures mounted at the center of rotor hubs, typically manufactured from aluminum castings, glass-fiber composites, or engineered thermoplastics, and engineered to shield pitch bearings, slip rings, and hydraulic couplings from moisture ingress, particulate abrasion, and lightning strike damage. Their primary commercial purpose is to extend turbine availability by preventing premature drivetrain corrosion and reducing unscheduled maintenance events. Aluminum material grade dominates current production volumes due to established foundry infrastructure and recyclability compliance with EU end-of-life directives. Aerodynamic Covers represent the fastest-expanding product type as OEMs pursue incremental annual energy production gains through rotor-nacelle interface streamlining. Offshore Systems application demand concentrates margin pools where salt spray resistance certifications and cathodic protection integration command technical premiums.
DNV certification standards, IEC 61400 structural load requirements, and EPA stormwater permitting for coastal manufacturing facilities collectively shape product design cycles and factory siting decisions across the value chain. The EU Green Deal industrial emissions benchmarks and China's dual carbon goals from MEE are tightening embodied carbon thresholds for hubcap material selection and foundry energy sourcing. Stakeholders must monitor evolving nacelle-integrated sensor architectures that may redefine hubcap enclosure geometries and access panel configurations.
Market Dynamics
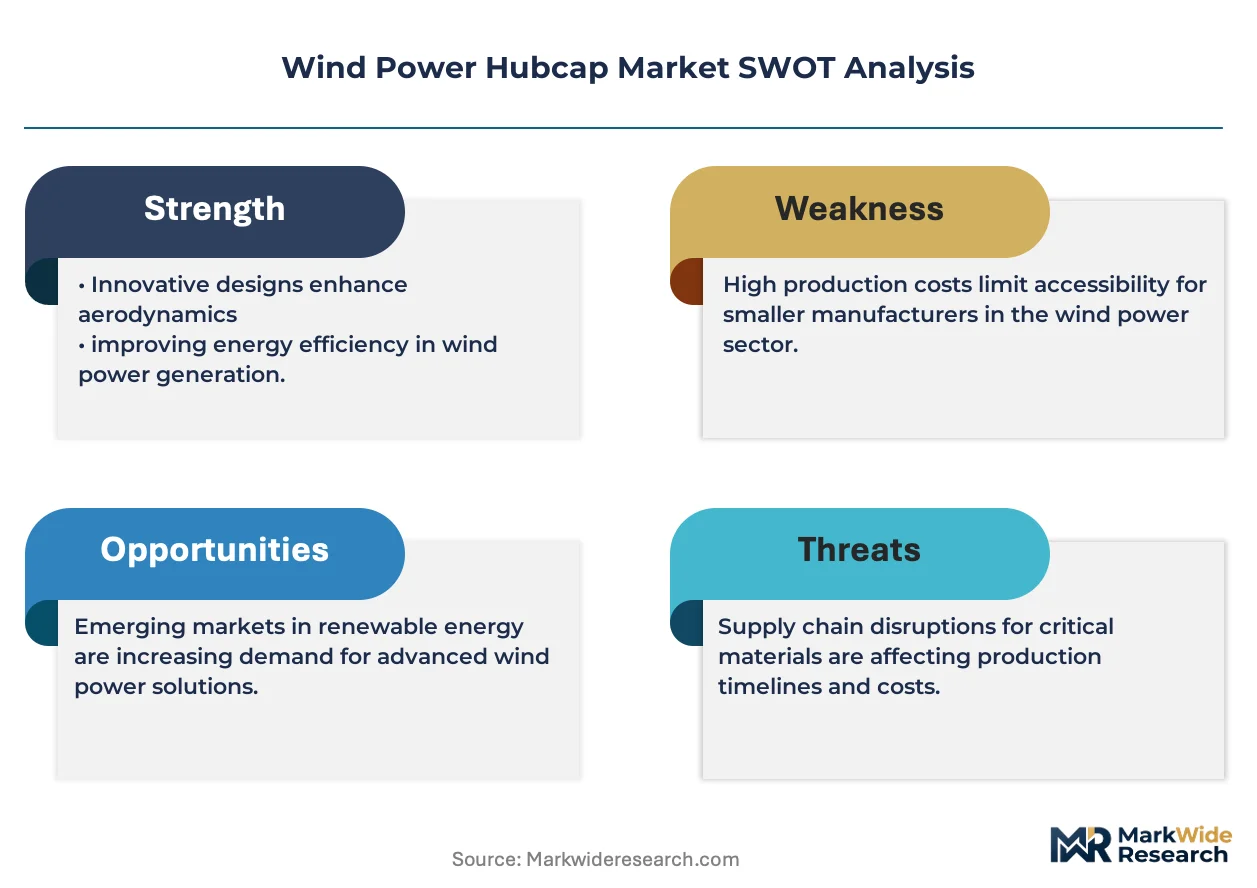
Offshore wind developers are scaling turbine diameters past 15 meters, forcing hubcap suppliers to reengineer structural load paths and aerodynamic profiles while maintaining corrosion resistance certifications. This dimensional pressure is compressing design cycles and concentrating procurement among foundries capable of integrated casting, machining, and surface treatment.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is accelerating demand for composite hubcap materials that eliminate refrigerant-intensive manufacturing processes in nacelle climate systems.
- Green hydrogen targets:National mandates in Germany and China are expanding offshore wind pipelines, driving procurement of cathodic protection-integrated hubcap assemblies for salt spray environments.
- Resin cost volatility:Carbon fiber reinforced polymer substitution toward aluminum in mid-size onshore applications is unlocking foundry capacity and stabilizing procurement budgets for utility-scale developers.
Market Restraints
- Foundry energy sourcing:EU Green Deal industrial emissions benchmarks are constraining aluminum smelter output in Germany and Poland, tightening primary material availability for cast hubcap production.
- Composite resin price swings:Epoxy and vinyl ester feedstock volatility is compressing margins for glass-fiber hubcap manufacturers without long-term petrochemical supply agreements.
- DNV certification timelines:Extended structural load validation protocols for hubcap assemblies exceeding 12-meter diameters are delaying product qualification and freezing supplier selection decisions.
Strategic Opportunities
- US offshore lease auctions:Bureau of Ocean Energy Management lease rounds in the Gulf of Mexico and Pacific Northwest are creating first-mover positioning for corrosion-resistant hubcap suppliers without European incumbent relationships.
- Nacelle-integrated sensor architectures:Convergence of lidar systems and pitch bearing condition monitoring is redefining hubcap enclosure geometries, opening design partnerships with turbine OEMs retrofitting existing fleets.
- China dual carbon goals:MEE embodied carbon thresholds are favoring domestic aluminum foundries with renewable energy sourcing, creating procurement windows for local hubcap manufacturers serving state-owned wind developers.
Industry Challenges
- Aerodynamic testing capacity:Dedicated wind tunnel availability for hubcap drag coefficient validation is concentrated among three European facilities, creating bottlenecks for new product development timelines.
- Lightning protection integration:Reconciling Faraday cage geometries with pitch system access panel configurations is extending engineering cycles and requiring cross-functional coordination between electrical and mechanical design teams.
- End-of-life recyclability:EU end-of-life directives for wind turbine components are forcing material selection trade-offs between aluminum recyclability and composite weight reduction, complicating procurement specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Hubcap Market |
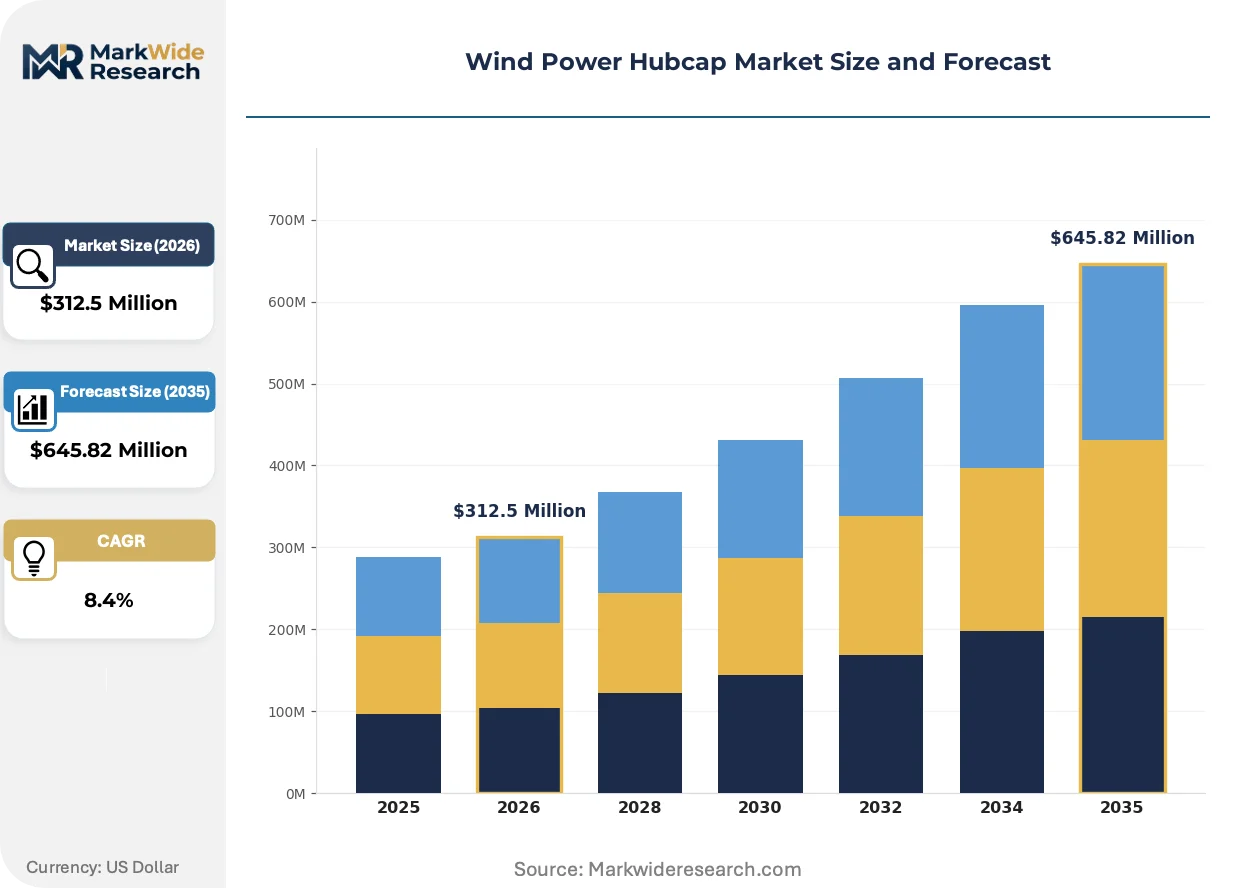
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hubcaps, Custom Designs, Aerodynamic Covers, Lightweight Options Material: Aluminum, Plastic, Steel, Composite Application: Wind Turbines, Offshore Systems, Onshore Farms, Renewable Projects Size: Small, Medium, Large, Extra Large |
| Companies Covered | Vestas Wind Systems, GE Vernova, Siemens, NextEra Energy, Sungrow Power Supply, Ørsted, Enel, ACWA Power, Equinor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Hubcap Market Trends and Innovations
Material substitution and regulatory tightening are compressing traditional design paradigms while opening technical white space in sensor integration and modular access systems. Suppliers are racing to align product architectures with evolving nacelle electronics footprints.
Engineered thermoplastics with embedded lightning strike meshes are expanding into offshore hubcap applications previously dominated by aluminum castings. Siemens Gamesa and Vestas procurement teams are qualifying these assemblies for 14-meter-plus rotor hubs in North Sea installations. The technology is expanding into margin pools where cathodic protection integration and reduced mass justify material cost premiums against metallic alternatives.
China's MEE dual carbon enforcement is tightening embodied carbon disclosure requirements for wind component imports, affecting hubcap material selection and foundry energy sourcing decisions. Manufacturers serving European turbine OEMs with Chinese supply chains must document renewable electricity shares in aluminum smelting and composite curing processes. Glass-fiber hubcap producers with captive solar-powered resin infusion facilities are capturing qualification advantages over conventional fossil-dependent competitors.
Utility-scale developers are consolidating hubcap procurement under long-term nacelle supply agreements rather than discrete component sourcing, compressing supplier count and elevating tier-one foundry relationships. Independent hubcap specialists without captive turbine OEM partnerships are pivoting toward aftermarket replacement and retrofit markets. This concentration is most visible in Germany and the United States, where Ørsted and NextEra Energy procurement frameworks favor integrated drivetrain suppliers over standalone component vendors.
Wind Power Hubcap Market Segmentation
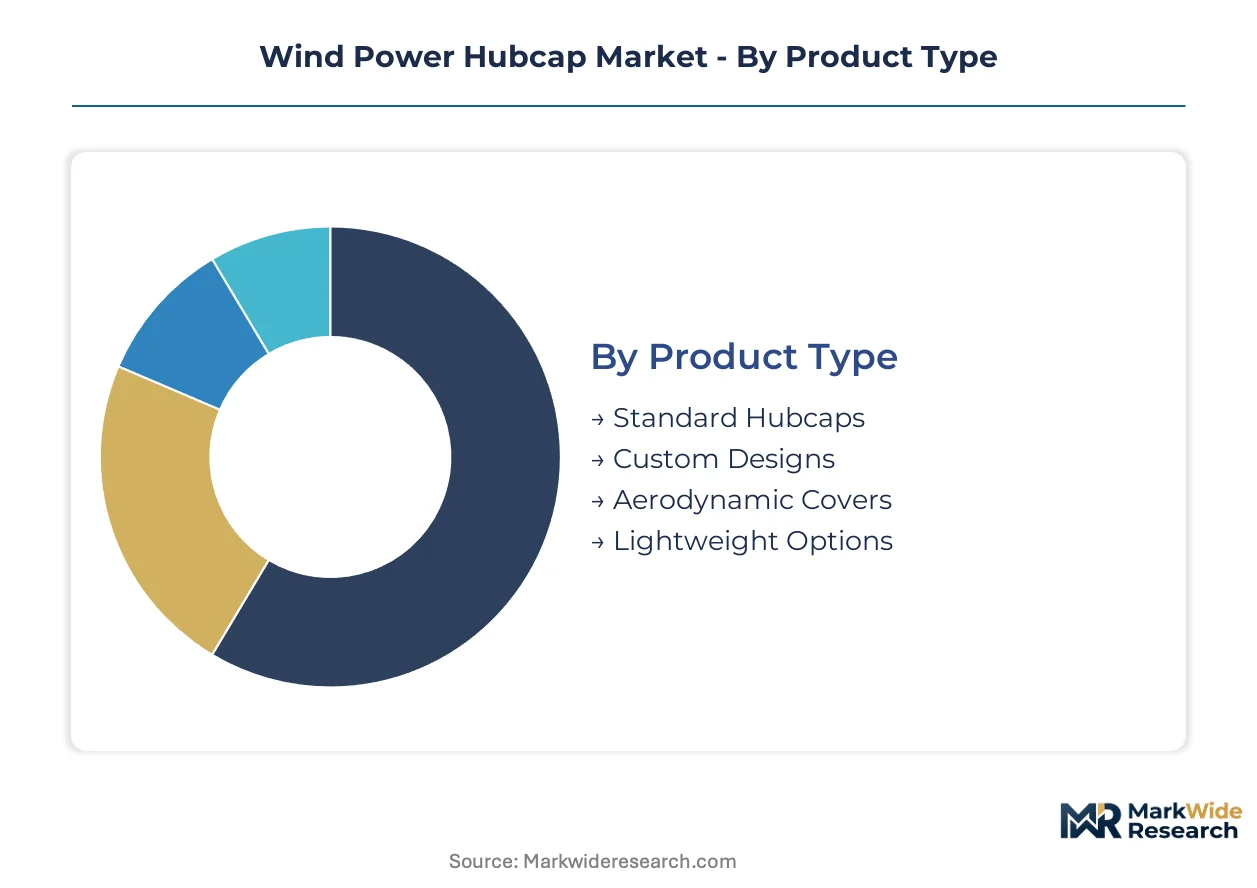
Wind power hubcap procurement splits across four distinct category axes, each governing supplier selection criteria and margin capture potential. Turbine OEMs and utility developers weight these dimensions differently depending on project scale, site conditions, and certification timelines.
Product Type:
Upgrade cycles for existing fleets are accelerating procurement of specialized hubcap variants as operators retrofit older turbines with improved aerodynamics and sensor integration capabilities.
- Aerodynamic Covers:Streamlined enclosures reduce rotor-nacelle interface drag, delivering incremental annual energy production gains. Vestas and Siemens Gamesa procurement teams in the North Sea and Baltic markets specify these for 14-meter-plus rotor hubs where certification premiums justify material cost differentials.
- Standard Hubcaps:Conventional protective enclosures dominate replacement volumes for turbines reaching mid-life maintenance windows. Foundries in Germany and Poland supply these through established casting networks, though EU Green Deal emissions benchmarks are constraining primary aluminum availability.
- Custom Designs:Bespoke geometries accommodate nacelle-integrated lidar and pitch bearing monitoring systems.
- Lightweight Options:Engineered thermoplastic variants target offshore weight reduction objectives.
Standard Hubcaps sits at the top of the volume ranking, with Aerodynamic Covers climbing the fastest.
Material:
Cost tier stratification separates premium composite specifications from commodity metallic alternatives, with resin price volatility compressing mid-market positioning.
- Aluminum:Cast aluminum grades dominate current production due to established foundry infrastructure and recyclability compliance with EU end-of-life directives. German and Chinese smelters with renewable energy sourcing are capturing procurement windows under tightening embodied carbon thresholds.
- Composite:Glass-fiber and carbon-fiber reinforced polymers deliver weight reduction for offshore salt spray environments. Cathodic protection integration and reduced mass justify material premiums against metallic alternatives in North Sea installations.
- Plastic:Engineered thermoplastics with embedded lightning strike meshes expand into mid-size onshore applications.
- Steel:Legacy material retains niche presence in heavy-duty onshore specifications.
Aluminum commands the broadest installed base, while Composite gains share fastest in offshore procurement.
Application:
Site-specific environmental certification requirements drive material and geometry selection, with salt spray resistance and lightning protection integration commanding technical premiums.
- Offshore Systems:Salt spray resistance certifications and cathodic protection integration define procurement specifications. Bureau of Ocean Energy Management lease auctions in the Gulf of Mexico and Pacific Northwest are creating first-mover positioning for corrosion-resistant suppliers.
- Onshore Farms:Utility-scale installations in Germany, China, and the United States concentrate procurement volumes. Resin cost volatility is accelerating carbon fiber substitution toward aluminum in mid-size applications, unlocking foundry capacity.
- Wind Turbines:Generic category captures mixed-site procurement without environmental specialization.
- Renewable Projects:Green hydrogen-linked developments in Germany and China expand pipeline visibility.
Onshore Farms anchor current procurement volumes, with Offshore Systems expanding most quickly.
Size:
Turbine diameter scaling past 15 meters is compressing supplier qualification timelines and concentrating procurement among foundries with integrated casting, machining, and surface treatment capabilities.
- Large:Hubcap assemblies exceeding 12-meter diameters face extended DNV certification timelines that freeze supplier selection decisions. Integrated casting and finishing operations in South Carolina and European coastal facilities serve this specification tier.
- Extra Large:Emerging category for next-generation offshore turbines requiring reengineered structural load paths. Dedicated wind tunnel availability for drag coefficient validation is concentrated among three European facilities, creating development bottlenecks.
- Medium:Mid-size onshore specifications see active material substitution from composites to aluminum.
- Small:Legacy turbine replacement market served by standardized catalog offerings.
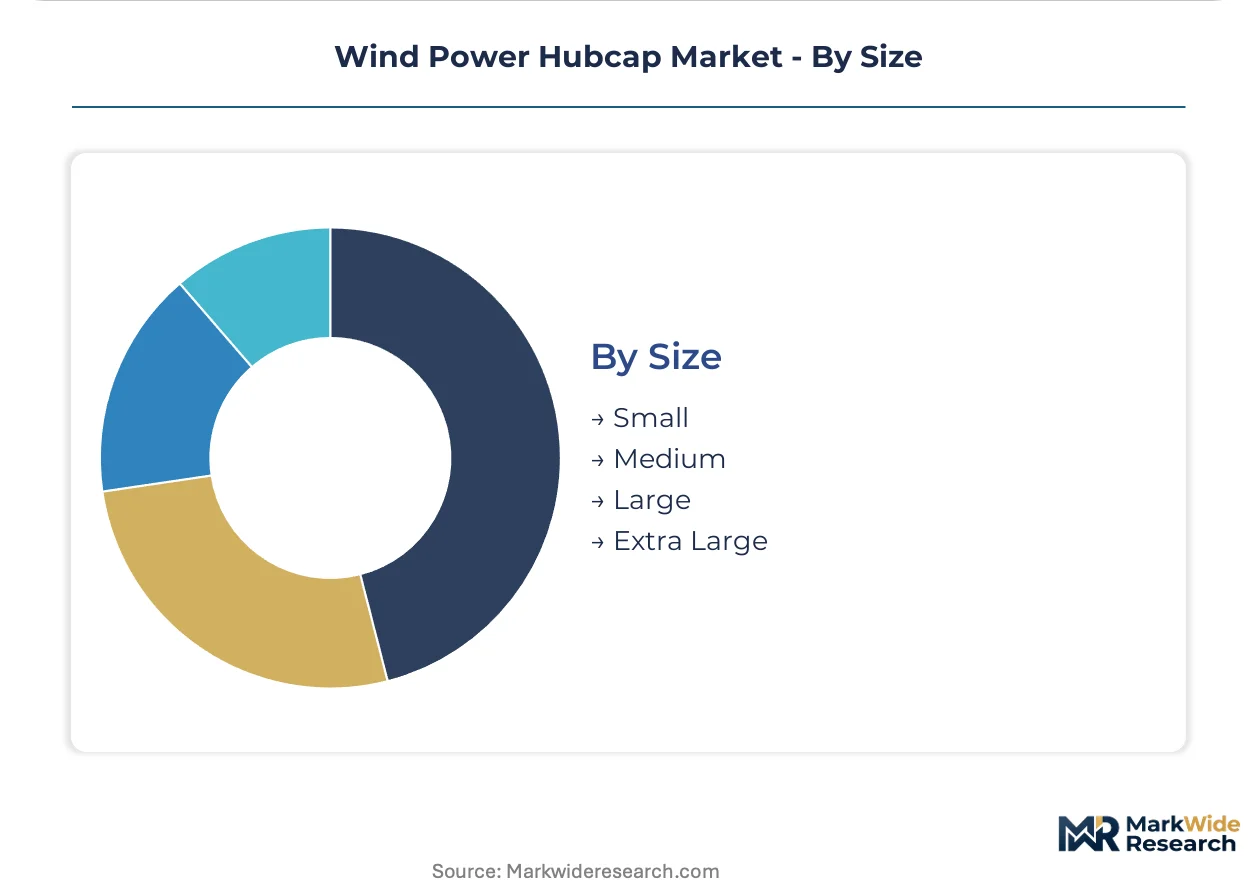
Medium specifications hold the largest installed base, with Extra Large gaining traction fastest in offshore pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundry clusters in North Rhine-Westphalia and Lower Saxony anchor procurement volumes for cast aluminum hubcap assemblies serving North Sea offshore installations.
Germany
Utility-scale offshore pipelines in the North Sea and Baltic Sea drive specification volumes for corrosion-resistant hubcap systems. The EU F-Gas Regulation accelerates composite material substitution in nacelle climate systems. Foundries in North Rhine-Westphalia and Lower Saxony concentrate casting capacity for 12-meter-plus diameter assemblies.
China
State-owned wind developers expand procurement for 15-meter rotor hub installations along eastern coastal provinces. MEE dual carbon enforcement tightens embodied carbon disclosure requirements for imported components. Yangtze River Delta manufacturing clusters integrate renewable-powered aluminum smelting to capture qualification advantages.
United States
Bureau of Ocean Energy Management lease auctions in the Gulf of Mexico and Pacific Northwest create procurement windows for cathodic protection-integrated assemblies. EPA stormwater permitting shapes coastal manufacturing facility siting decisions. South Carolina casting and finishing operations anchor North American supply for GE Vernova-integrated nacelle programs.
United Kingdom
Ørsted procurement frameworks favor integrated drivetrain suppliers over standalone hubcap vendors in North Sea development zones. UK offshore wind sector deal commitments accelerate domestic content requirements. Humber and Scottish east coast port clusters concentrate assembly and logistics operations for extra-large turbine components.
Poland
EU Green Deal industrial emissions benchmarks constrain primary aluminum smelter output for cast hubcap production. Baltic Sea offshore lease rounds expand addressable demand for salt spray-certified assemblies. Silesian and Pomeranian industrial zones balance foundry capacity against tightening renewable energy sourcing mandates.
Wind Power Hubcap Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated turbine OEMs deepen captive foundry relationships and independent specialists pivot toward aftermarket retrofit markets. The vendor base stratifies across three tiers: turbine OEMs with in-house casting operations, tier-one foundries under long-term nacelle supply agreements, and independent component specialists serving replacement demand. Strategic archetypes include vertically integrated drivetrain suppliers, aluminum foundries with renewable energy sourcing, and composite material specialists with cathodic protection integration. Geographic expansion and portfolio diversification represent the dominant competitive moves as suppliers position for US offshore lease auctions and China state-procurement windows.
Within the integrated OEM tier, Vestas Wind Systems, GE Vernova, and Siemens occupy positions that exemplify divergent strategic approaches to hubcap supply. Vestas leverages captive blade engineering expertise extending design logic into nacelle exterior components. GE Vernova anchors North American supply through South Carolina-based casting and finishing operations. Siemens competes on aerodynamic testing depth with dedicated wind tunnel validation capabilities. These three represent how turbine manufacturers are consolidating component procurement under long-term nacelle supply agreements rather than discrete sourcing arrangements.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| GE Vernova |
| Siemens |
| NextEra Energy |
| Sungrow Power Supply |
| Ørsted |
| Enel |
| ACWA Power |
| Equinor |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange aluminum price volatility cascades through German and Chinese foundry networks into three-tier pricing structures across premium, standard, and economy levels for hubcap assemblies. Casting energy costs and cathodic protection certification tiers stratify final procurement quotes as utility-scale developers consolidate under long-term nacelle agreements.
Pricing Analysis
Input-cost pass-through from primary aluminum smelting and epoxy resin feedstock drives contract-based long-term offtake agreements between foundries and turbine OEMs. Price differentiation separates DNV-certified offshore specifications from standard onshore catalog offerings, with certification grade and volume scale as the dominant tiering mechanisms. Cost compression in mid-size onshore segments intensifies because carbon fiber substitution unlocks foundry capacity and stabilizes procurement budgets. Independent component specialists serving replacement markets exhibit highest price sensitivity, while integrated OEMs with captive casting operations demonstrate lowest sensitivity due to upstream cost absorption.
Supply Chain Analysis
Workforce availability constraints in North Rhine-Westphalia and South Carolina foundry clusters are compressing machining and surface treatment lead times for large-diameter hubcap assemblies. Geographic supply concentration centers on Germany, China, and the United States, with raw material dependencies drawing from primary aluminum smelting, glass-fiber roving, and engineered thermoplastic resin systems. Single-source vulnerability around European wind tunnel testing capacity for aerodynamic validation creates qualification bottlenecks. Distribution runs through integrated nacelle supply agreements rather than discrete component channels, concentrating procurement relationships among tier-one foundries with renewable energy sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wind Power Hubcap Market functions as a stable compounder anchored by irreversible turbine diameter scaling past 15 meters, which perpetually refreshes demand for reengineered structural load paths and corrosion-resistant material specifications.
For Market Incumbents: Cement captive foundry relationships through backward integration into renewable-powered aluminum smelting to defend against resin cost volatility eroding composite hubcap margins. Prioritize certification investment in cathodic protection integration for Bureau of Ocean Energy Management lease auctions, locking out European competitors without US coastal manufacturing footprints. For New Entrants and Emerging Players: Launch via aftermarket retrofit partnerships targeting mid-life turbine maintenance windows where independent hubcap specialists retain procurement access despite OEM consolidation. Target US Gulf of Mexico offshore developments as the most penetrable geography, exploiting first-mover positioning without incumbent European relationships through engineered thermoplastic lightning-strike mesh qualifications. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic Chinese aluminum foundries with MEE-compliant renewable energy sourcing, positioned to capture state-owned wind developer procurement under tightening embodied carbon thresholds. Long-term viability rests on dual carbon enforcement durability and offshore pipeline visibility in eastern coastal provinces. Monitor DNV certification timeline compression as the inflection signal indicating supplier qualification bottlenecks easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Smelting | Captures MEE and EU Green Deal compliance advantages for German and Chinese foundry supply. |
| Cathodic Protection Certification Investment | Unlocks Bureau of Ocean Energy Management lease procurement for corrosion-resistant offshore assemblies. |
| Wind Tunnel Testing Partnership | Resolves aerodynamic validation bottlenecks concentrated among three European facilities. |
| Aftermarket Retrofit Channel Development | Preserves access as OEM consolidation compresses discrete component procurement relationships. |
| Engineered Thermoplastic Qualification | Expands margin pools in 14-meter-plus rotor hubs through lightning-strike mesh integration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with turbine OEM procurement directors, foundry operations managers, offshore wind project developers, and nacelle integration engineers with secondary validation against IEC 61400 structural load documentation, DNV certification registries, customs trade data for aluminum and composite inputs, and EPA stormwater permitting records for coastal manufacturing facilities. Bottom-up segmentation modeling and top-down macro constraint checks provided triangulation.
Comparable-period anchoring across historical installation volumes and forward pipeline visibility shaped the projection horizon, with segmentation dimensions spanning product type, material grade, application environment, and turbine diameter tier. CAGRs derived from unit economics modeling across foundry capacity utilization, resin cost trajectories, and offshore lease auction timing. Industry-specific inputs included embodied carbon disclosure thresholds and cathodic protection integration rates.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to EU F-Gas phase-down timelines, abrupt aluminum smelter curtailments under energy crisis scenarios, and technological displacement from nacelle-integrated sensor architectures eliminating traditional hubcap geometries. Forecasts reflect documented assumptions regarding certification timeline stability and offshore pipeline conversion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Wind Turbine Tower Market