
 Overhead Aluminium Conductors Market | 2026-2036
Overhead Aluminium Conductors Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Aluminium Conductors Market Insights
High-temperature low-sag (HTLS) specification tiers is collapsing the cost premium against conventional ACSR designs, forcing incumbent suppliers to recalibrate plant utilization. Prysmian Group leverages its European cable manufacturing footprint to anchor HTLS output for Mediterranean grid interconnections. Nexans competes through R&D intensity in thermal-resistant aluminum-zirconium alloys. Southwire Company dominates North American utility procurement through integrated rod-to-conductor verticality.
Overhead aluminium conductors are stranded wire assemblies of aluminum or aluminum-alloy filaments, typically reinforced with galvanized steel cores in ACSR configurations, engineered to carry electrical current across spans of 300–500 meters with tensile strength exceeding 1,500 MPa and operating temperatures up to 150°C for standard designs and 210°C for thermal variants. Their primary purpose is to transmit bulk electricity from generation points to substations and distribution nodes with minimal resistive loss over long distances. ACSR maintains volume leadership in emerging-market transmission builds where first-cost sensitivity governs procurement, while AAAC gains share in coastal and corrosive environments where steel-core degradation accelerates replacement cycles. The renewable energy application segment commands widening specification spreads as offshore wind export cables and solar farm collector systems require hybrid conductor designs with ampacity ratings 40–60% above legacy grid standards.
India's CEA mandates conductor testing under BIS IS 398 for all interstate transmission projects, compressing market access for uncertified imports and elevating domestic manufacturers like Apar Industries and Sterlite Power. China's GB/T 1179 and GB/T 20141 standards enforce aluminum purity thresholds and sag-tension modeling protocols that shape product development roadmaps for MIIT-licensed producers. The EU F-Gas Regulation indirectly steers conductor selection by restricting sulfur hexafluoride-dependent switchgear, pushing grid operators toward higher-ampacity lines that reduce substation count. Stakeholders must monitor how national content requirements and carbon-border adjustment mechanisms reshape sourcing economics for aluminum rod and drawn wire.
Market Dynamics
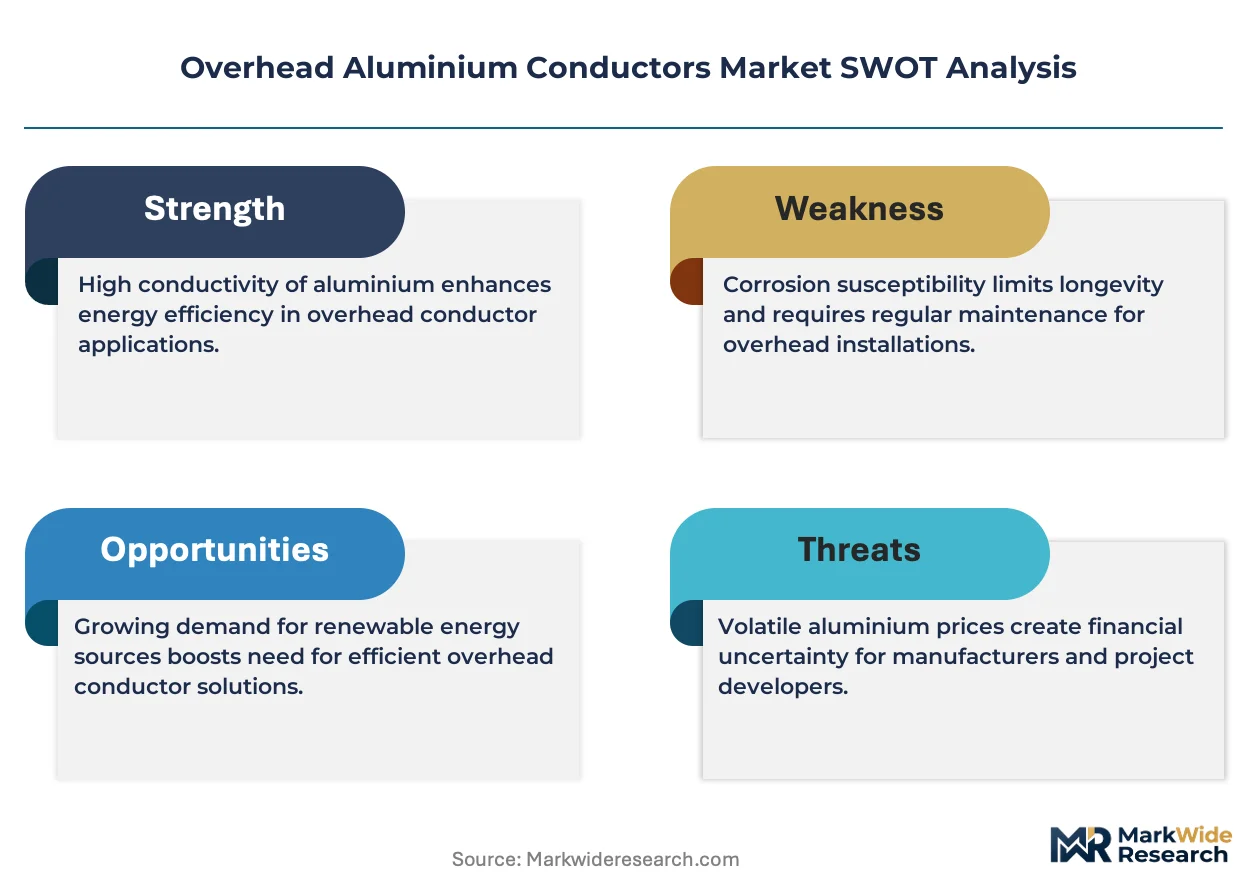
The collapse of HTLS cost premiums against conventional ACSR designs is compressing incumbent supplier margins and forcing plant utilization recalibration across stranded wire manufacturers.
Growth Catalysts
- India's CEA interstate mandates:BIS IS 398 certification requirements for all interstate transmission projects elevate domestic manufacturers and compress market access timelines for uncertified imports.
- Solar-wind hybrid reconductoring:Rajasthan and Gujarat renewable corridors require high-capacity conductor bundles at scale, accelerating procurement cycles for thermal-resistant alloy specifications.
- EU F-Gas Regulation indirect steering:Sulfur hexafluoride-dependent switchgear restrictions push grid operators toward higher-ampacity lines that reduce substation count across Mediterranean interconnections.
Market Restraints
- Aluminum rod input volatility:London Metal Exchange price swings for primary aluminum ingot transmit directly to drawn wire cost structures, eroding fixed-price contract viability.
- China MIIT-licensed supply concentration:GB/T 1179 and GB/T 20141 enforcement creates bottlenecked qualification pathways for non-domestic producers seeking thermal-resistant alloy market entry.
- Steel-core coastal degradation:Galvanized steel reinforcement in ACSR configurations accelerates replacement cycles in corrosive environments, elevating lifecycle costs against AAAC alternatives.
Strategic Opportunities
- Southeast Asia utility-scale builds:Vietnam and Thailand transmission expansion programs lack qualified domestic HTLS suppliers, creating first-mover positioning for certified exporters.
- Aluminum-zirconium alloy R&D convergence:Thermal-resistant filament development intersects with ampacity modeling software to enable 210°C operating designs for offshore wind export cables.
- Carbon-border adjustment pre-positioning:EU CBAM scope expansion toward aluminum-intensive products incentivizes low-carbon rod sourcing and green smelter partnerships.
Industry Challenges
- BIS certification timeline compression:Indian test laboratory capacity constraints extend qualification windows for new conductor entrants, delaying project award participation.
- Sag-tension modeling skill scarcity:Utility engineering departments lack personnel trained in high-temperature thermal modeling, forcing reliance on manufacturer-provided simulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Aluminium Conductors Market |
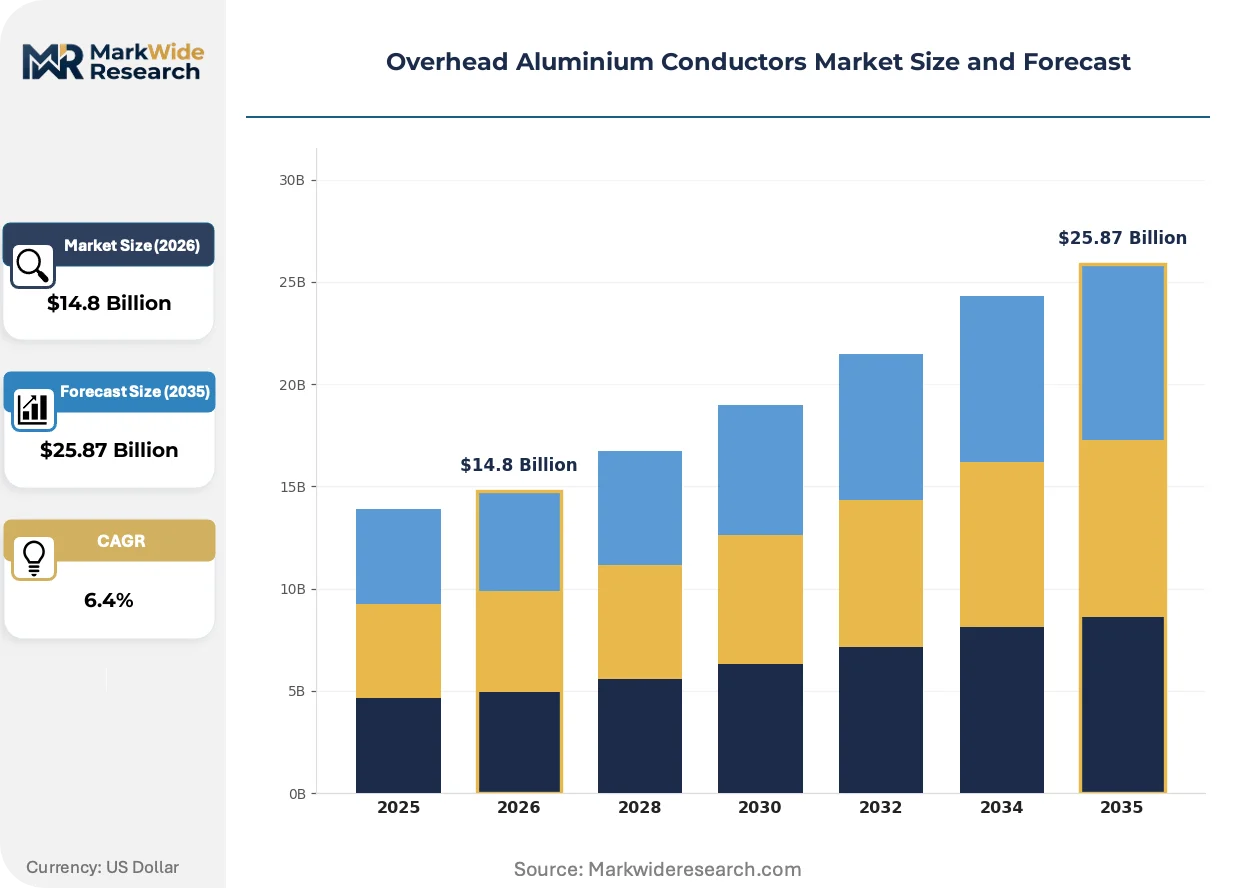
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
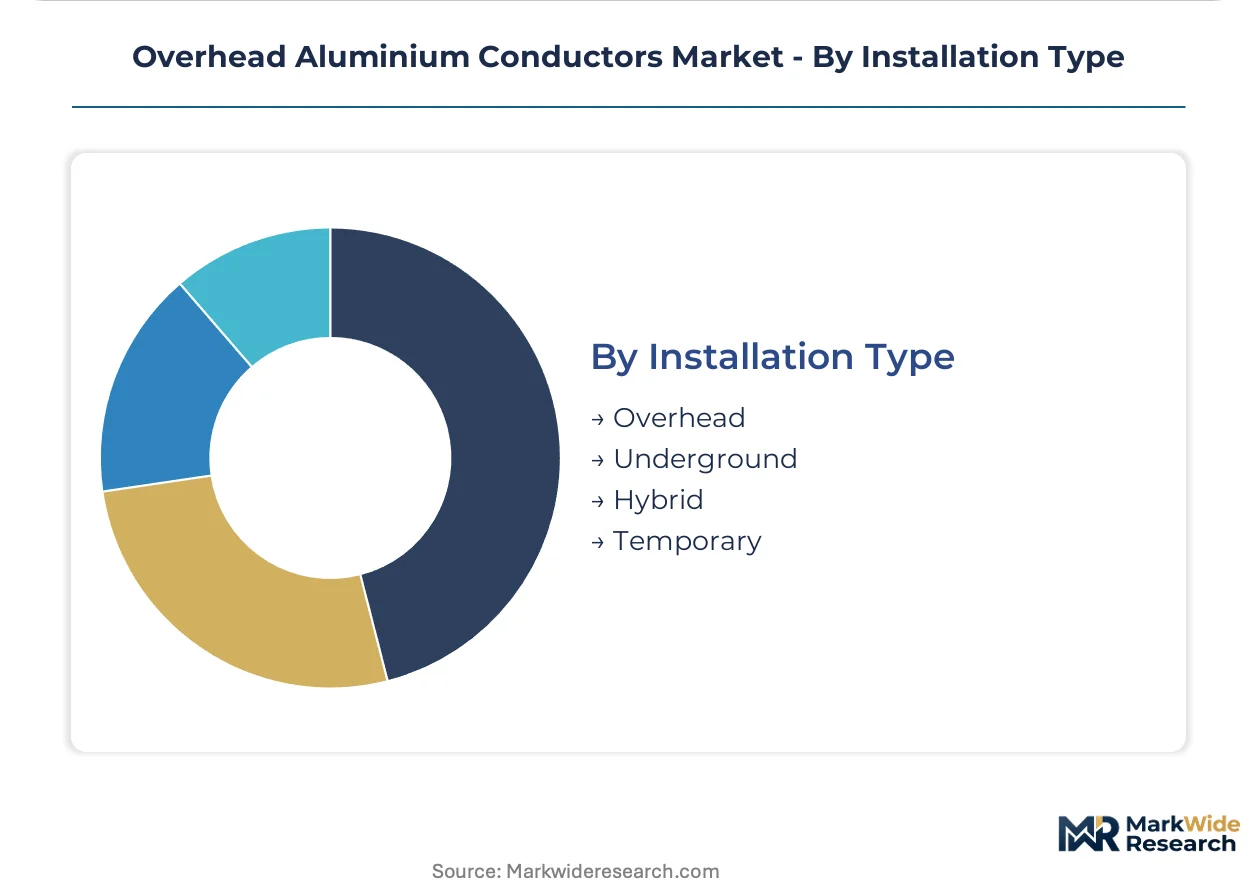
| Segmentation | Product Type: ACSR, AAC, AAAC, ACSR/AS Application: Transmission Lines, Distribution Networks, Power Grids, Renewable Energy End User: Utilities, Industrial, Construction, Telecommunications Installation Type: Overhead, Underground, Hybrid, Temporary |
| Companies Covered | Prysmian Group, Nexans, Southwire Company, Sumitomo Electric Industries, Apar Industries, Sterlite Power, ZTT, LS Cable & System, Oman Cables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Aluminium Conductors Market Trends and Innovations
Conductor technology evolution is bifurcating procurement specifications between legacy grid replacement and renewable export infrastructure, with thermal performance thresholds diverging sharply.
HTLS aluminum-zirconium composite core technology is fragmenting the traditional ACSR-versus-AAAC dichotomy by enabling 40–60% ampacity upgrades without tower replacement. European TSOs adopt these designs aggressively for cross-border interconnections. The cost compression against conventional steel-core alternatives is forcing incumbent manufacturers to retool drawing lines or exit thermal-resistant segments entirely.
China's MIIT enforces GB/T 20141 aluminum purity thresholds and mandatory sag-tension modeling protocols that reshape product development roadmaps for licensed producers. These standards propagate through Belt and Road infrastructure finance, conditioning equipment procurement in recipient countries. Southeast Asian utilities now specify Chinese-standard compliance even for non-Chinese contractor awards.
Utility procurement departments now unbundle conductor supply from installation and stringing services, reversing decades of integrated EPC contracting. This disintermediation elevates specialized installation contractors and compresses manufacturer margins through pure-material price competition. India's state transmission utilities exhibit this pattern most visibly, with separate tenders for conductor supply and line construction.
Overhead Aluminium Conductors Market Segmentation
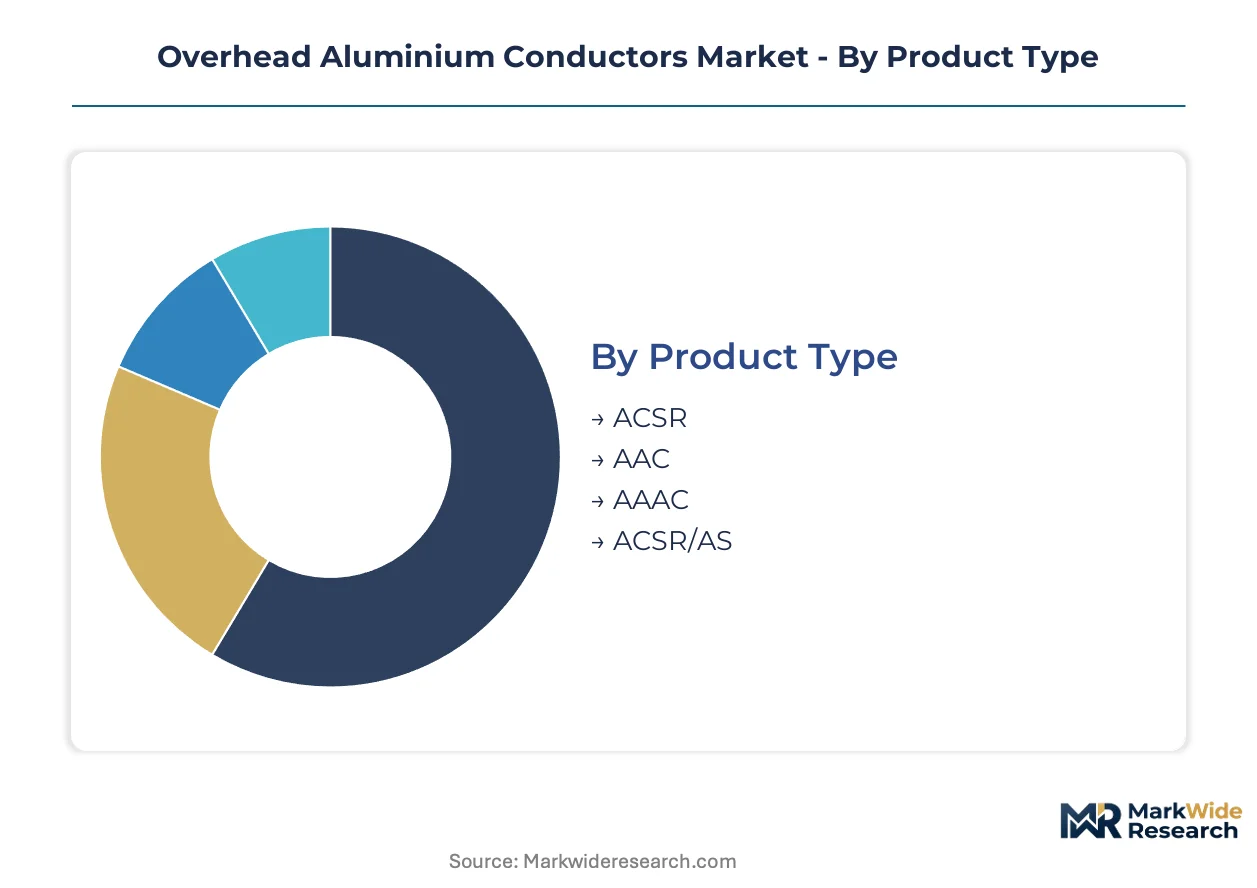
Segmentation in overhead aluminium conductors reveals how procurement channels bifurcate between legacy grid maintenance and renewable infrastructure builds. Product specifications diverge sharply across these channels, with thermal performance thresholds and alloy compositions driving supplier qualification requirements. Understanding these segment flows enables targeted positioning for certified manufacturers against fragmented utility procurement processes.
Product Type:
Channel distribution varies by conductor core technology, with steel-reinforced designs flowing through established utility supply chains while all-alloy variants penetrate coastal replacement markets and renewable export projects.
- ACSR:Aluminum conductor steel-reinforced configurations combine high-purity aluminum filaments with galvanized steel cores for tensile strength exceeding 1,500 MPa. India's Rajasthan and Gujarat renewable corridors deploy ACSR bundles at scale for solar-wind hybrid reconductoring, though steel-core degradation accelerates replacement cycles in coastal environments.
- AAAC:All-aluminum alloy conductors eliminate steel cores through aluminum-magnesium-silicon alloys, delivering superior corrosion resistance and lighter tower loading. Demand concentrates in Maharashtra and Tamil Nadu coastal zones where saline atmosphere degrades galvanized reinforcement, with procurement favoring lifecycle cost over first-cost metrics.
- AAC:All-aluminum conductors serve short-span distribution networks with moderate mechanical loading requirements.
- ACSR/AS:Aluminum-clad steel core variants offer intermediate corrosion protection for moderate coastal exposure zones.
ACSR dominates installed base across interstate transmission corridors. AAAC is where expansion concentrates for corrosion-critical replacement cycles.
Application:
Application segments stratify by project scale and thermal performance requirements, with bulk transmission commanding integrated EPC channels while renewable collector systems favor unbundled procurement.
- Transmission Lines:High-voltage interstate corridors require conductor bundles with ampacity ratings 40–60% above legacy standards. India's CEA mandates BIS IS 398 certification for all interstate projects, compressing market access for uncertified imports and elevating domestic manufacturers through approved channel structures.
- Renewable Energy:Offshore wind export cables and solar farm collector systems demand hybrid conductor designs with 210°C thermal ratings. Southeast Asian utility-scale builds in Vietnam and Thailand lack qualified domestic HTLS suppliers, creating first-mover positioning for certified exporters into these procurement channels.
- Distribution Networks:Medium-voltage urban and rural feeders prioritize cost-optimized ACSR for span distances under 300 meters.
- Power Grids:Integrated grid modernization programs bundle conductor replacement with smart metering infrastructure.
Transmission Lines anchor volume procurement through centralized utility tenders. Renewable Energy is climbing the fastest as hybrid park specifications diverge from legacy standards.
End User:
End user concentration determines contract structure, with utilities maintaining captive procurement departments while industrial and construction segments rely on distributor intermediaries.
- Utilities:State and national transmission utilities unbundle conductor supply from installation services, reversing decades of integrated EPC contracting. India's state transmission utilities exhibit this pattern most visibly, with separate tenders for conductor supply and line construction compressing manufacturer margins through pure-material price competition.
- Industrial:Captive power plants and heavy manufacturing facilities procure through specialized electrical distributors with project engineering support.
- Construction:Greenfield infrastructure developers rely on contractor-procured materials with performance guarantees.
- Telecommunications:Fiber optic ground wire integration drives secondary conductor demand for communication infrastructure.
Utilities dominate contract value through formal tender processes. Industrial procurement is gaining sophistication as captive power operators adopt utility-grade specifications.
Installation Type:
Installation modality shapes logistics requirements and channel partnerships, with overhead deployment leveraging established stringing contractors while underground and hybrid configurations demand specialized civil-electrical coordination.
- Overhead:Conventional tower and pole-mounted installation maintains cost advantage for span distances exceeding 300 meters. Southeast Asian transmission expansion programs in Vietnam and Thailand deploy overhead configurations exclusively, with procurement flowing through regional EPC contractors qualified under Chinese GB/T standards.
- Underground:Urban congestion and aesthetic constraints drive XLPE-insulated cable substitution for conductor in dense metropolitan zones.
- Hybrid:Mixed overhead-underground routing addresses right-of-way restrictions in peri-urban corridors.
- Temporary:Construction power and event infrastructure utilizes lightweight AAC for rapid deployment and recovery.
Overhead configurations retain cost leadership for bulk transmission. Underground installation is expanding most quickly in metropolitan densification zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for drawn aluminum wire and stranded conductors clusters in China, India, and select European industrial zones. These production hubs feed transmission buildouts across their respective spheres of commercial influence. Regulatory divergence on alloy purity and thermal testing protocols fragments qualification pathways for cross-border suppliers.
China
MIIT-licensed producers under GB/T 1179 and GB/T 20141 standards dominate domestic procurement and Belt and Road equipment exports. The Yangtze River Delta concentration supplies thermal-resistant alloy conductors to Southeast Asian transmission programs. ZTT and other licensed fabricators propagate Chinese standard compliance as a condition of project finance in recipient countries.
India
Rajasthan and Gujarat renewable corridors drive reconductoring demand for high-capacity bundles in solar-wind hybrid parks. CEA mandates BIS IS 398 certification for all interstate transmission projects, compressing market access timelines for uncertified imports. Apar Industries and Sterlite Power anchor domestic manufacturing capacity in Maharashtra and Tamil Nadu coastal zones.
United States
Utility-scale transmission upgrades across Texas and the Southwest prioritize integrated rod-to-conductor supply chains. FERC interconnection queue reforms accelerate procurement cycles for high-ampacity line designs. Southwire Company anchors southeastern manufacturing clusters serving regional transmission organizations and municipal utilities.
Germany
Cross-border grid interconnections through the Mediterranean corridor absorb HTLS output from European cable manufacturers. EU F-Gas Regulation restrictions on sulfur hexafluoride-dependent switchgear push TSOs toward higher-ampacity lines reducing substation count. Prysmian Group leverages continental manufacturing footprints for thermal-resistant alloy supply.
Vietnam
Utility-scale transmission expansion programs lack qualified domestic HTLS suppliers, creating import dependency for thermal-resistant specifications. Chinese GB standard compliance conditions equipment procurement through Belt and Road infrastructure finance. Northern provinces including Thai Binh and Ha Nam concentrate overhead line construction activity.
Overhead Aluminium Conductors Market Competitive Landscape
Concentration sits with vertically integrated cable specialists and regional rod-to-conductor manufacturers. The competitive structure bifurcates between European multinationals with HTLS technology leadership and Asian producers with cost-optimized ACSR scale. Three archetypes dominate: integrated energy cable conglomerates, national champions serving protected domestic markets, and specialized conductors pure-plays. Capacity expansion and certification pre-positioning constitute the dominant competitive moves as procurement unbundling compresses pure-material margins.
Within the integrated cable conglomerate tier, Prysmian Group and Nexans exemplify European technology leadership in thermal-resistant alloys and HTLS designs. Apar Industries represents the national champion archetype, anchoring Indian domestic supply under BIS certification mandates. Southwire Company occupies the North American position through captive aluminum rod supply and utility procurement relationships. These three anchors illustrate how geographic certification requirements and vertical integration depth stratify competitive positioning across regional markets.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Sumitomo Electric Industries |
| Apar Industries |
| Sterlite Power |
| ZTT |
| LS Cable & System |
| Oman Cables |
| Others |
Pricing and Supply Chain Analysis
HTLS aluminum-zirconium composite core substitution for galvanized steel reinforcement simultaneously redraws manufacturing geography toward MIIT-licensed Chinese producers and compresses cost premiums across procurement tiers, eroding margin buffers for incumbent ACSR specialists.
Pricing Analysis
BIS IS 398 certification mandates dictate the pricing tier structure across Indian interstate transmission procurement, separating BIS-approved domestic manufacturers from import-dependent competitors. Three-tier pricing structure across premium HTLS, standard ACSR, and economy AAC levels reflects certification grade and thermal performance thresholds. Cost compression in standard ACSR bundles is intensifying because procurement unbundling separates material supply from installation services. State transmission utilities exhibit highest price sensitivity through pure-material tender formats, while offshore wind developers show lowest sensitivity due to lifecycle ampacity requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Southeast Asian transmission builds, creating logistical exposure for aluminum rod shipments from Chinese smelters. Manufacturing gravity centers on China, India, and Germany, with primary aluminum ingot, aluminum-zirconium master alloy, and galvanized steel wire drawing from concentrated upstream sources. Single-source vulnerability sits with MIIT-licensed thermal-resistant alloy supply for Belt and Road projects. Distribution runs through regional EPC contractors qualified under Chinese GB/T standards or Indian BIS protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement unbundling across utility tenders fragments contract structures, creating specialist niches for certified pure-play manufacturers and independent installation contractors.
For Market Incumbents: Fortify backward integration into aluminum rod casting to defend margin compression from London Metal Exchange volatility. Anchor captive supply relationships with low-carbon smelters ahead of EU carbon-border adjustment scope expansion. Prioritize BIS IS 398 and GB/T 20141 certification maintenance as procurement gates tighten. For New Entrants and Emerging Players: Anchor in Vietnam and Thailand transmission expansion corridors where qualified domestic HTLS suppliers remain absent. Target thermal-resistant alloy segments for offshore wind export cable specifications. Pursue Chinese GB standard compliance as a go-to-market prerequisite for Belt and Road financed projects. For Investors and Strategic Acquirers: EU F-Gas Regulation implementation reshapes the acquisition landscape by elevating high-ampacity conductor demand and reducing substation-dependent switchgear exposure. Mid-term viability through the next decade rests on positioning for HTLS technology convergence rather than legacy ACSR scale. Monitor aluminum-zirconium alloy R&D intensity as an inflection signal for competitive technology leadership.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | BIS IS 398 and GB/T 20141 compliance secures access to Indian interstate and Belt and Road procurement channels. |
| Green Smelter Partnership | Low-carbon aluminum rod sourcing aligns conductor supply with EU carbon-border adjustment mechanism requirements. |
| HTLS Capacity Buildout | Thermal-resistant alloy drawing lines capture reconductoring demand from Rajasthan and Gujarat renewable corridors. |
| Installation Service Unbundling | Pure-material positioning responds to Indian state utility tender separation of conductor supply from line construction. |
| Aluminum-Zirconium R&D Investment | 210°C operating temperature designs penetrate offshore wind export cable specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with transmission utility procurement officers, EPC contractor project managers, and conductor manufacturing plant directors; and secondary validation through BIS certification registries, CEA interstate project approvals, MIIT licensing databases, and London Metal Exchange aluminum price series. Bottom-up volume estimates from project-level transmission line awards triangulated against top-down market sizing from national grid expansion programs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning conductor core technology, thermal performance tier, application channel, and regional regulatory cluster. CAGRs derived from utility capital expenditure trajectories and renewable interconnection queue data, with aluminum rod input cost assumptions and certification timeline compression factored as sensitivity variables.
Decision-makers should treat outputs as directional under base assumptions of sustained Indian renewable corridor buildout and Chinese standard propagation through Belt and Road finance; material deviation in LME aluminum volatility or certification capacity constraints would warrant model refresh. Practitioners should keep alternative scenarios live as EU carbon-border adjustment scope and F-Gas Regulation enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market