
 Portugal Wind Energy Market | 2026-2036
Portugal Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Wind Energy Market Analytics
Long-term operations and maintenance contracting is consolidating how turbine capacity gets monetized across Portugal's wind fleet. EDP Renováveis leverages its scale to secure multi-decade service agreements covering onshore and offshore assets. Iberdrola Renovables Portugal anchors its position through integrated project development from site origination to grid connection. Siemens Gamesa Renewable Energy specializes in blade technology and digital monitoring systems that reduce unplanned downtime.
Portugal wind energy encompasses the harnessing of kinetic wind resources through rotating turbine assemblies to generate electrical power, with modern installations reaching hub heights above 120 meters and rotor diameters exceeding 160 meters to capture stronger, more consistent air streams at altitude. The primary purpose is grid-scale electricity supply for national consumption and export to interconnected European markets. Onshore turbines still dominate installed capacity, though floating wind systems represent the fastest-expanding technology segment as Portugal develops deep-water sites off the Atlantic coast. Utility companies constitute the largest end user category by volume, while independent power producers capture disproportionate margin pools through merchant exposure and bilateral offtake structures.
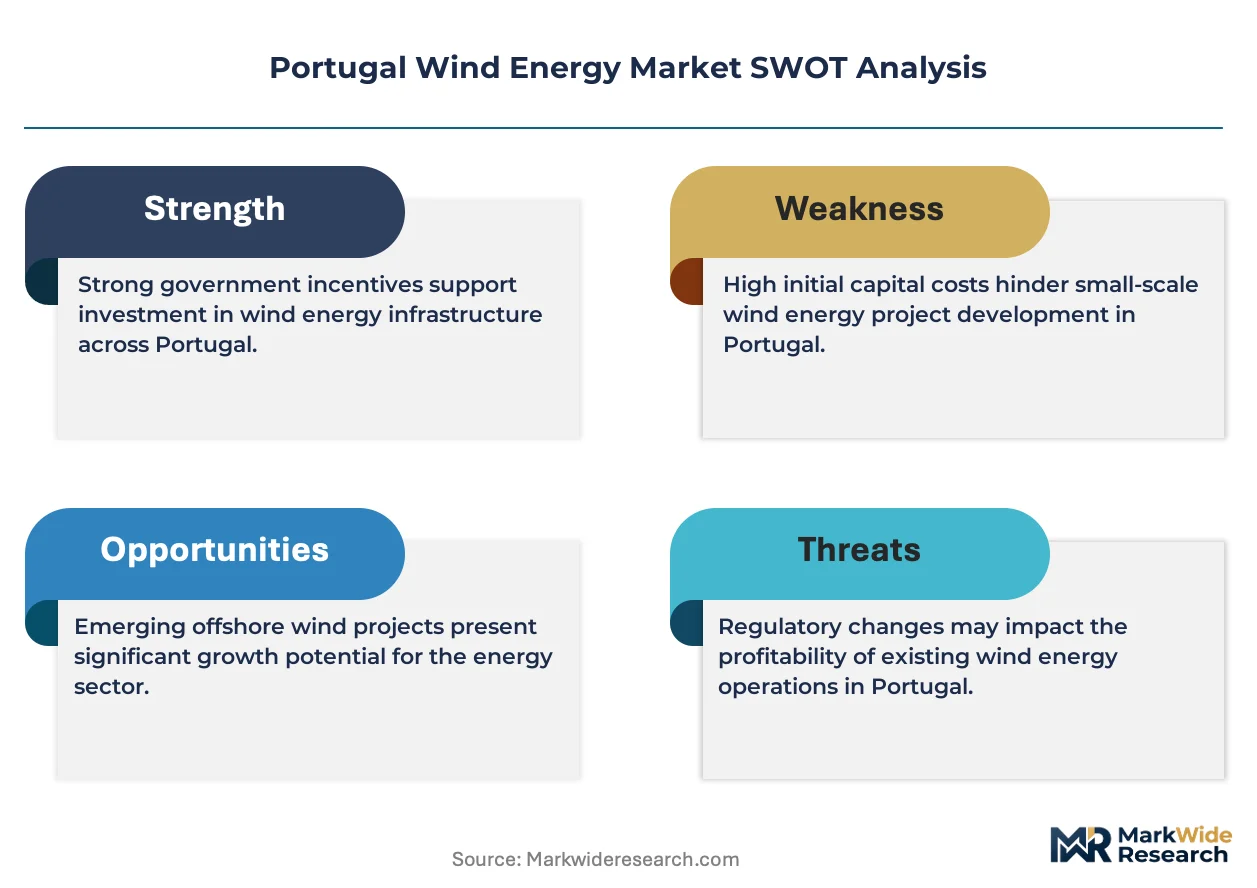
DGEG, Portugal's energy and geology directorate, administers concession licensing and environmental permitting for wind developments, while REN manages grid integration standards and transmission access protocols. EU Green Deal targets and the national carbon neutrality roadmap mandate renewable expansion, directly shaping auction design and permitting timelines. The Recovery and Resilience Plan channels structural funds into grid reinforcement and port infrastructure essential for offshore logistics. Stakeholders must monitor floating wind demonstration results and evolving auction price floors to calibrate capital allocation between established onshore sites and higher-risk offshore opportunities.
Market Dynamics
Floating offshore wind technology is absorbing capital allocation from established onshore sites as developers pursue deeper Atlantic waters beyond fixed-foundation limits. The EU Green Deal mandates and Portugal's Recovery and Resilience Plan channel public financing toward port infrastructure and grid reinforcement that enables this technology shift.
Growth Catalysts
- Recovery and Resilience Plan auctions:The EU structural fund framework mandates renewable energy concession rounds with price floors that de-risk developer capital commitment for floating wind demonstration projects.
- Grid interconnection expansion:REN's transmission access protocols prioritize renewable capacity zones in northern and central coastal regions where wind shear coefficients exceed national averages.
- Blade manufacturing localization:Port of Leixões and Port of Sines infrastructure investments are absorbing nacelle assembly and blade logistics functions previously concentrated in northern European facilities.
Market Restraints
- Steel and rare earth input volatility:Turbine tower and permanent magnet supply chains face price pressure from concentrated Chinese processing capacity for neodymium and dysprosium.
- Environmental licensing duration:DGEG concession timelines and ICNF biodiversity assessments create 18-36 month permitting friction for onshore sites in Natura 2000 zones.
- Grid curtailment risk:REN's transmission reinforcement lag in Alentejo and interior Centro regions forces output throttling during high-generation periods.
Strategic Opportunities
- Floating foundation supply chain:Portuguese shipyards and maritime engineering firms can capture semisubmersible platform fabrication from technology licensors targeting Iberian Atlantic depths.
- Green hydrogen offtake integration:Electrolyzer co-location at port industrial clusters creates captive demand for otherwise curtailed offshore generation during low-price hours.
- Corporate PPA origination:Energy-intensive manufacturing in Porto and Aveiro industrial corridors seeks direct bilateral contracts bypassing utility intermediation.
Industry Challenges
- Floating wind installation vessel scarcity:Heavy-lift jack-up and dynamic positioning vessel availability constrains project sequencing during narrow Atlantic weather windows.
- SCADA and digital twin skill gaps:Turbine OEMs and independent service providers compete for limited Portuguese talent pools in predictive analytics and remote diagnostics engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Wind Energy Market |
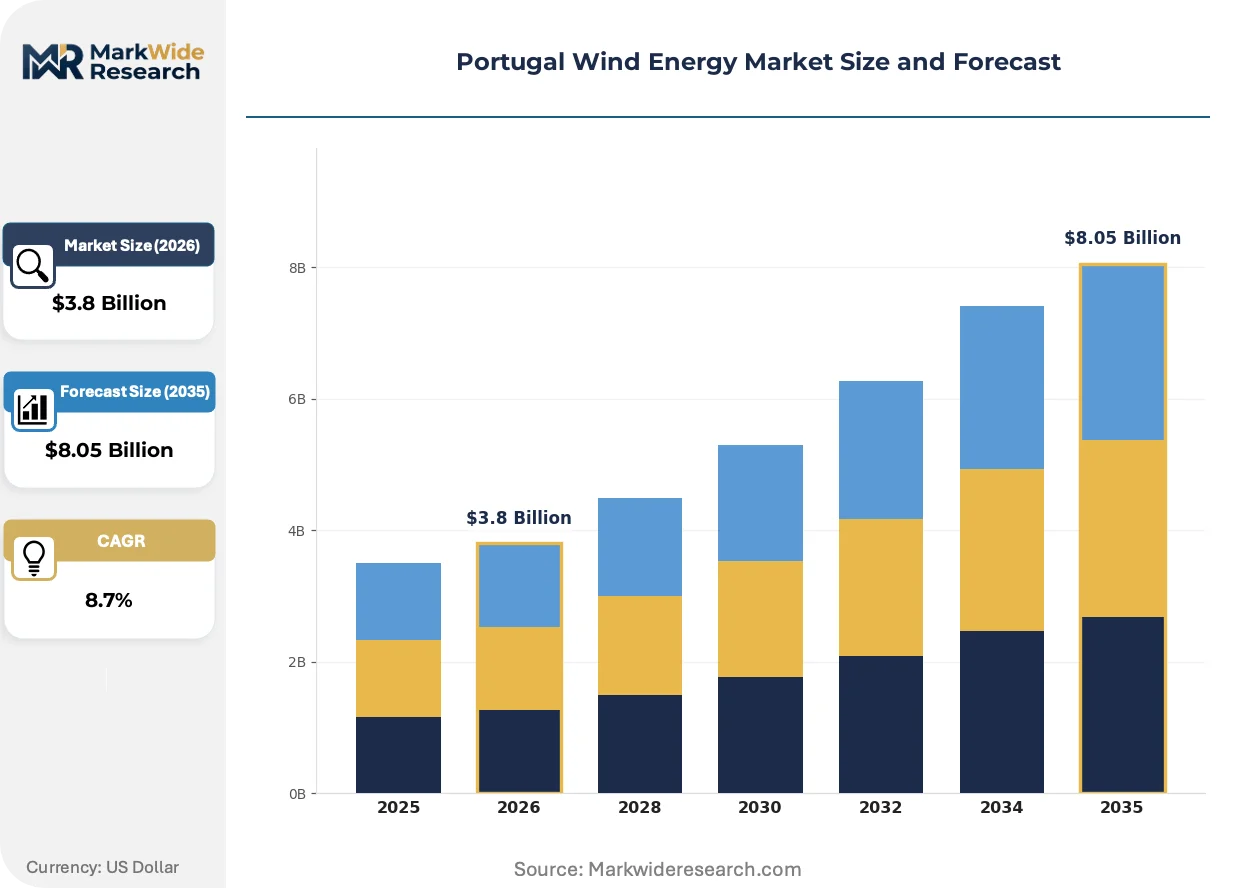
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore Turbines, Offshore Turbines, Floating Wind Systems, Vertical Axis Application: Power Generation, Grid Integration, Distributed Generation, Energy Storage End User: Utility Companies, Independent Power Producers, Government Agencies, Commercial Users Deployment: Project Development, Operations & Maintenance, Retrofitting, Consulting Services |
| Companies Covered | EDP Renováveis, Iberdrola Renovables Portugal, Finerge, Ocean Winds, Siemens Gamesa Renewable Energy, Vestas Wind Systems A/S, Greenvolt, Voltalia Portugal, Ørsted, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Wind Energy Market Evolving Landscape
Portugal's wind sector is absorbing capital reallocation toward floating platform demonstration as fixed-bottom site saturation intensifies land-use conflict. Technology convergence between maritime engineering and turbine system integration is compressing development timelines for deep-water deployment.
Direct-drive permanent magnet generators are absorbing market share from geared drivetrain architectures in offshore specifications above 12 MW. EDP Renováveis and international developers specify these systems for floating platforms where nacelle weight reduction improves platform stability. The technology is absorbing service contract value toward magnetic component replacement cycles rather than gearbox overhaul intervals.
EU Green Deal implementation through Portugal's national carbon neutrality roadmap is mandating auction price floors that compress developer margin risk. DGEG concession design now requires supply-chain localization commitments that reshape component sourcing patterns. Offshore floating segments face the steepest compliance thresholds, forcing joint venture structures with domestic maritime fabricators.
Utility procurement departments are unbundling long-term service agreements from initial equipment supply contracts. Independent power producers and merchant exposure seekers now specify aftermarket competition clauses that fragment OEM captive service revenue. This pattern concentrates in northern Portugal's established onshore fleet where turbine aging creates predictable maintenance demand.
Portugal Wind Energy Market Segmentation
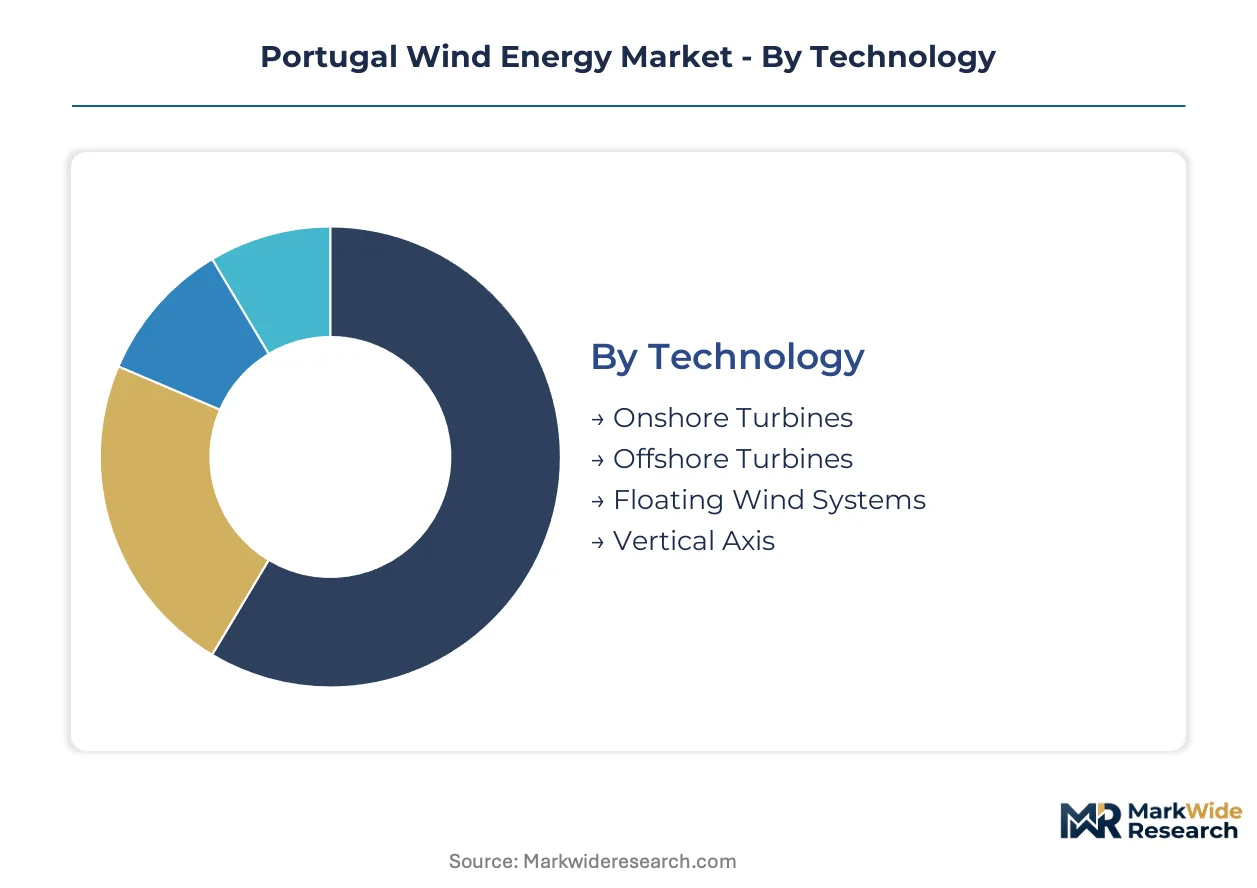
Segmentation in Portugal's wind energy market reveals how capital allocation shifts between mature onshore infrastructure and emerging floating platforms. Understanding these divisions helps stakeholders calibrate investment timelines against technology readiness and regulatory support intensity.
Technology:
Standalone turbine architectures dominate current installations, while integrated floating systems require maritime engineering convergence.
- Onshore Turbines:Fixed-foundation horizontal-axis systems with hub heights exceeding 120 meters and rotor diameters above 160 meters capture stronger air streams at altitude. Northern and central coastal zones concentrate demand where wind shear coefficients exceed national averages and grid interconnection protocols from REN prioritize renewable access.
- Offshore Turbines:Fixed-bottom installations in shallow Atlantic waters up to 60 meters depth anchor near-term capacity expansion. Port of Sines infrastructure investments absorb nacelle assembly functions, though installation vessel scarcity constrains project sequencing during narrow weather windows.
- Floating Wind Systems:Semisubmersible platforms enabling deployment beyond fixed-foundation limits represent the steepest expansion trajectory in Portuguese waters.
- Vertical Axis:Omnidirectional rotor designs suit distributed generation niches with lower wind speed thresholds.
Volume placements concentrate in Onshore Turbines; the faster expansion belongs to Floating Wind Systems.
Application:
Grid-facing applications absorb the largest capital commitments, while behind-the-meter configurations serve residual demand.
- Power Generation:Utility-scale electricity production for national consumption and export to interconnected European markets. EDP Renováveis and Iberdrola Renovables Portugal anchor procurement through auction mechanisms under the Recovery and Resilience Plan framework with mandated price floors.
- Grid Integration:Transmission access protocols and interconnection standards managed by REN shape renewable zone prioritization. Northern and central coastal regions receive preferential treatment where reinforcement timelines align with generation capacity.
- Distributed Generation:Smaller-scale installations bypassing centralized transmission infrastructure serve industrial corridors.
- Energy Storage:Co-located battery systems and green hydrogen electrolyzers absorb otherwise curtailed output during low-price hours.
Capital deployment clusters in Power Generation; Grid Integration commands the premium pricing tier for access certainty.
End User:
Volume buyers structure long-term procurement, while merchant exposure seekers capture asymmetric margin opportunities.
- Utility Companies:EDP Renováveis and integrated national operators dominate procurement through multi-decade concession agreements. DGEG auction design under EU Green Deal mandates channels structural funds toward de-risked developer commitments.
- Independent Power Producers:Merchant exposure and bilateral offtake structures enable disproportionate margin capture. Corporate PPA origination in Porto and Aveiro industrial corridors bypasses utility intermediation for energy-intensive manufacturing.
- Government Agencies:Public sector procurement supports demonstration projects and research infrastructure.
- Commercial Users:Direct bilateral contracting from manufacturing and data center operators grows with sustainability commitments.
Contract volume concentrates with Utility Companies; margin expansion favors Independent Power Producers.
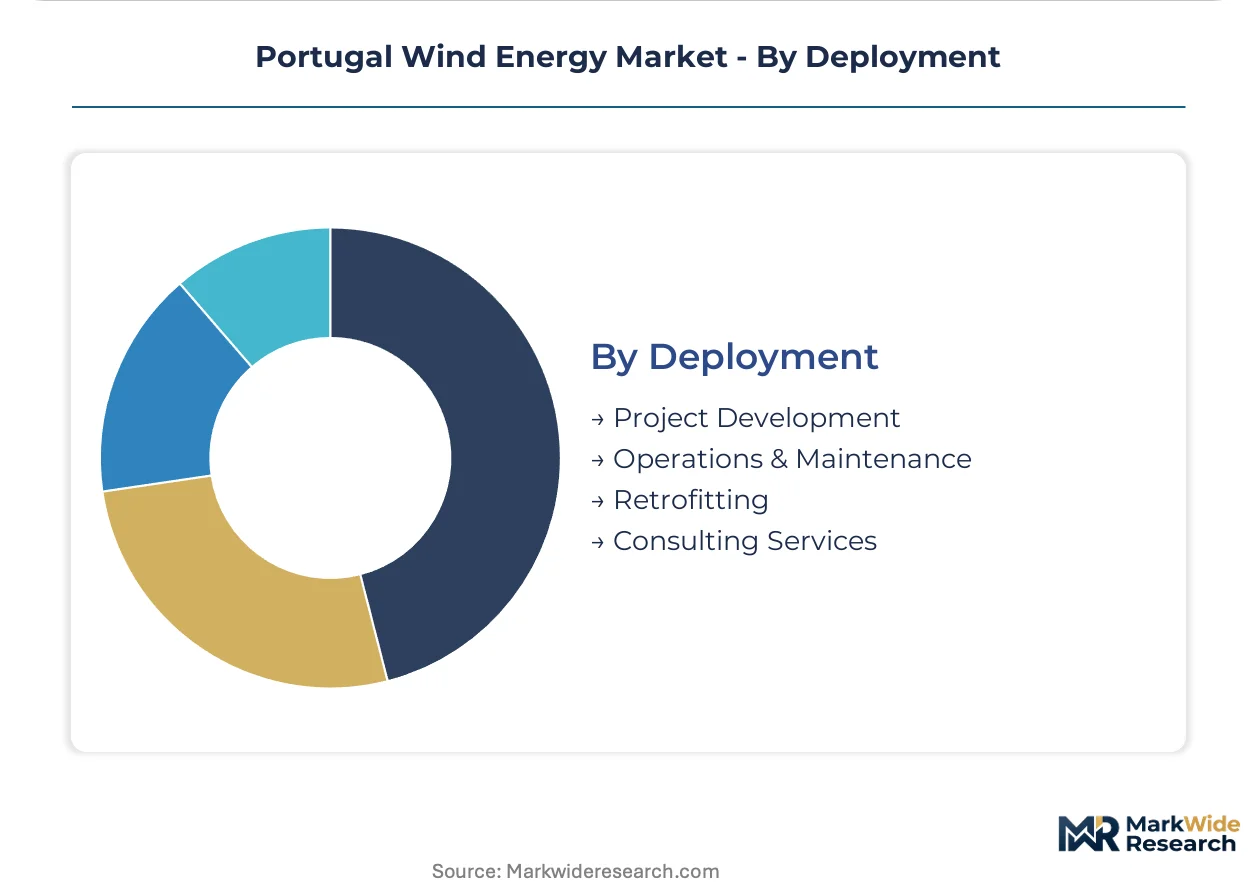
Deployment:
Initial capital deployment differs materially from recurring revenue streams in operational phases.
- Project Development:Site origination through grid connection spans 18-36 month permitting friction in Natura 2000 zones. ICNF biodiversity assessments and DGEG concession licensing create timeline uncertainty that shapes joint venture structures with domestic fabricators.
- Operations & Maintenance:Long-term service agreements consolidate turbine fleet monetization. Independent power producers now specify aftermarket competition clauses that fragment OEM captive revenue in northern Portugal's aging onshore fleet.
- Retrofitting:Blade extension and control system upgrades extend asset life in mature installations.
- Consulting Services:Environmental permitting and maritime engineering advisory supports floating platform development.
Revenue stability concentrates in Operations & Maintenance; growth investment flows toward Project Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porto anchors Portugal's wind energy industrial corridor, with the Port of Leixões absorbing nacelle assembly and blade logistics functions. The northern and central coastal zones concentrate development where wind shear coefficients exceed national averages and REN transmission protocols prioritize renewable access.
Northern Portugal
Industrial manufacturing in Porto and Aveiro drives corporate PPA demand for direct bilateral contracting. DGEG concession licensing under the Recovery and Resilience Plan channels EU structural funds toward grid reinforcement in this zone. The Port of Leixões infrastructure investments enable blade manufacturing localization previously concentrated in northern European facilities.
Central Portugal
Coastal wind resources with consistent Atlantic air streams attract utility-scale project development from EDP Renováveis and Iberdrola. ICNF biodiversity assessments create 18-36 month permitting friction for onshore sites in Natura 2000 zones. The Coimbra-Leiria corridor hosts established onshore turbine fleets where independent power producers now specify aftermarket competition clauses.
Alentejo
Interior wind sites face grid curtailment risk as REN transmission reinforcement lags behind generation capacity installation. The region's solar-wind hybrid potential attracts merchant exposure seekers pursuing diversified renewable portfolios. Évora and Beja industrial zones remain underpenetrated for direct corporate offtake structures.
Lisbon Metropolitan Area
Administrative concentration of DGEG and REN headquarters shapes regulatory interpretation and grid access protocol development. The Port of Sines anchors offshore logistics infrastructure for floating wind demonstration projects. Maritime engineering firms in Setúbal cluster around semisubmersible platform fabrication opportunities.
Portugal Wind Energy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Portugal's wind energy value chain. Utility-affiliated developers with captive balance sheets dominate auction procurement through multi-decade concession agreements. Independent power producers and merchant exposure seekers occupy asymmetric margin positions through bilateral offtake structures. Technology licensors and component suppliers fragment across blade manufacturing, nacelle assembly, and digital monitoring systems. Dominant competitive moves include joint venture formations with domestic maritime fabricators and unbundling of long-term service agreements from initial equipment supply contracts.
Among Iberian utility-affiliated developers, EDP Renováveis and Iberdrola Renovables Portugal exemplify the integrated project development archetype spanning site origination through grid connection. Siemens Gamesa Renewable Energy occupies a position within the technology supply tier, representing turbine OEMs specializing in blade systems and digital monitoring platforms. These three anchors illustrate how scale-driven concession holders and specialized equipment providers coexist within Portugal's auction-driven market structure.
| Leading Market Players |
|---|
| EDP Renováveis |
| Iberdrola Renovables Portugal |
| Finerge |
| Ocean Winds |
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems A/S |
| Greenvolt |
| Voltalia Portugal |
| Ørsted |
| Others |
Value Network & Pricing Analysis
Offshore-to-onshore performance divergence in turbine output capacity manifests in contract pricing spreads exceeding 40 percent, with floating platform premiums reflecting both technology immaturity and concentrated Portuguese maritime fabrication capacity. EU Green Deal auction price floors compress developer margins while channeling procurement toward domestic supply-chain localization commitments at Port of Sines and Port of Leixões.
Pricing Analysis
Cost-down pressure on floating wind developers accelerates because DGEG auction design mandates supply-chain localization that forces joint venture structures with domestic fabricators. Three-tier pricing structure across premium offshore floating, standard fixed-bottom, and economy onshore repowering segments reflects technology readiness and installation risk. Premium tiers absorb permanent magnet generator specifications and dynamic positioning vessel scarcity, while standard onshore segments face price erosion from aging fleet aftermarket competition. Utility procurement departments exhibit lowest price sensitivity given captive balance sheet capacity, whereas independent power producers negotiate aggressively on service unbundling clauses.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale turbine demand from EDP Renováveis and Iberdrola, while project developers source semisubmersible platforms through technology licensors with Portuguese shipyard partnerships. Component manufacturing concentrates in Spain, Germany, and Denmark for nacelle assembly and blade systems, with Chinese processing capacity dominating neodymium and dysprosium permanent magnet supply. Steel tower fabrication and rare earth magnet procurement face commodity price volatility from concentrated upstream refining. Distribution runs through port infrastructure investments at Leixões and Sines that absorb logistics functions previously concentrated in northern European facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portugal's wind sector sits in a technology-transition phase where floating offshore platforms displace fixed-bottom architectures in Atlantic depths beyond 60 meters. This shift restructures capital allocation, supply-chain localization requirements, and service contract unbundling across the value chain.
For Market Incumbents: Anticipate floating wind installation vessel scarcity constraining project sequencing during narrow Atlantic weather windows by securing multi-year charter agreements with North Sea operators. Consolidate aftermarket service revenue through predictive analytics platforms that reduce unplanned downtime for aging northern Portugal onshore fleets, countering independent power producer demands for competition clauses. For New Entrants and Emerging Players: EU Green Deal implementation in Portugal opens a window for corporate PPA origination in Porto and Aveiro industrial corridors, where energy-intensive manufacturing seeks direct bilateral contracts bypassing utility intermediation. Target green hydrogen electrolyzer co-location at port industrial clusters as the most penetrable application, leveraging captive demand for otherwise curtailed offshore generation during low-price hours. For Investors and Strategic Acquirers: Re-rating potential sits with independent power producers possessing merchant exposure and bilateral offtake structures given asymmetric margin capture in auction-exposed markets. Monitor floating wind demonstration results at Portuguese Atlantic test sites as the specific signal indicating technology readiness for capital-scale deployment across Iberian deep-water zones.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Supply Chain Localization | Portuguese shipyard partnerships with technology licensors capture semisubmersible fabrication from Iberian Atlantic projects. |
| Corporate PPA Origination | Direct bilateral contracts with Porto and Aveiro manufacturing bypass utility intermediation for energy-intensive consumers. |
| Service Agreement Unbundling | Aftermarket competition clauses fragment OEM captive revenue in northern Portugal's aging onshore turbine fleet. |
| Green Hydrogen Integration | Electrolyzer co-location at Sines and Leixões industrial clusters creates captive demand for curtailed offshore output. |
| Grid Reinforcement Alignment | REN transmission access protocols prioritize northern and central coastal zones where wind shear coefficients exceed national averages. |
Research Methodology
Multi-period observation of DGEG concession licensing timelines, REN grid interconnection protocols, and floating wind demonstration milestones anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and maritime engineering specialists. Secondary validation drew from EU Recovery and Resilience Plan disbursement records, IEA renewable energy reports, FERC-equivalent transmission filings, and port infrastructure investment disclosures. Bottom-up project pipeline tracking and top-down auction capacity allocation triangulated market sizing across the analysis window.
Segment-weighting approaches distributed value and volume across technology tiers, application categories, end-user procurement archetypes, and deployment phases. The analytical framework modeled onshore turbine repowering, fixed-bottom offshore expansion, and floating platform demonstration as distinct growth trajectories over the projection horizon. CAGRs derived from capacity installation schedules, auction price floor evolution, and grid reinforcement timeline alignment. Industry-specific inputs included wind shear coefficient mapping, installation vessel availability curves, and permanent magnet supply chain concentration metrics.
The model assumes a particular technology adoption path; alternative pathways for floating platform commercialization would alter the outlook if semisubmersible designs fail to achieve cost parity with fixed-bottom systems. Forecasts reflect base-case assumptions regarding EU structural fund disbursement continuity and DGEG permitting timeline compression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Floating Wind Turbine Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market