
 Netherlands Solar Energy Market | 2026-2036
Netherlands Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Solar Energy Market Foresight
Utility-scale buyers are unwinding the historical dominance of residential rooftop installations in Dutch solar deployment. Vattenfall AB leverages its offshore wind heritage to anchor integrated renewable portfolios across the Netherlands. Shell plc competes through downstream energy trading capabilities that monetize solar output volatility. Solarfields Nederland BV specializes in agrivoltaic project development, occupying a niche between agricultural land use and energy generation.
Netherlands solar energy encompasses photovoltaic systems converting sunlight into electricity through semiconductor junctions, typically silicon-based cells with conversion efficiencies ranging from twenty to twenty-two percent for commercial monocrystalline modules. These installations feed into the Dutch low-voltage distribution network or high-voltage transmission grid, displacing natural gas-fired generation in the national energy mix. Rooftop installations dominate absolute capacity additions due to dense urban land constraints and streamlined municipal permitting. Ground-mounted arrays represent the fastest-expanding segment as agricultural cooperatives lease fields for solar park development. Bifacial technology leads module selection for utility projects, capturing reflected irradiance from Dutch flat terrain to boost yield.
The Netherlands Enterprise Agency implements the SDE++ subsidy scheme, conditioning financial support on projects meeting EU Green Deal carbon reduction benchmarks. Net metering regulations from the Dutch Authority for Consumers and Markets shape residential payback calculations and inverter sizing decisions. Stakeholders must monitor grid congestion pricing reforms in high-penetration provinces to determine optimal project locations and battery co-location strategies.
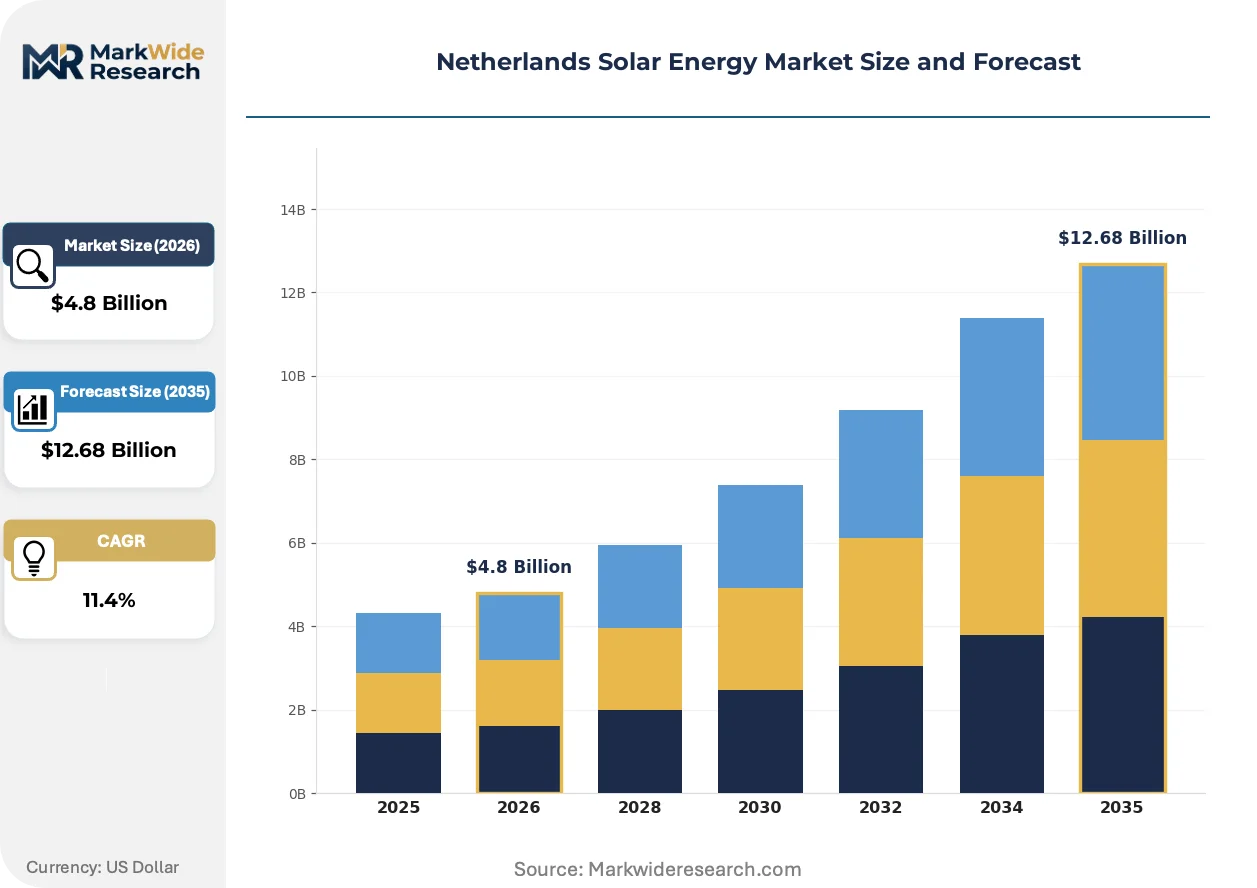
Market Dynamics
Utility-scale solar deployment in the Netherlands is fragmenting the historical residential rooftop dominance as agricultural cooperatives and industrial off-takers secure priority grid access through SDE++ subsidy allocations.
Growth Catalysts
- REPowerEU Acceleration:The EU Green Deal framework has compressed Dutch permitting timelines from eighteen months to under six months for ground-mounted arrays, unlocking stranded agricultural land for solar park development.
- Agrivoltaic Land Use:Dual-use solar installations allow Dutch farmers to maintain crop production beneath elevated bifacial panels, generating lease revenue without sacrificing agricultural output.
- Grid Interconnection Density:North Holland and South Holland provinces host high-voltage substation clusters that reduce transmission upgrade costs for utility-scale developers.
Market Restraints
- Polysilicon Supply Concentration:Dutch project developers remain exposed to Xinjiang-sourced polysilicon supply chain disruptions and associated EU forced labor due diligence requirements.
- Grid Congestion Pricing:The Dutch Authority for Consumers and Markets is implementing locational marginal pricing in high-penetration provinces, eroding project economics for solar parks without battery co-location.
- Land Use Competition:Strict Dutch zoning laws under the Crisis and Recovery Act prioritize food security, limiting available hectares for ground-mounted development relative to rooftop alternatives.
Strategic Opportunities
- Flevoland Province Expansion:Reclaimed polder land with flat topography and existing high-voltage infrastructure offers underpenetrated territory for next-generation agrivoltaic parks.
- Battery-Solar Hybrid Integration:Co-located lithium-ion storage systems qualify for stacked SDE++ subsidies while resolving grid congestion constraints in South Holland distribution networks.
- Corporate PPA Structuring:Dutch data center operators and greenhouse horticulture facilities are signing fifteen-to-twenty-year power purchase agreements, bypassing merchant price exposure.
Industry Challenges
- Electrical Engineering Talent Scarcity:Dutch grid integration specialists command premium wages as project pipelines outpace technical workforce expansion at technical universities.
- Net Metering Phase-Out Execution:The transition from net metering to feed-in tariffs requires residential installers to retrain sales teams on battery sizing and self-consumption optimization.
- Bifacial Performance Validation:Dutch flat terrain albedo conditions vary seasonally, complicating energy yield guarantees and financier due diligence for utility-scale projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Solar Energy Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Mounting Systems, Batteries End User: Residential, Commercial, Industrial, Utilities Installation Type: Rooftop, Ground-mounted, Off-grid, Hybrid Technology: Thin-film, Monocrystalline, Polycrystalline, Bifacial |
| Companies Covered | Chint Solar Netherlands B.V., DMEGC Solar Energy, Solarfields Nederland BV, Sunrock Investment B.V., Orsted A/S, Vattenfall AB, AB Solar Total, Shell plc, BayWa r.e. GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Solar Energy Market Shifts & Advancements
Technology convergence between photovoltaic generation and battery storage is restructuring Dutch project development economics, while regulatory pressure on supply chain transparency forces module sourcing strategy revisions.
Bifacial solar module technology is fragmenting the Dutch utility-scale procurement landscape. These double-sided panels capture reflected irradiance from Dutch flat agricultural terrain, boosting effective yield by eight-to-twelve percent over monofacial equivalents. Agricultural cooperatives in Flevoland and Gelderland are specifying bifacial glass-glass constructions for twenty-five-year durability. This technology is fragmenting incumbent supplier relationships as developers bypass traditional distributors to secure direct factory allocations from Asian manufacturers.
The EU Green Deal's carbon border adjustment mechanism and forced labor due diligence directives are reshaping Dutch module procurement protocols. Project developers must now document supply chain provenance from polysilicon through cell manufacturing to qualify for SDE++ subsidies. Dutch banks are embedding these requirements into project finance covenants, extending due diligence timelines by four-to-six weeks. Utility-scale developers are responding by diversifying sourcing across Southeast Asian cell manufacturing facilities.
Corporate offtake agreements are displacing traditional merchant solar development in Dutch commercial deployment. Greenhouse operators and cold storage logistics firms are negotiating fifteen-year fixed-price contracts directly with project sponsors, bypassing utility intermediaries. This direct contracting model concentrates credit risk assessment capabilities within developer origination teams. The shift is most visible in Westland municipality, where horticulture energy demand density supports dedicated solar park development without grid export requirements.
Netherlands Solar Energy Market Segmentation
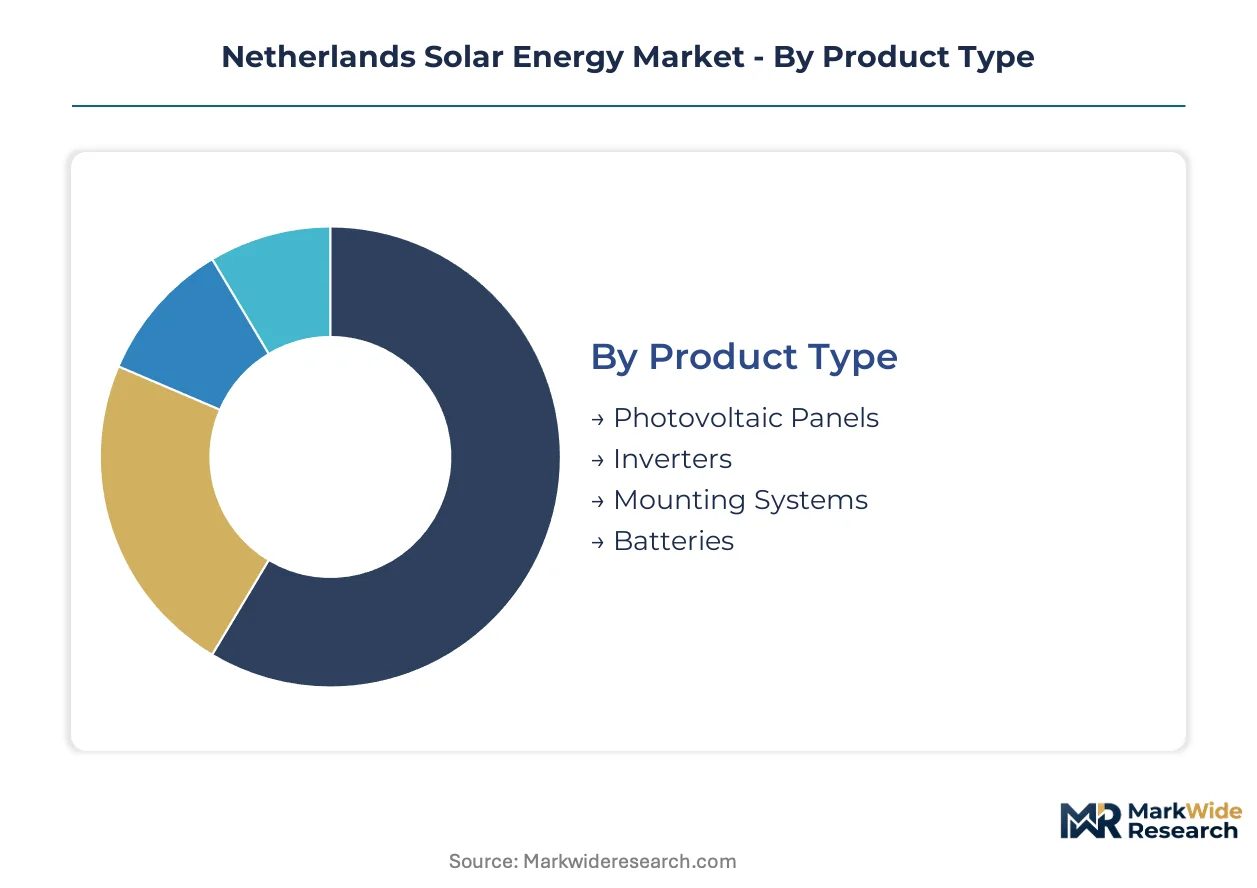
Segmentation reveals how Dutch solar deployment fragments across competing value pools. Technology choices and installation configurations determine subsidy eligibility under SDE++ rules. End-user categories face divergent grid interconnection constraints and permitting pathways.
Product Type:
Margin pools concentrate in power electronics and storage systems rather than commoditized panel supply. Dutch developers prioritize component interoperability to secure SDE++ qualification.
- Photovoltaic Panels:Silicon-based modules with conversion efficiencies ranging from twenty to twenty-two percent for monocrystalline variants. North Holland utility-scale projects specify bifacial glass-glass constructions to capture reflected irradiance from flat agricultural terrain.
- Inverters:Power conversion systems transforming DC panel output to grid-synchronous AC power. String inverters dominate residential rooftop economics in South Holland municipalities where net metering still shapes payback calculations.
- Mounting Systems:Structural hardware securing panels to rooftops or ground foundations. Agricultural cooperatives in Flevoland specify elevated agrivoltaic structures permitting crop cultivation beneath arrays.
- Batteries:Lithium-ion storage systems enabling self-consumption optimization and grid congestion management. Co-located battery-solar hybrids qualify for stacked SDE++ subsidies in high-penetration provinces.
Photovoltaic panels hold installed capacity. Batteries are rotating up the share rankings.
End User:
Customer type determines financing structure and offtake contract sophistication. Industrial buyers command longest contract tenors and direct PPA negotiation leverage.
- Residential:Single-family and multi-unit dwelling owners installing sub-fifteen-kilowatt systems. Streamlined municipal permitting in Dutch urban centers supports rooftop deployment despite net metering phase-out pressures.
- Commercial:Office buildings, retail facilities, and logistics warehouses seeking behind-the-meter generation. Greenhouse horticulture operators in Westland municipality anchor dedicated solar park development without grid export requirements.
- Industrial:Manufacturing facilities and data centers with continuous baseload demand. Dutch cold storage firms negotiate fifteen-to-twenty-year fixed-price contracts bypassing merchant price exposure.
- Utilities:Grid-scale developers and independent power producers securing priority interconnection. Vattenfall AB leverages offshore wind heritage to anchor integrated renewable portfolios across the Netherlands.
Utilities anchor megawatt-scale deployment. Commercial end users are rotating up the share rankings.
Installation Type:
Physical configuration dictates land use permissions and grid connection voltage levels. Rooftop density reflects Dutch urban planning constraints.
- Rooftop:Building-integrated and building-applied systems on residential and commercial structures. Dense urban land constraints in Randstad cities sustain absolute capacity additions despite ground-mounted growth.
- Ground-mounted:Free-field arrays on agricultural land and former industrial sites. REPowerEU permitting reforms compressed Dutch approval timelines from eighteen months to under six months for these installations.
- Off-grid:Standalone systems without utility interconnection serving remote facilities. Limited Dutch territory lacks grid access, constraining this segment to specialized agricultural and recreational applications.
- Hybrid:Integrated solar-plus-storage configurations optimizing self-consumption and grid services. Battery co-location resolves congestion pricing erosion in South Holland distribution networks.
Rooftop systems hold installed capacity. Ground-mounted arrays are rotating up the share rankings.
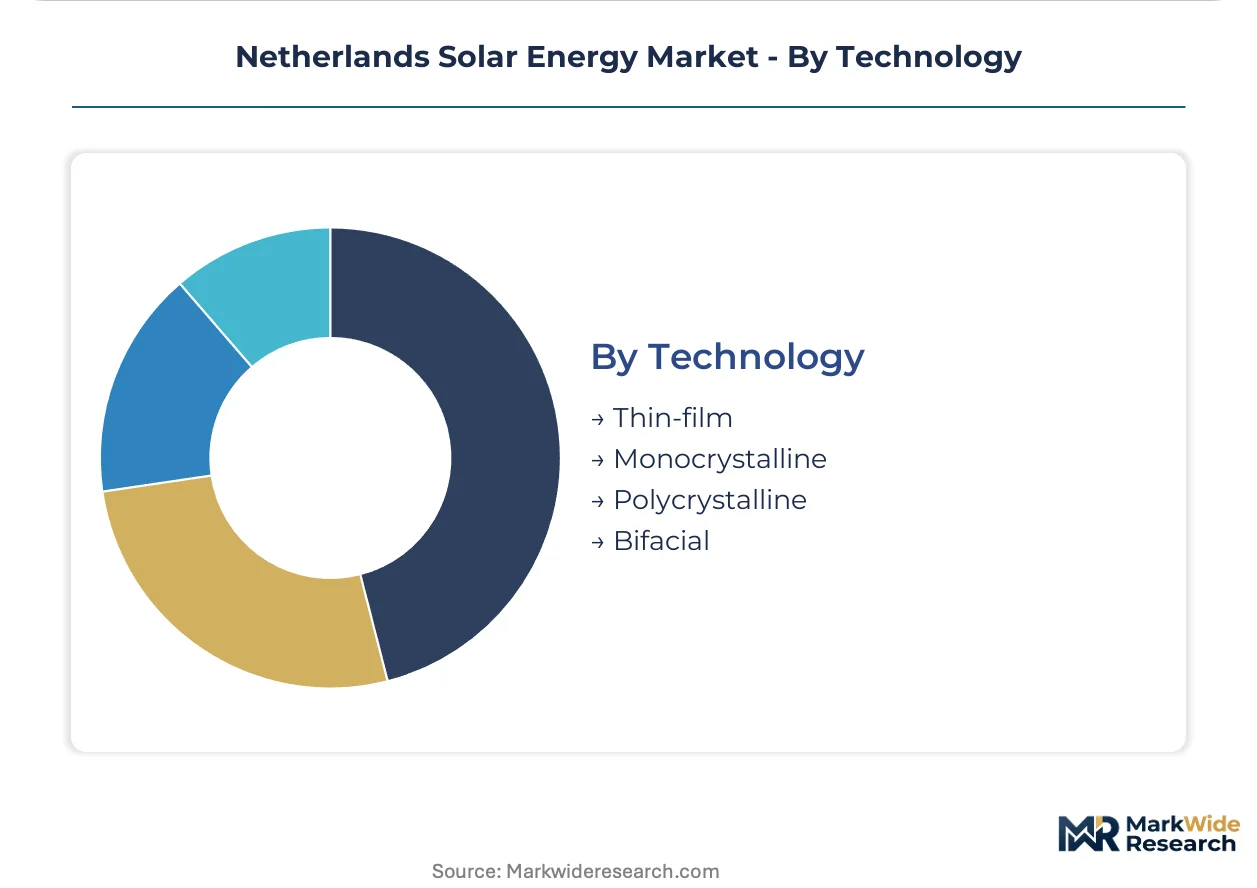
Technology:
Cell architecture determines yield profiles and supply chain provenance requirements. EU due diligence directives reshape module procurement protocols.
- Thin-film:Cadmium-telluride and amorphous silicon cells with lower efficiency but temperature coefficient advantages. Minimal Dutch deployment due to efficiency constraints and limited domestic supplier relationships.
- Monocrystalline:Single-crystal silicon cells delivering highest commercial efficiencies. Dutch residential installers favor these modules for constrained rooftop area optimization.
- Polycrystalline:Multi-crystal silicon cells with lower manufacturing costs but reduced efficiency. Price-sensitive commercial projects in Gelderland specify these for large flat rooftops.
- Bifacial:Double-sided panels capturing direct and reflected irradiance. These systems gain eight-to-twelve percent yield uplift on Dutch flat agricultural terrain, dominating utility-scale procurement.
Monocrystalline technology holds installed capacity. Bifacial modules are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale buyers concentrate deployment in North Holland and South Holland provinces where grid interconnection density supports large-scale solar parks. Agricultural cooperatives and industrial off-takers now secure priority grid access through SDE++ subsidy allocations.
North Holland
Data center operators and cold storage logistics firms drive commercial rooftop demand in Amsterdam and Haarlem metropolitan zones. The Dutch Authority for Consumers and Markets implements locational marginal pricing reforms here first. High-voltage substation clusters around Zaandam reduce transmission upgrade costs for utility-scale developers building bifacial ground-mounted arrays.
South Holland
Greenhouse horticulture facilities in Westland municipality anchor dedicated solar park development without grid export requirements. Net metering regulations from the Dutch Authority for Consumers and Markets shape residential payback calculations in Rotterdam and The Hague urban corridors. Battery-solar hybrid integration qualifies for stacked SDE++ subsidies while resolving congestion pricing in Delft distribution networks.
Flevoland Province
Reclaimed polder land with flat topography and existing high-voltage infrastructure offers underpenetrated territory for agrivoltaic parks. The Netherlands Enterprise Agency conditions SDE++ financial support on projects meeting EU Green Deal carbon reduction benchmarks. Agricultural cooperatives in Lelystad and Almere specify elevated bifacial structures permitting crop cultivation beneath arrays.
Brabant
Industrial manufacturing facilities and logistics warehouses seek behind-the-meter generation in Eindhoven Region technology corridors. REPowerEU framework reforms compressed permitting timelines from eighteen months to under six months for ground-mounted installations. Tilburg and Breda host emerging commercial rooftop clusters as streamlined municipal permitting sustains absolute capacity additions.
Gelderland
Price-sensitive commercial projects specify polycrystalline modules for large flat rooftops in Arnhem and Nijmegen industrial zones. Strict Dutch zoning laws under the Crisis and Recovery Act prioritize food security, limiting available hectares for ground-mounted development. Agricultural cooperatives lease fields for solar park development in the Achterhoek sub-region where flat terrain albedo conditions vary seasonally.
Netherlands Solar Energy Market Competitive Landscape
Player mix skews toward integrated European utilities and specialized Dutch project developers with agrivoltaic expertise. Market structure fragments across three tiers: offshore wind heritage operators leveraging renewable portfolios, downstream energy trading conglomerates monetizing output volatility, and niche agricultural land-use specialists. Strategic archetypes include subsidy-anchored utility developers, corporate PPA originators, and agrivoltaic land-use optimizers. Dominant competitive moves center on battery co-location partnerships and fifteen-to-twenty-year direct offtake negotiations bypassing utility intermediaries.
Within the utility heritage tier, Vattenfall AB and Orsted A/S exemplify integrated renewable portfolio strategies spanning offshore wind and solar development. Shell plc occupies a position among downstream energy trading conglomerates. Solarfields Nederland BV represents the specialized agrivoltaic archetype, sitting between agricultural land use and energy generation. Chint Solar Netherlands B.V. anchors the Chinese manufacturing-backed development segment. These five entities illustrate how competitive positioning fragments across capability origins rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| Chint Solar Netherlands B.V. |
| DMEGC Solar Energy |
| Solarfields Nederland BV |
| Sunrock Investment B.V. |
| Orsted A/S |
| Vattenfall AB |
| AB Solar Total |
| Shell plc |
| BayWa r.e. GmbH |
| Others |
Supply & Pricing Matrix
The EU Green Deal's forced labor due diligence directives and carbon border adjustment mechanism simultaneously gate supply qualification and price differentiation in Dutch solar procurement. Developers must document polysilicon-to-module provenance to secure SDE++ subsidies, extending project finance timelines while compressing margins for non-compliant sourcing.
Pricing Analysis
Monocrystalline modules command premium positioning over polycrystalline alternatives and emerging heterojunction next-generation cells. Three-tier pricing structure across premium glass-glass bifacial, standard monofacial, and economy polycrystalline tiers reflects efficiency differentials and warranty duration. Cost compression in polycrystalline tiers is intensifying because agricultural cooperatives prioritize capex minimization over yield optimization. Commercial greenhouse operators exhibit lowest price sensitivity due to fifteen-year PPA anchoring, while residential installers face acute margin pressure from net metering phase-out.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Dutch developers. Module supply concentrates in China, Vietnam, and Malaysia, with polysilicon feedstock drawing from Xinjiang and Inner Mongolia smelters. Dutch project finance covenants now embed EU forced labor due diligence requirements, creating regulatory restriction risk for single-source Asian procurement. Distribution runs through specialized renewable EPC contractors and direct developer-factory relationships, bypassing traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands solar market sits in a subsidy-driven cyclical upswing as SDE++ allocations and REPowerEU permitting reforms compress project development timelines. This recovery phase favors developers with secured grid interconnection and validated supply chain provenance.
For Market Incumbents: Consolidate project development pipelines in Flevoland and South Holland provinces where grid congestion pricing has already cleared marginal competitors. Acquire specialized agrivoltaic engineering capabilities to defend against agricultural cooperative self-development. Prioritize backward integration into battery storage system procurement to capture stacked SDE++ subsidies and resolve distribution network constraints.
For New Entrants and Emerging Players: Lead with corporate PPA origination for data center and cold storage operators in North Holland, bypassing merchant price exposure that incumbents tolerate. Target Westland municipality greenhouse horticulture facilities as the most penetrable segment due to dedicated solar park development without grid export requirements. Deploy direct sales teams with horticulture sector expertise rather than generic renewable origination.
For Investors and Strategic Acquirers: The SDE++ subsidy phase-out timeline reshapes the acquisition landscape toward developers with contracted offtake visibility beyond subsidy dependency. Long-term viability hinges on battery-solar hybrid integration capabilities and agricultural land-use partnerships. Monitor locational marginal pricing implementation signals in South Holland as the inflection indicator for project economics recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Solar Hybrid Integration | Stacked SDE++ subsidies resolve South Holland grid congestion pricing erosion. |
| Corporate PPA Structuring | Fifteen-year contracts with Westland greenhouse operators bypass merchant volatility. |
| Agrivoltaic Project Development | Elevated bifacial structures in Flevoland maintain crop production beneath arrays. |
| Supply Chain Provenance Documentation | EU due diligence compliance secures project finance covenant satisfaction. |
| Grid Interconnection Priority Access | North Holland substation clusters reduce transmission upgrade capital requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with utility planning officers, IPP project developers, EPC contractors, and agricultural cooperative managers; and secondary validation against Netherlands Enterprise Agency SDE++ allocation records, TenneT grid interconnection queues, and EU Green Deal implementation guidance. Bottom-up project pipeline aggregation triangulated against top-down national capacity installation statistics from the Dutch Central Bureau of Statistics.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning installation type, end-user category, technology architecture, and provincial grid infrastructure density. CAGRs were derived from capacity deployment trajectories under varying subsidy allocation scenarios. Key inputs included SDE++ budget envelope projections, net metering phase-out implementation pace, and bifacial module cost decline curves.
Forecasts assume regulatory continuity in EU Green Deal carbon border adjustment and Dutch Authority for Consumers and Markets grid pricing reforms; material policy shifts would require re-modeling. Supply chain disruption scenarios and land-use zoning modifications represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Global Ultra Efficient Solar Power Market