
 Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market | 2026-2036
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market Insights
China is tilting the competitive map as domestic wind turbine OEMs build captive test facilities for gearbox validation. Brüel & Kjær Vibro leverages its acoustic emission expertise to anchor high-end offshore contracts in Northern Europe. SKF sustains integrated advantage by combining bearing know-how with vibration analytics. Siemens competes through digital twin platforms that merge test data with operational turbine fleets.
Wind turbine gearbox vibration and condition monitoring test platforms are integrated electromechanical systems that apply controlled mechanical loading to full-scale or sub-scale gearboxes while capturing multi-channel vibration, acoustic, and thermal signatures through accelerometers and fiber optic sensors at sampling rates exceeding 50 kHz. These platforms replicate 20-year operational stress cycles in compressed test windows to certify gearbox designs before field deployment. Sensor modules and data acquisition systems capture the dominant share of platform bill-of-materials as channel density requirements rise with multi-megawatt turbine classes. Software analytics is the fastest-expanding segment as machine learning-based fault classification replaces threshold-based alarming in predictive maintenance workflows.
FDA oversight applies where platforms incorporate medical-grade data logging components, while ISO 13374 condition monitoring standards and IEC 61400 wind turbine design codes shape test protocol harmonization across OEM supply chains. China's GB standards and MIIT equipment certification rules create parallel compliance tracks for domestic platform suppliers. Stakeholders must weigh regulatory divergence against the cost of dual-certified test architectures as turbine exports cross multiple jurisdictional boundaries.
Market Dynamics
Offshore wind farm operators in Germany and Denmark are compressing gearbox certification timelines as the EU F-Gas Regulation tightens reliability standards, forcing test platform providers to accelerate 20-year operational stress replication into shorter validation windows.
Growth Catalysts
- EU F-Gas Regulation:Tightening reliability standards for offshore gearboxes are mandating expanded condition monitoring programs across North Sea installations.
- China's MIIT equipment certification:Domestic turbine OEMs are building captive validation laboratories to satisfy GB standards compliance for multi-megawatt turbine classes.
- Fiber optic sensing:Distributed acoustic sensing is displacing conventional accelerometer arrays in high-channel-density test configurations.
Market Restraints
- Sensor module cost volatility:Precision accelerometers and high-speed data acquisition cards constitute the dominant share of platform bill-of-materials, exposing margins to semiconductor supply fluctuations.
- Dual certification burden:China's parallel GB standards and MIIT rules create compliance friction for European platform suppliers seeking access to domestic OEM laboratories.
- Technical limitation:Current thermal signature capture at 50 kHz sampling rates remains insufficient for detecting incipient white-etching cracks in high-speed planetary stages.
Strategic Opportunities
- Digital twin convergence:Machine learning-based fault classification is hybridizing with physics-based gearbox models to enable real-time design iteration during compressed test cycles.
- Service unbundling:Independent test houses in Hamburg and Copenhagen are capturing validation work previously retained by OEM captive facilities.
- India's CEA grid codes:Emerging offshore wind targets are creating first-mover openings for condition monitoring platform deployment at ports in Gujarat and Tamil Nadu.
Industry Challenges
- Skill scarcity:Vibration analysts capable of interpreting multi-channel acoustic emission data at 50 kHz sampling rates remain concentrated in Northern European technical institutes.
- Capex intensity:Full-scale gearbox test rigs require specialized foundation isolation and megawatt-scale dynamometer investment that limits facility replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market |
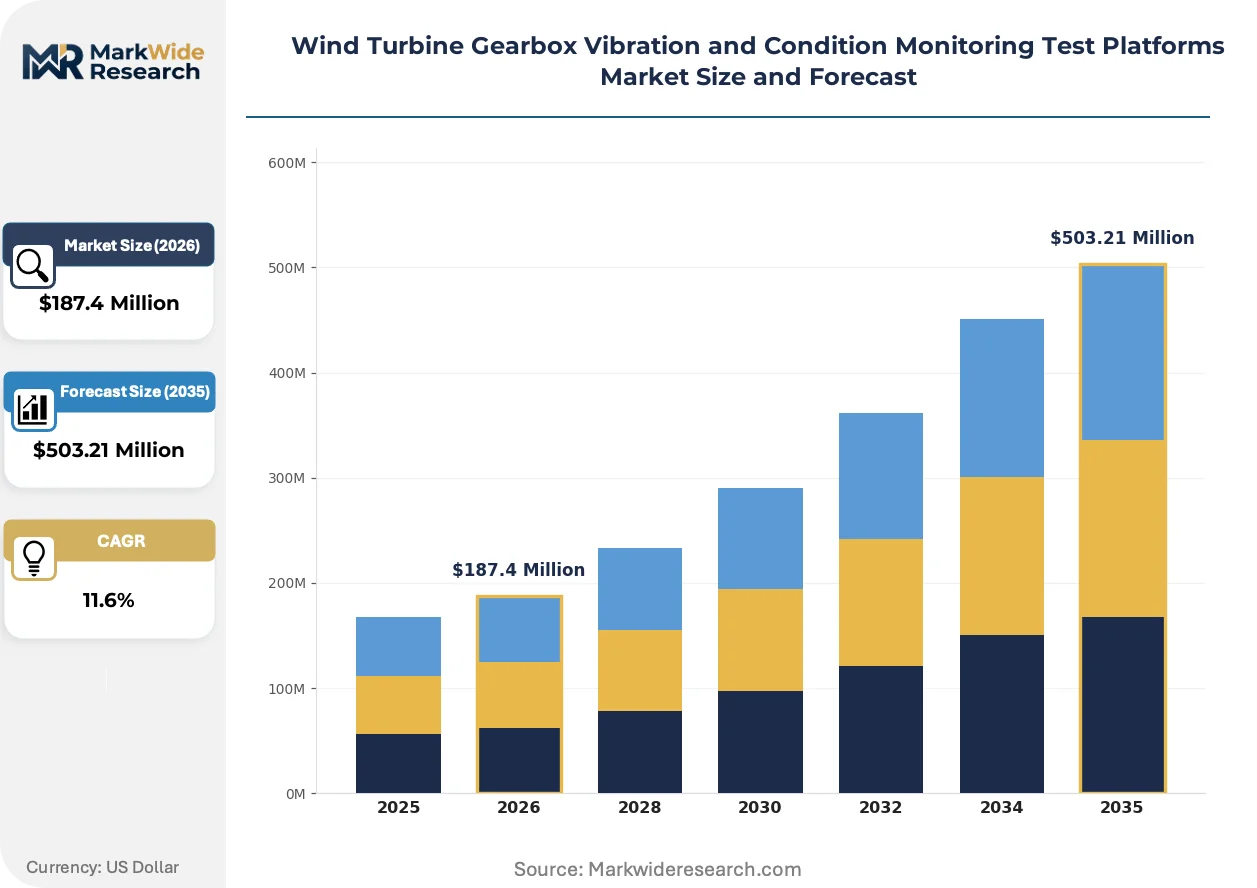
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Modules, Data Acquisition Systems, Signal Conditioners, Software Analytics, Wireless Transmitters, Power Supplies Technology: Accelerometers, Fiber Optic Sensors, Eddy Current Probes, Ultrasonic Detectors, Infrared Sensors, Strain Gauges Application: Fault Diagnosis, Predictive Maintenance, Performance Analysis, Structural Health Monitoring, Load Measurement, Noise Assessment End User: Wind Farm Operators, Condition Monitoring Specialists, Gearbox Manufacturers, Maintenance Contractors, Research Institutes, OEMs |
| Companies Covered | Brüel & Kjær Vibro, SKF, HBM, ifm electronic, Advantech, Analog Devices, Romax Technology, General Electric, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market Trends and Innovations
Machine learning architectures are displacing threshold-based alarming in predictive maintenance workflows, compressing fault classification timelines from weeks to hours while raising channel density requirements for test platforms.
Digital twin technology is hybridizing physics-based gearbox simulation with operational fleet data, enabling Siemens and SKF to merge test platform outputs with real-time turbine performance monitoring. Offshore operators in the North Sea are adopting these integrated platforms to pre-certify gearbox designs against actual load spectra rather than standardized duty cycles. The structural consequence is collapsing the boundary between laboratory validation and field condition monitoring, forcing standalone test platform suppliers to embed fleet connectivity or surrender high-margin contracts.
The EU F-Gas Regulation is mandating comprehensive leak detection and reliability documentation for offshore gearbox hydraulic systems, extending test protocol scope beyond mechanical loading to integrated fluid monitoring. German certification bodies are revising IEC 61400 compliance checklists to incorporate these requirements. Platform suppliers serving Vestas and Siemens Gamesa installations must now demonstrate thermal imaging and pressure signature capture capabilities that were previously optional.
Buyer concentration among Chinese domestic OEMs is consolidating procurement authority at Goldwind, Envision, and MingYang headquarters, displacing distributed purchasing through European engineering subsidiaries. These manufacturers are specifying GB-standard test protocols that diverge from IEC harmonization, fragmenting global platform architecture requirements. The divergence is most visible in channel density specifications, where Chinese laboratories demand 30% higher accelerometer counts for equivalent turbine ratings.
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market Segmentation
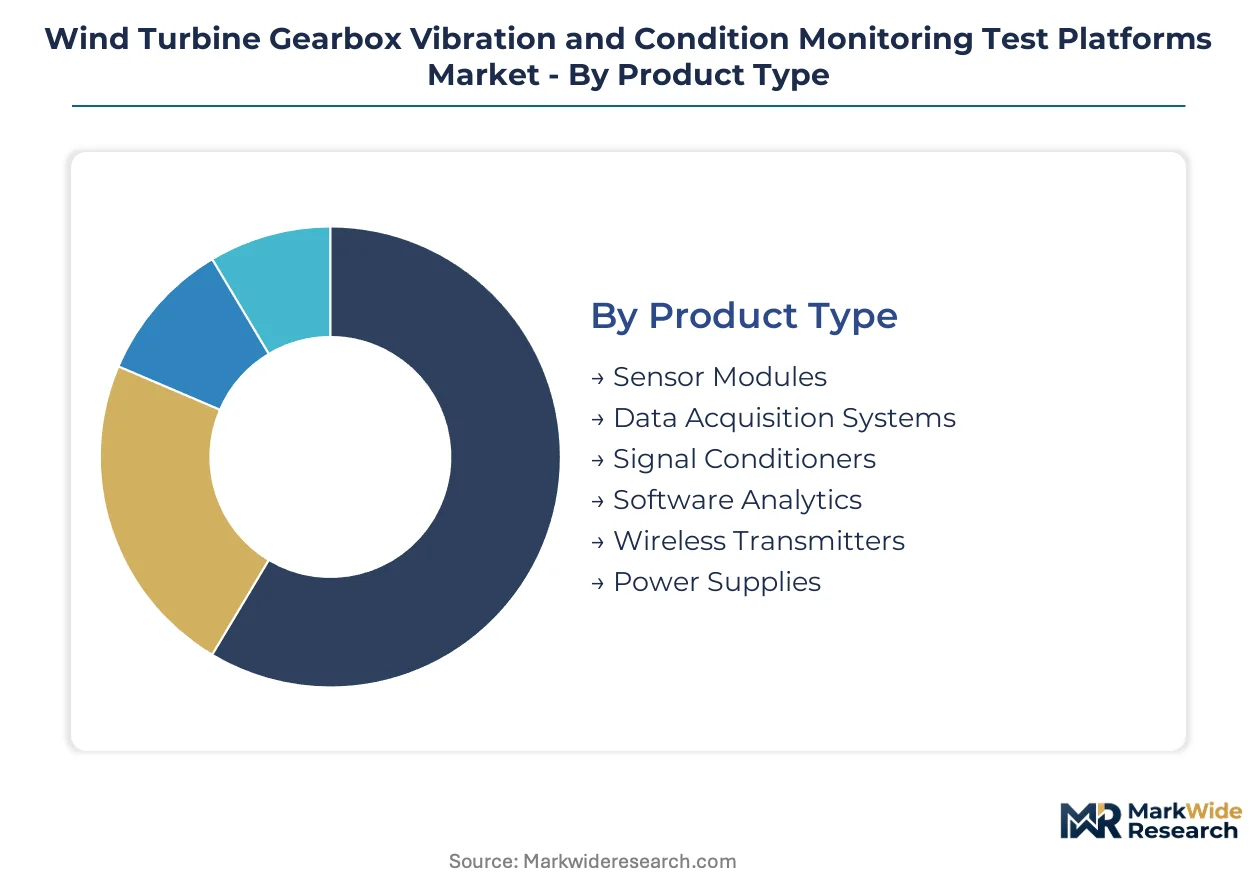
Test platform procurement patterns diverge sharply across buyer types and operational contexts. Segmentation reveals how channel density requirements, compliance mandates, and technology maturity reshape supplier positioning across the value chain.
Product Type:
Mature hardware categories dominate installed base volumes while emerging software layers capture expanding margins through predictive analytics integration.
- Sensor Modules:Multi-channel accelerometer and fiber optic arrays constitute the dominant bill-of-materials share. Goldwind and Envision specifications in China now demand 30% higher channel counts than IEC-harmonized European platforms, compressing supplier margins through precision component sourcing pressure.
- Software Analytics:Machine learning-based fault classification architectures are displacing threshold-based alarming systems. North Sea offshore operators in Germany and Denmark prioritize these platforms for real-time gearbox certification against actual load spectra rather than standardized duty cycles.
- Data Acquisition Systems:High-speed sampling cards operating above 50 kHz anchor platform signal integrity.
- Signal Conditioners:Analog filtering modules bridge sensor outputs to digitization stages.
- Wireless Transmitters:Industrial IoT protocols enable distributed sensor networking without cable harness complexity.
- Power Supplies:Isolated DC systems protect sensitive measurement electronics from dynamometer electrical noise.
Sensor modules handle the majority of throughput; software analytics is the fastest mover on share.
Technology:
Cost tier stratification separates established electromechanical methods from premium photonic sensing approaches gaining traction in high-channel-density configurations.
- Accelerometers:Piezoelectric and MEMS-based vibration transducers remain the foundational measurement technology. German certification bodies under TÜV and DEWI standards specify these for IEC 61400 compliance verification across onshore installations.
- Fiber Optic Sensors:Distributed acoustic sensing arrays are displacing conventional accelerometer configurations in offshore test rigs. Brüel & Kjær Vibro leverages this technology to anchor high-end contracts for Vestas and Siemens Gamesa North Sea deployments.
- Eddy Current Probes:Non-contact displacement measurement for shaft orbit analysis in planetary gear stages.
- Ultrasonic Detectors:High-frequency emission monitoring for detecting incipient bearing raceway defects.
- Infrared Sensors:Thermal signature capture for lubrication system and bearing temperature profiling.
- Strain Gauges:Direct torque and bending moment measurement on gearbox housings and shafts.
Accelerometers retain the deepest installed base; fiber optic sensing is expanding most quickly as offshore channel density requirements intensify.
Application:
Customer type differentiation splits routine operational monitoring from intensive design validation cycles with diverging platform specification priorities.
- Predictive Maintenance:Continuous condition monitoring workflows prioritize anomaly detection speed over absolute measurement precision. Hamburg and Copenhagen independent test houses capture validation work previously retained by OEM captive facilities through streamlined predictive service offerings.
- Fault Diagnosis:Root-cause analysis applications demand archival-grade data retention and multi-physics correlation. China's MIIT equipment certification rules mandate this capability for domestic OEM laboratory accreditation.
- Performance Analysis:Efficiency mapping under controlled loading conditions for gearbox design optimization.
- Structural Health Monitoring:Tower and nacelle integration testing beyond gearbox-specific validation.
- Load Measurement:Direct mechanical torque and force quantification for drivetrain characterization.
- Noise Assessment:Acoustic emission profiling for environmental compliance and community impact mitigation.
Predictive maintenance commands the largest operational expenditure; fault diagnosis is climbing the fastest as certification timelines compress.
End User:
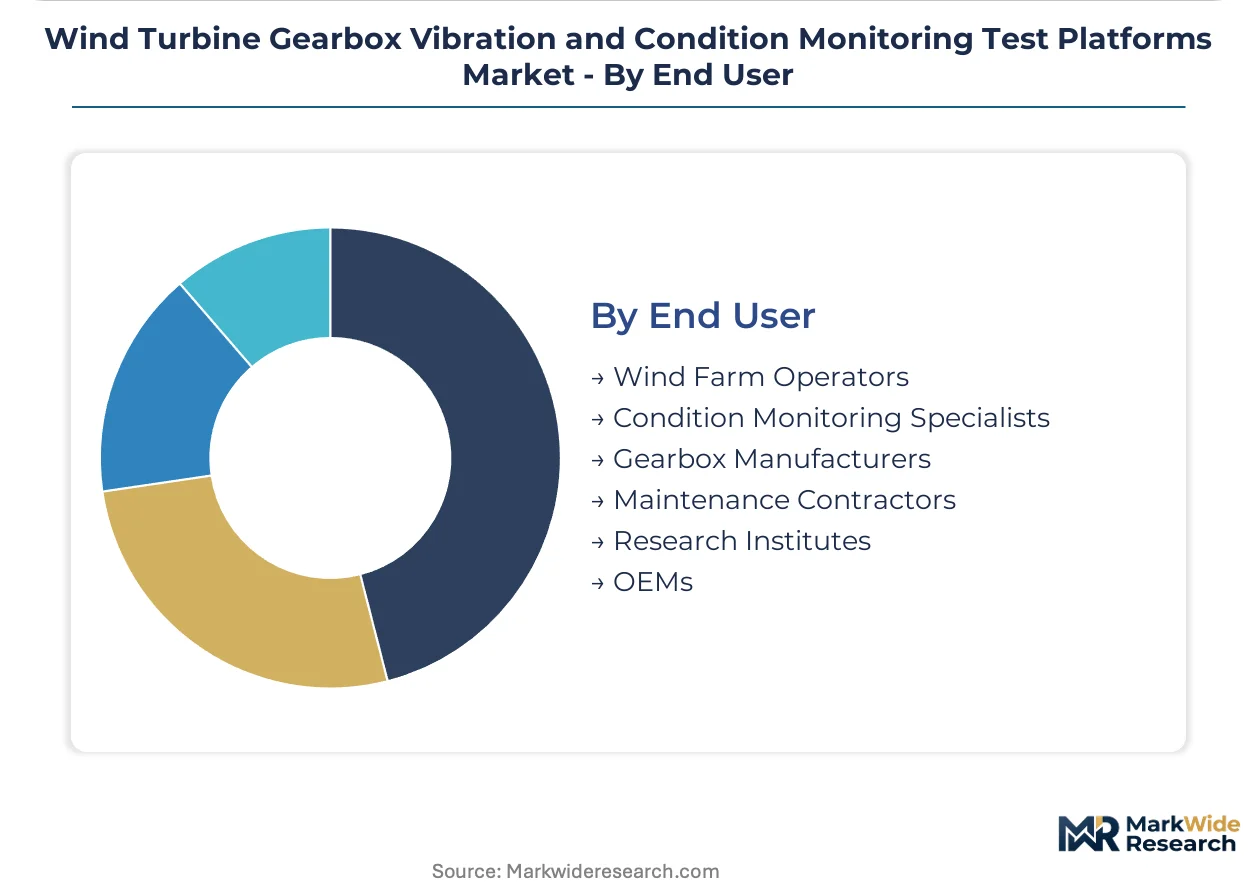
Supply concentration among Chinese domestic OEMs consolidates procurement authority while fragmenting global platform architecture requirements through GB-standard divergence.
- Wind Farm Operators:Offshore asset owners in Germany and Denmark drive demand for integrated fleet connectivity. EU F-Gas Regulation mandates expanded condition monitoring programs across North Sea installations, forcing platform suppliers to demonstrate thermal imaging and pressure signature capture capabilities.
- OEMs:Captive validation laboratories at Goldwind, Envision, and MingYang headquarters specify GB-standard test protocols. These domestic Chinese turbine manufacturers are building in-house facilities that diverge from IEC harmonization on channel density and sampling protocol specifications.
- Condition Monitoring Specialists:Independent service providers unbundling analytics from hardware supply.
- Gearbox Manufacturers:Suppliers to multiple turbine OEMs seeking multi-protocol platform flexibility.
- Maintenance Contractors:Field service organizations prioritizing portable and rapid-deployment configurations.
- Research Institutes:Academic and national laboratory users advancing next-generation sensing methodologies.
OEMs dominate capital procurement volume; wind farm operators are gaining share fastest through operational technology integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European offshore operators compress gearbox validation timelines through accelerated stress replication, while Chinese OEMs extend test protocol scope through GB-standard channel density mandates that diverge from IEC harmonization.
China
Domestic turbine OEMs at Goldwind, Envision, and MingYang headquarters consolidate procurement authority for captive validation laboratories. MIIT equipment certification rules mandate GB-standard compliance tracks that demand 30% higher accelerometer channel counts than European equivalents. Yangtze River Delta clusters around Shanghai host the densest concentration of newly commissioned multi-megawatt test facilities.
Germany
North Sea offshore wind farm operators expand condition monitoring programs to reduce unplanned gearbox downtime under tightening reliability standards. TÜV and DEWI certification bodies revise IEC 61400 compliance checklists to incorporate EU F-Gas Regulation leak detection requirements. Hamburg independent test houses capture validation work previously retained by OEM captive facilities through streamlined predictive service offerings.
Denmark
Offshore asset owners mandate comprehensive reliability documentation for gearbox hydraulic systems extending test protocol scope beyond mechanical loading. National technical institutes concentrate vibration analysts capable of interpreting multi-channel acoustic emission data at 50 kHz sampling rates. Copenhagen service providers unbundle analytics from hardware supply to capture outsourced certification work.
United States
Onshore wind farm operators adopt predictive maintenance workflows as machine learning-based fault classification displaces threshold-based alarming systems. FDA oversight applies where platforms incorporate medical-grade data logging components. Texas and Iowa industrial corridors drive demand for portable rapid-deployment test configurations serving maintenance contractor networks.
India
Emerging offshore wind targets at ports in Gujarat and Tamil Nadu create first-mover openings for condition monitoring platform deployment. CEA grid codes shape technical specifications for integrated test and monitoring systems. Domestic engineering procurement concentrates through national laboratory partnerships advancing next-generation sensing methodologies.
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market Competitive Landscape
Capability concentration sits with specialized sensing and analytics providers; scale advantage sits with diversified industrial conglomerates. The market structure tiering separates premium-tier integrated platform suppliers from mid-tier component specialists and emerging regional fabricators. Three strategic archetypes dominate: acoustic emission specialists leveraging fiber optic expertise, bearing-integrated vibration analytics providers, and digital twin platform developers merging test data with operational fleets. Competitive moves concentrate on strategic partnerships for channel density expansion and technology licensing for GB-standard protocol adaptation.
Within the acoustic emission specialist tier, Brüel & Kjær Vibro anchors high-end offshore contracts through distributed sensing expertise. SKF occupies a position combining bearing know-how with integrated vibration analytics. Siemens exemplifies the digital twin convergence archetype through physics-based simulation hybridization. These three companies represent distinct competitive vectors—specialized sensing, component-integrated analytics, and fleet-connected validation platforms—that collectively define current positioning dynamics.
| Leading Market Players |
|---|
| Brüel & Kjær Vibro |
| SKF |
| HBM |
| ifm electronic |
| Advantech |
| Analog Devices |
| Romax Technology |
| General Electric |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters anchor precision accelerometer supply, channeling pricing power toward sensor module suppliers as Chinese OEMs demand 30% higher channel densities than IEC-harmonized European equivalents. This geographic concentration compresses margins for test platform integrators while amplifying cost pass-through leverage for fiber optic sensing specialists serving North Sea offshore contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement between European test houses and sensor module suppliers, though spot purchasing persists for high-speed data acquisition cards exposed to semiconductor supply volatility. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified platforms for Chinese captive laboratories from IEC-harmonized European configurations and portable rapid-deployment units for maintenance contractors. Cost compression in standard-tier hardware is intensifying because Goldwind and Envision specifications force accelerometer count inflation without proportional value capture. Maintenance contractors exhibit highest price sensitivity due to capex constraints, while offshore operators in Germany and Denmark prioritize premium-tier fiber optic configurations for reliability documentation mandates.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements as test platform integrators manage working capital through supply-chain finance facilities. Precision accelerometer manufacturing concentrates in Germany, Japan, and the United States, while high-speed data acquisition card production rests on Taiwan and South Korea semiconductor fabrication. Fiber optic sensing arrays, precision bearings, and thermal imaging modules constitute critical component dependencies. Single-source vulnerability in 50 kHz sampling rate chipsets threatens platform delivery timelines. Distribution runs through direct OEM procurement for captive laboratories and independent test house networks in Hamburg and Copenhagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
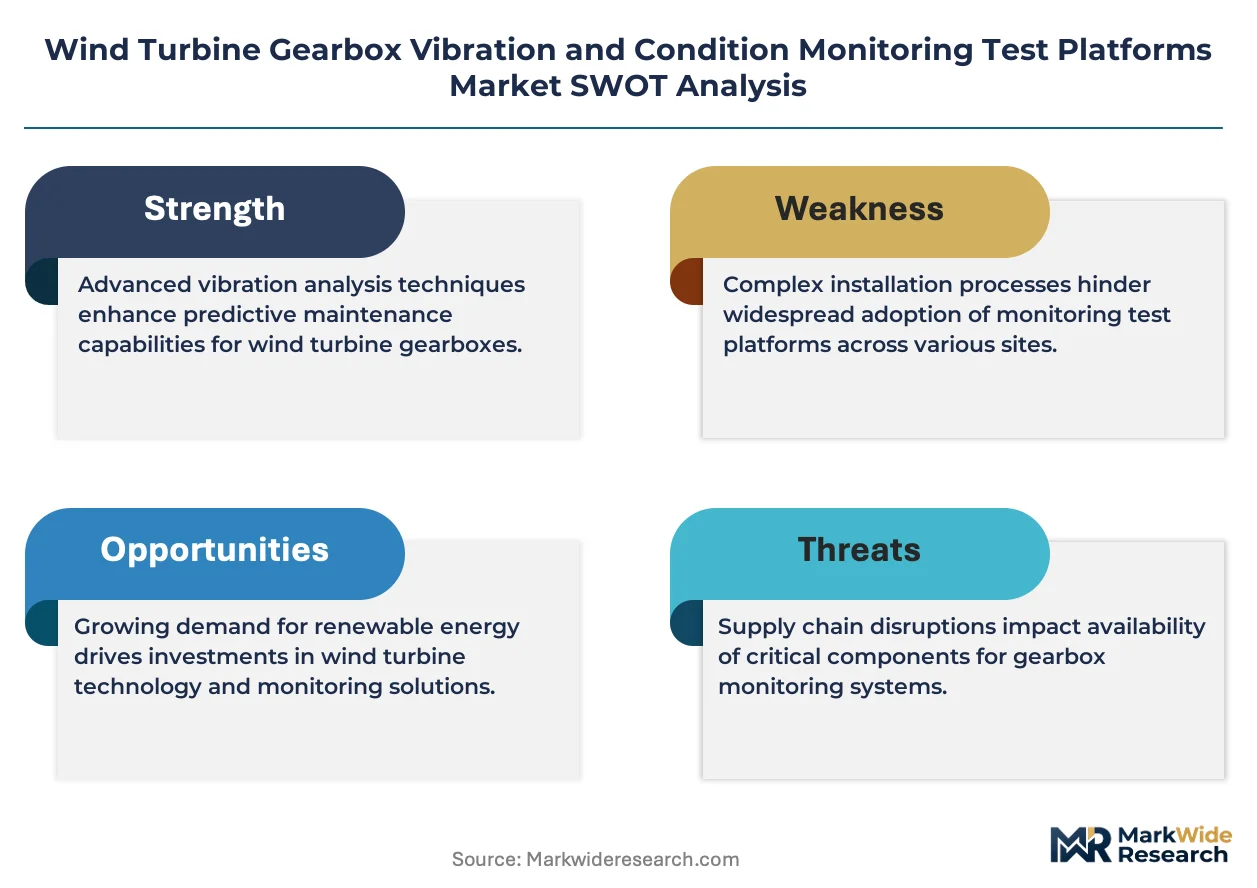
This market is recovering from a cyclical trough as offshore wind installation schedules accelerate gearbox certification demand across North Sea lease rounds.
For Market Incumbents: Pre-empt fiber optic sensing displacement of conventional accelerometer arrays by anchoring distributed acoustic sensing expertise in Vestas and Siemens Gamesa supply relationships. Secure backward integration into precision bearing supply through SKF-style component-integrated analytics to defend against standalone software analytics entrants. GB-standard protocol adaptation investment is essential as Chinese OEM procurement authority consolidates at Goldwind, Envision, and MingYang headquarters. For New Entrants and Emerging Players: Pursue unbundled predictive maintenance service contracts at Hamburg and Copenhagen independent test houses previously retained by OEM captive facilities. India's CEA grid code implementation at Gujarat and Tamil Nadu ports offers the most penetrable geography for first-mover condition monitoring platform deployment. Position through machine learning-based fault classification capabilities that compress anomaly detection timelines from weeks to hours. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software analytics providers with machine learning-based fault classification architectures displacing threshold-based alarming systems. Long-term viability favors platforms bridging laboratory validation with operational fleet connectivity through digital twin convergence. Acquisition targets should demonstrate thermal imaging and pressure signature capture capabilities mandated by EU F-Gas Regulation. Watch for GB-standard certification timeline acceleration as signal of Chinese domestic OEM laboratory buildout inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GB-Standard Protocol Adaptation | MIIT equipment certification rules in China demand parallel compliance tracks for European platform suppliers seeking Goldwind and Envision contracts. |
| Fiber Optic Sensing Integration | Brüel & Kjær Vibro leverages distributed acoustic sensing to anchor high-end offshore contracts for Vestas North Sea deployments. |
| Digital Twin Platform Development | Siemens merges test platform outputs with operational turbine performance monitoring through physics-based simulation hybridization. |
| Independent Test House Expansion | Copenhagen and Hamburg service providers unbundle analytics from hardware supply to capture outsourced certification work from OEM captives. |
| Machine Learning Fault Classification | North Sea operators prioritize real-time gearbox certification against actual load spectra rather than standardized duty cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC 61400 design code documentation, EU F-Gas Regulation implementation guidance, and MIIT equipment certification rule sets. Primary interviews engaged vibration analysts at Northern European technical institutes, procurement directors at Goldwind and Envision headquarters, and aftermarket service heads at gearbox manufacturers. Secondary validation drew from TÜV and DEWI certification body publications, customs data on precision accelerometer trade flows, and patent filings in distributed acoustic sensing. Bottom-up platform bill-of-materials analysis triangulates against top-down market size estimates derived from OEM capital expenditure disclosures.
Forecast inputs span sensor module channel density requirements by turbine class, software analytics penetration rates in predictive maintenance workflows, and offshore wind installation pipeline data across German and Danish lease areas. Segmentation dimensions include product type, sensing technology maturity tier, application intensity, and end-user procurement authority concentration. CAGRs were derived from regression analysis against historical platform procurement cycles and projected gearbox validation demand. Industry-specific inputs incorporate EU F-Gas Regulation compliance timeline acceleration and China's GB standards divergence trajectory.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by fiber optic sensing specialists or accelerated GB-standard harmonization efforts by Chinese regulators would shift outcomes. Macroeconomic contraction in offshore wind financing, semiconductor supply disruption affecting 50 kHz data acquisition card availability, or regulatory deviation in IEC 61400 revision timelines would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Australia Wind Energy Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Wind Turbine Lenses Market