
 Thailand Renewable Energy Market | 2026-2036
Thailand Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Renewable Energy Market Insights
Thai independent power producers is decoupling from conventional fuel dependence as renewable capacity auctions accelerate. Energy Absolute leverages its integrated battery storage and electric vehicle charging infrastructure to anchor long-term offtake contracts. B.Grimm Power sustains competitive positioning through diversified solar and wind assets across provincial industrial zones. Ratch Group dominates conventional-renewable hybrid project development, extending its engineering capabilities into biomass and small hydro installations.
Thailand renewable energy encompasses electricity and thermal output derived from solar irradiance, wind kinetic energy, organic biomass feedstock, and hydrological flow, typically converted through photovoltaic cells with 15-22% module efficiency, horizontal-axis wind turbines with 80-120 meter hub heights, or anaerobic digesters processing agricultural residues at 35-55 degrees Celsius. Photovoltaic technology leads installed capacity due to declining polysilicon module costs and distributed rooftop suitability for commercial factories. Wind turbine deployment grows fastest in southern coastal provinces where monsoon patterns deliver consistent capacity factors above 25 percent. Industrial customers concentrate margin pools through multi-year direct power purchase agreements that bypass utility tariff structures.
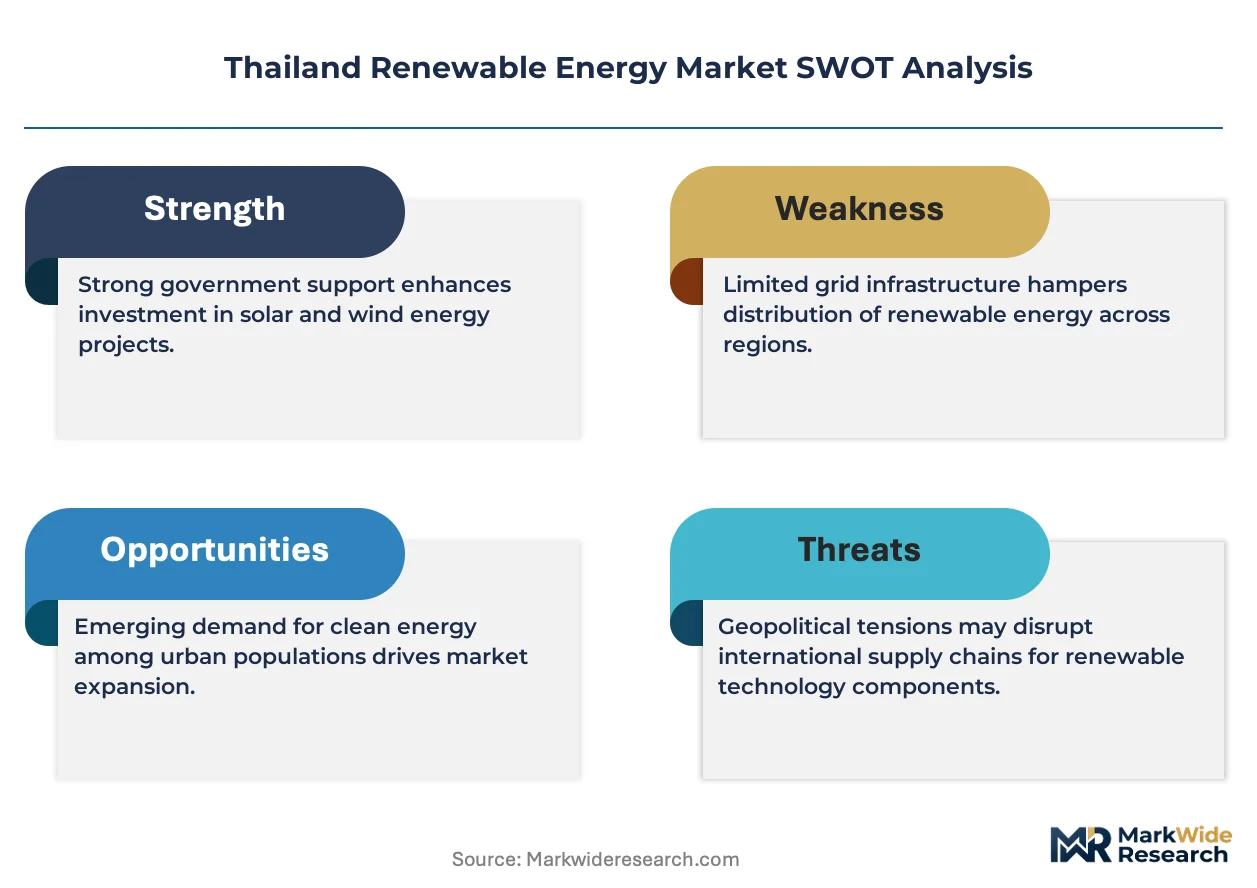
The Energy Regulatory Commission governs feed-in tariff mechanisms and power purchase agreement standardization, while the Department of Alternative Energy Development and Efficiency administers national renewable portfolio targets and resource assessments. Thailand's Power Development Plan and net metering regulations shape investor confidence by defining grid interconnection standards and dispatch priority for renewable generators. Stakeholders must monitor auction pricing floors and transmission congestion in the Central region to align project pipelines with evolving offtake structures.
Market Dynamics
Feed-in tariff revisions by the Energy Regulatory Commission are redirecting capital flows from distributed rooftop solar toward utility-scale photovoltaic auctions, compressing developer margins while accelerating procurement timelines for industrial offtakers in the Eastern Economic Corridor.
Growth Catalysts
- Power Development Plan targets:The Department of Alternative Energy Development and Efficiency mandates renewable capacity additions that create guaranteed procurement pipelines for independent power producers.
- Automotive cluster demand:Electronics and electric vehicle manufacturers in Chonburi and Rayong provinces execute multi-year direct power purchase agreements that bypass utility tariff structures.
- Polysilicon cost curves:Declining module production costs enable 15-22% efficiency photovoltaic systems to undercut conventional gas-fired generation on a levelized basis.
Market Restraints
- Transmission congestion:Grid interconnection bottlenecks in the Central region delay dispatch priority for renewable generators and extend project commissioning timelines.
- Monsoon intermittency:Southern coastal wind farms face capacity factor volatility that requires battery storage co-investment, raising capital intensity.
- Biomass feedstock competition:Agricultural residues face competing demand from food processing and biofuel sectors, constraining anaerobic digester supply security.
Strategic Opportunities
- Net metering expansion:Regulatory frameworks for commercial rooftop solar in provincial industrial zones enable behind-the-meter generation that reduces grid dependence.
- Battery-wind hybridization:Converging lithium-ion storage with southern wind assets creates dispatchable renewable capacity that commands premium offtake terms.
- Small hydro rehabilitation:Existing dam infrastructure in northern provinces offers low-capex capacity upgrades with established environmental permits.
Industry Challenges
- Grid code compliance:Interconnection standards for inverter synchronization and voltage regulation require specialized engineering capabilities that concentrate among a limited contractor base.
- Auction pricing floors:Competitive bidding mechanisms compress developer returns and demand precise resource assessment to avoid underperforming assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Renewable Energy Market |
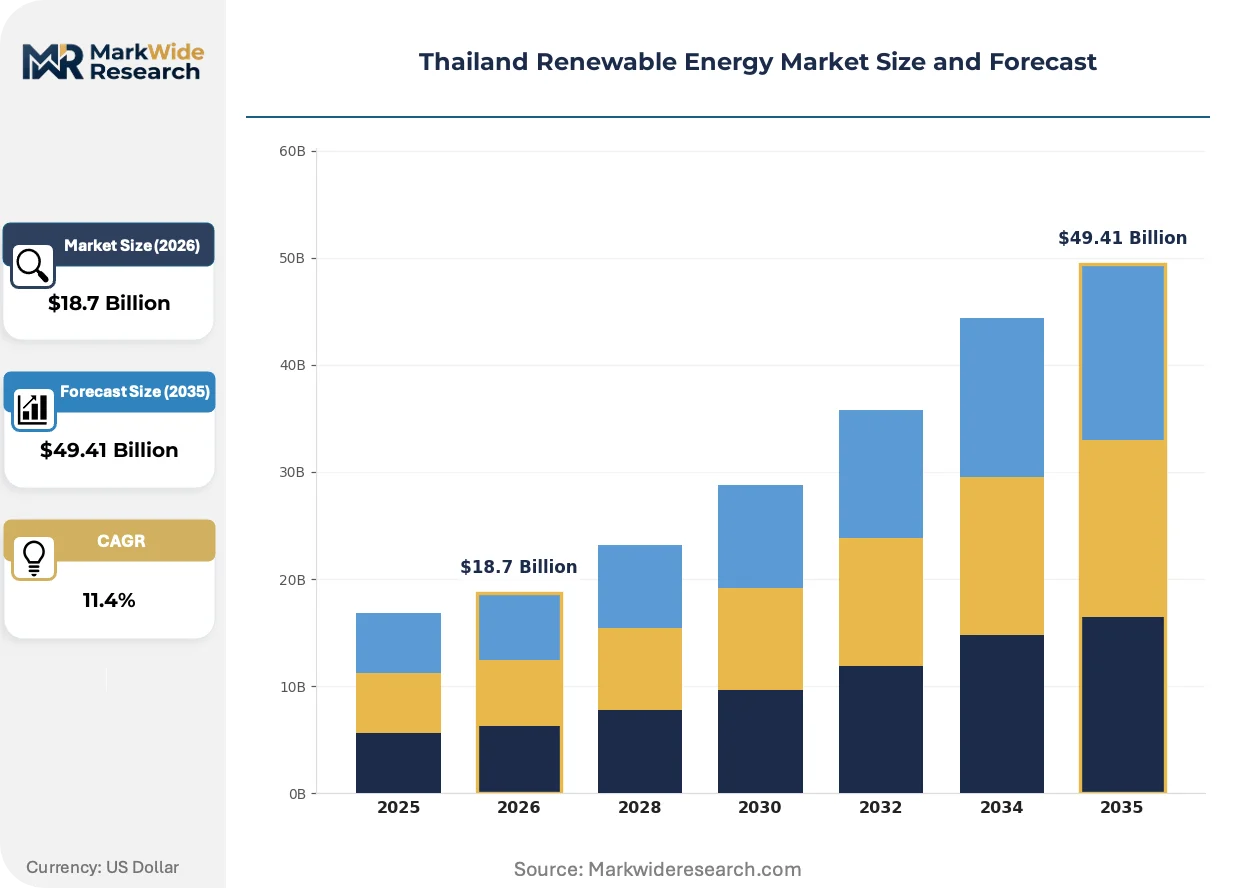
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydro Technology: Photovoltaic, Concentrated Solar Power, Wind Turbines, Anaerobic Digestion Application: Power Generation, Heating, Transportation, Industrial Use Customer Type: Residential, Commercial, Industrial, Government |
| Companies Covered | Energy Absolute, B.Grimm Power, Ratch Group, Global Green Power, SPCG Public Company Limited, Thai Solar Energy, Solartron, Gunkul Engineering Public Company Limited, Super Energy Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Renewable Energy Market Trends and Innovations
Photovoltaic system architecture is fragmenting into standardized, containerized units that reduce installation labor and enable rapid capacity scaling for industrial offtakers with uncertain load growth trajectories.
Bifacial solar module technology captures reflected irradiance from ground surfaces and rooftops, boosting yield per installed watt. Manufacturing facilities in the Eastern Economic Corridor adopt these systems to maximize generation density on constrained land parcels. The technology is modularizing project development into repeatable, bankable units that attract non-specialist institutional capital.
The Energy Regulatory Commission's feed-in tariff revision eliminates premium rates for distributed generation above 10 megawatts, concentrating investment in utility-scale auctions. This policy pivot forces developers to restructure equity partnerships and accelerates consolidation among mid-scale independent power producers. Provincial industrial zones now prioritize direct bilateral contracts over regulated utility offtake.
Industrial buyers are consolidating procurement authority under chief sustainability officers who negotiate multi-year direct power purchase agreements. This organizational shift bypasses traditional utility intermediaries and transfers price volatility risk to generators. Automotive and electronics clusters in Chonburi demonstrate this pattern most visibly, with contract tenors extending to match equipment depreciation schedules.
Thailand Renewable Energy Market Segmentation
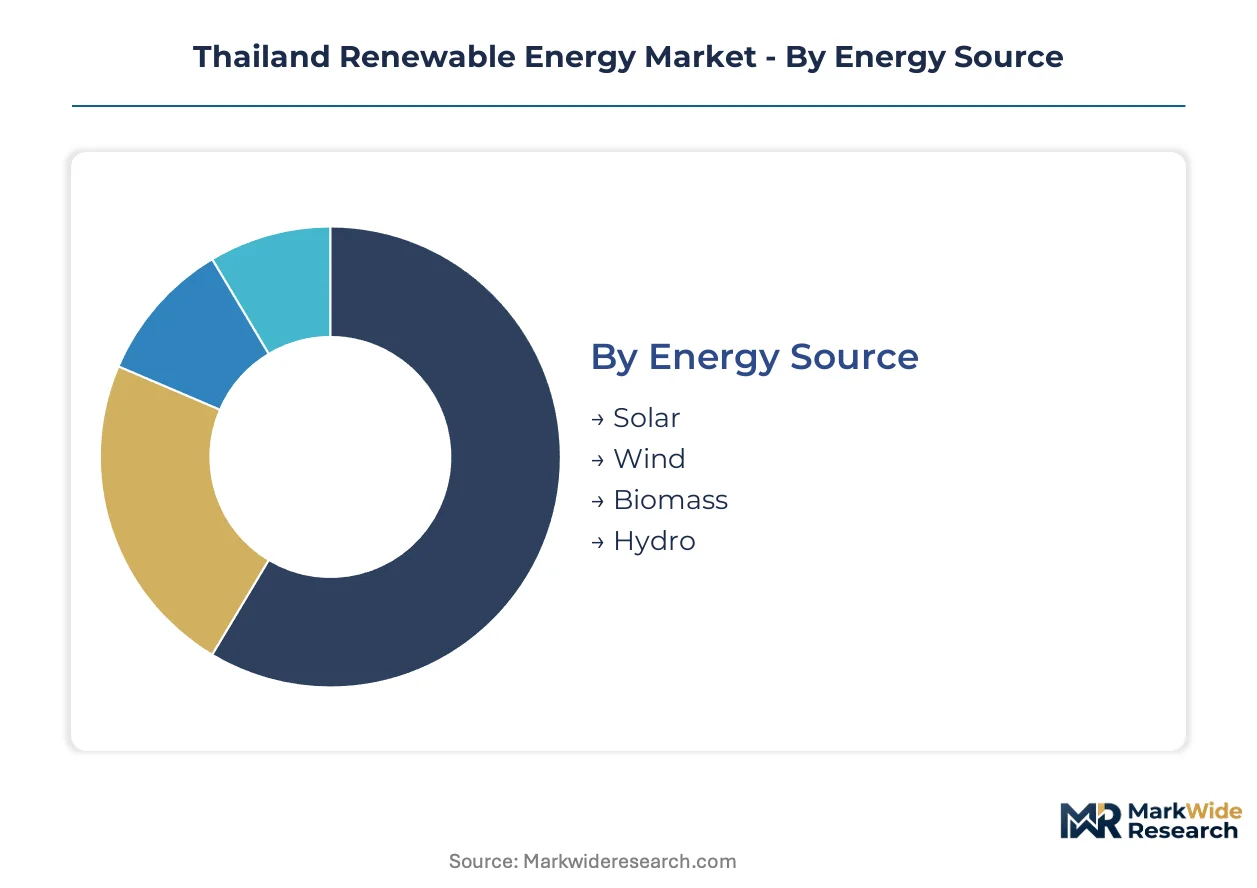
Thailand's renewable energy market fragments across four critical dimensions that determine project economics, regulatory treatment, and offtake structures. Each segmentation layer reveals distinct margin pools, capital intensity profiles, and customer concentration patterns that shape developer strategy.
Energy Source:
Solar installations operate as standalone merchant assets feeding provincial grids, while biomass and small hydro embed within industrial facilities for captive thermal and electrical loads.
- Solar:Photovoltaic arrays with 15-22% module efficiency dominate installed capacity across the Central Plains and Eastern Economic Corridor. Manufacturing clusters in Chonburi and Rayong execute direct power purchase agreements that bypass utility tariff structures, concentrating demand among automotive and electronics offtakers.
- Wind:Horizontal-axis turbines with 80-120 meter hub heights cluster in southern coastal provinces where monsoon patterns deliver capacity factors above 25 percent. Battery storage co-investment requirements raise capital intensity for developers targeting premium dispatch contracts.
- Biomass:Agricultural residue combustion and anaerobic digestion at 35-55 degrees Celsius supplies captive thermal energy to food processing facilities. The Energy Regulatory Commission classifies these as distributed generation eligible for modified feed-in tariff treatment.
- Hydro:Run-of-river and small reservoir installations in northern provinces leverage existing dam infrastructure with established environmental permits. Rehabilitation projects offer low-capex capacity upgrades for provincial independent power producers.
Volume placements concentrate in Solar; the faster expansion belongs to Wind.
Technology:
Cost tiers separate mature commercialized systems from emerging configurations still scaling manufacturing supply chains.
- Photovoltaic:Polysilicon module costs have declined sufficiently to undercut gas-fired generation on a levelized basis. Bifacial technology capturing reflected irradiance boosts yield per watt for constrained industrial rooftops in the Eastern Economic Corridor.
- Concentrated Solar Power:Thermal storage integration enables dispatchable renewable capacity commanding premium offtake terms. High capital intensity and site-specific solar resource requirements limit deployment to utility-scale auctions in Nakhon Ratchasima and Surin provinces.
- Wind Turbines:Southern coastal installations face intermittency challenges requiring grid stabilization investments. The Department of Alternative Energy Development and Efficiency prioritizes these assets in provincial renewable portfolio targets.
- Anaerobic Digestion:Agricultural residue processing generates biogas for combined heat and power applications. Feedstock competition from food processing and biofuel sectors constrains supply security for digester operators.
Technology adoption clusters in Photovoltaic; Concentrated Solar Power shows the steepest expansion trajectory among emerging configurations.
Application:
Customer integration depth varies from behind-the-meter industrial loads to grid-connected merchant generation serving aggregated demand.
- Power Generation:Utility-scale auctions and distributed rooftop systems feed provincial transmission networks. The Power Development Plan mandates capacity additions that create guaranteed procurement pipelines for independent power producers.
- Heating:Biomass thermal systems serve food processing and textile manufacturing facilities with high-temperature steam requirements. Captive installations reduce grid dependence for industrial parks in provincial zones.
- Transportation:Electric vehicle charging infrastructure integrates with solar-plus-storage assets to anchor long-term offtake contracts. Energy Absolute leverages this convergence to secure bilateral agreements with fleet operators.
- Industrial Use:Direct power purchase agreements bypass utility intermediaries and transfer price volatility risk to generators. Chief sustainability officers at automotive and electronics manufacturers consolidate procurement authority for multi-year contracts.
Application demand centers on Power Generation; Industrial Use is gaining share fastest as direct bilateral contracting expands.
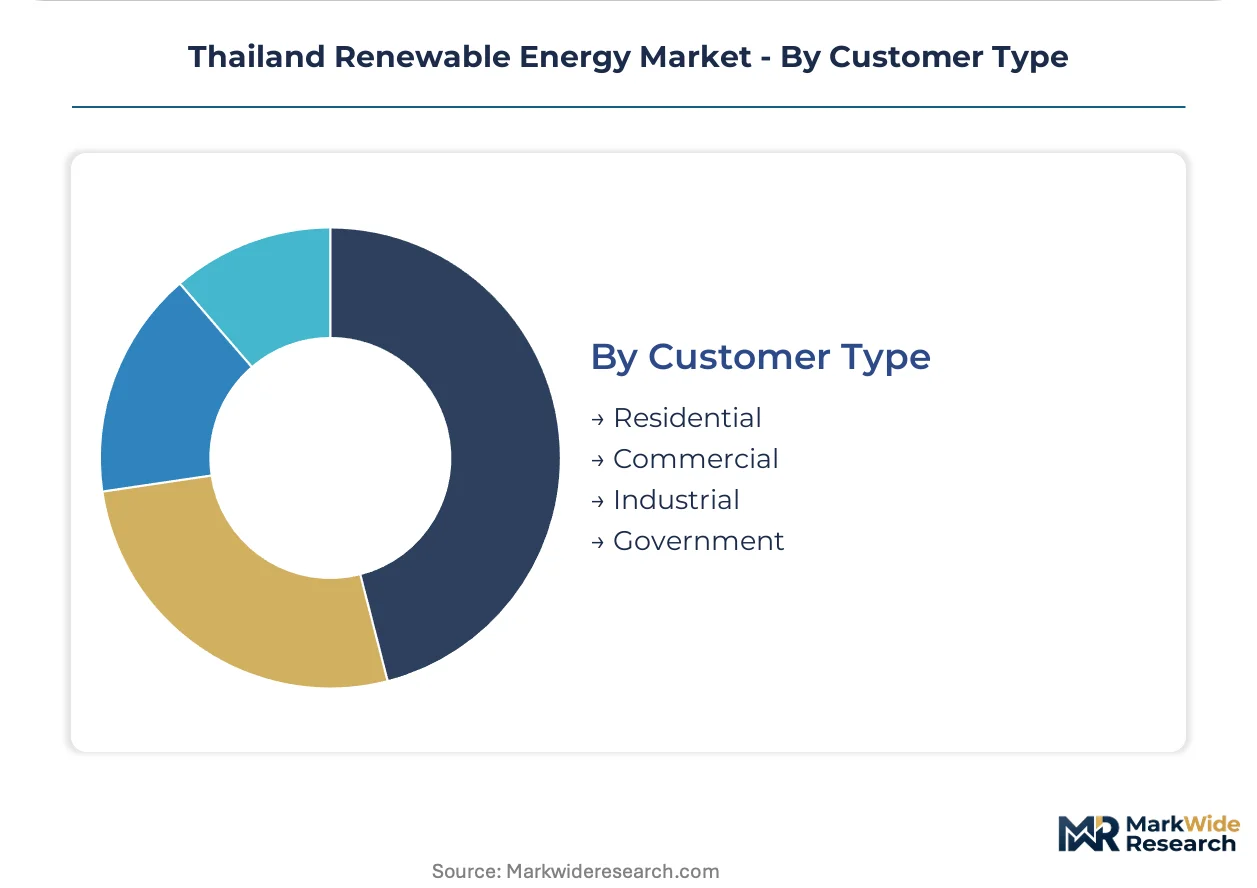
Customer Type:
Margin profiles diverge between regulated utility offtake and negotiated bilateral contracts with price-sensitive commercial buyers.
- Residential:Net metering regulations enable behind-the-meter rooftop generation reducing household grid dependence. Installation scale constraints limit individual project returns for developers.
- Commercial:Office and retail facilities in Bangkok metropolitan area pursue sustainability credentials through renewable energy certificates and green tariff programs. Procurement decisions concentrate under facility management rather than specialized energy teams.
- Industrial:Manufacturing clusters execute multi-year direct power purchase agreements matching contract tenors to equipment depreciation schedules. The Eastern Economic Corridor anchors demand concentration for utility-scale and distributed solar assets.
- Government:State-owned enterprises and municipal utilities procure renewable capacity through competitive auctions governed by Energy Regulatory Commission pricing floors. Procurement timelines accelerate to meet Power Development Plan compliance deadlines.
Customer volume concentrates in Industrial; Government procurement is climbing the fastest under accelerated auction schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monsoon-fed river basins in northern Thailand anchor hydropower feedstock availability, while solar irradiance concentrates across the Central Plains and Eastern seaboard where industrial demand clusters.
Central Plains
Photovoltaic installations dominate capacity additions across Nakhon Pathom and Saraburi provinces where automotive suppliers execute direct power purchase agreements. The Energy Regulatory Commission's feed-in tariff revisions compress distributed generation margins above 10 megawatts, redirecting developer capital toward utility-scale auctions. Manufacturing facilities in Ayutthaya industrial parks adopt bifacial rooftop systems to maximize generation density on constrained land parcels.
Eastern Economic Corridor
Chonburi and Rayong provinces concentrate demand from electronics and electric vehicle manufacturers pursuing multi-year bilateral contracts. Chief sustainability officers at automotive clusters consolidate procurement authority, bypassing traditional utility intermediaries. The Department of Alternative Energy Development and Efficiency prioritizes this corridor for accelerated renewable portfolio compliance deadlines.
Southern Coastal Provinces
Wind kinetic resources in Nakhon Si Thammarat and Songkhla deliver capacity factors above 25 percent during monsoon seasons. Battery storage co-investment requirements raise capital intensity for developers targeting premium dispatch contracts. Provincial independent power producers pursue hybrid wind-lithium configurations to stabilize intermittency and command favorable offtake terms.
Northern Highlands
Existing dam infrastructure in Chiang Mai and Chiang Rai offers low-capex small hydro rehabilitation with established environmental permits. Run-of-river installations leverage agricultural residue feedstock integration for combined heat and power applications. Provincial industrial zones prioritize captive thermal generation to reduce grid dependence for food processing facilities.
Northeastern Plateau
Agricultural residue availability in Khon Kaen and Udon Thani provinces anchors biomass anaerobic digester development at 35-55 degrees Celsius. Feedstock competition from food processing and biofuel sectors constrains supply security for digester operators. The Power Development Plan mandates capacity additions that create guaranteed procurement pipelines for provincial independent power producers.
Thailand Renewable Energy Market Competitive Landscape
Global majors compete with regional champions across project development and offtake contracting, creating a tiered structure where scale advantages separate auction winners from mid-scale developers. The vendor base organizes around three strategic archetypes: integrated utilities with captive demand, independent power producers with diversified renewable portfolios, and specialists in storage-plus-generation hybrids. Competitive intensity concentrates in M&A consolidation among mid-scale players and strategic partnerships for grid stabilization technology access.
Within the integrated utility tier, Energy Absolute anchors long-term offtake through battery storage and electric vehicle charging infrastructure convergence. B.Grimm Power occupies a diversified position spanning solar and wind assets across provincial industrial zones. Ratch Group exemplifies the conventional-renewable hybrid archetype, extending engineering capabilities into biomass and small hydro installations. These three entities represent distinct strategic postures: vertical integration into downstream demand, geographic diversification across renewable technologies, and legacy asset transformation toward cleaner generation mixes.
| Leading Market Players |
|---|
| Energy Absolute |
| B.Grimm Power |
| Ratch Group |
| Global Green Power |
| SPCG Public Company Limited |
| Thai Solar Energy |
| Solartron |
| Gunkul Engineering Public Company Limited |
| Super Energy Corporation |
| Others |
Pricing and Supply Chain Analysis
Containerized photovoltaic system architecture simultaneously compresses installation labor costs and concentrates procurement leverage among specialized EPC contractors capable of rapid capacity scaling. This production-method transition reshapes cost economics by modularizing project development into bankable units while embedding supply chain power with firms controlling standardized component flows.
Pricing Analysis
Warranty bundling separates premium from standard tiers, with comprehensive O&M coverage commanding margin premiums while unbundled hardware-only contracts attract price-sensitive provincial independent power producers. Three-tier pricing structure across premium, standard, and economy levels reflects bifacial module efficiency grades and grid code compliance certification. Pricing pressure stems from competitive auction pricing floors set by the Energy Regulatory Commission, compressing developer returns. Government procurement demonstrates lowest price sensitivity due to compliance-driven timelines, while mid-scale commercial offtakers exhibit highest elasticity.
Supply Chain Analysis
End-of-life module refurbishment and recycling flows remain underdeveloped, constraining circular material recovery and embedding virgin polysilicon dependency into cost structures. Manufacturing concentration centers on China, Vietnam, and Malaysia for cell and module assembly, with inverter electronics sourcing from Taiwan and Germany. Lithium-ion battery cells, tracking systems, and power conditioning equipment constitute critical input dependencies. Single-source vulnerability for high-efficiency bifacial modules creates procurement risk. Distribution runs through EPC-led project delivery to utility-scale auctions and direct bilateral industrial contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photovoltaic technology is displacing conventional gas-fired generation as the dominant capacity addition, forcing asset repricing and contract restructuring across the Thai power sector.
For Market Incumbents: Cement auction competitiveness through backward integration into polysilicon module supply and captive battery storage manufacturing. Consolidate engineering capabilities around grid code compliance specialization to defend against EPC contractor concentration. Prioritize long-term offtake anchoring through electric vehicle charging infrastructure convergence. For New Entrants and Emerging Players: Launch via direct bilateral contracting with automotive clusters in the Eastern Economic Corridor, bypassing utility intermediaries entirely. Target small hydro rehabilitation in northern provinces where environmental permits are grandfathered and capital requirements are modest. Pursue anaerobic digester development in northeastern agricultural zones with captive feedstock agreements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated utilities seeking renewable portfolio diversification rather than IPO liquidity. Five-to-ten year viability hinges on Power Development Plan compliance deadlines and auction schedule density. Monitor Energy Regulatory Commission feed-in tariff revision timing as the critical inflection signal for developer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Utility-Scale Auction Participation | Secures guaranteed procurement pipelines under Power Development Plan mandates. |
| Battery-Wind Hybridization | Stabilizes southern coastal intermittency and commands premium dispatch terms. |
| Direct PPA Structuring | Bypasses Energy Regulatory Commission tariff floors for automotive cluster offtake. |
| Small Hydro Rehabilitation | Leverages existing northern dam infrastructure with established environmental clearance. |
| Grid Code Compliance Certification | Concentrates specialized engineering capabilities among limited contractor base. |
Research Methodology
International Energy Agency country reports, Department of Alternative Energy Development and Efficiency resource assessments, and Energy Regulatory Commission auction records formed the secondary backbone for demand-side quantification. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators validated installation timelines and offtake contract structures. Bottom-up capacity addition tracking and top-down macroeconomic demand modeling were triangulated to anchor projections.
Historical capacity deployment trends across solar, wind, biomass, and small hydro segments informed trajectory extrapolation over the projection horizon. Segmentation modeling incorporated energy source, technology tier, application type, and customer category dimensions. CAGRs were derived from regression analysis of auction pricing floors, module cost curves, and industrial electricity demand elasticity. Forecast inputs included polysilicon price volatility and transmission interconnection queue depth.
Feed-in tariff revision timing, transmission congestion resolution, and auction schedule acceleration are the dominant revision risks to installed capacity trajectories. Forecasts embed assumptions around regulatory stability and grid code enforcement consistency. Practitioners should monitor auction pricing floor adjustments and central region transmission expansion timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Sweden Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Rectenna Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market