
 Offshore Inspection, Repair, and Maintenance Market | 2026-2036
Offshore Inspection, Repair, and Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Inspection, Repair, and Maintenance Market Intelligence
Demand from offshore energy operators managing renewable assets is rotating market share away from traditional oil exploration firms. This shift redefines service requirements for asset integrity management, prioritizing long-term monitoring for wind turbine foundations and subsea cables. Fugro specializes in advanced geotechnical and survey services for site assessment. Oceaneering International, Inc. leverages its strong position in remotely operated vehicles and subsea tooling, while Schlumberger positions its portfolio to serve both conventional energy infrastructure and emerging offshore wind projects.
Offshore inspection, repair, and maintenance encompasses services ensuring the operational integrity of subsea and surface assets. These services employ non-destructive techniques like ultrasonic testing to detect material flaws without damaging the component. The primary purpose is to extend asset life and ensure safety for infrastructure such as pipelines and floating production storage units. Within the service mix, inspection activities form the foundational volume, while robotic solutions and drone surveillance represent the fastest-growing technology segment due to safety and cost advantages.
Regulatory frameworks from bodies like the U.S. Environmental Protection Agency (EPA) and the European Union's offshore safety directives mandate strict integrity management protocols. In Brazil, the Agência Nacional do Petróleo, Gás Natural e Biocombustíveis (ANP) sets operational standards that influence local service procurement. These regulations directly compel recurring inspection and repair cycles for all offshore installations. Stakeholders must now decide how to integrate advanced automation technologies to meet these compliance demands cost-effectively.
Market Dynamics
The convergence of stringent regulatory enforcement and the operational imperative for cost efficiency defines the market's core dynamic. Asset operators face dual pressures to extend the life of aging infrastructure while simultaneously integrating advanced automation to meet compliance mandates from bodies like the EPA and ANP.
Growth Catalysts
- Offshore Energy Expansion:Investment in new offshore wind farms, particularly across the North Sea, and continued development in Brazil's pre-salt oil fields create a sustained need for site assessment, installation support, and long-term integrity management services.
- Regulatory Mandates:Strict safety and environmental frameworks, including the European Union's offshore safety directives, compel operators to conduct regular, documented inspections, directly driving recurring service demand for all subsea and surface assets.
- Robotic Technology Adoption:The deployment of remotely operated vehicles (ROVs) and autonomous drones for inspection tasks improves safety by reducing human exposure to hazardous environments and enhances efficiency, lowering operational expenditures for asset owners.
Market Restraints
- High Operational Costs:The inherent expense of deploying specialized vessels, equipment, and personnel to remote and harsh deepwater environments creates significant budgetary pressures for operators, potentially delaying non-critical maintenance activities.
- Weather-Dependent Operations:Service delivery is often constrained by narrow operational windows dictated by weather and sea conditions, leading to project delays and increased logistical complexity, particularly in regions like the North Sea.
- Skilled Labor Scarcity:A shortage of technicians and engineers with dual expertise in subsea robotics and traditional asset integrity disciplines limits the capacity of service providers to scale operations in line with demand growth.
Strategic Opportunities
- Predictive Maintenance Integration:Combining sensor data from inspections with artificial intelligence and digital twin models offers a significant opportunity to shift from reactive repairs to predictive, data-driven asset integrity management programs.
- Asset Decommissioning Services:The growing portfolio of aging offshore oil and gas platforms nearing the end of their operational life presents a substantial new service line for inspection, planning, and execution of decommissioning projects.
- Geographic Expansion into Renewables:Service providers can leverage their expertise to support emerging offshore wind markets in Asia-Pacific and the United States, where new project pipelines are creating demand for site surveying and foundation inspection.
Industry Challenges
- Data Integration Complexity:Integrating vast and varied data streams from new robotic inspection tools with clients' legacy enterprise asset management (EAM) systems presents a significant technical and workflow challenge for service providers.
- Personnel Certification Gaps:The rapid evolution of inspection technologies creates a gap between available training programs and the on-the-ground need for cross-certified personnel who can operate diverse equipment and interpret complex data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Inspection, Repair, and Maintenance Market |
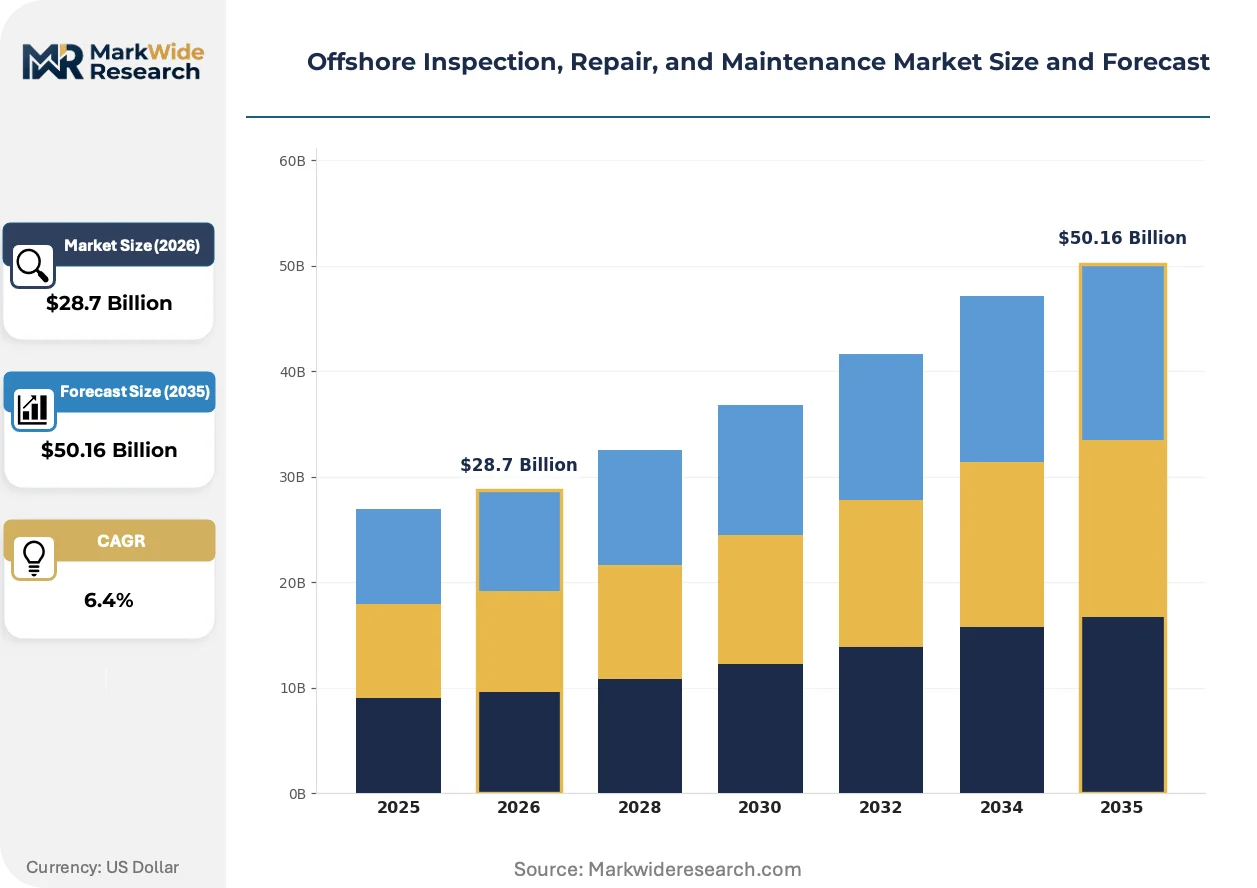
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Corrosion Protection, Structural Repair, Equipment Calibration, Coating Application Technology: Ultrasonic Testing, Magnetic Particle Inspection, Robotic Solutions, Diver-Assisted Methods, Drone Surveillance Application: Subsea Equipment, Floating Production Storage, Offshore Wind Platforms, Mooring Systems, Pipeline Integrity End User: Oil Exploration Firms, Offshore Energy Operators, Marine Contractors, Environmental Agencies, Platform Managers |
| Companies Covered | Baker Hughes Company, Oceaneering International, Inc., Schlumberger Limited, Fugro, Aker Solutions, TechnipFMC, Subsea 7, Saipem, Halliburton Energy Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Inspection, Repair, and Maintenance Market Strategic Shifts & Innovations
Automation and data analytics are fundamentally reconfiguring service delivery in the offshore IRM sector. The market is moving beyond simple visual inspections toward a model where integrated robotic systems and predictive software platforms manage asset integrity throughout the entire lifecycle.
Advanced non-destructive testing (NDT) sensors provide the core data for material flaw detection. Offshore wind and deepwater oil operators are rapidly adopting these tools to gain deeper insights into asset health without intrusive methods. This technology is miniaturizing, enabling its deployment on smaller, more agile autonomous underwater vehicles (AUVs) and drones, which reduces the need for large, costly support vessels.
Regulatory frameworks are increasingly focused on data-driven compliance and lifecycle tracking. The European Union’s offshore safety directives, for instance, demand verifiable proof of asset integrity, compelling operators to adopt more sophisticated monitoring. This directly impacts the inspection segment, which must now provide auditable digital records and analytics rather than simple inspection reports, especially for aging assets in the North Sea.
Service procurement models are evolving from fixed-term contracts to more flexible, data-centric agreements. This shift disrupts the traditional approach where operators owned and managed all inspection campaigns, creating space for service providers offering integrated "inspection-as-a-service" packages. This trend is most visible in the global offshore wind sector, where new asset owners seek to minimize capital-intensive hardware ownership.
Offshore Inspection, Repair, and Maintenance Market Segmentation
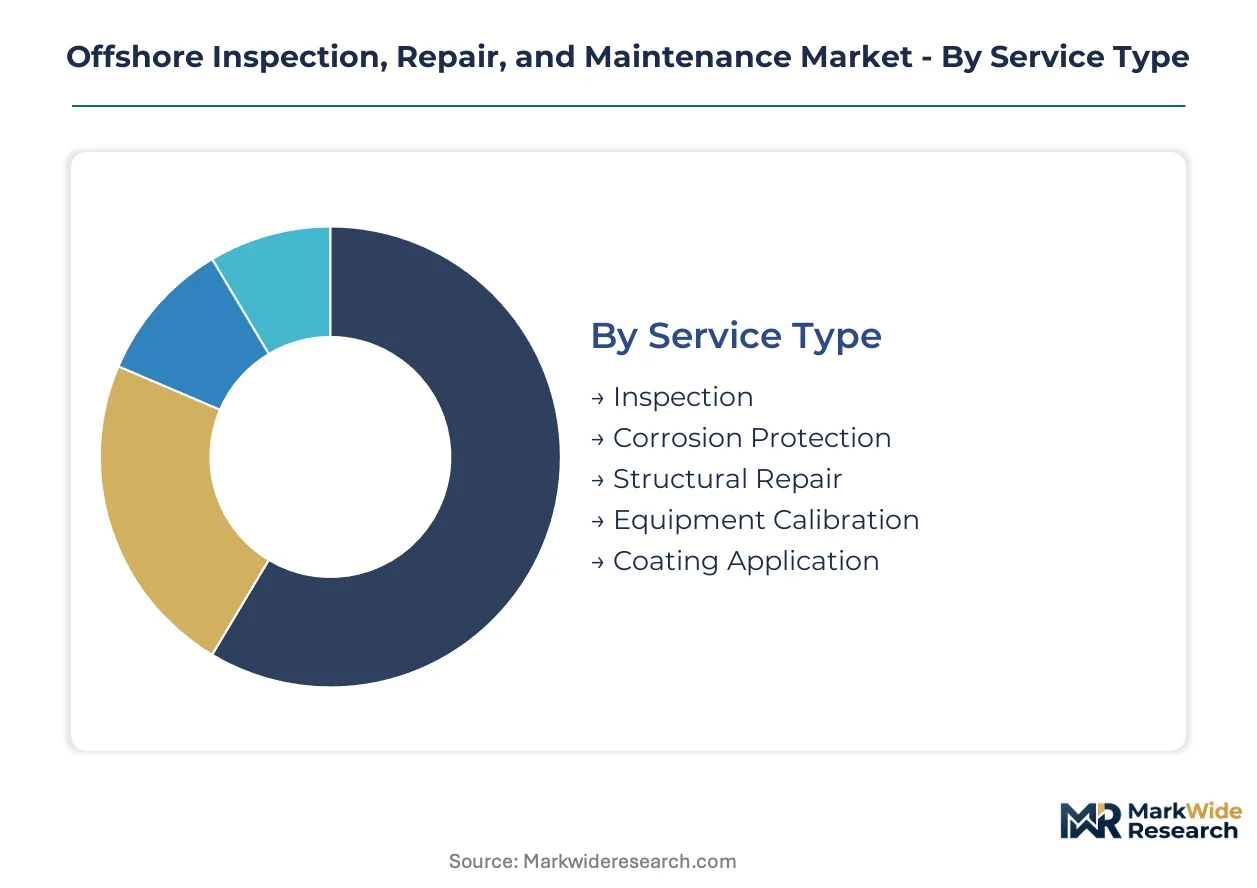
The Offshore Inspection, Repair, and Maintenance Market is delineated by distinct service offerings, technological approaches, operational applications, and end-user profiles. Understanding these segments reveals where value creation concentrates and how shifting demands from offshore energy operators are reconfiguring service delivery models.
Service Type:
Margin pools within the service type segment are influenced by the complexity and specialization required, with highly technical repairs often commanding premium rates.
- Inspection:These services involve systematic examination of assets using visual, non-destructive, and remote sensing methods. Demand concentrates in the North Sea, driven by stringent EU regulatory mandates.
- Corrosion Protection:This involves applying specialized coatings and cathodic protection systems to prevent material degradation in harsh marine environments. Offshore wind platforms require extensive corrosion management.
- Structural Repair:This segment includes welding, patching, and component replacement for damaged subsea and topside infrastructure.
- Equipment Calibration:This ensures the accuracy and reliability of sensors, gauges, and operational instruments on offshore installations.
- Coating Application:This service focuses on applying protective layers to prevent wear, corrosion, and biofouling on offshore structures.
The dominant share belongs to Inspection, while Corrosion Protection is closing the gap fastest due to extended asset lifecycles.
Technology:
The cost structure for technology deployment varies, with advanced robotic solutions requiring higher upfront investment but delivering long-term operational efficiencies.
- Robotic Solutions:This category encompasses ROVs and AUVs for complex subsea inspections and interventions. Offshore energy operators increasingly deploy these tools to improve safety and reduce human exposure.
- Drone Surveillance:This involves aerial drones equipped with cameras and sensors for visual and thermal inspections of topside structures. Their adoption reduces costs for platform managers in the North Sea.
- Ultrasonic Testing:This non-destructive technique uses sound waves to detect internal flaws and measure material thickness in pipelines.
- Magnetic Particle Inspection:This method identifies surface and subsurface defects in ferromagnetic materials, crucial for detecting cracks in structural welds.
- Diver-Assisted Methods:These traditional techniques rely on human divers for close-up visual inspections and minor repairs in shallow depths.
The adoption of Robotic Solutions is accelerating, driven by the imperative for enhanced safety and operational efficiency.
Application:
The maturity of asset types within this segment dictates the volume and regularity of IRM services required.
- Offshore Wind Platforms:These applications involve integrity management for foundations, turbines, and subsea cables of renewable energy installations. Demand is concentrating in the North Sea.
- Pipeline Integrity:This focuses on the inspection and maintenance of subsea and export pipelines to prevent leaks and ensure continuous flow. Brazil's pre-salt fields require continuous monitoring.
- Subsea Equipment:This includes the inspection and repair of wellheads, manifolds, and other production equipment on the seabed.
- Floating Production Storage:This covers the maintenance of FPSOs and other floating facilities for oil and gas processing and storage.
- Mooring Systems:This segment addresses the inspection and repair of chains, ropes, and anchors securing offshore platforms.
Demand for Pipeline Integrity services remains stable, while Offshore Wind Platforms shows significant expansion potential.
End User:
The volume of service procurement within this segment directly correlates with the scale of offshore assets managed by each end-user type.
- Offshore Energy Operators:This group includes companies managing both traditional oil and gas assets and a growing portfolio of renewable energy installations. They prioritize long-term monitoring for wind turbine foundations.
- Oil Exploration Firms:These entities focus on hydrocarbon discovery and extraction, requiring extensive IRM for drilling rigs and production facilities. Their demand is strong in established pre-salt fields.
- Marine Contractors:These firms provide specialized vessel support, installation, and subsea construction services, often requiring integrated IRM solutions.
- Environmental Agencies:These bodies mandate compliance with safety and environmental regulations, driving recurring inspection and repair cycles.
- Platform Managers:These individuals oversee the day-to-day operations and asset integrity of specific offshore installations.
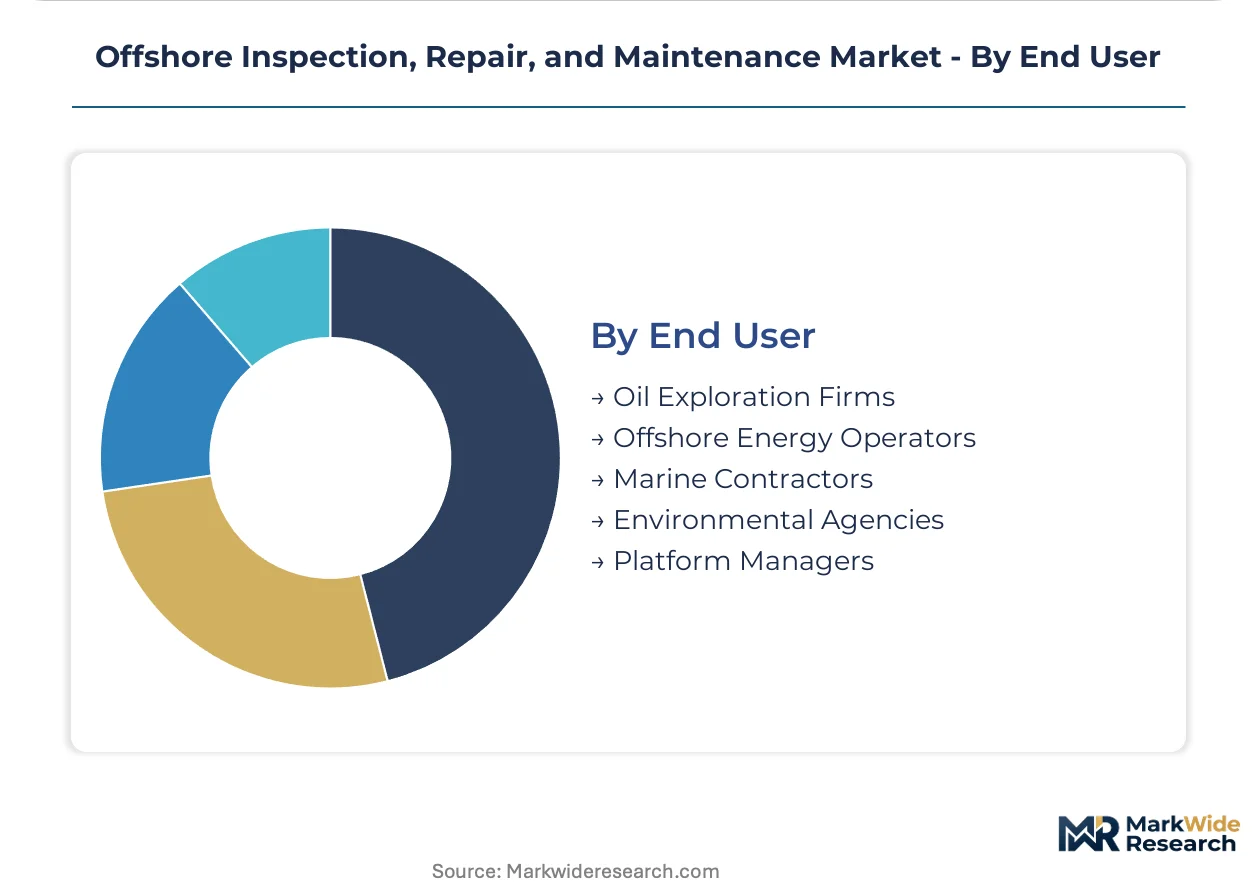
Shifting investment patterns are rebalancing service procurement between Oil Exploration Firms and Offshore Energy Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service providers from established offshore hubs export specialized expertise to emerging energy markets. This global movement of technical capabilities underpins offshore inspection, repair, and maintenance activities. The market's regional dynamics reflect varied regulatory landscapes and investment cycles across key maritime basins.
United Kingdom
Demand for IRM services in the United Kingdom is driven by extensive North Sea oil and gas infrastructure and offshore wind farm expansion. The UK's Health and Safety Executive (HSE) mandates strict asset integrity management protocols for all offshore installations. Aberdeen serves as a central hub for North Sea operations, coordinating advanced subsea inspection and maintenance projects.
Norway
Norway's offshore sector requires continuous IRM for aging platforms and new deepwater developments. The Petroleum Safety Authority Norway (PSA) enforces rigorous safety and environmental standards, compelling frequent inspections. Stavanger hosts a significant cluster of offshore service companies, focusing on robotic solutions for complex subsea environments.
Brazil
Brazil's pre-salt oil fields generate substantial demand for pipeline integrity and subsea equipment maintenance. The Agência Nacional do Petróleo, Gás Natural e Biocombustíveis (ANP) sets operational standards influencing local service procurement. Rio de Janeiro is a key operational base, supporting extensive subsea inspection and repair campaigns for deepwater assets.
United States
The United States offshore market, particularly in the Gulf of Mexico, drives demand for structural repair and corrosion protection services. The Bureau of Safety and Environmental Enforcement (BSEE) regulates offshore drilling and production, requiring robust integrity programs. Houston functions as a major energy capital, housing numerous firms specializing in advanced inspection technologies and services.
Australia
Offshore gas projects in Australia require significant IRM for subsea pipelines and floating production storage units. The National Offshore Petroleum Safety and Environmental Management Authority (NOPSEMA) oversees safety and environmental performance, driving compliance. Perth serves as a strategic gateway for supporting offshore operations, particularly for remote gas fields.
Offshore Inspection, Repair, and Maintenance Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of offshore inspection, repair, and maintenance services. The market structure exhibits a tiered consolidation, with large integrated service providers operating alongside niche technology developers and regional contractors. Strategic archetypes include diversified energy service giants, specialized subsea solution providers, and focused technology innovators. Companies are pursuing portfolio diversification into renewable energy support and strategic partnerships to expand their geographic reach.
Specialized subsea solution providers like Oceaneering International, Inc. exemplify companies leveraging remotely operated vehicles and advanced tooling for complex underwater tasks. Diversified energy service giants such as Schlumberger Limited position their portfolios to serve both conventional oil and gas infrastructure and emerging offshore wind projects. Fugro, a Netherlands-based firm, represents the archetype of a geotechnical and survey specialist, providing critical site assessment services for new offshore developments. These firms collectively demonstrate the industry's pivot towards integrated service offerings and technological innovation to meet evolving client demands.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Oceaneering International, Inc. |
| Schlumberger Limited |
| Fugro |
| Aker Solutions |
| TechnipFMC |
| Subsea 7 |
| Saipem |
| Halliburton Energy Services, Inc. |
| Others |
Cost & Logistics Intelligence
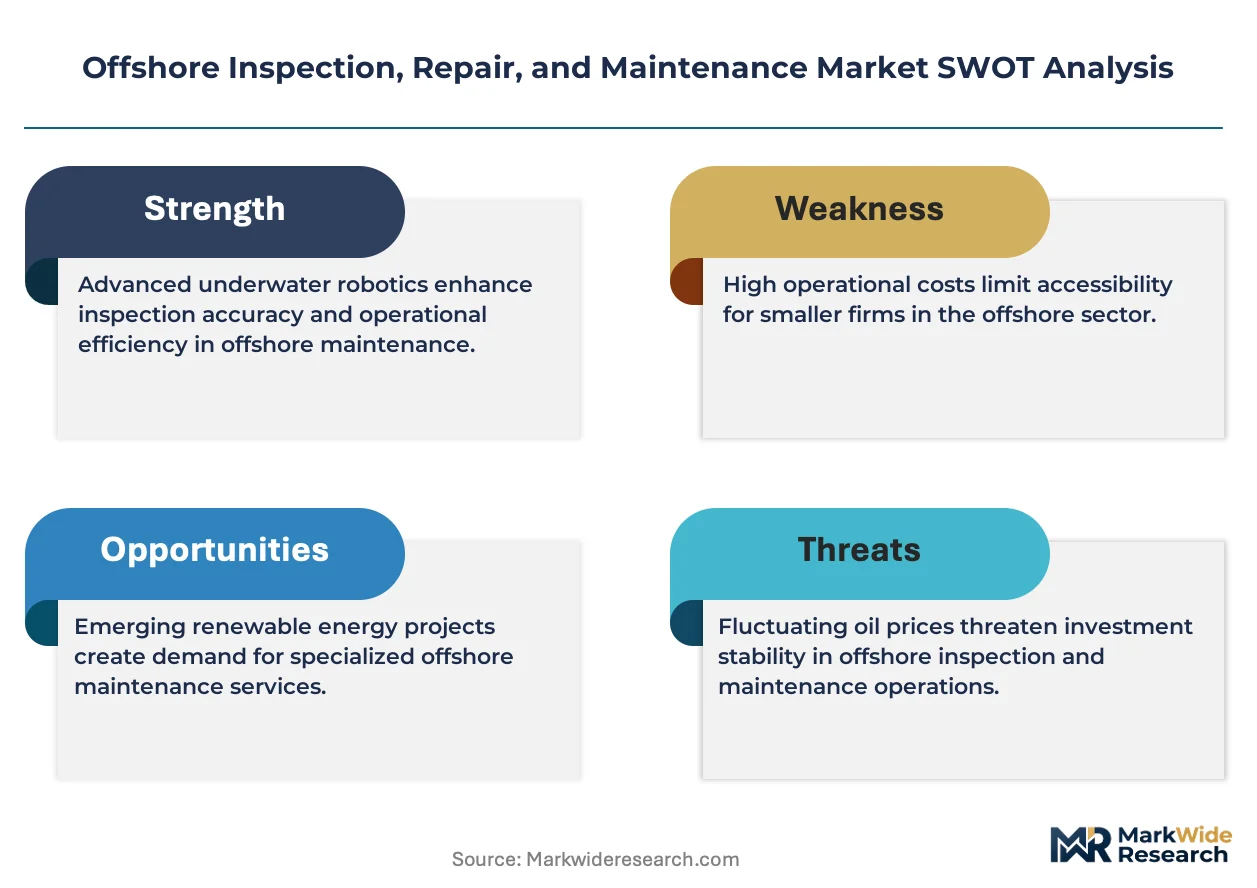
The increasing adoption of robotic automation in offshore IRM is simultaneously reshaping the supply chain for specialized equipment and influencing project-based pricing. This technological shift impacts the cost structures for service delivery, especially for deepwater operations.
Pricing Analysis
Technology-generation gaps create distinct pricing tiers for offshore IRM services. Project-based contracts dominate the market, alongside long-term service agreements for critical assets. Price differentiation hinges on technology sophistication, such as advanced ROV capabilities, and the inherent geographic delivery complexity of remote deepwater sites. Pricing softness stems from operators seeking cost efficiencies amidst fluctuating energy prices. Oil Exploration Firms typically exhibit higher price sensitivity compared to Offshore Energy Operators managing long-term renewable assets.
Supply Chain Analysis
Strategic stockpiling of critical components and specialized vessels characterizes the offshore IRM supply chain, particularly for high-value subsea interventions. Supply concentration for advanced subsea equipment and specialized personnel centers in the United Kingdom, Norway, and the United States. Key dependencies include specialized vessels, advanced ROV components, and sophisticated NDT sensors. Skilled labor scarcity represents a significant structural risk, limiting service providers' capacity to scale. Distribution runs through direct service provision, often bundled into integrated service packages for asset owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore IRM market is increasingly defined by a capability scarcity, particularly a shortage of cross-certified personnel proficient in both traditional asset integrity and advanced robotic inspection technologies. This talent gap hinders operational scalability and the efficient deployment of next-generation solutions.
For Market Incumbents: Secure long-term contracts with major offshore energy operators to stabilize revenue streams against market volatility. Incumbents must invest heavily in upskilling their existing workforce for robotic solutions to bridge the personnel certification gaps. Strategic acquisitions of niche technology developers can mitigate the threat from highly specialized tech-first entrants. Certification investment in advanced inspection technologies will reinforce market leadership and ensure compliance with evolving regulatory mandates.
For New Entrants and Emerging Players: Service-layer gaps in data integration and predictive analytics present a significant opportunity for new entrants. Developing specialized software for real-time data interpretation from diverse sensor inputs offers a clear white-space target. Focusing on drone surveillance for remote offshore wind farms in emerging Asia-Pacific markets provides a penetrable application. The "inspection-as-a-service" model offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward technology innovators and specialized service providers with strong intellectual property in robotic solutions or data analytics. The offshore IRM market offers robust long-term viability, driven by essential asset integrity needs. Acquisition targets should include agile tech developers specializing in AUVs or AI-driven predictive maintenance platforms. Regulatory shifts demanding higher data traceability represent a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced robotic fleet expansion | Enhances subsea inspection capabilities and reduces human exposure in hazardous deepwater environments. |
| Develop AI-driven predictive maintenance platforms | Shifts asset management from reactive repairs to proactive, data-informed integrity strategies for offshore wind farms. |
| Establish cross-training programs for dual certification | Addresses the critical skilled labor scarcity in subsea robotics and traditional asset integrity disciplines. |
| Forge strategic partnerships with offshore wind developers | Secures long-term service contracts and expands market share within the rapidly growing renewable energy sector. |
| Acquire specialized data analytics firms | Integrates complex inspection data with client enterprise asset management systems for enhanced compliance. |
Research Approach
Desk research of regulatory filings, technical journals, and industry association reports preceded structured interviews with offshore energy operators, subsea engineers, and regulatory compliance officers. This approach combined primary insights with secondary validation from corporate financial disclosures and government reports. Bottom-up data collection from specific projects was triangulated with top-down market sizing estimates. Marine contractors provided crucial perspectives on operational challenges.
Variance decomposition analysis isolated the impact of investment in offshore wind platforms and oil field development on market growth across the analysis window. The analytical framework segmented the market by service type, technology, application (including subsea cables), end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected technology adoption.
Forecasts assume regulatory continuity in the U.S. Gulf of Mexico, North Sea, and Brazilian pre-salt regimes; material policy shifts would require re-modeling. These forecasts reflect assumptions regarding sustained energy demand and technological advancements. Revision becomes warranted when major offshore investment cycles cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market