
 Seismic Support Vessels Market | 2026-2036
Seismic Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Seismic Support Vessels Market Analytics
IMO Tier III certification is bifurcating the competitive landscape between compliant newbuilds and legacy fleets facing obsolescence. Ulstein Group ASA leverages its X-BOW hull technology to sustain premium positioning in harsh-environment contracts. Damen Shipyards Group anchors European supply through standardized platform variants that compete aggressively on delivery timelines. Cemre Shipyard specializes in mid-size multipurpose conversions that occupy a growing niche between purpose-built and retrofitted assets.
Seismic support vessels are specialized offshore craft designed to tow streamer arrays, deploy ocean-bottom nodes, and sustain geophysical survey operations across variable water depths; modern units integrate dynamic positioning class 2 or 3 systems with acoustic source arrays rated for 3,000+ meter operations. The primary commercial purpose centers on enabling hydrocarbon discovery and subsea infrastructure mapping for energy producers and their contracted geophysical service providers. Deep water deployment leads value generation as frontier basins in Brazil, West Africa, and Southeast Asia push equipment specifications toward higher channel counts and extended tow spreads. Multi-purpose vessels represent the fastest-growing vessel type as operators consolidate fleet counts and demand modular reconfigurability between survey, supply, and light intervention roles. Geophysical surveys command the largest service-type revenue pool, though data acquisition margins compress where vessel oversupply concentrates in mature basins.
The International Maritime Organization shapes newbuild demand through successive emission-control area expansions and the Energy Efficiency Existing Ship Index, while flag-state regulators such as Norway's Maritime Authority and the US Coast Guard enforce national safety standards that limit market access for non-compliant operators. Classification societies including DNV and ABS further constrain design freedom through revised rules for offshore support vessel structural integrity and station-keeping reliability. Stakeholders must monitor how emerging carbon-border adjustments and EU emissions trading scheme extension to maritime transport reshape total cost of ownership calculations for fleet investment decisions.
Market Dynamics
The International Maritime Organization's Carbon Intensity Indicator is forcing seismic operators to retire older tonnage and accelerate newbuild orders with hybrid-electric propulsion architectures.
Growth Catalysts
- Deepwater Frontier Expansion:Brazil's pre-salt basins and West African ultra-deepwater blocks are extending towed-streamer operations beyond 3,000 meters, requiring vessels with enhanced dynamic positioning and expanded deck capacity for longer spreads.
- EU Emissions Trading Scheme Extension:Maritime transport inclusion under the EU ETS from 2024 is creating compliance-driven replacement demand among European-flagged fleets operating in the North Sea and Atlantic margins.
- Ocean-Bottom Node Deployment:Seabed seismic acquisition for carbon capture site characterization and reservoir monitoring is pulling vessel days toward node-handling configurations with integrated ROV systems.
Market Restraints
- Steel and Specialized Equipment Cost Volatility:Hull-grade steel plate and high-channel-count streamer winch systems face supply tightness from limited European and Asian fabricators, compressing newbuild margins.
- Engine Maker Concentration:Medium-speed marine diesel and hybrid powertrain supply concentrates among a handful of European and Japanese manufacturers, creating delivery bottlenecks for Tier III-compliant propulsion packages.
- Technical Obsolescence of Legacy Fleets:Pre-2010 vessels lacking DP-3 redundancy and integrated bridge systems cannot access contracts in Norway's Maritime Authority jurisdiction or Equinor's vendor qualification framework.
Strategic Opportunities
- Southeast Asian Basin Development:Indonesia's North Sumatra and Vietnam's Nam Con Son basins remain underpenetrated by modern 3D seismic coverage, offering first-mover positioning for vessels with shallow-draft node deployment capability.
- Carbon Storage Site Surveying:Offshore CO2 injection projects in the UK North Sea and Norwegian Continental Shelf are generating demand for high-resolution 4D seismic monitoring using reconfigurable multi-purpose platforms.
- Hybrid Propulsion Convergence:Battery-electric peak shaving combined with dual-fuel methanol engines is opening technical differentiation for newbuilds targeting Norway's NOx fund incentives and future fuel flexibility requirements.
Industry Challenges
- Dynamic Positioning Officer Shortage:DP-2 and DP-3 certification holders are concentrated among aging workforces in Norway and Scotland, constraining fleet expansion despite vessel availability.
- Class Society Compliance Timelines:DNV's revised offshore vessel structural integrity rules and ABS station-keeping notations are extending design approval cycles by 8-12 months for novel hull forms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seismic Support Vessels Market |
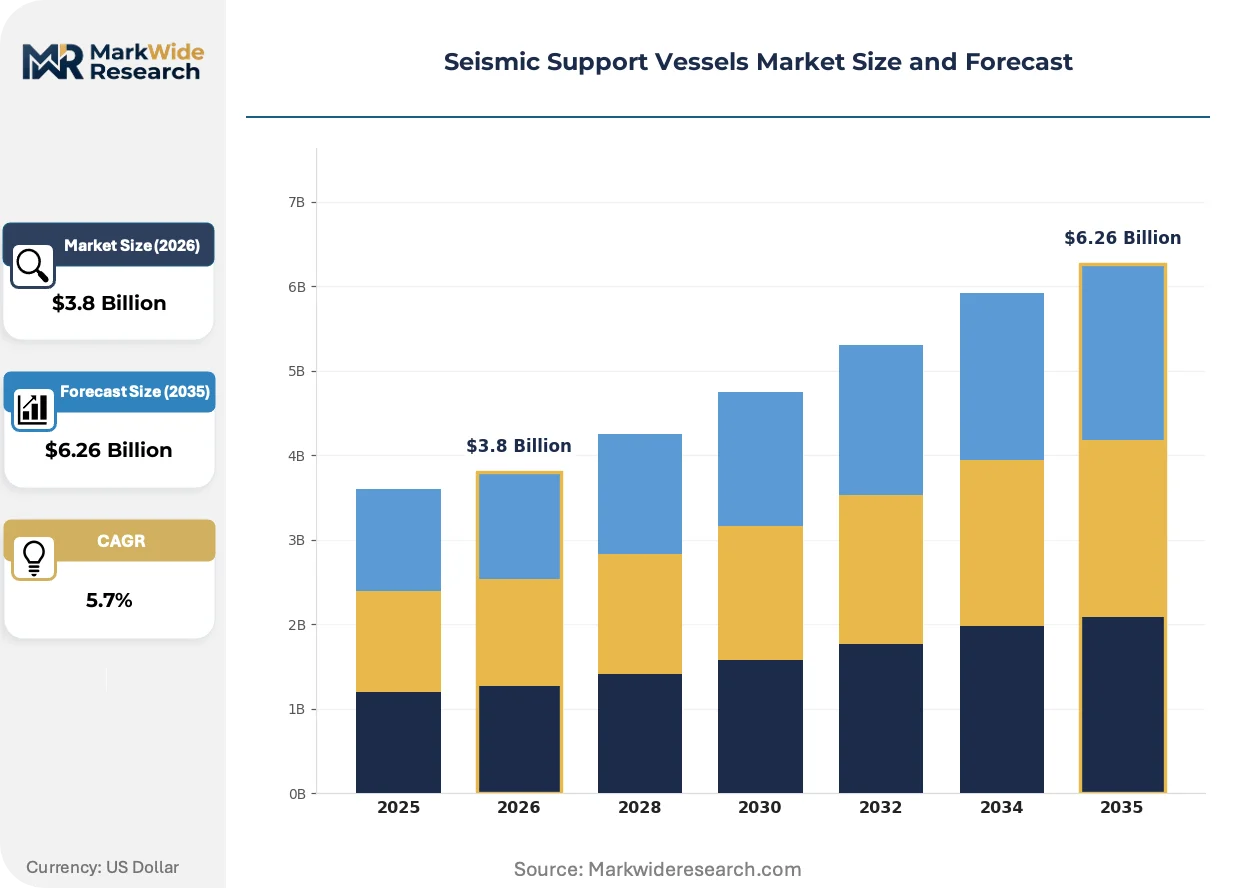
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Multi-purpose Vessels, Supply Vessels, Survey Vessels, Tugs Service Type: Geophysical Surveys, Support Services, Mobilization, Data Acquisition Deployment Model: Onshore Operations, Offshore Operations, Shallow Water Deployment, Deep Water Deployment End User: Energy Companies, Contractors, Research Organizations, Government Agencies |
| Companies Covered | Ulstein Group ASA, Damen Shipyards Group, Cemre Shipyard, Tananger Offshore AS, Rederij Groen, Naval Dynamics, Sanco Shipping AS, Salt Ship Design, Swire Pacific Offshore Operations (Pte) Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seismic Support Vessels Market Evolving Landscape
Propulsion architecture, regulatory compliance frameworks, and charter contracting models are simultaneously restructuring how seismic support vessels are specified, financed, and deployed across frontier and mature basins.
Modular streamer handling systems are miniaturizing. Compact winch arrays with integrated tension monitoring now fit within reduced deck footprints, enabling smaller vessel platforms to execute surveys previously requiring larger tonnage. Independent geophysical contractors in West Africa are adopting these configurations to reduce day-rate exposure on frontier blocks with uncertain commercial timelines. The technology is compressing minimum efficient scale for 3D acquisition, fragmenting contract award patterns toward lower-capital entrants.
REACH regulation amendments targeting persistent organic pollutants in marine lubricants and hydraulic fluids are restricting fluid formulations used in subsea handling equipment. European-flagged vessels must now document fluid chain-of-custody from supplier to disposal, adding administrative burden but creating compliance service revenue for technical management firms. Norwegian-registered fleets face the strictest enforcement timelines, with Maritime Authority audits expanding to cover hydraulic system maintenance records.
Charterers are unbundling vessel supply from data acquisition services, separating the maritime transport contract from geophysical execution. Supermajors now tender vessel provision independently from seismic processing, forcing shipowners to negotiate directly with energy company procurement functions rather than through integrated geophysical service providers. This pattern is most visible in UK and Norwegian North Sea tenders, where BP and Shell have restructured supplier segmentation to isolate marine asset risk from survey technical risk.
Seismic Support Vessels Market Segmentation
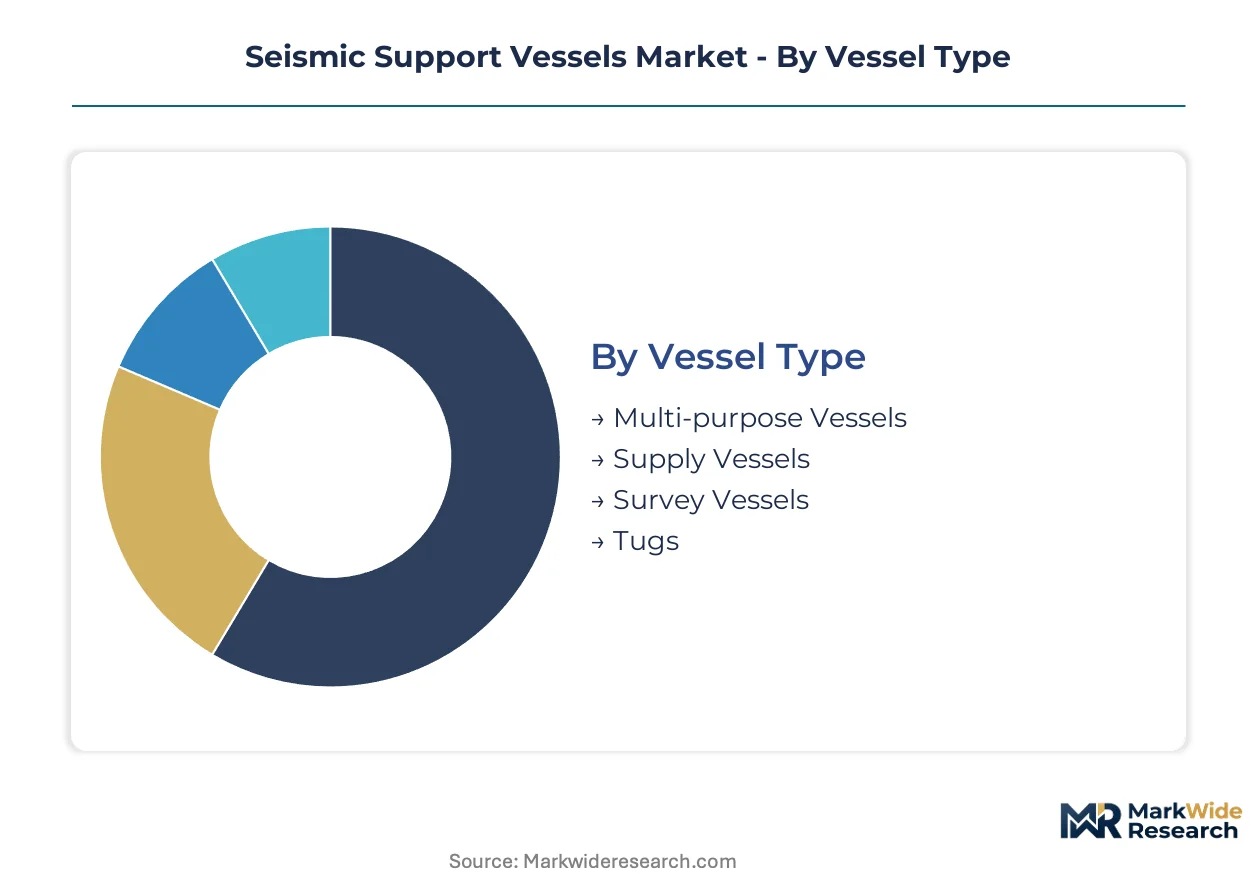
Segmentation in seismic support vessels reveals how technical specifications, contract structures, and regulatory exposure split margin pools across fundamentally different operational profiles. Understanding these divisions exposes where fleet owners can defend pricing power and where commoditization pressures concentrate.
Vessel Type:
Margin pools concentrate in vessels capable of multi-mission reconfiguration, where charterers pay premiums for operational flexibility across survey, supply, and intervention roles.
- Multi-purpose Vessels:Modular deck layouts accommodate rapid reconfiguration between streamer towing, ocean-bottom node deployment, and light subsea construction. Demand clusters in Norway's North Sea sector where Equinor and Aker BP consolidate vendor lists around vessels qualified for multiple contract types under single charter agreements.
- Survey Vessels:Purpose-built hulls integrate permanently mounted source arrays and high-channel-count streamer winches rated for 3,000-meter operations. Brazil's pre-salt basins and West African ultra-deepwater blocks absorb the majority of newbuild deliveries as Petrobras and TotalEnergies extend towed-streamer campaigns into frontier depths.
- Supply Vessels:General cargo and deck capacity configurations support seismic crew transfer, fuel bunkering, and equipment resupply without dedicated survey equipment. These units compete on day-rate efficiency in mature basins where survey activity runs on predictable schedules.
- Tugs:Escort and anchor-handling specifications serve pre-positioning and recovery of floating seismic spreads in harsh weather windows. North Sea and Barents Sea operations drive specification requirements for bollard pull and ice-class notation.
Survey Vessels holds installed capacity. Multi-purpose Vessels is rotating up the share rankings.
Service Type:
Revenue concentration follows the technical intensity of data collection, with front-end geophysical execution commanding multiples over logistics and mobilization functions.
- Geophysical Surveys:Towed-streamer and ocean-bottom seismic acquisition generates the largest revenue pool through integrated contracts combining vessel provision, source operation, and data quality control. Compression in day-rate spreads occurs where vessel oversupply concentrates in mature North Sea and Gulf of Mexico basins.
- Data Acquisition:Real-time quality control, positioning verification, and initial processing aboard vessel-mounted computing infrastructure. Frontier campaigns in Southeast Asia and East Africa require 24/7 acquisition uptime, pulling vessel specifications toward redundant systems and expanded technician quarters.
- Support Services:Equipment maintenance, crew rotation logistics, and supply chain coordination without direct survey execution. These functions face margin pressure as supermajors unbundle maritime transport from technical services in UK and Norwegian tender restructuring.
- Mobilization:Port-to-field transit, equipment load-out, and spread configuration before survey commencement. Contract structures increasingly separate mobilization fees from day-rates, exposing owners to utilization risk on distant frontier deployments.
Geophysical Surveys retains the deepest contract backlog. Data Acquisition is climbing the fastest as real-time processing requirements intensify.
Deployment Model:
Water depth thresholds determine equipment specifications and regulatory jurisdiction, with frontier deepwater commanding technology premiums and shallow water facing day-rate commoditization.
- Deep Water Deployment:Operations beyond 1,000 meters require dynamic positioning class 2 or 3 redundancy, extended streamer spreads, and acoustic source arrays rated for high-pressure environments. Brazil's pre-salt province and West African conjugate margins absorb the majority of qualified tonnage.
- Offshore Operations:General classification for field activities outside territorial baselines, subject to flag-state safety enforcement and IMO emission control area regulations. European-flagged fleets face accelerated compliance timelines under EU ETS maritime inclusion.
- Shallow Water Deployment:Draft-limited operations in coastal zones and continental shelf environments using smaller vessels with portable equipment packages. Indonesia's North Sumatra basin and Vietnam's Nam Con Son blocks present underpenetrated opportunities for shallow-draft node deployment.
- Onshore Operations:Land-based seismic crew support and equipment staging without vessel involvement, relevant for transition zone surveys and coastal logistics coordination.
Deep Water Deployment holds the premium contract tier. Shallow Water Deployment is gaining share fastest as Southeast Asian frontier licensing accelerates.
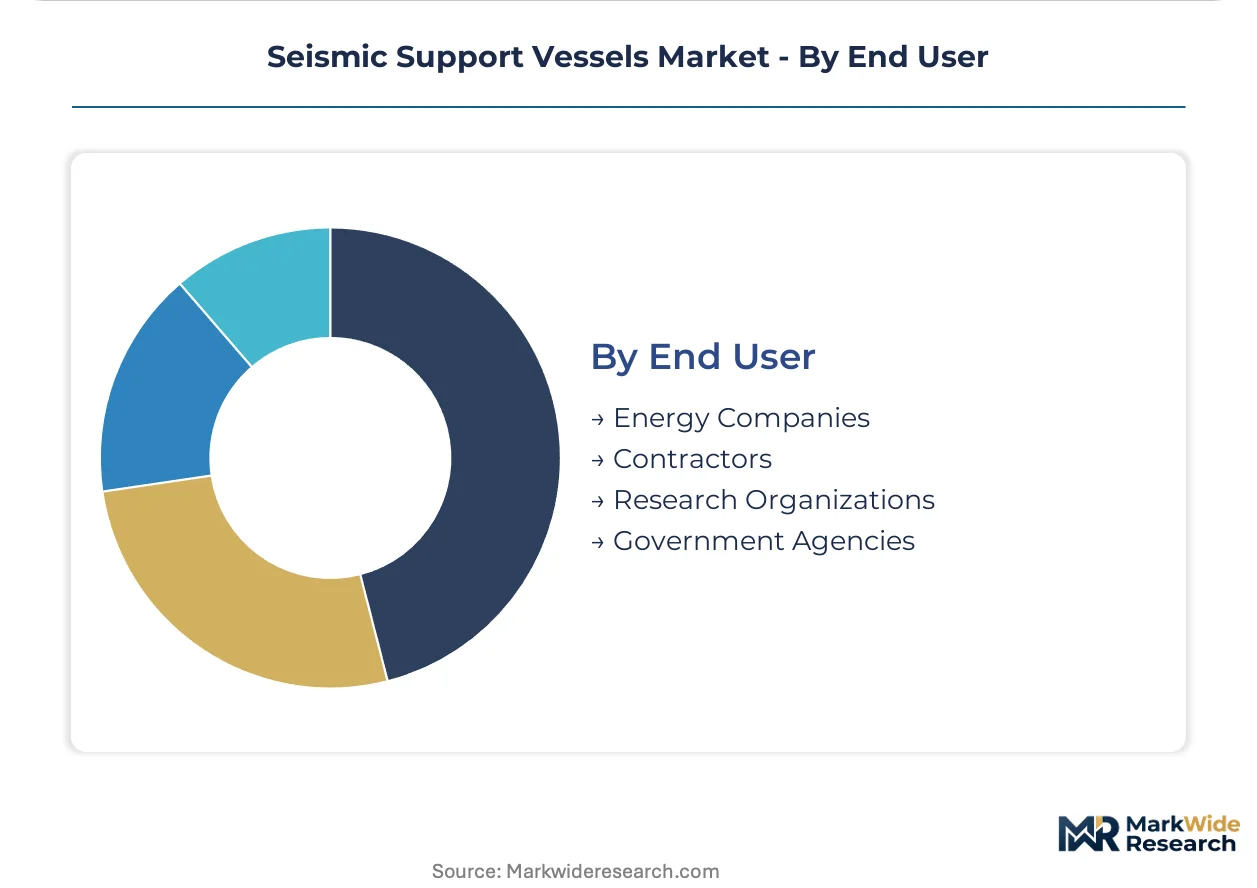
End User:
Procurement authority and risk tolerance diverge sharply between integrated energy companies, contracted service providers, and public-sector research bodies.
- Energy Companies:Supermajors including BP, Shell, and Equinor directly charter vessels for proprietary survey programs, increasingly unbundling maritime supply from geophysical execution in segmented tender structures. These entities enforce the strictest qualification frameworks around safety, emissions, and local content.
- Contractors:Independent geophysical service providers including TGS, PGS, and Shearwater GeoServices operate multi-vessel fleets on speculative multi-client surveys or exclusive contracts. These operators face capital intensity pressures and vessel utilization optimization challenges.
- Government Agencies:National oil companies and geological survey organizations commission basin-wide mapping for licensing round preparation and resource assessment. Brazil's ANP and Norway's NPD drive recurring demand for regional 3D coverage.
- Research Organizations:Academic and environmental monitoring programs requiring vessel access for seabed characterization, carbon storage site assessment, and climate research infrastructure deployment.
Energy Companies command the dominant procurement volume. Contractors is rotating up the share rankings as multi-client speculative surveys expand in frontier basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's NOx fund incentives and the EU Emissions Trading Scheme maritime extension are accelerating fleet renewal decisions across North Sea and Atlantic margin operators. Brazil's ANP licensing rounds and West African ultra-deepwater concessions are pulling vessel specifications toward frontier-depth capabilities.
Norway
Equinor and Aker BP consolidate vendor lists around multi-mission vessels qualified for integrated charter agreements. The Norwegian Maritime Authority enforces DP-3 redundancy requirements that exclude pre-2010 tonnage from contract access. Bergen and Stavanger anchor the North Sea cluster where seismic survey activity remains dense and NOx fund rebates incentivize hybrid-electric newbuilds.
Brazil
Petrobras extends towed-streamer campaigns into pre-salt blocks beyond 3,000 meters, demanding enhanced dynamic positioning and expanded deck capacity. ANP licensing rounds for frontier acreage generate recurring demand for regional 3D coverage. Rio de Janeiro concentrates vessel provisioning and subsea equipment logistics for Atlantic margin operations.
United Kingdom
BP and Shell restructure supplier segmentation to unbundle maritime transport from geophysical execution in segmented tender structures. The UK North Sea Transition Authority oversees carbon storage site licensing that pulls vessel days toward 4D seismic monitoring contracts. Aberdeen maintains its position as the primary marine asset coordination hub for UK continental shelf activity.
United States
Gulf of Mexico day-rate compression concentrates where vessel oversupply meets mature basin survey schedules. The US Coast Guard enforces national safety standards that limit market access for non-compliant foreign-flagged operators. Houston hosts the primary procurement functions for supermajor seismic program planning and vendor qualification.
Indonesia
North Sumatra basin licensing remains underpenetrated by modern 3D seismic coverage, offering first-mover positioning for shallow-draft node deployment. The country's national oil company commissions basin-wide mapping for licensing round preparation. Jakarta and Batam cluster vessel agency services and equipment staging for Southeast Asian frontier campaigns.
Seismic Support Vessels Market Competitive Landscape
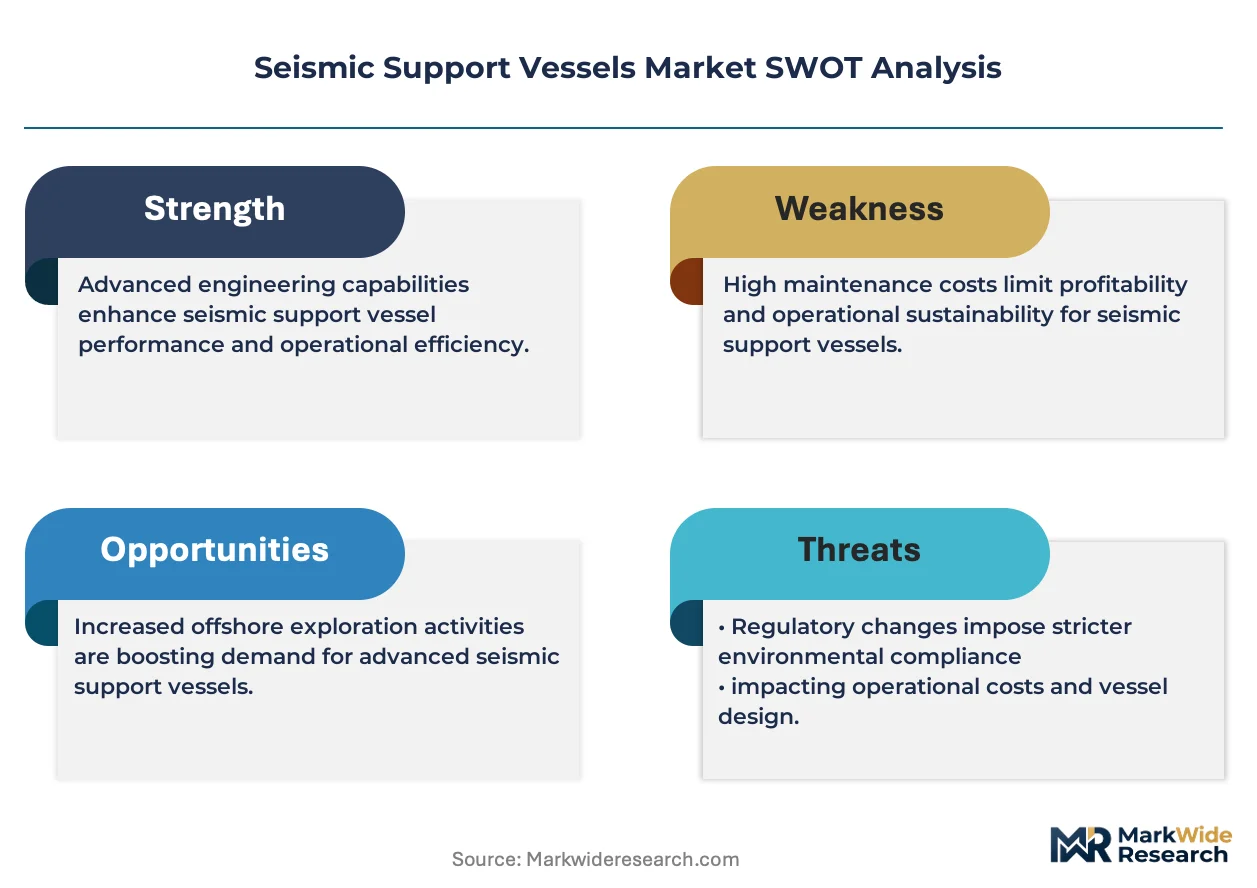
Listed leaders compete with private specialists across capital access and contract flexibility dimensions. The vendor base splits between consolidated European shipyards with integrated design-build capabilities and fragmented regional fabricators competing on delivery speed. Three archetypes dominate: premium newbuild specialists with proprietary hull technologies, standardized platform producers optimizing production economies, and conversion yards occupying niches between purpose-built and retrofitted assets. Competitive moves concentrate on hybrid propulsion differentiation and strategic partnerships for Tier III engine package procurement.
Among Norwegian design-build specialists, Ulstein Group ASA and Salt Ship Design occupy positions defined by harsh-environment hull form innovation. Damen Shipyards Group anchors European supply through standardized platform variants. Cemre Shipyard exemplifies the mid-size conversion specialist archetype serving modular reconfigurability demand.
| Leading Market Players |
|---|
| Ulstein Group ASA |
| Damen Shipyards Group |
| Cemre Shipyard |
| Tananger Offshore AS |
| Rederij Groen |
| Naval Dynamics |
| Sanco Shipping AS |
| Salt Ship Design |
| Swire Pacific Offshore Operations (Pte) Ltd |
| Others |
Value Network & Pricing Analysis
IMO Tier III certification gates both yard qualification and day-rate premiums simultaneously, compressing contract access for non-compliant operators while rewarding Norwegian and Dutch newbuilds with NOx fund-eligible propulsion packages. Charterers now segment vendor lists around emission-grade tiers that directly map to pricing bands.
Pricing Analysis
Certification level creates the primary spread between DP-3 redundant newbuilds and pre-2010 legacy tonnage. Three-tier pricing structure across premium, standard, and economy levels reflects dynamic positioning class, emission compliance grade, and hull ice notation. Cost compression in the standard tier is intensifying because European-flagged fleets face EU ETS maritime inclusion from 2024. Contractors operating speculative multi-client surveys exhibit highest price sensitivity; supermajors with proprietary programs show lowest.
Supply Chain Analysis
Strait of Hormuz transit underwrites fuel oil delivery to West African and Southeast Asian operating bases, exposing fleets to bunker cost volatility and geopolitical disruption. Hull-grade steel plate concentrates in South Korea, Japan, and China; medium-speed marine diesel and hybrid powertrain supply anchors in Germany, Finland, and Japan. Single-source vulnerability concentrates around Tier III engine package procurement from a handful of European and Japanese manufacturers. Distribution runs through integrated shipyard-procurement functions rather than spot market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seismic support vessels sit in early-cycle expansion as offshore CO2 storage site characterization pulls vessel days toward 4D monitoring contracts. Frontier basin licensing in Southeast Asia and West Africa extends penetration runway for qualified tonnage.
For Market Incumbents: Fortify DP-3 redundancy coverage across existing fleets to maintain Equinor and Aker BP vendor list access as Norwegian Maritime Authority enforcement tightens. Accelerate hybrid-electric retrofits on 2015-2020 tonnage to capture NOx fund rebates before incentive pools deplete. Anchor backward integration into battery-electric peak shaving systems to reduce engine maker concentration risk.
For New Entrants and Emerging Players: Anchor in Indonesia's North Sumatra basin and Vietnam's Nam Con Son blocks where shallow-draft node deployment capability remains scarce. Target government agency survey tenders from Brazil's ANP and Norway's NPD that prioritize local content over fleet scale. Pursue conversion yard partnerships with Turkish or Southeast Asian fabricators to compress delivery timelines against European newbuild competition.
For Investors and Strategic Acquirers: EU ETS maritime extension reshapes the acquisition landscape toward emission-compliant assets with verified carbon intensity trajectories. Long-term viability centers on vessels with methanol-ready dual-fuel architecture and modular deck configurations spanning survey, supply, and light intervention roles. Monitor Norwegian Maritime Authority audit expansion as the inflection signal for legacy fleet stranding risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Retrofit | NOx fund rebates in Norway improve newbuild economics against legacy tonnage. |
| Modular Deck Reconfiguration Capability | Multi-mission flexibility commands premium day-rates from Equinor integrated charters. |
| Tier III Engine Package Partnership | Dual-fuel methanol readiness future-proofs vessels against EU ETS compliance costs. |
| Ocean-Bottom Node Handling Integration | Carbon storage site surveying pulls vessel specifications toward ROV-equipped configurations. |
| DP-3 Redundancy Certification Investment | Norwegian Maritime Authority rules exclude pre-2010 tonnage from contract access. |
Research Methodology
The analysis maps multi-purpose vessel configurations, survey vessel specifications, and supply vessel platforms, each validated through vessel operators, shipyard procurement directors, chartering managers at supermajors, and classification society surveyors. Primary interviews with fleet managers at TGS, PGS, and Shearwater GeoServices combined with secondary validation from DNV vessel registers, IMO emission control area databases, ANP licensing round documentation, and EU ETS maritime extension regulatory filings. Bottom-up vessel deployment counts triangulated against top-down energy company capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include vessel type, service intensity tier, water depth deployment threshold, and end-user procurement authority. CAGRs derived from fitted trend extrapolation with cross-validation against fleet orderbook pipelines and regulatory compliance timelines. Industry-specific forecast inputs encompass ANP licensing round schedules and Norwegian NOx fund incentive trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained offshore exploration licensing and EU ETS maritime enforcement; material deviation in carbon border adjustment scope or frontier basin resource assessment would warrant model refresh. Practitioners should keep alternative scenarios live as hybrid propulsion technology costs and battery-electric range capabilities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Ship Gangways Market