
 Offshore Pipeline Market | 2026-2036
Offshore Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Pipeline Market Analysis
Subsea fabrication yards on the US Gulf Coast is expanding welded pipe output to meet pre-salt and deepwater project timelines. TechnipFMC plc leverages integrated engineering-to-installation capabilities across flexible pipe systems. Shell anchors its project portfolio with proprietary high-pressure, high-temperature designs for ultra-deepwater fields. Samsung Engineering competes on Korean yard capacity and modular construction discipline for export pipeline contracts.
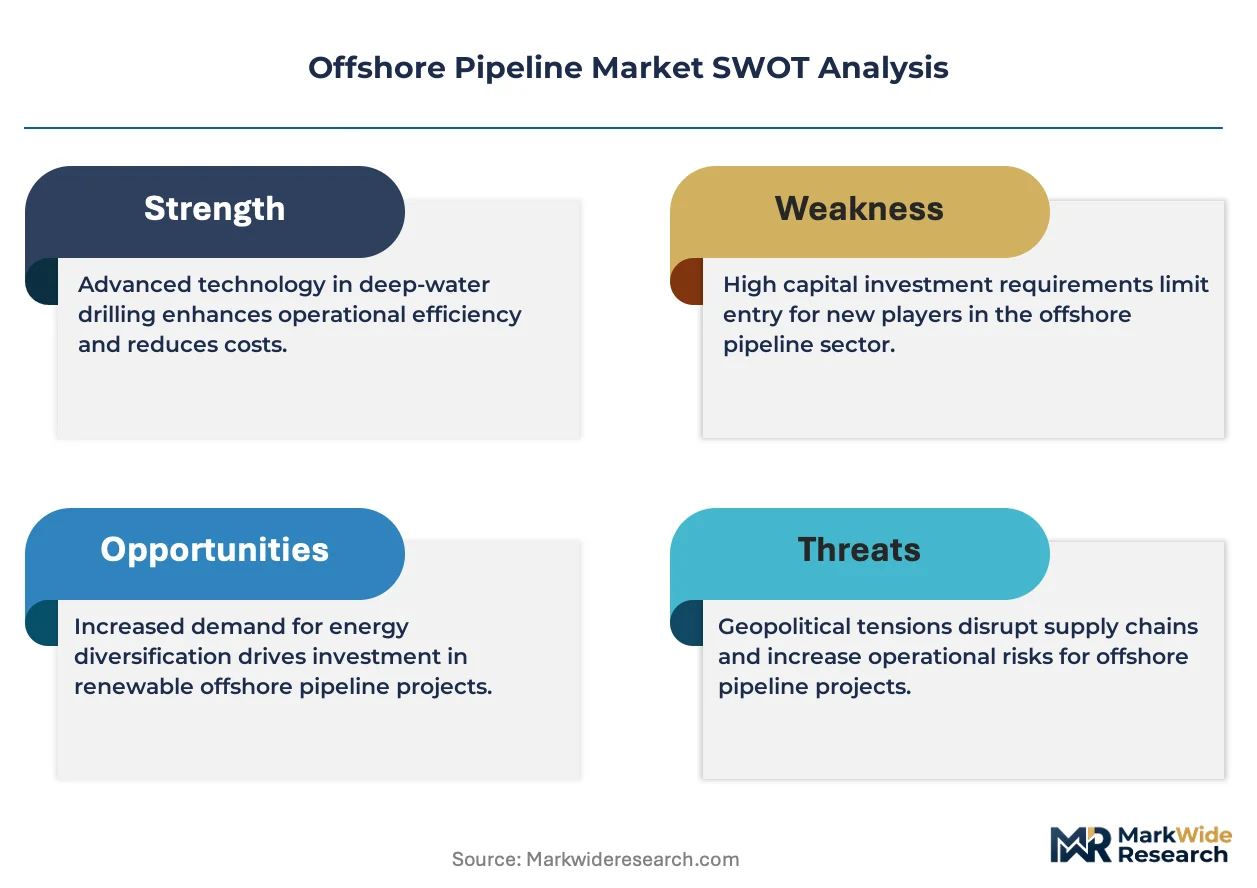
Offshore pipeline denotes subsea conduits—typically carbon steel or corrosion-resistant alloy, with diameters ranging from 6 to 48 inches and wall thickness engineered to withstand hydrostatic pressures exceeding 300 bar—transporting hydrocarbons from wellheads to platforms or shore terminals. Steel pipes dominate capital expenditure due to established metallurgy and deepwater pressure ratings, while flexible pipes capture tieback growth where dynamic riser configurations and vessel motion tolerance prove essential. Installation method selection shapes project economics: S-lay vessels handle trunkline scale in shallow-to-mid water, whereas J-lay systems access depths beyond 2,500 meters where rigid steel remains necessary.
The American Petroleum Institute governs material specifications and welding protocols for US-destined projects, while Brazil's national petroleum regulator enforces local content thresholds that redirect procurement toward domestic pipe mills and installation fleets. The International Maritime Organization's subsea infrastructure guidelines further constrain routing and environmental impact assessments. Stakeholders must weigh regulatory compliance costs against the technical limits of emerging composite materials as they allocate capital across water depth thresholds and field development architectures.
Market Dynamics
Deepwater field development economics are compressing tieback distances and forcing pipeline specifications toward higher pressure ratings, with Brazil's pre-salt discoveries and Gulf of Mexico ultra-deepwater plays demanding metallurgical advances that outpace standard carbon steel capabilities.
Growth Catalysts
- Pre-salt development mandates:Brazil's national petroleum regulator enforces local content thresholds that redirect procurement toward domestic pipe mills and installation fleets, creating captive demand for specialized subsea infrastructure.
- API specification tightening:The American Petroleum Institute's updated offshore construction standards are tightening material certification requirements, elevating demand for corrosion-resistant alloys in high-pressure, high-temperature applications.
- Flexible pipe technology:Dynamic riser configurations and vessel motion tolerance in deepwater tiebacks are accelerating adoption of non-metallic flexible systems where rigid steel proves impractical.
Market Restraints
- Alloy supply concentration:Corrosion-resistant alloy production concentrates in a limited number of specialized mills, creating input cost volatility and extended lead times for project procurement.
- Installation vessel scarcity:J-lay and reel-lay vessel availability constraints in the North Sea and US Gulf Coast limit project execution capacity during peak demand windows.
- Composite material limitations:Thermoplastic composite pipes face pressure rating ceilings below 300 bar that exclude them from ultra-deepwater trunkline applications despite weight advantages.
Strategic Opportunities
- West African frontier basins:Underexplored deepwater provinces off Senegal and Mauritania present first-mover pipeline infrastructure requirements as development plans advance.
- Electrification tieback networks:Subsea power cable and pipeline bundle installations are converging with offshore wind export systems, opening integrated engineering contracts.
- EU methane emissions regulation:The European Union's methane performance standards create retrofit demand for leak detection systems and pipeline integrity monitoring across North Sea infrastructure.
Industry Challenges
- Welding inspector certification backlog:API 1104 and ASME Section IX qualified welder availability lags project ramp schedules, extending fabrication timelines at Gulf Coast yards.
- Legacy platform integration:Brownfield tieback designs must accommodate incompatible flange specifications and pressure ratings from 1980s infrastructure without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Pipeline Market |
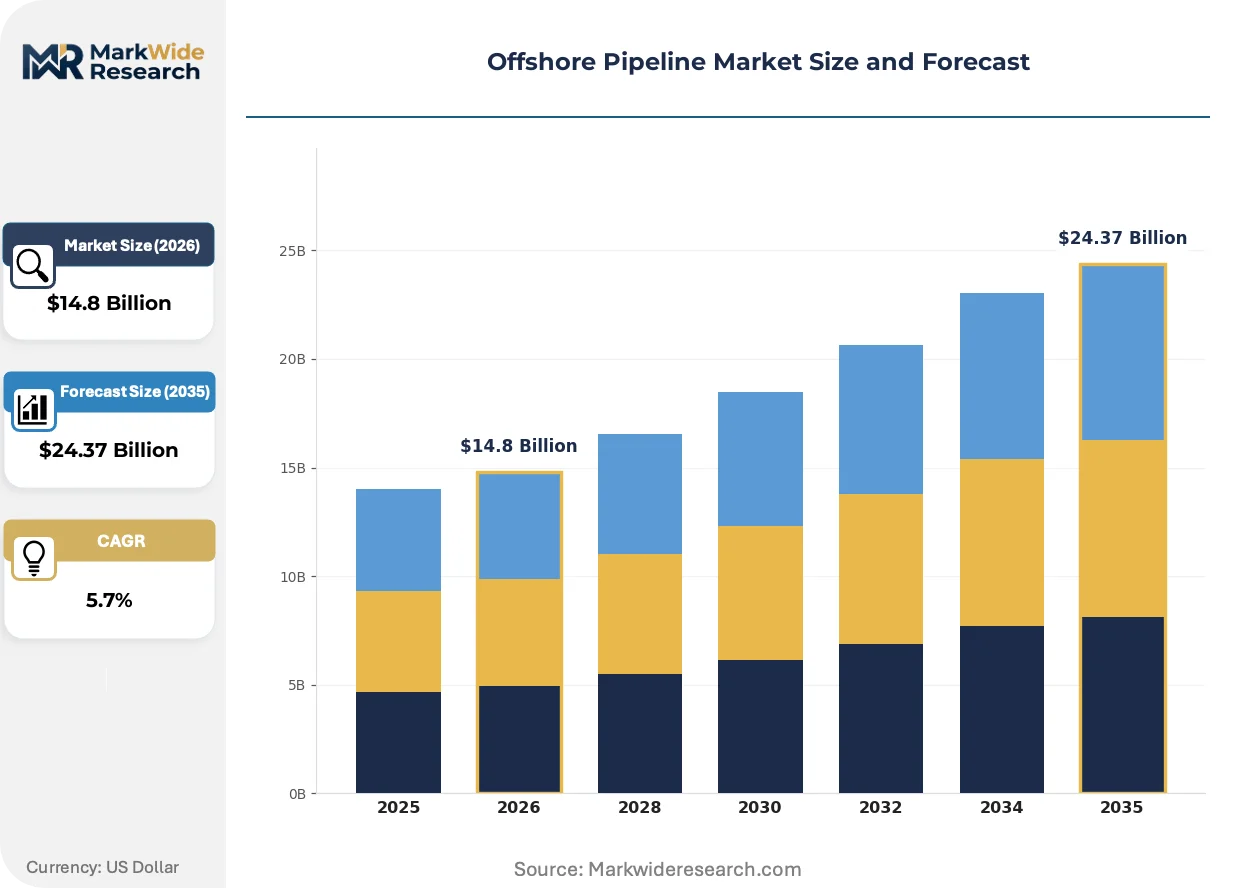
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Pipes, Composite Pipes, Flexible Pipes, Subsea Systems Installation Method: Trenching, S-Lay, J-Lay, Tow Method End User: Oil & Gas Companies, Utility Providers, Engineering Firms, Contractors Service Type: Installation Services, Inspection Services, Maintenance Services, Consulting Services |
| Companies Covered | Primoris, QatarEnergy, TechnipFMC plc, YPF SA, Shell, Bechtel Corporation, Woodside Energy Group, Samsung Engineering, Bonatti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Pipeline Market Emerging Trajectories
Subsea pipeline engineering is pivoting from commodity steel procurement toward integrated system design, with metallurgy, installation method, and digital monitoring converging into unified performance contracts that redefine supplier-customer relationships.
Corrosion-resistant alloy cladding is converging with standard carbon steel substrates to create hybrid pipe systems that withstand sour gas environments without full CRA construction. Major operators in Brazil's pre-salt fields specify these metallurgical sandwiches for cost-sensitive deepwater trunklines. The technology is converging with automated welding protocols that reduce field joint costs by half compared to solid CRA alternatives.
The International Maritime Organization's subsea infrastructure guidelines are constraining routing and environmental impact assessments, extending permitting timelines by 12-18 months for projects traversing sensitive marine habitats. Pipeline developers must now incorporate real-time monitoring commitments and decommissioning bonds into front-end engineering. Gulf of Mexico operators are responding by clustering developments around existing corridor infrastructure to minimize new seabed disturbance.
Integrated service contracts are displacing discrete equipment procurement as the dominant commercial model for complex deepwater developments. Operators bundle pipeline engineering, installation, and integrity management into decade-long performance agreements with single-source suppliers. This consolidation is most visible in Norway's continental shelf, where Equinor and Aker BP have shifted procurement authority from project teams to centralized supply chain functions.
Offshore Pipeline Market Segmentation
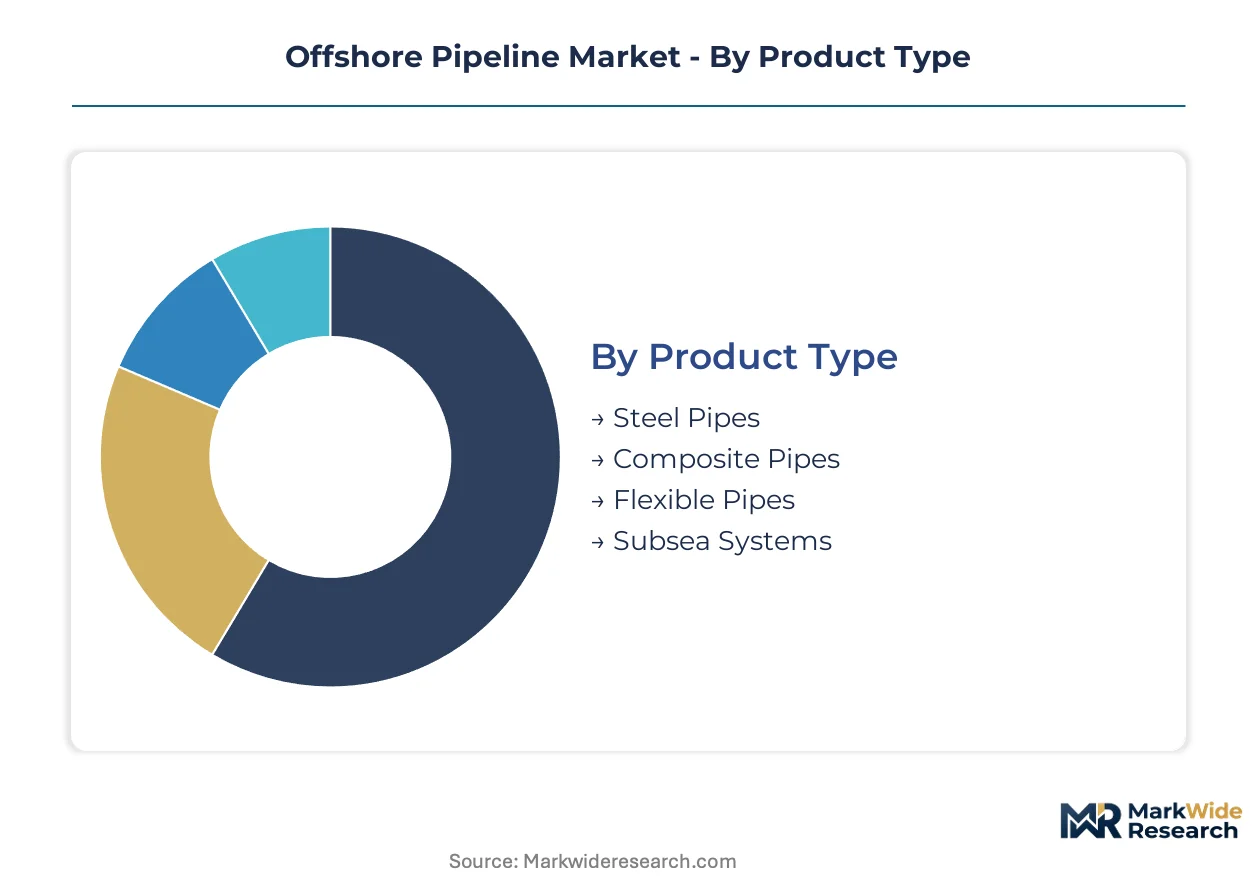
Pipeline procurement decisions hinge on water depth, pressure specifications, and field architecture. Each segmentation dimension carries distinct capital requirements, regulatory exposure, and supplier qualification thresholds that reshape project economics.
Product Type:
Capital intensity peaks with metallurgical complexity and pressure rating requirements across subsea conduit categories.
- Steel Pipes:Carbon steel and corrosion-resistant alloy substrates dominate trunkline specifications for depths exceeding 2,500 meters. Brazil's pre-salt developments and Gulf of Mexico ultra-deepwater fields anchor procurement volumes where hydrostatic pressures exceed 300 bar.
- Flexible Pipes:Non-metallic dynamic riser systems integrate polymer barrier layers and tensile armor wires for vessel motion tolerance. Demand concentrates in tieback networks off West Africa and Southeast Asia where rigid steel proves impractical for floating production connections.
- Composite Pipes:Thermoplastic reinforced conduits offer weight advantages for shallow-water gathering lines. ANVISA certification requirements in Brazil and API specifications in the United States constrain adoption below pressure thresholds.
- Subsea Systems:Bundled pipeline, umbilical, and riser configurations reduce interface risk for integrated field developments. Norwegian continental shelf operators specify these packages for brownfield tieback efficiency.
Most installed capacity flows through Steel Pipes. Expansion is steepest in Flexible Pipes.
Installation Method:
Contractor fleet specialization and day-rate structures segment project execution economics by water depth and pipeline diameter.
- S-Lay:Stovage and welding aboard conventional vessels suits shallow-to-mid water trunklines up to 48-inch diameter. US Gulf Coast yards deploy this method for Gulf of Mexico corridor infrastructure where seabed gradients permit.
- J-Lay:Near-vertical pipe departure enables access beyond 2,500 meters with minimal bending stress. Vessel scarcity in the North Sea and Asia-Pacific creates procurement bottlenecks for ultra-deepwater schedules.
- Trenching:Post-lay burial operations protect against fishing gear interaction and hydrodynamic instability. Regulatory mandates from the International Maritime Organization drive adoption across North Sea export routes.
- Tow Method:Pre-assembled pipeline strings towed to site reduce offshore welding exposure. Suitable for short tiebacks in benign metocean conditions off West Africa.
Project volume runs heaviest through S-Lay. J-Lay commands premium day rates and steepest expansion trajectory.
End User:
Risk allocation and procurement authority patterns diverge between asset owners and service intermediaries.
- Oil & Gas Companies:Integrated majors and national oil companies retain engineering specification authority for proprietary high-pressure designs. Shell and Equinor centralize supply chain decisions for decade-long performance agreements.
- Engineering Firms:TechnipFMC and Subsea 7 bundle design, procurement, and installation under integrated EPIC contracts. These arrangements displace discrete equipment purchasing in complex deepwater developments.
- Contractors:Installation specialists assume execution risk through lump-sum turnkey structures. Brazilian local content thresholds redirect procurement toward domestic fleet operators.
- Utility Providers:Offshore wind export cable and pipeline convergence creates hybrid infrastructure demand. North Sea electrification projects drive bundled procurement with subsea power distribution.
Procurement volume concentrates with Oil & Gas Companies. Engineering Firms are capturing share fastest through integrated service models.
Service Type:
Revenue recurrence and margin stability separate one-time installation from multi-decade integrity obligations.
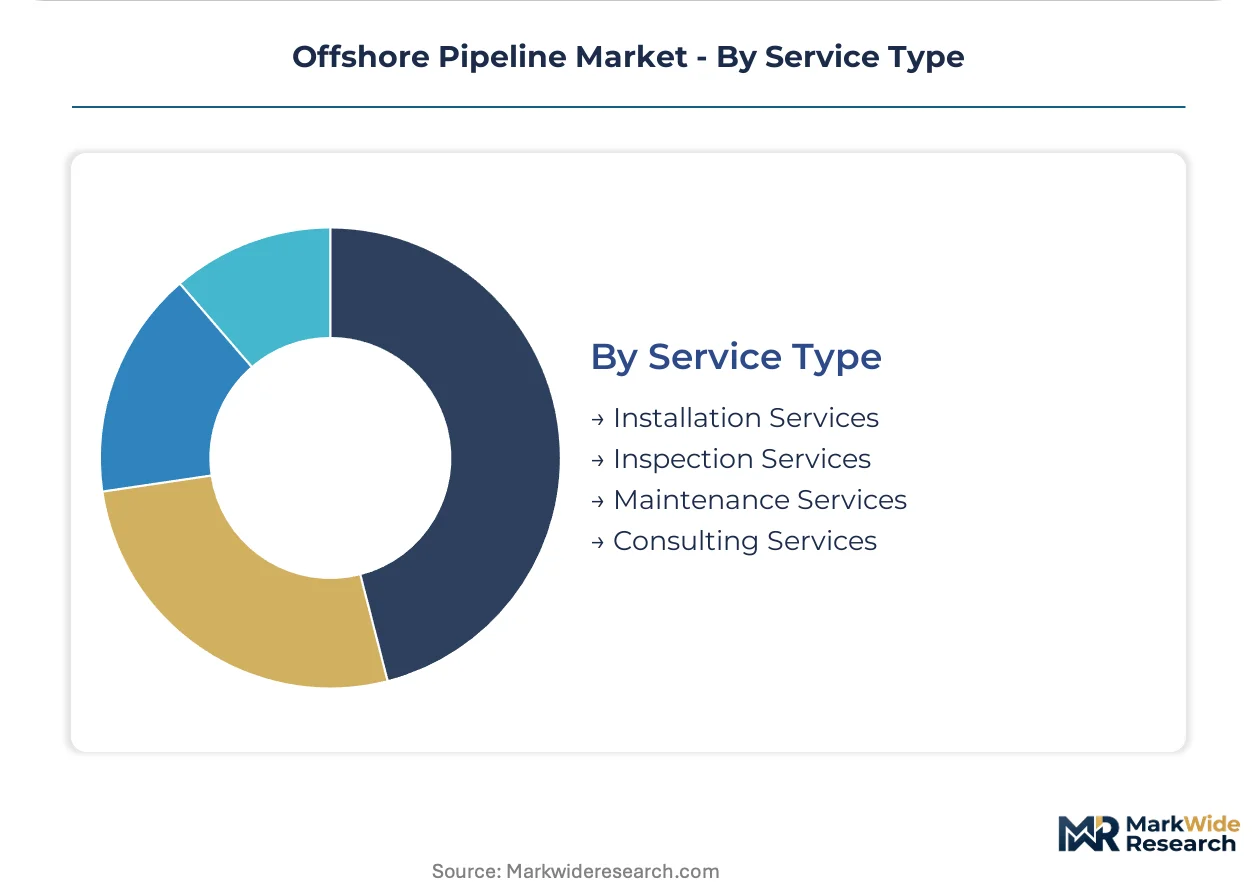
- Installation Services:Vessel mobilization, welding, and commissioning represent front-loaded capital deployment. Project timing concentrates in Brazil's pre-salt campaign windows and Gulf of Mexico lease sale cycles.
- Maintenance Services:Corrosion inhibition, pigging operations, and repair interventions generate recurring revenue across asset lifespans. EU methane emissions regulation creates retrofit demand for North Sea infrastructure.
- Inspection Services:Intelligent pigging and autonomous underwater vehicle surveys verify pipeline integrity. Real-time monitoring commitments now feature in front-end engineering designs.
- Consulting Services:Route selection, permitting support, and decommissioning planning extend professional service engagement. International Maritime Organization guidelines extend environmental assessment timelines.
Revenue scale peaks with Installation Services. Maintenance Services deliver the most predictable long-term margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt fields generate pipeline demand volumes that dwarf Norway's North Sea maintenance cycle, while the US Gulf Coast concentrates installation capacity for both markets.
United States
Gulf of Mexico ultra-deepwater discoveries and Appalachian shale export requirements drive steel pipe procurement. The American Petroleum Institute's updated offshore construction standards tighten material certification protocols for high-pressure applications. Houston-Galveston fabrication yards expand welded pipe output to meet pre-salt project timelines.
Brazil
Pre-salt development mandates from Petrobras anchor flexible pipe and rigid steel demand for depths exceeding 2,500 meters. ANVISA certification requirements and national petroleum regulator local content thresholds redirect procurement toward domestic pipe mills. Rio de Janeiro state hosts specialized installation fleets serving Santos Basin trunkline deployments.
Norway
North Sea electrification tiebacks and brownfield integrity retrofits sustain maintenance service contracts. EU methane emissions regulation creates retrofit demand for leak detection systems across aging infrastructure. Stavanger-Bergen corridor operators bundle pipeline engineering into decade-long performance agreements.
United Kingdom
Decommissioning obligations and offshore wind export cable convergence reshape North Sea procurement patterns. The International Maritime Organization's subsea infrastructure guidelines extend environmental assessment timelines for new routing. Aberdeen clusters pivot toward integrated engineering contracts combining pipeline and power distribution.
Qatar
North Field expansion and LNG export capacity growth require subsea gathering systems at scale. QatarEnergy's integrated project authority consolidates procurement decisions for complex deepwater developments. Ras Laffan Industrial City fabrication facilities serve Gulf-wide trunkline installation schedules.
Offshore Pipeline Market Vendor Landscape
US Gulf Coast producers anchor one tier; Korean and European specialists hold integrated engineering capabilities that command premium contract structures. The vendor base concentrates around three strategic archetypes: state-affiliated energy companies with captive demand, integrated engineering-procurement-installation contractors, and pure-play installation specialists with vessel assets. Consolidation pressures favor M&A among fabrication yards and strategic partnerships between pipe mills and installation fleets.
Within the integrated engineering tier, TechnipFMC plc and Samsung Engineering exemplify divergent geographic positioning—one leveraging North Atlantic project experience, the other deploying Korean yard capacity for modular construction discipline. Shell occupies a position as operator-specifier, anchoring demand through proprietary high-pressure designs rather than external procurement. These three represent the competitive spectrum: engineering-led integration, fabrication-scale execution, and operator-captive specification authority.
| Leading Market Players |
|---|
| Primoris |
| QatarEnergy |
| TechnipFMC plc |
| YPF SA |
| Shell |
| Bechtel Corporation |
| Woodside Energy Group |
| Samsung Engineering |
| Bonatti |
| Others |
Supply Flow & Price Mechanics
CRA-clad versus solid alloy specifications create a bifurcated procurement ladder where hybrid metallurgy commands 40-60% cost savings over full corrosion-resistant alloy construction, reshaping both mill capacity allocation and installation contractor bidding strategies across Brazil's pre-salt campaigns and Gulf of Mexico ultra-deepwater schedules.
Pricing Analysis
Project-based lump-sum contracting dominates ultra-deepwater developments, with price differentiation driven by pressure rating certification tiers and vessel day-rate availability. Cost compression in standard carbon steel trunklines intensifies as Korean and Chinese mills expand welded pipe output. National oil companies exhibit lowest price sensitivity due to local content mandates, while independent operators in West African frontier basins face capital constraints.
Supply Chain Analysis
Nickel alloy feedstock rests on Indonesian and Philippine laterite mining operations, with semifinished slab concentration in Japan and Finland. Corrosion-resistant alloy cladding, automated welding consumables, and J-lay vessel capacity represent critical input dependencies. Single-source vulnerability concentrates in specialized reel-lay vessel availability. Distribution runs through engineering-procurement-installation contractors who bundle procurement authority under decade-long performance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's local content thresholds impose 25-40% cost premiums versus Gulf of Mexico equivalents, creating arbitrage opportunities for operators with flexible procurement geography and contractors with dual-hemisphere installation capacity.
For Market Incumbents: Acquire stranded J-lay and reel-lay vessel capacity before peak demand windows in Brazil's pre-salt campaign. Backward integration into corrosion-resistant alloy cladding technology defends margin position against Korean mill competition. Invest in API 1104 welding inspector certification pipelines to preempt fabrication timeline extensions at US Gulf Coast yards. For New Entrants and Emerging Players: Launch via integrated integrity management service contracts targeting North Sea brownfield electrification tiebacks. West African frontier basins off Senegal and Mauritania offer lowest competitive density for first-mover pipeline infrastructure. Bundle real-time monitoring commitments with installation bids to differentiate from pure-play vessel operators. For Investors and Strategic Acquirers: Consolidation pressure builds where fabrication yard capacity utilization crosses 85% during simultaneous Brazil and Gulf of Mexico project ramps. Target mid-tier engineering firms with proprietary high-pressure, high-temperature design libraries and established regulator relationships. Watch ANVISA certification backlog duration as inflection indicator for Brazilian procurement timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Capacity Acquisition | Locking J-lay and reel-lay assets before Brazil's pre-salt peak demand secures execution slots. |
| CRA Cladding Technology Licensing | Hybrid metallurgy adoption by Petrobras and Shell creates captive demand for automated welding protocols. |
| Integrated EPIC Contracting | Bundling engineering, procurement, and installation displaces discrete equipment purchasing in Norway's continental shelf. |
| North Sea Electrification Tiebacks | EU methane emissions regulation drives retrofit demand for leak detection across aging infrastructure. |
| West African Frontier Basin Entry | First-mover pipeline requirements off Senegal and Mauritania lack established contractor relationships. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged subsea project managers at national oil companies, fabrication yard procurement directors, installation vessel fleet operators, and regulatory affairs leads at classification societies. Secondary validation drew from American Petroleum Institute specification filings, ANVISA certification databases, International Maritime Organization subsea infrastructure guidelines, and customs records for corrosion-resistant alloy imports. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the forecast window to documented project sanctioning cycles and vessel day-rate movements across the analysis window. Segmentation dimensions modeled include product type, installation method, water depth threshold, and field architecture complexity. CAGRs derived from regression against capital expenditure deployment patterns and rig count trajectories in named deepwater basins. Specific forecast inputs incorporated Petrobras pre-salt development timelines and Gulf of Mexico lease sale schedules.
Several conditions sit outside the modeled scope, including force majeure disruptions to specialized mill capacity, abrupt shifts in Brazilian local content percentage requirements, and technological breakthroughs in thermoplastic composite pressure ratings. Forecasts reflect documented assumptions about vessel availability and alloy supply continuity. Material deviation in regulator enforcement intensity or J-lay fleet mobilization rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Underwater Concrete Market