
 Hoist Chains Market | 2026-2036
Hoist Chains Market Size, Share, and Industry Trends Forecast 2026-2036
Hoist Chains Market Intelligence
The capability gap between integrated forge operators and outsourced assemblers is collapsing as automated heat-treatment investments reset minimum viable scale. Gunnebo leverages captive steel sourcing and in-house induction hardening to sustain margin on Grade 100 and 120 offerings. RUD competes through proprietary chain coupling systems that anchor its position in offshore rigging and subsea installations. FEW Ketten Walder differentiates via precision calibration for overhead crane OEMs, occupying a narrow but defensible niche in German-speaking industrial markets.
Hoist chains are engineered load-bearing assemblies manufactured from alloy, carbon, or stainless steel grades, typically heat-treated to achieve tensile strengths exceeding 800 MPa and calibrated to specific pitch dimensions for sprocket engagement and uniform load distribution. These components serve as the primary lifting medium in overhead cranes, mine hoists, and marine winch systems where mechanical failure carries catastrophic safety and operational consequences. Alloy steel chains dominate value capture due to their strength-to-weight optimization in mining and heavy construction, while stainless steel variants command premium positioning in chemical processing and coastal marine environments where corrosion resistance governs replacement cycles. The construction vertical leads volume absorption across developing industrial corridors, though warehousing and automated material handling represent the fastest-growing demand pool as e-commerce fulfillment centers spec high-cycle hoist systems.
ISO 1834 and ISO 3077 govern dimensional tolerances and mechanical testing protocols, while OSHA and EU Machinery Directive 2006/42/EC mandate traceable certification and periodic inspection regimes that shape replacement demand and vendor qualification. China's GB/T 20947 and Japan's JIS B 8818 impose additional metallurgical and marking requirements that fragment supplier compliance portfolios across export markets. Buyers must monitor evolving alloy surcharge volatility and regulatory convergence between ASME B30.9 and EN 818 standards to avoid stranded inventory or certificate gaps in multi-jurisdiction project supply.
Market Dynamics
Automated heat-treatment investments are collapsing the capability gap between integrated forge operators and outsourced assemblers, resetting minimum viable scale across the supplier base and compressing margins for mid-tier heat-treatment-only facilities.
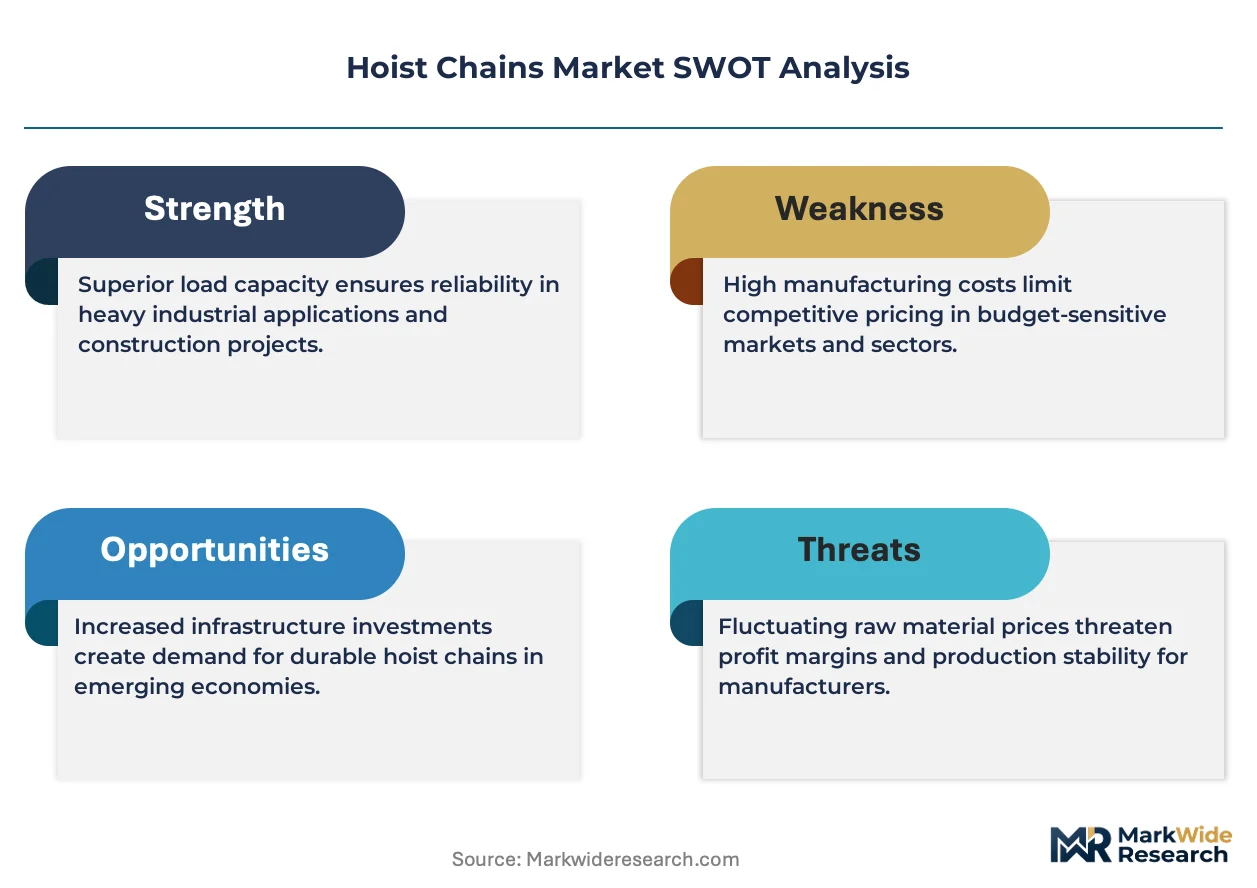
Growth Catalysts
- ISO 1834 and ISO 3077 harmonization:Dimensional tolerance and mechanical testing standardization is streamlining vendor qualification for multi-jurisdiction mining projects in Chile and Canada.
- Deepened open-pit extraction:Australian mining operations are generating sustained demand for high-capacity Grade 100 and 120 lifting assemblies as extraction depths increase.
- Port modernization clusters:Shanghai and Tianjin industrial corridors are absorbing bulk orders for heavy-capacity hoist systems tied to steel production expansion.
Market Restraints
- Alloy surcharge volatility:Nickel and chromium input cost swings are compressing margin predictability for heat-treated alloy chain producers.
- Supply concentration in German-speaking industrial markets:Precision calibration specialists for overhead crane OEMs face limited alternative sourcing.
- Stainless steel substitution ceiling:Premium pricing for corrosion-resistant variants limits penetration in cost-sensitive construction verticals.
Strategic Opportunities
- Subsea installation expansion:Proprietary chain coupling systems are opening offshore rigging applications in North Sea and Gulf of Mexico developments.
- E-commerce fulfillment center automation:High-cycle hoist system specifications are creating new demand pools in warehousing and automated material handling.
- EU Machinery Directive 2006/42/EC traceability mandates:Periodic inspection regime requirements are accelerating replacement cycle monetization for certified vendors.
Industry Challenges
- Metallurgical certification timeline compression:China's GB/T 20947 and Japan's JIS B 8818 marking requirements are fragmenting supplier compliance portfolios.
- Induction hardening capex intensity:In-house heat-treatment capacity requires substantial furnace and quench system investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoist Chains Market |
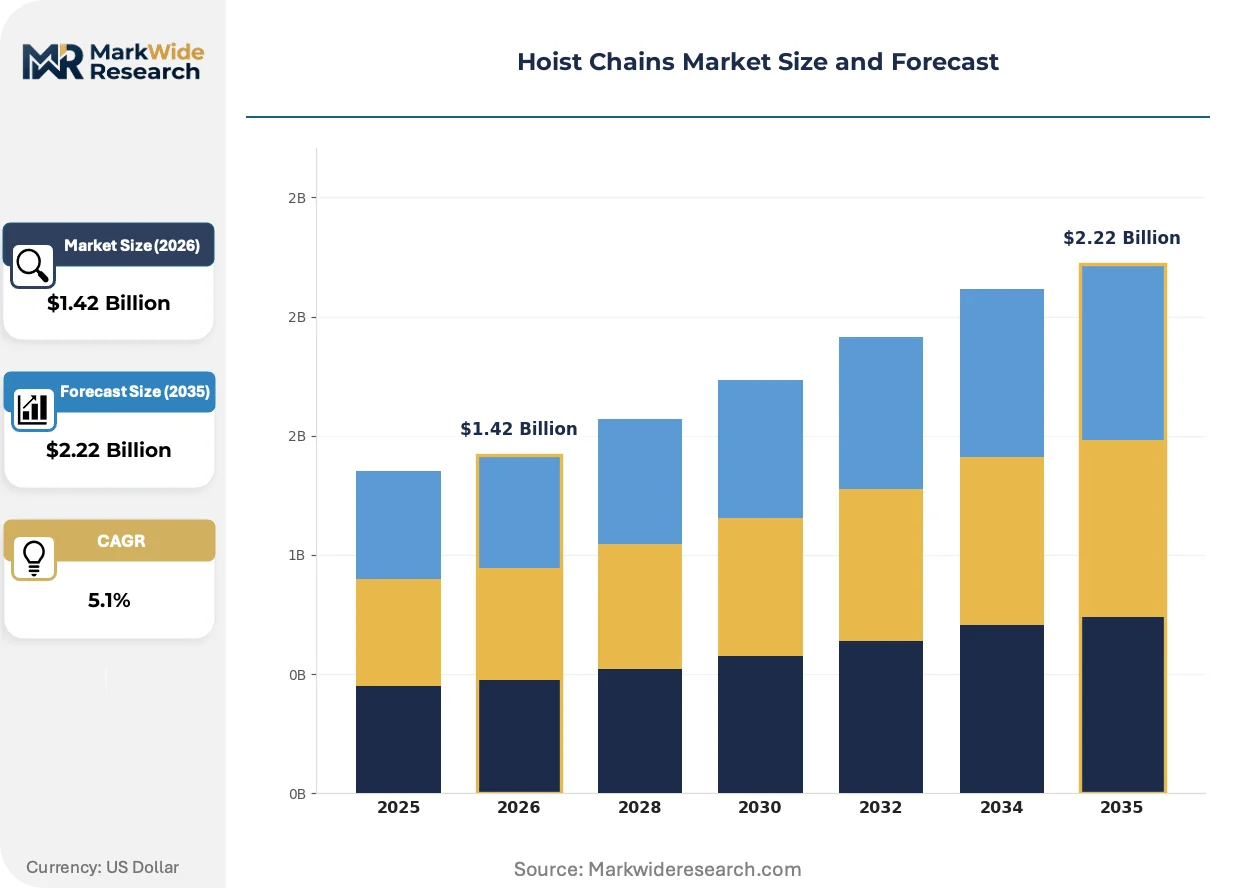
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 5.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Steel Chains, Carbon Steel Chains, Stainless Steel Chains, Heat Treated Chains Industry Vertical: Construction, Shipbuilding, Mining, Warehousing, Material Handling Application: Load Lifting, Rigging, Towing, Securing Cargo, Hoisting Equipment End User: Manufacturing Facilities, Logistics Providers, Engineering Firms, Metal Fabricators |
| Companies Covered | Gunnebo, FEC Corporation, J.D. Theile, RUD, Pewag, Weissenfels, Parsons Chain, FEW Ketten Walder, Chaineries Limoujines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoist Chains Market Strategic Shifts & Innovations
Digital traceability and predictive maintenance integration are reshaping how hoist chain specifications are written into long-term service contracts. Buyers now embed sensor-readiness and fatigue-monitoring compatibility as baseline procurement criteria.
Embedded fiber-optic strain sensing is miniaturizing load-monitoring hardware directly into chain link geometries. Mining operators in Western Australia are specifying these smart-chain assemblies for real-time tension telemetry in autonomous haulage systems. The technology is miniaturizing what previously required external load cells and wired instrumentation into passive, maintenance-free link structures.
REACH substance restrictions and RoHS compliance deadlines are forcing reformulation of surface coating chemistries for corrosion protection. European port equipment OEMs are accelerating qualification of hexavalent-chromium-free alternatives ahead of 2026 sunset dates. Stainless steel variants with enhanced pitting resistance are capturing specification share in North Sea offshore contracts.
Buyer consolidation among integrated mining houses is compressing supplier negotiation cycles and unbundling after-sales inspection services from original equipment supply. Tier-one extractive operators in Chile and Canada are mandating third-party certification continuity as a condition of framework agreements. Procurement teams are penalizing vendors who cannot demonstrate seamless ASME B30.9 and EN 818 standard convergence across certificate portfolios.
Hoist Chains Market Segmentation
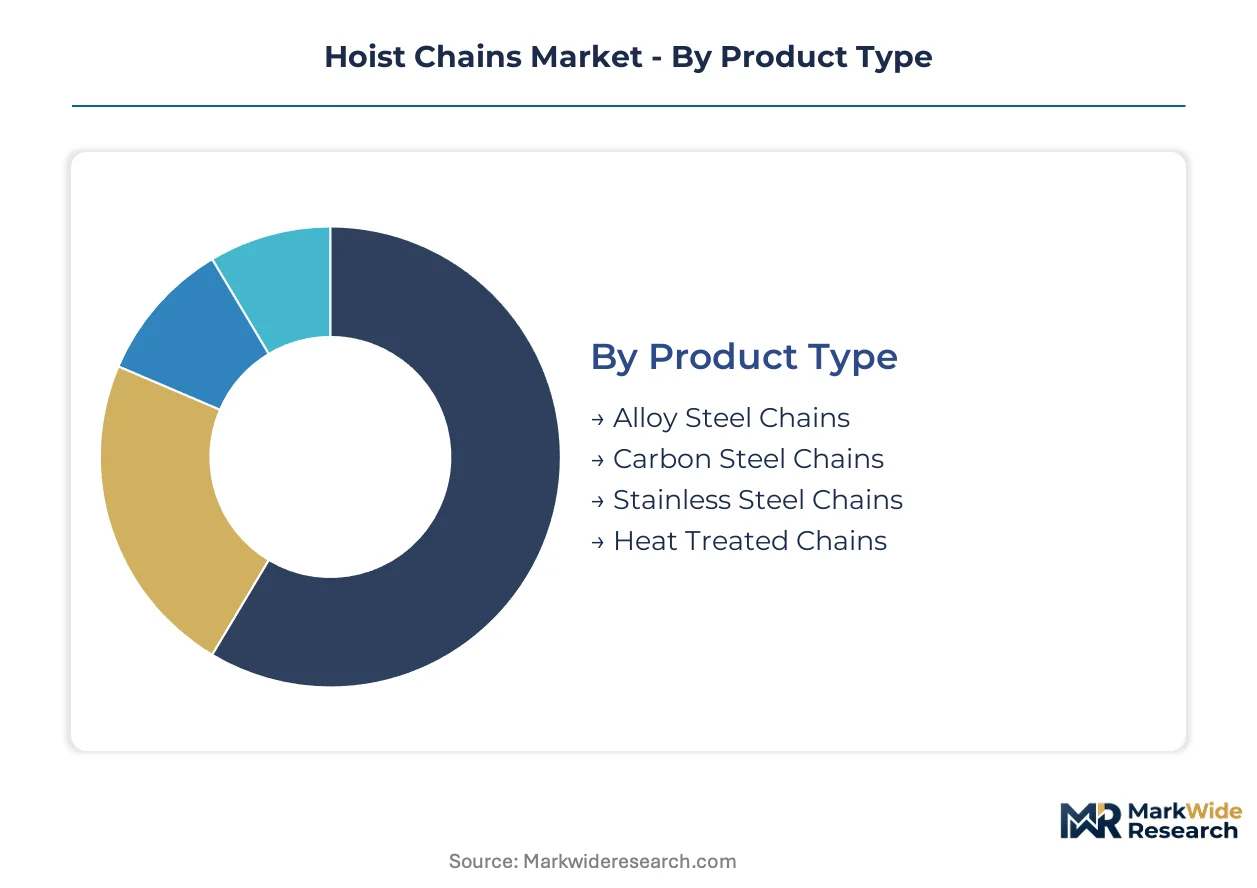
Hoist chain procurement specifications diverge sharply across metallurgical grades and operational environments. Buyers align material selection with load-cycle intensity, corrosion exposure, and regulatory inspection regimes rather than upfront unit cost.
Product Type:
Margin pools concentrate in heat-treated alloy grades where certification continuity commands pricing power over commodity carbon alternatives.
- Alloy Steel Chains:Manufactured from chromium-nickel-molybdenum grades and induction-hardened to tensile strengths exceeding 800 MPa. Australian open-pit mining operators specify Grade 100 and 120 variants for deep extraction haulage systems where mechanical failure carries catastrophic safety consequences.
- Stainless Steel Chains:Austenitic and duplex grades deliver pitting resistance in chloride-rich coastal marine and chemical processing environments. North Sea offshore contractors absorb premium pricing for these variants where replacement access is logistically constrained and corrosion governs service intervals.
- Carbon Steel Chains:Baseline construction and general rigging applications in cost-sensitive developing markets.
- Heat Treated Chains:Value-add processing segment where automated furnace investments reset supplier viability thresholds.
Alloy steel holds installed capacity. Stainless steel is rotating up the share rankings.
Industry Vertical:
Volume absorption patterns track capital expenditure cycles in extractive industries and port infrastructure modernization.
- Construction:Volume leader across developing industrial corridors where overhead crane deployment scales with vertical build-out. China's steel production expansion around Shanghai and Tianjin sustains bulk orders for high-capacity lifting assemblies in structural erection and precast handling.
- Mining:Grade-intensive vertical where ISO 3077 mechanical testing and traceable certification are non-negotiable. Chilean and Canadian safety codes tighten procurement standards as extraction depths increase replacement frequency for fatigue-critical components.
- Shipbuilding:Marine classification society rules govern alloy selection and proof-load documentation.
- Warehousing:E-commerce fulfillment center automation is expanding most quickly as high-cycle hoist system specifications proliferate.
- Material Handling:Port modernization and logistics hub upgrades drive standardized fleet replacement.
Construction anchors volume absorption. Warehousing is climbing the fastest.
Application:
Functional differentiation separates safety-critical lifting from utility rigging where failure modes carry divergent liability profiles.
- Load Lifting:Primary revenue pool encompassing overhead crane operations, mine hoists, and marine winch systems. OSHA and EU Machinery Directive 2006/42/EC mandate traceable certification and periodic inspection regimes that accelerate replacement monetization.
- Rigging:Offshore and subsea installations where proprietary chain coupling systems anchor vendor positioning. Gulf of Mexico developments specify these assemblies for platform mooring and subsea equipment deployment.
- Towing:Marine salvage and vessel assistance operations with dynamic load variability.
- Securing Cargo:Container lashing and deck stowage in international shipping.
- Hoisting Equipment:Integrated OEM supply for crane manufacturers and winch builders.
Load lifting dominates value capture. Rigging is gaining share fastest.
End User:
Procurement sophistication varies across integrated operators and fragmented maintenance-repair-oreplace channels.
- Manufacturing Facilities:Integrated steel, automotive, and heavy equipment producers with in-house maintenance divisions. These buyers negotiate framework agreements penalizing vendors who cannot demonstrate seamless ASME B30.9 and EN 818 standard convergence.
- Logistics Providers:Third-party warehouse operators and port terminal managers specifying high-cycle systems for automated material handling. Fulfillment center build-outs in industrial corridors absorb sensor-ready chain assemblies for predictive maintenance integration.
- Engineering Firms:Project-based procurement for infrastructure and energy construction.
- Metal Fabricators:Job shop and specialty contractor segments with spot-buy patterns.
Manufacturing facilities hold procurement leverage. Logistics providers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Australian mining corridors absorb Grade 100 and 120 assemblies for deep-haulage systems, while German-speaking industrial markets concentrate precision-calibration demand for overhead crane OEMs. Chinese port clusters drive bulk orders tied to steel production expansion.
Australia
Western Australian open-pit operations generate sustained demand for high-capacity lifting assemblies as extraction depths increase. The country's national mining safety regulator mandates traceable fatigue certification for hoist components under state-level occupational health frameworks. Perth-based procurement offices coordinate fleet replacement cycles for autonomous haulage systems across the Pilbara iron ore belt.
China
GB/T 20947 metallurgical marking requirements impose additional compliance burdens on suppliers targeting domestic infrastructure projects. MIIT oversees industrial standard convergence with ISO 3077 mechanical testing protocols. Shanghai and Tianjin industrial corridors absorb bulk orders for heavy-capacity hoist systems tied to port modernization and steel production expansion.
Germany
Precision calibration specialists serve overhead crane OEMs in a narrow but defensible niche segment. KBA-aligned machinery safety frameworks enforce EU Machinery Directive 2006/42/EC traceability mandates. The Ruhr industrial region and Bavarian manufacturing clusters sustain demand for sensor-ready chain assemblies in automated material handling installations.
Chile
Copper extraction depth increases drive replacement frequency for fatigue-critical lifting components in Andean mining operations. The national mining regulator tightens alloy grade certification requirements under ISO 1834 dimensional tolerance standards. Antofagasta and Santiago procurement offices penalize vendors lacking seamless ASME B30.9 and EN 818 certificate convergence.
Canada
Oil sands and hard-rock mining operations specify Grade 100 variants for extreme load-cycle environments. Health Canada and provincial occupational safety bodies enforce periodic inspection regimes that accelerate replacement monetization. Alberta and Ontario industrial corridors concentrate demand from integrated mining houses with framework agreement negotiation leverage.
Hoist Chains Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with automated heat-treatment investments resetting minimum viable scale across the supplier base. Mid-tier heat-treatment-only facilities face margin compression as capability gaps collapse between forge operators and outsourced assemblers. Strategic archetypes include captive steel sourcers with in-house induction hardening, proprietary chain coupling system developers, and precision calibration specialists for OEM channels. Dominant competitive moves encompass backward integration into steel supply and technology licensing for sensor-ready chain geometries.
Among European fabricators, Gunnebo GmbH and RUD occupy positions exemplifying divergent strategic archetypes—one anchored in captive material control, the other in proprietary connection systems. FEW Ketten Walder represents the precision-calibration specialist tier serving German-speaking industrial markets. These three entities illustrate how supplier positioning fragments across metallurgical control, coupling technology, and dimensional calibration vectors.
| Leading Market Players |
|---|
| Gunnebo |
| FEC Corporation |
| J.D. Theile |
| RUD |
| Pewag |
| Weissenfels |
| Parsons Chain |
| FEW Ketten Walder |
| Chaineries Limoujines |
| Others |
Cost & Logistics Intelligence
ISO 3077 mechanical testing and traceable certification regimes simultaneously gate supplier qualification and stratify price tiers, forcing buyers to absorb premium positioning for Grade 100 and 120 assemblies or accept higher failure-risk exposure in uncertified alternatives. Alloy surcharge volatility in nickel and chromium inputs compresses margin predictability, while automated heat-treatment investments reset minimum viable scale and collapse the pricing power of mid-tier heat-treatment-only facilities.
Pricing Analysis
Long-term offtake contracts dominate procurement for integrated mining houses in Australia and Chile, locking in volume commitments against alloy price hedges, while spot-market transactions serve fragmented maintenance-repair-replace channels with volatile exposure to nickel and chromium swings. Price differentiation rests on certification grade continuity and in-house induction hardening capability, with Gunnebo and RUD commanding premiums through captive steel sourcing and proprietary coupling systems respectively. Cost compression in carbon steel tiers intensifies as outsourced assemblers match integrated forge quality through automated furnace investments. Construction vertical buyers exhibit highest price sensitivity, while North Sea offshore contractors absorb stainless steel premiums where replacement access constraints govern total cost of ownership.
Supply Chain Analysis
Strategic stockpiling of certified alloy billets characterizes procurement for Australian and Canadian mining safety codes, whereas just-in-time inventory governs German overhead crane OEM channels where precision calibration demands rapid specification turnaround. Supply concentrates in China for GB/T 20947-compliant domestic infrastructure, Germany for precision-calibration specialist output, and Sweden for captive steel sourcing integrated with induction hardening. Raw material dependencies center on chromium-nickel-molybdenum alloy grades, high-purity carbon steel billets, and hexavalent-chromium-free coating chemistries facing REACH sunset deadlines. Single-source vulnerability in precision calibration specialists for German-speaking industrial markets elevates supply risk. Distribution runs through direct OEM supply agreements for integrated mining houses and authorized distributor networks for fragmented construction and warehousing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded fiber-optic strain sensing and predictive maintenance integration are reshaping procurement specifications, creating first-mover advantage for suppliers capable of sensor-ready chain geometries and digital traceability compliance under tightening EU Machinery Directive mandates.
For Market Incumbents: Compound certification continuity investments to defend pricing power against automated heat-treatment entrants collapsing capability gaps, while deepening backward integration into alloy billet supply to offset nickel and chromium volatility. Priority capacity addition targets Australian Pilbara and Chilean Antofagasta mining corridors where extraction depth increases replacement frequency. Threat: Mid-tier outsourced assemblers achieving Grade 100 parity through furnace automation. For New Entrants and Emerging Players: Differentiate on sensor-ready chain geometries for e-commerce fulfillment center automation, the most penetrable demand pool with nascent specification standards and limited incumbent lock-in. White-space targets include warehousing high-cycle hoist systems and subsea installation chain coupling for Gulf of Mexico developments. Go-to-market angle: Predictive maintenance integration partnerships with port terminal operators and logistics providers. For Investors and Strategic Acquirers: EU Machinery Directive 2006/42/EC traceability mandates and REACH coating chemistry deadlines reshape the acquisition landscape toward targets with pre-qualified hexavalent-chromium-free surface treatments and seamless ASME B30.9 and EN 818 certificate convergence. Long-term viability favors vertically integrated forge operators with captive steel sourcing over heat-treatment-only facilities facing margin compression. Signal to watch: Acceleration of third-party certification continuity requirements in Chilean and Canadian framework agreement negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Billet Supply | Gunnebo's captive steel sourcing insulates margins against nickel and chromium volatility in Grade 100 production. |
| Sensor-Ready Chain Geometry Development | Embedded fiber-optic strain sensing captures Western Australian autonomous haulage specification shifts. |
| Hexavalent-Chromium-Free Coating Qualification | REACH compliance deadlines ahead of 2026 sunset dates open replacement demand in European port equipment. |
| Precision Calibration Capacity Expansion | FEW Ketten Walder's dimensional accuracy defends narrow but defensible German-speaking OEM niche. |
| Subsea Chain Coupling System Licensing | RUD's proprietary connection technology anchors positioning in North Sea and Gulf of Mexico offshore rigging. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at Australian and Chilean mining operations, overhead crane OEM procurement teams in Germany, port terminal engineering managers in Shanghai and Tianjin, and aftermarket service heads at integrated steel producers. Secondary validation drew from ISO 1834 and ISO 3077 certification databases, GB/T 20947 and JIS B 8818 marking registries, customs trade data for alloy steel chain shipments, and SEC filings of listed industrial component manufacturers. Bottom-up demand modeling across end-use verticals was triangulated against top-down macroeconomic indicators for mining capital expenditure and port infrastructure investment.
Across the analysis window, the forecasting framework segmented volume and value outputs by metallurgical grade, industry vertical, functional application, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical replacement cycle data, alloy price elasticity coefficients, and regulatory compliance cost pass-through assumptions. Industry-specific inputs included autonomous haulage system deployment timelines in Western Australia, e-commerce fulfillment center build-out pipelines in Chinese industrial corridors, and offshore rigging project sanctioning activity in the North Sea.
Decision-makers should treat outputs as directional under base assumptions of sustained mining extraction depth increases and REACH coating chemistry deadline adherence; material deviation in nickel and chromium price volatility or regulatory timeline acceleration would warrant model refresh. Revision becomes warranted when alloy surcharge volatility crosses thresholds that trigger procurement contract renegotiation or when GB/T 20947 and ISO 3077 harmonization timelines shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
North America Conveyor Belt Market