
 US Aerial Work Platform Market | 2026-2036
US Aerial Work Platform Market Size, Share, and Industry Trends Forecast 2026-2036
US Aerial Work Platform Market Insights
Domestic boom lift manufacturing capacity in the Midwest is pivoting toward electrified platforms and higher-reach models. JLG Industries leverages its integrated supply chain in Pennsylvania and Iowa to sustain rapid fulfillment timelines for rental channel partners. Terex Corporation anchors its Genie brand through vertical integration into mast fabrication and control systems engineering. Haulotte Group competes on compact electric scissor lifts designed for indoor manufacturing environments where emissions compliance has tightened.
An aerial work platform is a mobile elevating device with a work platform and controls at the platform level, typically extending from twenty to one hundred eighty feet vertically, used to position personnel and tools at elevated work sites across construction, industrial, and utility applications. Boom lifts articulate or telescope to reach over obstacles, while scissor lifts provide strictly vertical elevation on crossed folding supports for slab work and facility maintenance. Electric and hybrid technology segments are gaining structural momentum as rental fleets face decarbonization mandates and indoor job sites restrict combustion engines. Hydraulic systems still occupy the majority of installed base but carry higher maintenance cost structures that erode total cost of ownership advantages over multi-year rental cycles.
OSHA enforces fall protection and operator training standards under 29 CFR 1926, while ANSI A92 standards govern machine design, safe use, and training requirements that manufacturers must certify before market entry. The EPA regulates off-road diesel emissions under Tier 4 Final standards, pushing OEMs toward battery-electric and hybrid powertrain architectures that alter fleet procurement economics. Stakeholders must monitor how state-level clean fleet mandates in California and New York propagate into rental fleet specification decisions and residual value calculations.
Market Dynamics
Fleet decarbonization mandates from California and New York are forcing rental operators to accelerate electric platform procurement ahead of residual value depreciation curves for diesel units.
Growth Catalysts
- ANSI A92 Training Mandates:Updated standards require recertification every three years, creating recurring revenue streams for training providers and equipment lessors bundling education with rentals.
- Data Center Construction:Hyperscale facility builds across Northern Virginia and Phoenix demand compact electric scissor lifts for interior mechanical installation where emissions restrictions apply.
- Utility Grid Hardening:Investor-owned utilities in Texas and Florida are expanding bucket truck and insulated boom lift fleets to accelerate storm recovery and vegetation management programs.
Market Restraints
- Steel Input Volatility:Boom fabrication relies on high-strength alloy plate subject to tariff-adjusted pricing swings that compress OEM margin visibility on multi-quarter rental fleet orders.
- Battery Supply Concentration:Lithium-ion cell production for electric platforms concentrates in Asian manufacturing bases, exposing fleet buyers to logistics bottlenecks and duty exposure.
- Reach Limitations:Electric drivetrains currently cap platform payload and boom extension torque compared to hydraulic diesel equivalents, restricting substitution in heavy-lift construction segments.
Strategic Opportunities
- Telematics-Enabled Fleet Optimization:Integration of utilization tracking with predictive maintenance algorithms allows rental houses to price by actual hours versus calendar periods.
- Indoor Manufacturing Retrofits:Automotive battery plants in Michigan and Tennessee require zero-emission elevated access for assembly line reconfiguration on compressed timelines.
- Inflation Reduction Act Credits:Clean commercial vehicle tax incentives reduce effective acquisition cost for electric AWPs below diesel parity in qualifying fleet deployments.
Industry Challenges
- Certified Operator Scarcity:OSHA 29 CFR 1926 compliance requires documented practical evaluation that rental coordinators struggle to schedule during peak construction seasons.
- Legacy Fleet Stranding Risk:Rental operators holding Tier 3 diesel units face accelerated obsolescence as municipal job sites adopt engine-ban clauses in contract specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Aerial Work Platform Market |
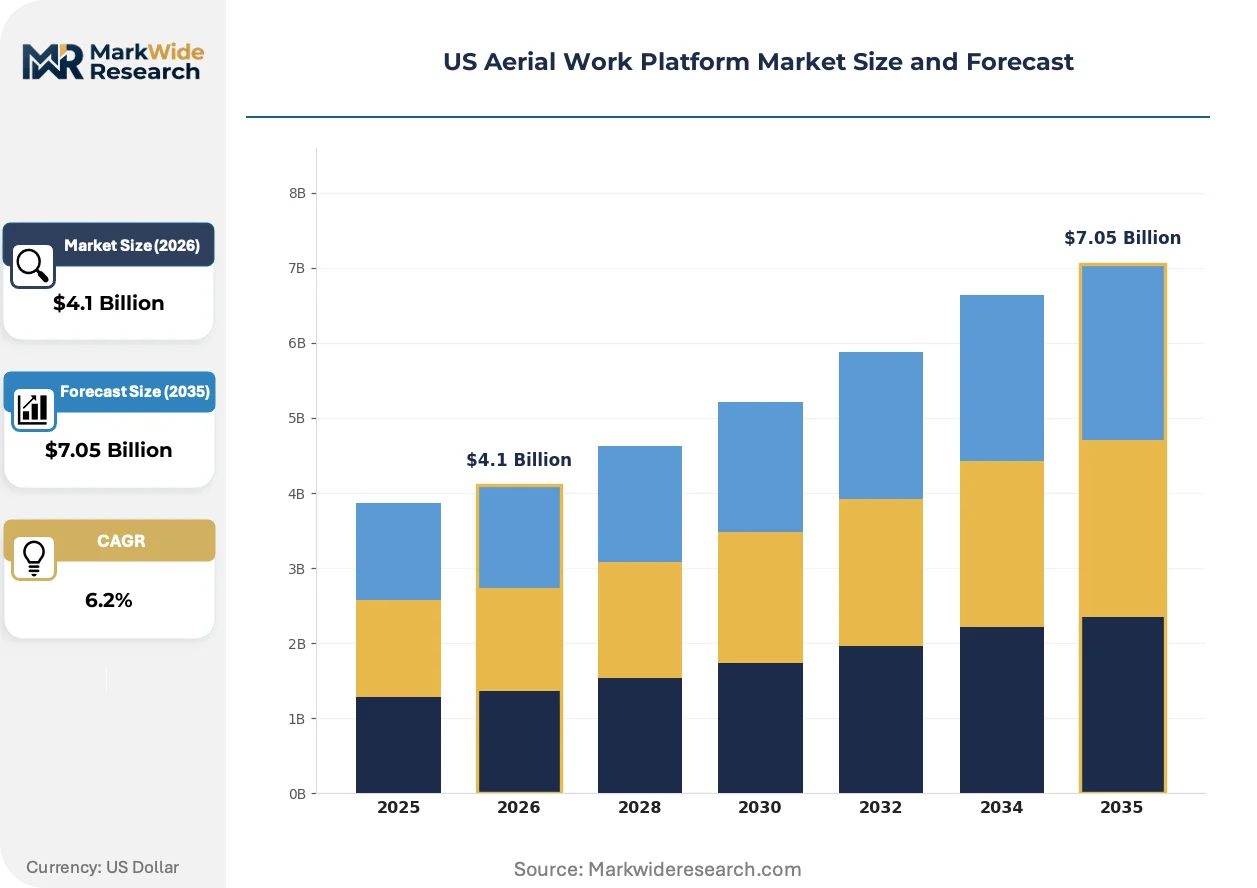
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.05 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lifts, Boom Lifts, Telehandlers, Vertical Masts End User: Construction, Manufacturing, Utilities, Maintenance Deployment: On-Site, Rental, Off-Site, Permanent Technology: Hydraulic, Electric, Gas, Hybrid |
| Companies Covered | JLG Industries, Terex Corporation, Haulotte Group, Skyjack, Snorkel Lifts, Manitou Group, LGMG North America, Palfinger AG, Niftylift, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Aerial Work Platform Market Trends and Innovations
Electrification architectures and connected fleet management systems are compressing the traditional seven-year rental equipment replacement cycle and redefining residual value calculations.
Lithium iron phosphate battery packs with integrated thermal management are rewriting platform duty-cycle economics. Large rental houses in Texas and Florida are specifying these systems for solar farm construction where daily runtime demands exceed lead-acid limitations. The technology is compressing total cost of ownership advantages previously held by diesel hydraulics in outdoor applications.
OSHA's emphasis on documented operator evaluation under updated ANSI A92.24 standards is tightening training provider accreditation. Rental fleet managers now bundle certification with equipment delivery to reduce jobsite startup friction. The policy shift most affects multi-state contractors operating across jurisdictions with inconsistent reciprocity recognition.
Telematics penetration among mid-sized rental operators has crossed a threshold where utilization data now drives procurement timing. Equipment lessors in California and Arizona are selling aggregated fleet performance analytics to general contractors bidding fixed-price work. The behavioral shift is most visible in commercial construction verticals where labor productivity guarantees dominate contract structures.
US Aerial Work Platform Market Segmentation
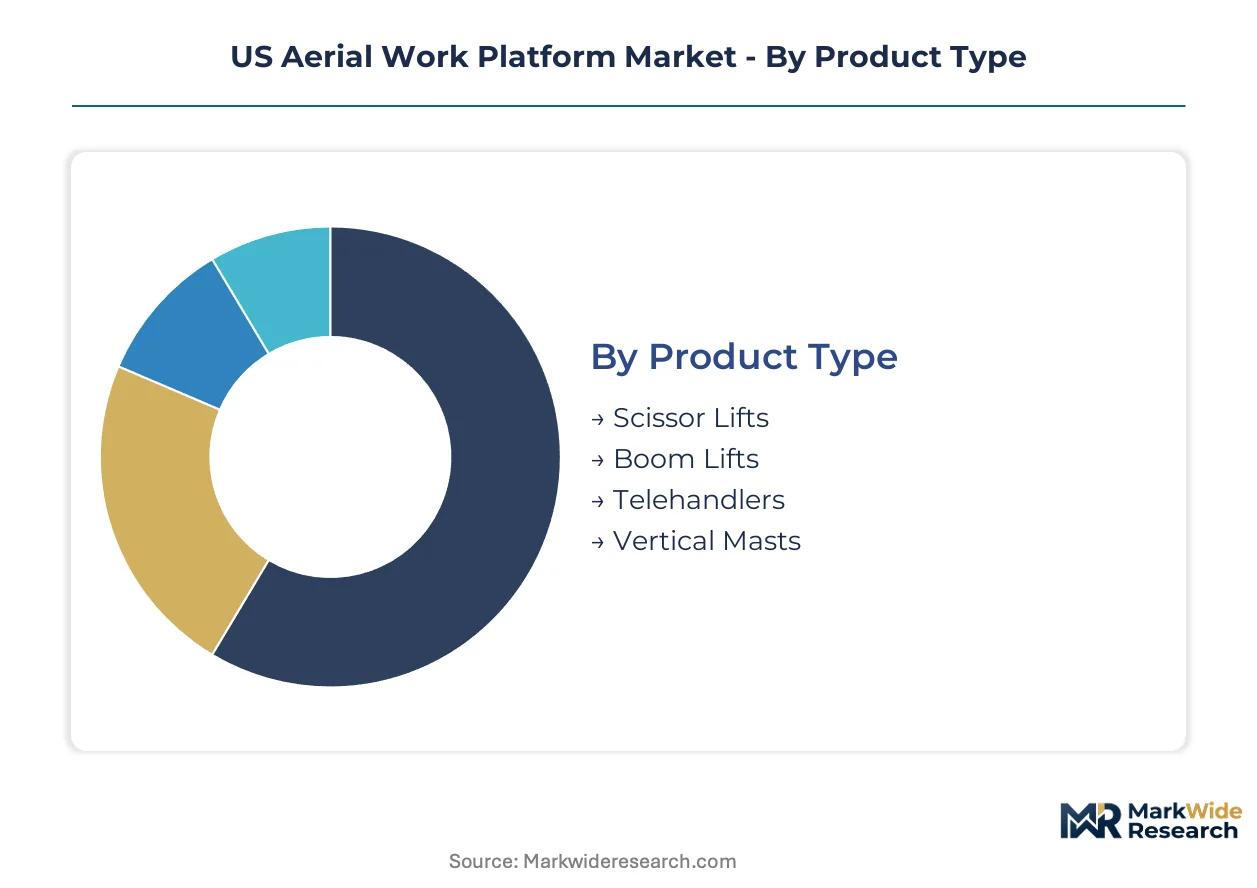
Segmentation clarity determines procurement strategy for rental fleet managers balancing utilization rates against residual value risk. Equipment specification varies sharply across powertrain technology and deployment model, with electrification mandates compressing traditional replacement timelines in coastal states.
Product Type:
Fleet refresh programs are accelerating platform turnover as Tier 4 Final diesel units face obsolescence pressure and electric alternatives achieve runtime parity.
- Scissor Lifts:Crossed folding support structures deliver strictly vertical elevation from twenty to fifty feet, optimized for slab work and facility maintenance. Demand clusters in Texas and Florida warehouse construction where slab pours require dense equipment staging. OSHA 29 CFR 1926 fall protection mandates drive specification toward units with integrated guardrail systems.
- Boom Lifts:Articulating and telescoping booms extend sixty to one hundred eighty feet with horizontal outreach capability for obstacle navigation. Utility grid hardening programs in storm-prone states are expanding insulated bucket truck procurement. ANSI A92 design standards require continuous stability monitoring systems that add cost but reduce insurance premiums.
- Telehandlers:Telescopic material handlers with rough-terrain chassis and fork attachments serve multi-story framing operations. Residential construction in Sun Belt metros specifies these for truss placement efficiency.
- Vertical Masts:Compact single-mast platforms with zero-turn radius occupy narrow aisle manufacturing environments. Automotive battery plant retrofits in Michigan and Tennessee require these for assembly line reconfiguration.
Volume placements concentrate in Scissor Lifts; the faster expansion belongs to Boom Lifts.
End User:
Application-specific duty cycles dictate powertrain selection and maintenance cost structures across customer verticals.
- Construction:General contractors and specialty trades account for the dominant equipment placement volume. Non-residential building permits in California and Texas drive rental demand for hybrid units capable of indoor-outdoor transition.
- Manufacturing:Zero-emission mandates at indoor facilities are displacing propane-fueled legacy fleets. Food processing plants in the Midwest specify stainless steel platforms for washdown compliance.
- Utilities:Investor-owned electric utilities in Florida and Texas are hardening distribution infrastructure against storm damage. Insulated boom specifications require dielectric testing certification that extends procurement lead times.
- Maintenance:Facility management contractors bundle aerial access with HVAC and lighting services. Commercial property portfolios in Arizona specify telematics-enabled units for utilization tracking.
Construction dominates current fleet placements; manufacturing is climbing the fastest as electrification mandates tighten.
Deployment:
Ownership economics shift as rental penetration deepens and residual value uncertainty around electric platforms favors operational flexibility.
- Rental:Equipment lessors capture over seventy percent of new unit placements through fleet refresh programs. United Rentals and Sunbelt Rentals are specifying lithium iron phosphate battery systems for solar farm construction.
- On-Site:Large general contractors with multi-year project backlogs maintain captive fleets. Data center builders in Northern Virginia prefer owned equipment for schedule certainty.
- Off-Site:Prefabrication yards and modular construction facilities deploy permanent-mounted platforms. Steel fabrication shops in the Midwest use fixed gantries for repetitive welding operations.
- Permanent:Industrial facilities install dedicated elevated access for production line maintenance. Automotive assembly plants specify integrated platforms with conveyor synchronization.
Rental channels absorb the highest placement volume; on-site ownership is gaining share fastest among data center specialists.
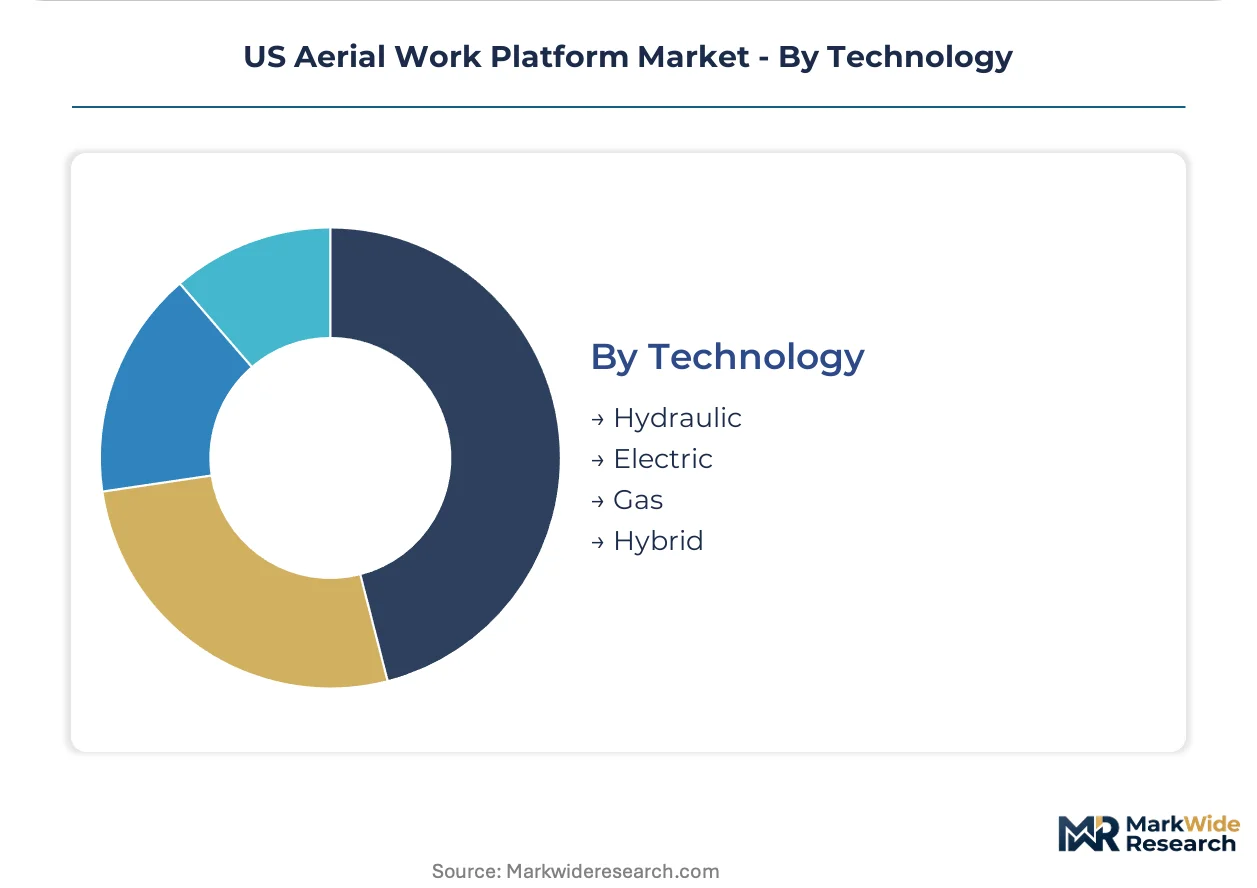
Technology:
Powertrain selection now determines facility access permissions as municipal contracts adopt engine-ban clauses.
- Electric:Battery-electric platforms with lithium iron phosphate packs are achieving diesel-comparable duty cycles. California clean fleet mandates are accelerating procurement ahead of total cost of ownership parity.
- Hydraulic:Diesel-hydraulic systems retain dominance in heavy-lift applications exceeding electric torque limits. Steel input volatility on boom fabrication is compressing OEM margins on these units.
- Hybrid:Dual-power architectures enable indoor-outdoor flexibility for mixed-use contractors. EPA Tier 4 Final compliance adds aftertreatment cost that hybrid designs partially offset.
- Gas:Propane-fueled units serve transitional fleets in jurisdictions without full electrification mandates. Indoor air quality regulations are restricting permissible runtime in enclosed facilities.
Hydraulic systems retain the largest installed base; electric platforms are expanding most quickly as battery economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mills in Indiana and Ohio supply high-strength alloy plate that anchors boom fabrication for the domestic aerial work platform supply chain. Regional demand concentrates in Sun Belt construction corridors and Great Lakes manufacturing belts where fleet electrification mandates are reshaping procurement patterns.
Texas
Utility grid hardening programs and data center construction in Dallas-Fort Worth and Austin drive insulated boom lift demand. ERCOT infrastructure resilience mandates accelerate bucket truck fleet expansion for storm recovery. Houston's petrochemical maintenance sector specifies hybrid platforms for refinery turnaround work.
California
Clean fleet mandates under CARB regulations force rental operators toward battery-electric procurement ahead of total cost parity. Bay Area data center builds and Los Angeles commercial construction require compact electric scissor lifts for indoor mechanical installation. Sacramento's warehouse construction boom absorbs slab-work platform volumes.
Florida
Hurricane recovery protocols and vegetation management programs expand utility bucket truck fleets across investor-owned territories. Miami-Dade commercial high-rise construction and Tampa warehouse development drive rental demand for articulating booms. Orlando's theme park maintenance sector specifies zero-emission vertical masts for indoor facility work.
Michigan
Automotive battery plant retrofits in Detroit and Grand Rapids require zero-emission elevated access for assembly line reconfiguration. Michigan OSHA alignment with federal standards tightens operator certification requirements for manufacturing contractors. Lansing's state procurement policies now preference electric platforms for public infrastructure contracts.
Pennsylvania
Integrated supply chain operations in the Pittsburgh corridor sustain rapid fulfillment timelines for rental channel partners. Philadelphia's commercial construction recovery and Harrisburg infrastructure maintenance absorb boom lift and telehandler placements. State-level apprenticeship programs address certified operator scarcity through union-affiliated training centers.
US Aerial Work Platform Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification specialization and telematics integration. The vendor base clusters around three strategic archetypes: integrated domestic manufacturers with captive component supply, European specialists in compact electric designs, and Asian scale players penetrating through price-competitive entry models. Dominant competitive moves include backward integration into battery pack assembly and strategic partnerships with rental houses for fleet data sharing.
Among Pennsylvania-based integrated producers, JLG Industries exemplifies the captive supply chain archetype through its Midwest fabrication footprint. Terex Corporation anchors the multi-brand portfolio tier with its Genie operations. Haulotte Group represents the European electric specialization vector. These three occupy positions across distinct competitive vectors rather than direct feature-for-feature rivalry.
| Leading Market Players |
|---|
| JLG Industries |
| Terex Corporation |
| Haulotte Group |
| Skyjack |
| Snorkel Lifts |
| Manitou Group |
| LGMG North America |
| Palfinger AG |
| Niftylift |
| Others |
Pricing and Supply Chain Analysis
Fleet electrification mandates from California and New York are compelling rental operators to specify lithium iron phosphate battery systems ahead of total cost parity, forcing OEMs to absorb battery pack premiums while steel input volatility on boom fabrication compresses margin visibility on multi-quarter orders.
Pricing Analysis
Extended warranty and telematics bundling now separate premium-tier procurement from unbundled economy transactions. Three-tier pricing structure across premium, standard, and economy levels tracks ANSI A92 certification grade and integrated service coverage. Cost compression in the economy tier is intensifying because Asian scale players are penetrating through price-competitive entry models. Large rental houses with multi-state footprints show the least price sensitivity due to utilization guarantees, while small regional lessors face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Pennsylvania and Iowa anchor hub-and-spoke fulfillment patterns that sustain rapid turnaround timelines for rental channel partners. High-strength alloy plate draws from domestic steel mills in Indiana and Ohio, while lithium-ion cell production centers on South Korean and Chinese manufacturing bases. Single-source vulnerability in battery supply exposes fleet buyers to logistics bottlenecks and duty exposure. Distribution runs through integrated manufacturer-direct networks and third-party equipment lessors with captive service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is concentrating around backward integration into battery pack assembly and control systems engineering, as players race to capture margin upstream and secure supply certainty for electrified platform architectures.
For Market Incumbents: Deepen captive supply chain control over mast fabrication and thermal management systems to defend against Asian scale entrants penetrating through price-competitive electric models. Expand Pennsylvania and Iowa distribution footprints to compress fulfillment timelines for Sun Belt rental partners. Prioritize ANSI A92.24 training accreditation investments that bundle certification with equipment delivery.
For New Entrants and Emerging Players: CARB clean fleet mandates in California open a window for compact electric scissor lift specialization targeting data center construction in Northern Virginia and Phoenix. Target automotive battery plant retrofits in Michigan and Tennessee where zero-emission elevated access demand outpaces incumbent capacity. Pursue telematics-native platform designs that enable utilization-based pricing for commercial property portfolios.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive component supply and established rental house data partnerships. Long-term viability hinges on residual value management capabilities as electric platform depreciation curves diverge from diesel legacy units. Monitor municipal engine-ban clause adoption in Texas and Florida contract specifications as inflection indicator for stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Assembly Integration | Captures margin upstream from lithium iron phosphate cell supply concentrated in Asian manufacturing bases. |
| Telematics-Enabled Fleet Partnerships | Enables utilization-based pricing models for United Rentals and Sunbelt Rentals channel partners. |
| ANSI A92.24 Training Accreditation | Bundles operator certification with equipment delivery to reduce jobsite startup friction for multi-state contractors. |
| Zero-Emission Platform Specialization | Addresses CARB mandates and indoor air quality restrictions tightening across California and New York. |
| Regional Distribution Expansion | Compresses fulfillment timelines for Texas and Florida construction corridors through Pennsylvania and Iowa hubs. |
Research Methodology
Document review covered SEC 10-K filings from equipment manufacturers, EPA Tier 4 Final regulatory dockets, and OSHA 29 CFR 1926 enforcement data, complemented by interviews with fleet procurement managers at major rental houses, plant engineers at automotive battery facilities, and aftermarket service heads at regional lessors. Secondary validation drew from customs trade records, ANSI standards documentation, and utility capital expenditure disclosures. Bottom-up unit placement estimates triangulated against top-down construction spending allocations.
Segmented outputs across powertrain technology, product type, and end-use vertical were generated over the projection horizon. Modeled dimensions included electric-hydraulic-hybrid-gas architecture, scissor-boom-telehandler-mast category, and construction-manufacturing-utility-maintenance application. CAGRs were derived from fitted trend lines adjusted for fleet refresh cycle compression and electrification mandate propagation. Key inputs encompassed steel price indices, battery pack cost curves, and non-residential building permit flows.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric platform runtime parity. Forecasts reflect documented assumptions regarding regulatory enforcement timing and rental penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
United States Crane Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Drilling Machine Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Cold Planers Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Fixed Crane Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Grout Bags Market
Construction Equipment
Stick Welding Electrode Market