
 Flood Control Sandbags Market | 2026-2036
Flood Control Sandbags Market Size, Share, and Industry Trends Forecast 2026-2036
Flood Control Sandbags Market Insights
Polypropylene is realigning flood control sandbag economics as it displaces traditional burlap across cost-sensitive procurement channels. Cherokee Manufacturing leverages vertical integration in woven polypropylene to sustain margin stability during resin price cycles. Palmetto Industries anchors Gulf Coast distribution through dedicated disaster-response logistics networks. FloodSax differentiates via self-inflating polymer technology that eliminates on-site fill requirements.
Flood control sandbags are temporary, fillable containers constructed from woven or non-woven materials, typically measuring 14 by 26 inches and rated for 50-pound sand capacity, designed to create impermeable barriers against rising water and soil erosion. Polypropylene sandbags dominate municipal procurement due to UV resistance and tensile strength exceeding 800 psi, while burlap sandbags retain niche demand among environmental contractors seeking biodegradable erosion control. Emergency response applications command premium pricing through expedited fulfillment requirements, whereas water diversion projects generate recurring volume through seasonal infrastructure maintenance programs.
The EPA administers stormwater discharge permits under the National Pollutant Discharge Elimination System, directly mandating temporary sediment controls that elevate sandbag specifications for construction sites. FEMA's hazard mitigation grants shape demand timing through post-disaster replenishment cycles that prioritize pre-qualified suppliers. Stakeholders must monitor evolving material standards from the American Society for Testing and Materials regarding synthetic fabric degradation rates, as regulatory recognition of extended-lifecycle alternatives could restructure competitive positioning among incumbent manufacturers.
Market Dynamics
Polypropylene resin price volatility is compressing margins across woven bag manufacturers while EPA stormwater enforcement tightens specification requirements for temporary erosion controls. Municipal procurement cycles now synchronize with FEMA hazard mitigation grant calendars, creating predictable demand spikes that favor suppliers with pre-positioned inventory.
Growth Catalysts
- EPA NPDES Permit Expansion:Construction site coverage mandates under the National Pollutant Discharge Elimination System are elevating sandbag deployment rates for sediment control. The regulation applies to sites disturbing one acre or more.
- Hurricane Corridor Infrastructure Hardening:Gulf Coast municipalities are institutionalizing annual stockpile replenishment protocols. Louisiana and Texas counties now maintain 90-day emergency reserves versus historical 30-day levels.
- Polymer Self-Inflation Technology:Self-inflating sandbag alternatives are eliminating on-site fill labor and reducing deployment time from hours to minutes. Emergency response teams are prioritizing these systems for rapid barrier construction.
Market Restraints
- Propylene Feedstock Volatility:Polypropylene resin costs fluctuate with crude oil and natural gas liquid pricing. Woven bag manufacturers lack pricing power to pass through input spikes to municipal buyers locked in annual contracts.
- Burlap Biodegradability Standards:ASTM D6400 compostability certification requirements for biodegradable erosion controls are raising burlap sandbag costs. Environmental contractors face specification conflicts between performance and biodegradation timelines.
- Single-Source Woven Fabric Concentration:Domestic polypropylene weaving capacity concentrates in the Southeast United States. Transportation costs to Western emergency response zones create regional supply imbalances during concurrent demand events.
Strategic Opportunities
- Midwest Riverine Floodplain Expansion:Mississippi and Missouri basin counties are adopting sandbag-based temporary levee systems. These jurisdictions historically relied on permanent infrastructure and represent untapped procurement volume.
- FEMA Pre-Positioned Stockpile Contracts:The agency's strategic national stockpile program is soliciting multi-year supply agreements. Qualified vendors gain priority access to post-disaster replenishment orders.
- UV-Stabilized Recycled Content Mandates:California and New York procurement guidelines are requiring minimum recycled polypropylene content. Early compliance positions suppliers for premium-tier specification capture.
Industry Challenges
- ASTM D3787 Burst Strength Certification:Testing facility bottlenecks are extending product qualification timelines from 6 weeks to 14 weeks. Manufacturers face working capital strain from finished goods inventory holds.
- Warehouse Network Reconfiguration:Just-in-time municipal delivery expectations are forcing distributors to maintain satellite facilities in secondary markets. Real estate and inventory carrying costs are eroding distributor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flood Control Sandbags Market |
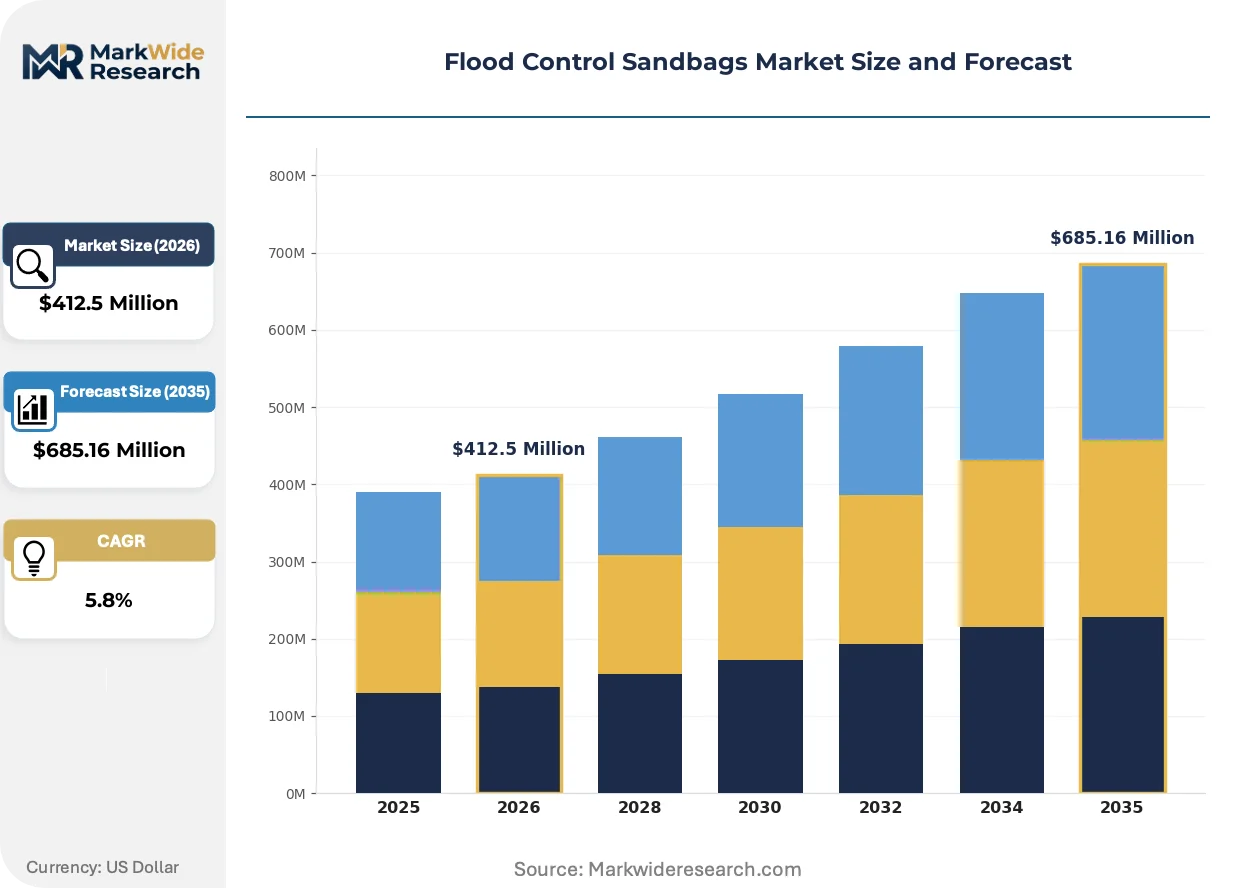
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene Sandbags, Burlap Sandbags, Plastic Sandbags, PVC Sandbags Application: Temporary Flood Barriers, Erosion Control, Water Diversion, Emergency Response End User: Municipalities, Construction Firms, Disaster Management Agencies, Environmental Contractors Distribution Channel: Direct Sales, Retail Stores, Online Retailers, Wholesale Suppliers |
| Companies Covered | Cherokee Manufacturing, Rapid Packaging, Palmetto Industries, FloodSax, IBS Technics GmbH, FloodBreak, The Flood Company, Quick Dam, TrapBag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flood Control Sandbags Market Trends and Innovations
Sandbag technology is bifurcating between commodity woven polypropylene and advanced polymer systems that eliminate manual fill operations. Regulatory pressure on deployment speed and labor safety is accelerating adoption of pre-filled alternatives.
Self-inflating polymer sandbags are decentralizing emergency response logistics by eliminating the need for sand sourcing and fill equipment at deployment sites. Municipal fire departments and county emergency management agencies are adopting these systems for rapid neighborhood protection. The technology is compressing traditional supply chain requirements by shifting inventory from bulk sand to compact, pre-positioned polymer units.
EPA enforcement of Construction General Permit sediment control provisions is mandating higher sandbag specification tiers for stormwater management. Sites in impaired watersheds now face enhanced monitoring and reporting obligations. California and Florida construction markets are responding by specifying UV-stabilized, high-tensile woven bags with documented burst strength certification.
Consolidated municipal purchasing cooperatives are displacing individual agency procurement for sandbag acquisition. State-level emergency management associations are negotiating master supply agreements that aggregate demand across counties. Texas and Florida are most advanced in this transition, with cooperative contracts covering 60 percent of annual municipal volume.
Flood Control Sandbags Market Segmentation
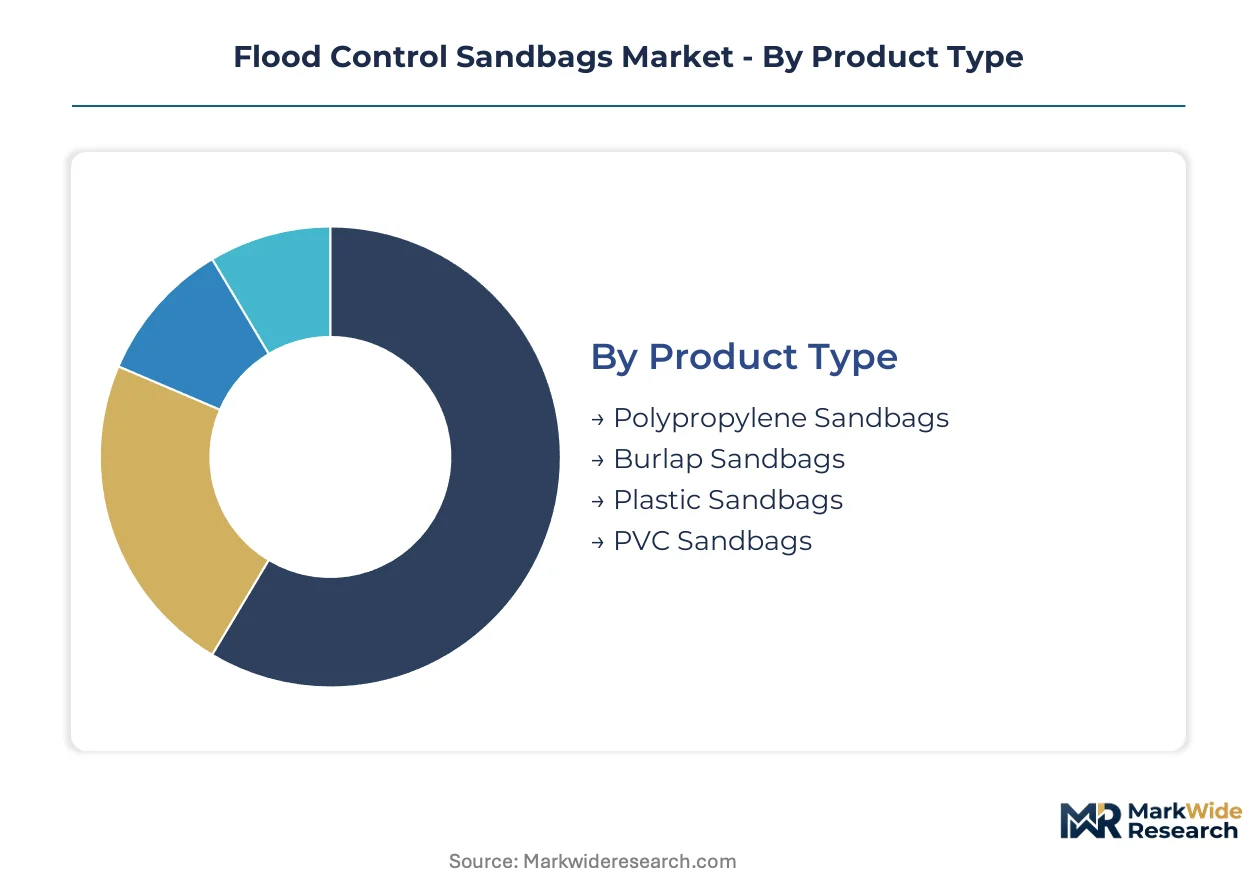
Flood control sandbags serve heterogeneous deployment scenarios that demand material and specification matching. Municipal buyers prioritize UV stability and burst strength for stockpile longevity, while emergency responders trade durability for deployment speed. Segmentation reveals where procurement premiums concentrate versus where commodity sourcing dominates.
Product Type:
The customization-standardization spectrum runs from engineered polymer specifications to commodity natural fiber alternatives, with municipal procurement gravitating toward certified synthetics and environmental applications tolerating biodegradable trade-offs.
- Polypropylene Sandbags:Woven polypropylene construction delivers tensile strength exceeding 800 psi with UV stabilization for multi-season stockpile storage. Gulf Coast municipalities specify these for hurricane season pre-positioning, driven by FEMA hazard mitigation grant requirements for 90-day emergency reserves.
- Burlap Sandbags:Natural jute fiber construction provides biodegradable erosion control that satisfies EPA stormwater management regulations for temporary sediment barriers. Environmental contractors on California and Florida construction sites specify these where ASTM D6400 compostability certification outweighs performance longevity concerns.
- Plastic Sandbags:Extruded polyethylene construction offers intermediate durability at lower unit cost than woven polypropylene.
- PVC Sandbags:Reinforced vinyl construction delivers maximum impermeability for high-pressure water diversion applications.
Most installed capacity flows through Polypropylene Sandbags. Expansion is steepest in PVC Sandbags for engineered water diversion projects.
Application:
Volume concentration sits with recurring infrastructure maintenance programs, while margin concentration follows expedited fulfillment requirements for unscheduled emergency deployment.
- Temporary Flood Barriers:Stacked sandbag walls form impermeable perimeter defenses against rising water, typically deployed in 14-inch by 26-inch configurations rated for 50-pound fill capacity. Louisiana and Texas counties institutionalized annual stockpile replenishment protocols that synchronize procurement with hurricane season preparation windows.
- Erosion Control:Slope stabilization and sediment retention applications on construction sites disturbing one acre or more fall under EPA NPDES Construction General Permit mandates. Sites in impaired watersheds face enhanced monitoring obligations that elevate specification tiers toward UV-stabilized, burst-strength-certified bags.
- Water Diversion:Channel redirection and flow management for seasonal infrastructure maintenance generates predictable recurring volume through municipal public works departments.
- Emergency Response:Rapid deployment for unscheduled flood events commands expedited fulfillment premiums and prioritizes pre-positioned inventory access.
Water Diversion captures the highest recurring volume base. Emergency Response is climbing the fastest as self-inflating polymer alternatives compress deployment timelines.
End User:
Procurement authority concentrates in public-sector entities with grant-funded replenishment cycles, while private-sector demand fragments across compliance-driven construction and environmental remediation.
- Municipalities:City and county emergency management agencies maintain strategic stockpiles with specification requirements tied to FEMA pre-positioned stockpile contract eligibility. Texas and Florida cooperative purchasing agreements now aggregate demand across county lines, covering 60 percent of annual municipal volume.
- Construction Firms:Site operators require NPDES-compliant sediment controls for ground disturbance exceeding one acre, with California and Florida markets specifying documented burst strength certification.
- Disaster Management Agencies:State and federal emergency response coordinators prioritize rapid deployment capability over unit cost optimization.
- Environmental Contractors:Remediation specialists specify biodegradable alternatives where project timelines align with compostability degradation windows.
Municipalities anchor procurement volume. Disaster Management Agencies are gaining share fastest as FEMA strategic stockpile program expands multi-year supply agreements.
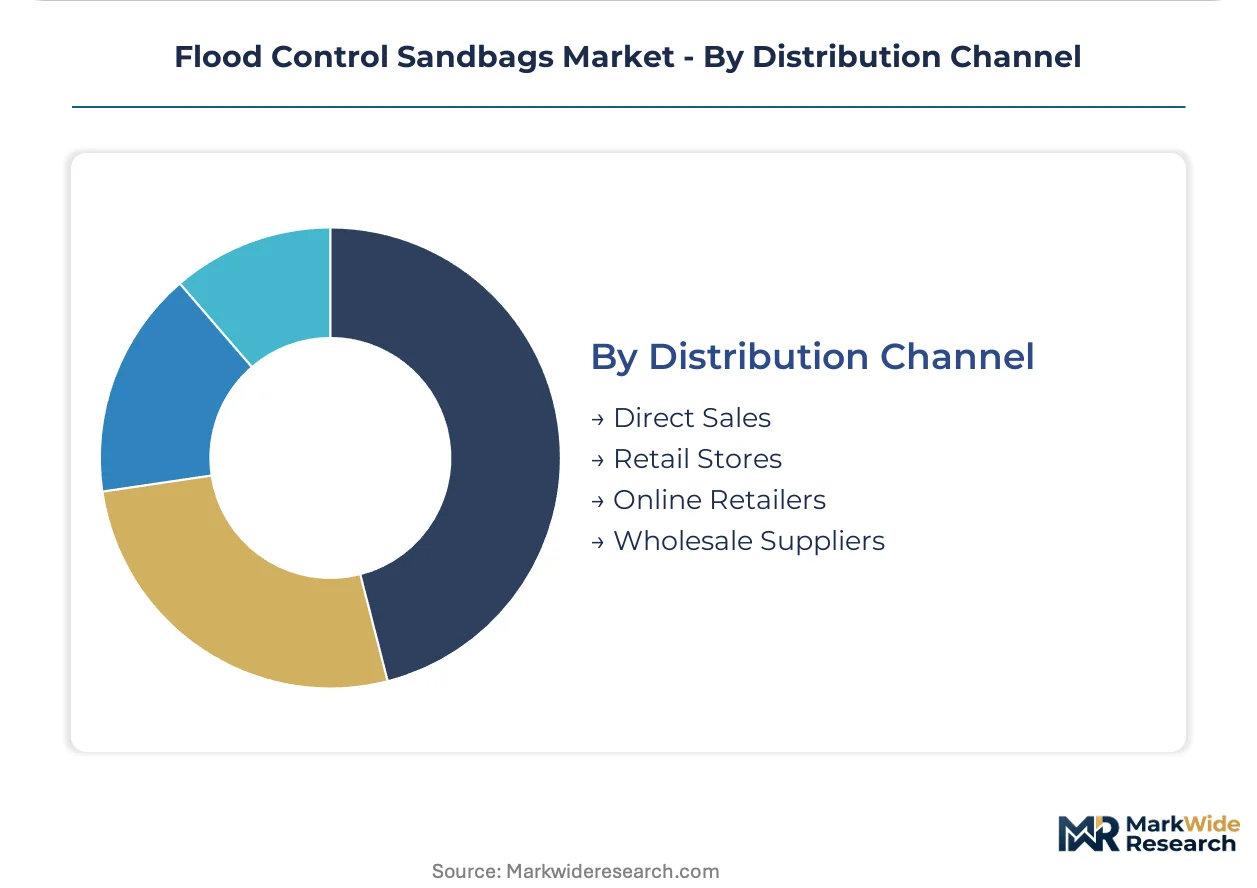
Distribution Channel:
Channel selection tracks order urgency and specification complexity, with direct relationships dominating large-volume municipal contracts and retail channels capturing small-quantity emergency replenishment.
- Direct Sales:Manufacturer-to-agency relationships support custom specification development and pre-positioned inventory arrangements. FEMA pre-qualified supplier status creates preferential access to post-disaster replenishment orders.
- Wholesale Suppliers:Regional distributors maintain satellite warehouse networks to satisfy just-in-time municipal delivery expectations, though real estate and inventory carrying costs compress margins.
- Retail Stores:Home improvement and agricultural supply outlets serve individual property owners and small contractors with standard-specification polypropylene bags.
- Online Retailers:E-commerce platforms facilitate rapid sourcing for unplanned emergency needs, particularly in Midwest riverine floodplains where historical reliance on permanent infrastructure limited traditional distribution presence.
Wholesale Suppliers move the highest transaction volume. Online Retailers are expanding most quickly as self-inflating polymer products enable compact inventory storage and rapid shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast metropolitan clusters dominate flood control sandbag procurement through hurricane-driven replenishment cycles and FEMA-funded stockpile programs.
United States
Louisiana and Texas counties maintain institutionalized 90-day emergency reserves versus historical 30-day levels, synchronizing procurement with hurricane season preparation windows. EPA NPDES Construction General Permit enforcement mandates sediment controls for sites disturbing one acre or more, elevating specification tiers toward UV-stabilized woven bags. Houston-Galveston and New Orleans metropolitan areas anchor domestic polypropylene weaving capacity concentration.
Germany
Rhine and Danube basin municipalities are adopting temporary sandbag levee systems as climate adaptation measures intensify. The country's national environmental regulator enforces stormwater management standards that align with EU-wide flood risk directives. Bavaria and Baden-Württemberg industrial clusters supply woven polypropylene fabric to Central European construction and emergency management sectors.
United Kingdom
Environment Agency flood defense procurement is shifting toward pre-positioned polymer alternatives for rapid deployment along Thames and Severn catchments. The national regulator's flood risk management regulations mandate temporary protection measures for designated high-risk zones. Greater Manchester and Yorkshire urban centers are piloting cooperative purchasing agreements modeled on Texas and Florida frameworks.
Netherlands
Randstad delta protection programs integrate sandbag systems into layered flood defense strategies alongside permanent infrastructure. The country's national water management authority coordinates procurement through Rijkswaterstaat emergency response protocols. Rotterdam-The Hague metropolitan logistics networks pre-position inventory for North Sea storm surge contingencies.
Japan
Typhoon corridor prefectures are expanding municipal stockpiles following revised disaster management framework requirements. The Ministry of Economy, Trade and Industry supports domestic woven fabric production for critical infrastructure materials. Kansai and Kyushu industrial zones manufacture high-tensile polypropylene bags for domestic consumption and selective export to Southeast Asian markets.
Flood Control Sandbags Market Competitive Landscape
Global majors compete with regional champions across material technology and emergency response logistics networks. Market structure tilts toward consolidated municipal procurement channels where FEMA pre-qualified supplier status creates preferential access barriers. Three archetypes dominate: vertically integrated woven fabric producers, specialized polymer technology developers, and regional distribution specialists with satellite warehouse networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure resin supply agreements and pre-position inventory near hurricane corridors.
Among North American specialists, Cherokee Manufacturing anchors the integrated production tier, while Palmetto Industries exemplifies Gulf Coast distribution concentration. FloodSax occupies a position within the polymer technology vector through self-inflating alternatives that eliminate on-site fill requirements. IBS Technics GmbH represents European engineering-focused positioning, with FloodBreak and Quick Dam sitting within the rapid-deployment product category. The Flood Company and TrapBag complete the named set, each representing distinct geographic or technological specializations without overlapping core positioning.
| Leading Market Players |
|---|
| Cherokee Manufacturing |
| Rapid Packaging |
| Palmetto Industries |
| FloodSax |
| IBS Technics GmbH |
| FloodBreak |
| The Flood Company |
| Quick Dam |
| TrapBag |
| Others |
Pricing and Supply Chain Analysis
Polypropylene resin futures on the CME Group commodity index cascade through woven bag manufacturing into three distinct pricing tiers that separate FEMA-prequalified municipal suppliers from secondary wholesale distributors and spot-market retail channels. Louisiana and Texas counties with 90-day emergency reserve mandates absorb premium contract pricing, while construction contractors facing EPA NPDES compliance costs gravitate toward mid-tier UV-stabilized specifications, and individual property owners in Midwest riverine floodplains default to economy-grade burlap alternatives.
Pricing Analysis
Input-cost pass-through from propylene feedstock volatility compresses margins for manufacturers locked into annual municipal contracts that lack resin price escalation clauses. Pricing stratifies across premium, standard, and economy tiers based on burst strength certification tier and geographic delivery radius. Pricing pressure stems from polypropylene weaving capacity concentration in the Southeast United States that limits regional pricing power. Municipal buyers with cooperative purchasing agreements exhibit lowest price sensitivity; small contractors in impaired watersheds face highest sensitivity due to compliance-driven specification mandates.
Supply Chain Analysis
Freight costs from Southeast weaving clusters to Western emergency response zones create regional supply imbalances that elevate landed costs for California and Pacific Northwest municipal buyers. Domestic polypropylene fabric production concentrates in the United States, with secondary weaving operations in Germany and Japan supplying European and Asian markets. Raw material dependencies rest on crude oil derivatives, natural gas liquids, and UV stabilizer additives. Single-source woven fabric concentration in hurricane corridor states creates vulnerability to concurrent demand events. Distribution runs through wholesale suppliers maintaining satellite warehouse networks for just-in-time municipal delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as FEMA pre-positioned stockpile contracts and EPA NPDES enforcement drive procurement toward certified premium specifications that command durable margin premiums over commodity alternatives.
For Market Incumbents: Acquire satellite warehouse assets in Midwest riverine floodplains where historical reliance on permanent infrastructure has left distribution networks underdeveloped. Cherokee Manufacturing and Palmetto Industries should expand backward integration into resin supply agreements to defend against propylene feedstock volatility that erodes contract margins. Secure ASTM D3787 burst strength certification ahead of testing facility bottlenecks to maintain FEMA pre-qualified supplier status. For New Entrants and Emerging Players: E-commerce direct-to-municipality platforms offer the most penetrable route for self-inflating polymer alternatives that eliminate sand sourcing logistics and compress deployment timelines. Target county emergency management agencies in Mississippi and Missouri basin jurisdictions that are adopting temporary levee systems without established supplier relationships. Lead with rapid-deployment capability demonstrations rather than unit cost competition. For Investors and Strategic Acquirers: Asymmetric upside sits with polymer technology developers holding proprietary self-inflation chemistry that displaces manual fill operations across emergency response applications. Long-term viability hinges on regulatory recognition of deployment speed advantages in FEMA grant allocation frameworks. Watch for California and New York recycled content mandate expansion as the inflection signal for UV-stabilized recycled polypropylene premium tier capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive propylene sourcing insulates margin stability against crude oil price cycles for woven bag manufacturers. |
| ASTM Certification Pre-Positioning | Burst strength documentation secures FEMA pre-qualified supplier status ahead of testing facility bottlenecks. |
| Midwest Warehouse Network Expansion | Satellite facilities in Missouri and Iowa counties address just-in-time delivery expectations for riverine floodplain protection. |
| Recycled Content Compliance Investment | California and New York procurement guidelines create premium-tier specification capture for early compliance. |
| Self-Inflating Polymer R&D Partnership | Deployment speed advantages align with EPA labor safety pressure and FEMA rapid response grant priorities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal emergency management directors, woven polypropylene plant managers, EPA compliance officers, FEMA procurement specialists, and construction site operators with secondary validation against customs trade data, SEC filings from resin suppliers, ASTM standard documentation, and FEMA hazard mitigation grant disbursement records. Bottom-up county-level stockpile assessments triangulated against top-down national market sizing.
Comparable historical procurement cycles anchored the forecast window to hurricane season replenishment patterns and post-disaster FEMA grant authorization timelines. The analytical framework modeled segmentation across material technology, application scenario, end-user authority, and distribution channel across the projection horizon. CAGRs derived from municipal budget allocation trajectories and construction permit volume trends. Key inputs included polypropylene resin price indices and cooperative purchasing agreement expansion rates.
The model assumes a particular technology adoption path; alternative pathways for self-inflating polymer deployment would alter the outlook if labor cost pressures or regulatory recognition accelerate faster than baseline assumptions. Forecasts reflect documented assumptions regarding FEMA grant continuity and EPA enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Submersible Dredge Pump Market