
 Global Pipe Laying Vessel Market | 2026-2036
Global Pipe Laying Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipe Laying Vessel Market Intelligence
The DNV-ST-N001 standard for marine operations is unwinding the historical separation between vessel capability and project complexity, mandating higher specifications for deepwater projects. Allseas specializes in complex, heavy-lift, and deepwater S-lay and J-lay projects. Boskalis leverages its diverse fleet for both traditional oil and gas installations and emerging offshore wind projects. Seaway7 ASA positions itself as a key contractor for subsea cable installation in the renewables sector.
A pipe laying vessel is a specialized maritime craft for subsea installation of pipelines and umbilicals. Key systems include S-lay or J-lay configurations and DP3-rated dynamic positioning to ensure stability during deepwater operations. J-lay vessels remain dominant for deepwater oil and gas applications, while reel-lay vessels are essential for offshore wind farm cabling. Subsea engineering contractors now prioritize vessels integrating heavy lift cranes with advanced remote operated vehicles for complex infrastructure deployment.
The International Maritime Organization's MARPOL convention dictates vessel emission standards, impacting engine and fuel selection. Environmental regulations from the U.S. EPA and under EU directives shape project permitting and operational procedures for subsea work. Fleet operators must decide whether to upgrade aging assets for compliance or invest in newbuilds optimized for deepwater and renewables.
Market Dynamics
The central force shaping the pipe laying vessel market is the dual demand from deepwater hydrocarbon projects and offshore renewable energy infrastructure. This creates a technical and commercial divergence, forcing fleet operators to specialize in either high-specification deepwater assets or versatile cable-lay vessels.
Growth Catalysts
- Offshore Wind Expansion:A primary source of new contracts stems from the rapid build-out of offshore wind farms, particularly in the North Sea and off the coast of the United States, which require extensive subsea cable installation.
- Deepwater Exploration:Renewed investment in deepwater oil and gas fields, especially in the pre-salt basins offshore Brazil and emerging plays in Guyana, drives demand for advanced J-lay and heavy-lift vessel capabilities.
- Subsea Interconnectors:The European Union's Green Deal is accelerating the development of subsea power transmission grids, creating a steady stream of demand for high-voltage cable laying vessels to connect national power systems.
Market Restraints
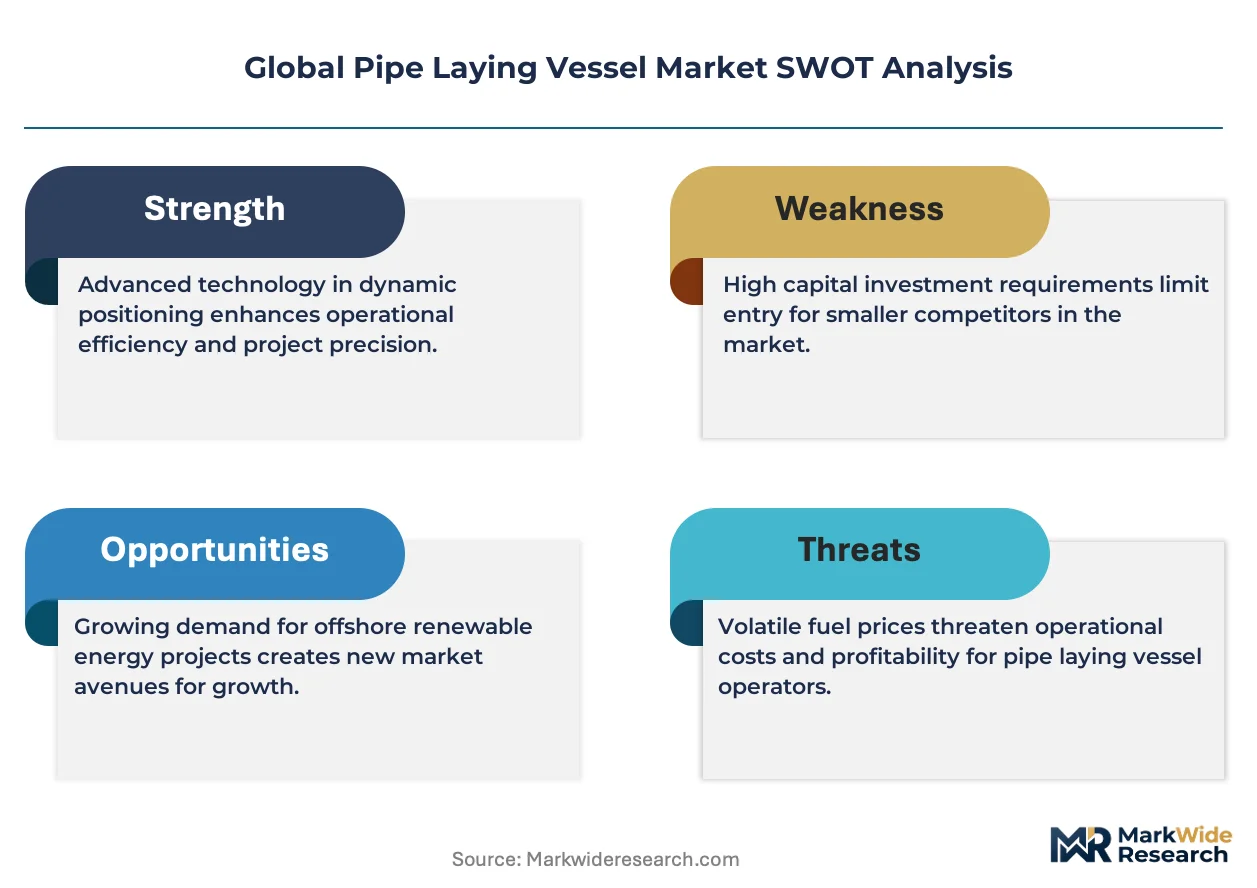
- High Capital Costs:The immense cost of constructing new DP3-rated, high-capacity vessels, along with the significant expense of upgrading older ships to meet modern standards, acts as a major barrier to entry and fleet expansion.
- Stringent Environmental Regulations:Compliance with emission standards under the IMO's MARPOL convention and permitting hurdles from bodies like the U.S. EPA increase operational costs and can delay project timelines.
- Weather-Related Risk:Deepwater operations are highly sensitive to adverse weather conditions, leading to significant non-productive time, increased operational risk, and potential project cost overruns, particularly in harsh environments.
Strategic Opportunities
- Alternative Fuel Adoption:Investing in newbuilds or retrofitting vessels with dual-fuel engines capable of running on LNG or methanol offers a path to long-term regulatory compliance and a competitive advantage with environmentally-conscious clients.
- Floating Wind Infrastructure:Specializing in the installation of dynamic power cables and complex mooring systems for floating offshore wind projects represents a key opportunity in a nascent but high-growth renewables segment.
- Geographic Diversification:Expanding operations into emerging deepwater markets beyond the traditional basins, such as offshore West Africa and the Eastern Mediterranean, allows contractors to capture first-mover advantages in new energy provinces.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of experienced maritime crew, specifically dynamic positioning operators and subsea engineers certified for complex deepwater projects, constrains the operational capacity of advanced vessels.
- Fleet Modernization Mandates:Operators face the difficult financial decision of undertaking costly upgrades to aging assets to comply with new standards like DNV-ST-N001 or risk their fleet becoming uncompetitive for high-specification tenders.
- Complex Systems Integration:Ensuring seamless integration of advanced remote operated vehicles, digital twin monitoring systems, and automated pipe handling equipment with legacy vessel control platforms presents a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipe Laying Vessel Market |
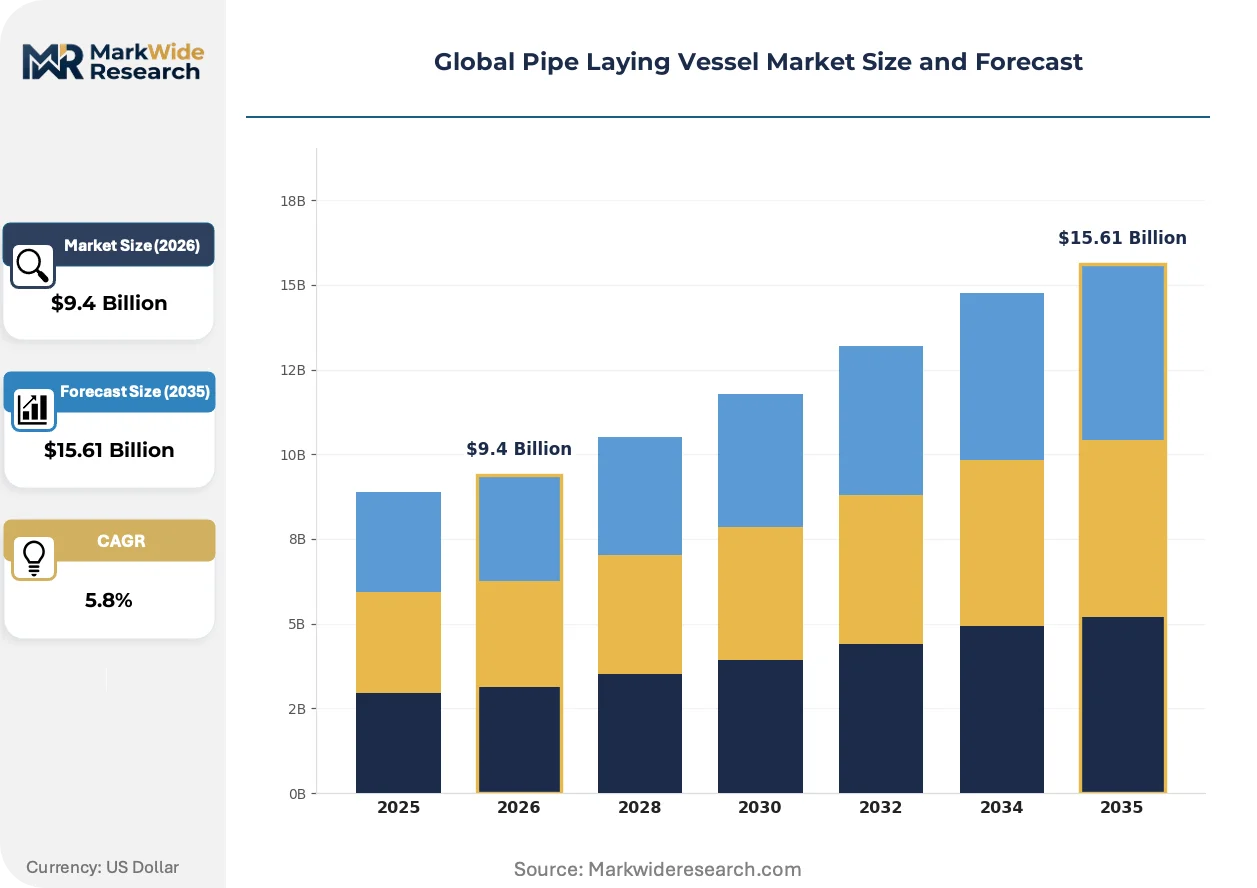
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: S-Lay Vessels, J-Lay Vessels, Reel-Lay Vessels, Divers Support Vessels, Multi-Purpose Support Vessels Technology: Dynamic Positioning, Offshore Welding, Remote Operated Vehicles, Subsea Survey Systems, Heavy Lift Cranes Application: Oil & Gas Pipeline Installation, Offshore Wind Farm Cabling, Subsea Infrastructure Deployment, Undersea Cable Laying End User: Exploration & Production Companies, Marine Construction Firms, Subsea Engineering Contractors, Energy Service Providers |
| Companies Covered | Nexans SA, DEME, Allseas, Boskalis, Jan De Nul, Prysmian S.p.A., Van Oord Dredging and Marine Contractors B.V., Azerbaijan Caspian Sea Shipping CJSC, Seaway7 ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipe Laying Vessel Market Strategic Shifts & Innovations
Technological specialization is reshaping the competitive landscape, creating distinct classes of vessels optimized for either deepwater energy or shallow-water renewables. This divergence influences fleet strategy, investment decisions, and the capabilities contractors must bring to integrated subsea projects, from design through commissioning.
Vessel design itself is undergoing a significant evolution driven by project complexity. The core function involves advanced pipe and cable handling systems, such as S-lay, J-lay, or reel-lay configurations. Deepwater oil and gas operators require J-lay vessels for extreme depths, while offshore wind developers favor reel-lay for speed in cable installation. This divergence in end-user needs is bifurcating the fleet into high-specification, heavy-lift assets and more agile, multi-purpose vessels for renewables.
The International Maritime Organization's MARPOL convention, specifically Annex VI, imposes strict limits on vessel emissions, including sulfur and nitrogen oxides. This global regulation forces operators to invest in exhaust gas cleaning systems, adopt cleaner fuels like LNG, or commission newbuilds with compliant engines. The financial impact is most significant for owners of mid-life or older vessels, particularly those operating in Emission Control Areas in North America and Europe.
A clear shift in contracting models favors integrated service packages over single-task vessel charters. Energy developers are now bundling subsea installation with survey, ROV support, and commissioning into a single engineering, procurement, and construction contract. This trend is most prominent in large-scale offshore wind farm developments, where project owners seek a single point of responsibility from contractors possessing a diverse fleet and extensive subsea engineering capabilities.
Global Pipe Laying Vessel Market Segmentation
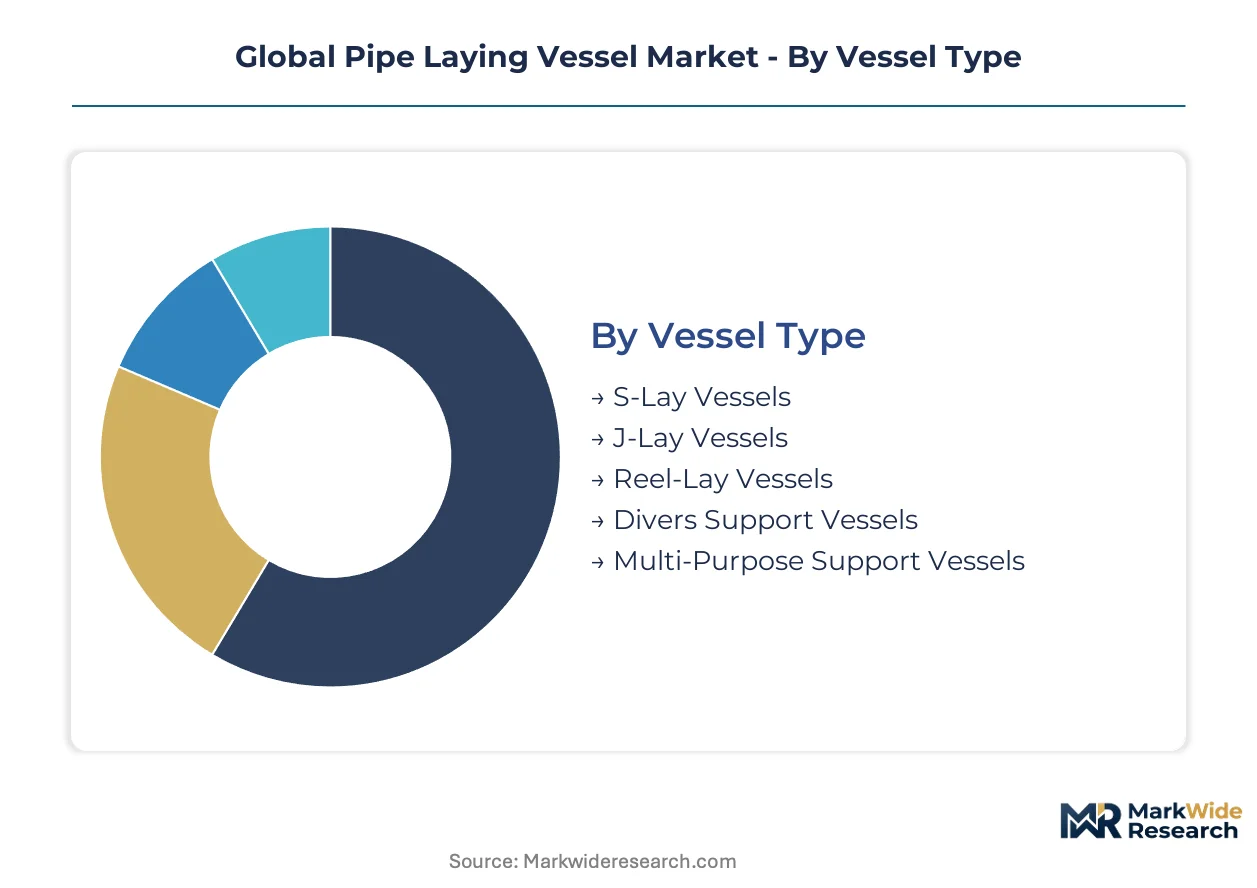
The Global Pipe Laying Vessel Market divides into distinct segments, each driven by specific technical requirements and end-user demands. Understanding these categories is essential for identifying areas of concentrated investment and emerging project opportunities within the subsea construction industry.
Vessel Type:
The geographic distribution of pipe laying vessel deployment often reflects regional energy priorities, with certain vessel types dominating in specific offshore basins.
- J-Lay Vessels:These vessels are optimized for deepwater and ultra-deepwater pipeline installation, handling pipe sections vertically from the vessel. Demand concentrates in challenging environments like the pre-salt basins offshore Brazil and the Gulf of Mexico, driven by complex hydrocarbon exploration projects.
- Reel-Lay Vessels:Designed for rapid installation of pre-welded pipeline sections spooled onto large reels, these vessels are essential for offshore wind farm cabling. Their efficiency is critical for connecting new wind energy projects in the North Sea and off the United States coast.
- S-Lay Vessels:These vessels lay pipelines in a horizontal S-curve configuration, primarily used for shallower water oil and gas projects. Their versatility supports various nearshore and continental shelf developments.
- Divers Support Vessels:Specialized vessels provide accommodation and operational support for saturation and air diving operations during subsea construction. These are crucial for inspection, maintenance, and repair tasks in various water depths.
- Multi-Purpose Support Vessels:These versatile ships combine various capabilities, including subsea construction, inspection, and light intervention, catering to diverse project requirements.
J-Lay Vessels command the established deepwater base. The steepest expansion runs through Reel-Lay Vessels.
Technology:
The cost structure for pipe laying technologies varies significantly, influencing investment decisions based on project scale and complexity.
- Dynamic Positioning:DP3-rated systems maintain precise vessel position without anchors, essential for deepwater operations and challenging environments. This technology minimizes non-productive time and enhances safety during complex subsea installations.
- Remote Operated Vehicles:Advanced ROVs provide crucial subsea inspection, intervention, and construction support, integrating with heavy-lift cranes for complex infrastructure deployment. Their capabilities are expanding for intricate tasks in ultra-deepwater.
- Offshore Welding:Automated welding systems ensure high-integrity pipe joints under challenging offshore conditions, critical for long-term pipeline reliability. This technology directly impacts project timelines and structural integrity.
- Subsea Survey Systems:These systems provide detailed seabed mapping and pipeline route surveys, crucial for planning and executing safe subsea installations. Accurate data underpins successful project execution.
- Heavy Lift Cranes:High-capacity cranes are integrated onto vessels for deploying large subsea structures, manifolds, and cable protection systems. Their lifting capabilities are vital for complex subsea infrastructure.
Dynamic Positioning systems underpin operational safety. Remote Operated Vehicles are gaining share fastest in complex deployment scenarios.
Application:
Different end-user segments drive demand for specific pipe laying applications, reflecting distinct project requirements and regulatory landscapes.
- Oil & Gas Pipeline Installation:This segment involves deploying pipelines for hydrocarbon transport from offshore fields to processing facilities. Demand for this application remains robust in deepwater basins offshore Brazil and in emerging plays like Guyana.
- Offshore Wind Farm Cabling:This application focuses on installing export and inter-array cables for offshore wind farms, connecting turbines to substations and to shore. The rapid build-out of new projects in the North Sea and off the United States coast drives significant demand.
- Subsea Infrastructure Deployment:This includes the installation of complex subsea production systems, manifolds, and other ancillary equipment for deepwater energy projects. These deployments require high-specification vessels and advanced heavy-lift capabilities.
- Undersea Cable Laying:This application covers the installation of fiber optic communication cables and high-voltage power interconnectors between landmasses or grids. The European Union's Green Deal accelerates investment in these cross-border power transmission projects.
Oil & Gas Pipeline Installation maintains a significant revenue base. Offshore Wind Farm Cabling is climbing the fastest in new project awards.
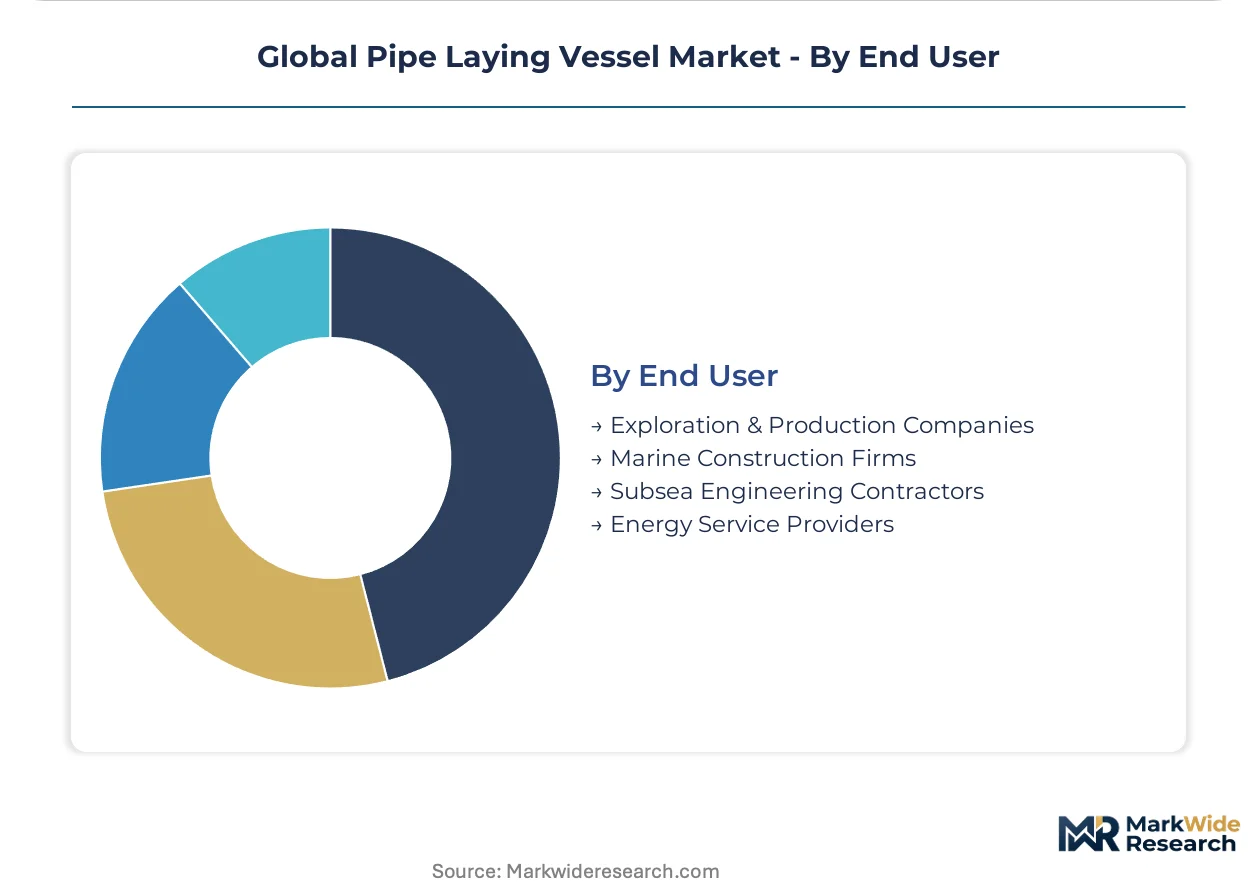
End User:
The supply chain for pipe laying services concentrates around key end-user groups, dictating procurement patterns and long-term contract relationships.
- Exploration & Production Companies:These entities are the primary clients for pipe laying services, commissioning projects for new oil and gas field developments. Major players like Petrobras and ExxonMobil drive significant contract volume.
- Subsea Engineering Contractors:These firms manage integrated engineering, procurement, construction, and installation (EPCI) contracts, often subcontracting vessel services. Companies such as Allseas and Seaway7 ASA offer comprehensive solutions to project owners.
- Marine Construction Firms:These companies specialize in the physical execution of offshore construction projects, including pipeline and cable installation. They often operate their own fleets or charter specialized vessels.
- Energy Service Providers:These companies offer a range of services supporting the energy industry, including subsea installation, maintenance, and decommissioning. Their offerings span both traditional hydrocarbon and renewable energy sectors.
Exploration & Production Companies remain the largest contracting entities. Subsea Engineering Contractors are expanding most quickly through integrated service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Green Deal significantly drives investment in subsea power transmission grids, creating substantial demand for cable laying vessels across the continent. This policy framework accelerates infrastructure development connecting national power systems and offshore wind farms to shore. Regional energy security concerns also reinforce strategic investments in robust subsea networks.
United States
United States demand stems from the rapid expansion of offshore wind farms along the East Coast and continued deepwater oil and gas exploration in the Gulf of Mexico. US EPA regulations influence operational procedures and permitting for subsea work, pushing for environmentally compliant vessels. Key activity concentrates around the Gulf of Mexico for hydrocarbon projects and the Atlantic seaboard for renewable energy developments.
Brazil
Brazil's market is primarily fueled by renewed investment in deepwater oil and gas fields, particularly the pre-salt basins, requiring advanced J-lay vessel capabilities. ANVISA, the country's health and environmental regulator, impacts project permitting and operational standards for offshore activities. Petrobras's extensive exploration and production activities in the Santos and Campos Basins drive significant contract volume.
Netherlands
Netherlands-based operations benefit from the extensive build-out of offshore wind farms in the North Sea, requiring specialized reel-lay vessels for cable installation. EU directives on renewable energy targets shape investment decisions and project pipelines for subsea infrastructure. The port of Rotterdam serves as a major hub for offshore wind logistics and vessel mobilization across the North Sea region.
China
China's market sees dual demand from its ambitious offshore wind development goals and ongoing expansion of domestic oil and gas production facilities. The Ministry of Ecology and Environment (MEE) implements stringent environmental regulations impacting vessel emissions and subsea construction practices. Significant subsea activity occurs in the Bohai Sea and the South China Sea, supporting both energy sectors.
Norway
Norway's market concentrates on sophisticated subsea infrastructure deployment for mature North Sea oil and gas fields and emerging deepwater projects. MARPOL convention compliance influences fleet modernization and fuel choices for vessels operating in Norwegian waters. Stavanger and Bergen remain critical operational bases for specialized subsea engineering and vessel support services.
Global Pipe Laying Vessel Market Key Industry Players
Player mix skews toward specialized marine contractors offering integrated subsea solutions, creating a tiered market structure. This market features large, integrated engineering, procurement, construction, and installation (EPCI) players, alongside more specialized vessel operators focusing on niche capabilities. Dominant competitive moves include strategic partnerships to pool resources for complex projects and ongoing capacity expansion through newbuilds optimized for renewables.
Specialized subsea engineering contractors often represent distinct operational archetypes within this market. Allseas, a European-based firm, exemplifies a focus on complex, heavy-lift, and deepwater S-lay and J-lay projects. Boskalis, a Dutch company, occupies a position leveraging its diverse fleet for both traditional oil and gas installations and emerging offshore wind projects. Seaway7 ASA, a Norwegian-listed entity, anchors its strategy as a key contractor for subsea cable installation in the renewables sector.
| Leading Market Players |
|---|
| Nexans SA |
| DEME |
| Allseas |
| Boskalis |
| Jan De Nul |
| Prysmian S.p.A. |
| Van Oord Dredging and Marine Contractors B.V. |
| Azerbaijan Caspian Sea Shipping CJSC |
| Seaway7 ASA |
| Others |
Cost & Logistics Intelligence
Newbuild vessel lead times, extending several years for high-specification assets, directly influence project pricing power and reflect the specialized nature of the pipe laying vessel supply chain.
Pricing Analysis
Certification level, particularly DNV-ST-N001 compliance and DP3 rating, creates the primary spread in vessel day rates for advanced pipe laying operations. Project-based pricing dominates the market, with long-term contracts for major deepwater or offshore wind developments offering stability. Price differentiation stems from vessel specialization, such as J-lay capabilities for ultra-deepwater and high-capacity heavy-lift cranes. Pricing softness affects older, less compliant assets due to stringent environmental regulations and fleet modernization mandates. Offshore wind farm cabling projects often exhibit higher price sensitivity compared to critical deepwater oil and gas installations.
Supply Chain Analysis
Skilled labor scarcity, specifically for dynamic positioning operators and subsea engineers, represents a chokepoint in the operational supply chain for advanced pipe laying vessels. The supply of high-grade steel for pipelines and complex marine electronics for DP systems draws from a concentrated base, with key shipyards in South Korea and Europe. Geopolitical instability in energy-producing regions poses a structural risk to project continuity and material availability. Distribution runs through direct contracts with Exploration & Production companies or via comprehensive EPCI agreements with subsea engineering contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pipe Laying Vessel Market is a high-growth disruption, driven by the dual inflection points of the EU Green Deal and renewed deepwater hydrocarbon investment.
For Market Incumbents: Consolidate market position by investing in dual-fuel newbuilds capable of meeting MARPOL Annex VI emission standards, mitigating the threat of regulatory-driven obsolescence. Upgrade aging assets to DNV-ST-N001 specifications to remain competitive for high-specification tenders. Prioritize R&D into integrated ROV and heavy-lift crane systems for complex subsea infrastructure deployment.
For New Entrants and Emerging Players: Lead with specialized capabilities in nascent but high-growth segments like floating offshore wind infrastructure and subsea interconnectors. The offshore wind farm cabling sector, particularly in the North Sea and off the United States coast, presents the most penetrable segment. Develop a go-to-market strategy emphasizing alternative fuel vessels for environmentally conscious clients and project owners.
For Investors and Strategic Acquirers: Long-term, this sits as a growth play because global energy transition targets and deepwater resource development demand extensive subsea infrastructure. Target specialized subsea engineering contractors with diverse, modern fleets and proven EPCI capabilities. The signal to watch is the volume of final investment decisions for floating offshore wind projects or large-scale subsea power grids.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Reel-Lay Vessels | Addresses the growing demand for subsea cable installation in offshore wind farm developments. |
| Investment in Dual-Fuel Engine Technology | Ensures compliance with IMO MARPOL regulations, reducing operational costs and environmental impact. |
| Strategic Partnerships with EPCI Contractors | Secures long-term project pipelines and integrates vessel services into comprehensive subsea solutions. |
| R&D in Advanced ROV Integration | Enhances capabilities for complex subsea infrastructure deployment and intricate intervention tasks. |
| Geographic Diversification into Emerging Deepwater Basins | Captures first-mover advantages in new energy provinces beyond established offshore regions. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings. Engagement included vessel operators, subsea engineers, E&P procurement leads, and offshore wind developers. Secondary validation drew from maritime classification society reports, IMO regulations, national energy agency reports, and company annual disclosures. This approach ensured a robust bottom-up and top-down triangulation of market insights.
Sensitivity analysis informs the forecast framework, accounting for variable market conditions across the analysis window. Segmentation dimensions modeled include vessel type, application, technology, and geographic region. Compound annual growth rates were derived from historical trends and projected investment cycles. Key forecast inputs include global offshore wind capacity targets and final investment decisions for deepwater oil & gas projects.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding energy policy stability and commodity price trajectories. Practitioners should keep alternative scenarios live as regulatory frameworks and global energy demand evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market