
 Marine Cranes Market | 2026-2036
Marine Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Cranes Market Intelligence
A transition from single-source supplier contracts to multi-vendor procurement strategies is shifting how large port operators and marine contractors acquire new equipment. This change favors suppliers with broad, modular portfolios and established global service networks capable of supporting diverse fleet requirements. Palfinger leverages its extensive product range to capture varied customer needs across different vessel types. Meanwhile, MacGregor and Cargotec compete on delivering fully integrated solutions for complex vessel and port handling operations.
A marine crane is a mechanical lifting apparatus specifically engineered for shipboard or offshore installation, operating under severe environmental stress. These devices feature active heave compensation systems and specialized marine-grade coatings to ensure safe functionality under dynamic sea conditions. The knuckle boom crane type leads in versatility for vessel-mounted applications, from cargo handling to subsea work. Hydraulic technology remains the dominant power source, especially for high-capacity lifts required in the offshore platforms application segment.
Product design and market access are governed by strict international and regional standards. Compliance with ISO standards, the European Union's CE marking, and API specifications for offshore equipment dictates manufacturing protocols. These regulations enforce rigorous testing for load-bearing capacity and safety systems. Equipment buyers must now weigh investing in all-electric systems for emissions compliance against the proven performance of next-generation hydraulic cranes.
Market Dynamics
The expansion of offshore renewable energy, driven by regulatory frameworks like the EU Green Deal, is the central force shaping the marine cranes market. This creates a focused demand for high-capacity, technologically advanced lifting equipment for wind turbine installation and maintenance.
Growth Catalysts
- Offshore Wind Development:Government mandates for renewable energy, particularly in North Sea countries, are accelerating offshore wind farm construction, creating a direct demand pipeline for heavy-lift installation cranes.
- Port Modernization:Infrastructure investment programs in Southeast Asian nations like Vietnam and Indonesia are upgrading port facilities, requiring new and more efficient cargo handling cranes to support growing trade volumes.
- Aquaculture Expansion:The growth of large-scale offshore fish farming operations creates a niche demand for versatile knuckle boom cranes for feed barge servicing, net handling, and general maintenance tasks.
Market Restraints
- Input Cost Volatility:Fluctuating prices and supply constraints for marine-grade steel and specialized high-strength alloys create significant cost uncertainty and can compress manufacturer margins.
- Regulatory Compliance Burden:The need to adhere to a complex web of standards, including ISO, API, and CE marking, results in long and expensive design, testing, and certification cycles for new equipment.
- Electrification Limits:Current battery energy density and charging infrastructure limitations hinder the viability of all-electric systems for the highest-capacity offshore cranes, slowing full decarbonization in heavy-lift segments.
Strategic Opportunities
- Predictive Maintenance Services:Integrating AI and sensor data with active heave compensation systems allows for new service models based on predicting component failure and optimizing maintenance schedules.
- US Offshore Wind Market:The nascent offshore wind industry in the United States, supported by federal incentives under the IRA, represents a significant new geographic market for both installation and service operation vessels.
- Autonomous Vessel Integration:Designing specialized cranes for the deployment and recovery of autonomous underwater vehicles and unmanned surface vessels opens a new application frontier in oceanography and defense.
Industry Challenges
- Specialized Skills Gap:A persistent shortage of technicians and engineers who possess combined expertise in advanced hydraulic systems, control software, and data analytics impedes service and innovation.
- Legacy Fleet Retrofitting:Integrating modern, digitally controlled cranes with the older power and structural systems of existing vessels presents significant technical and financial challenges for fleet owners.
- High R&D Investment:The substantial capital expenditure needed to develop and validate next-generation all-electric and low-emission hydraulic systems puts pressure on smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Cranes Market |
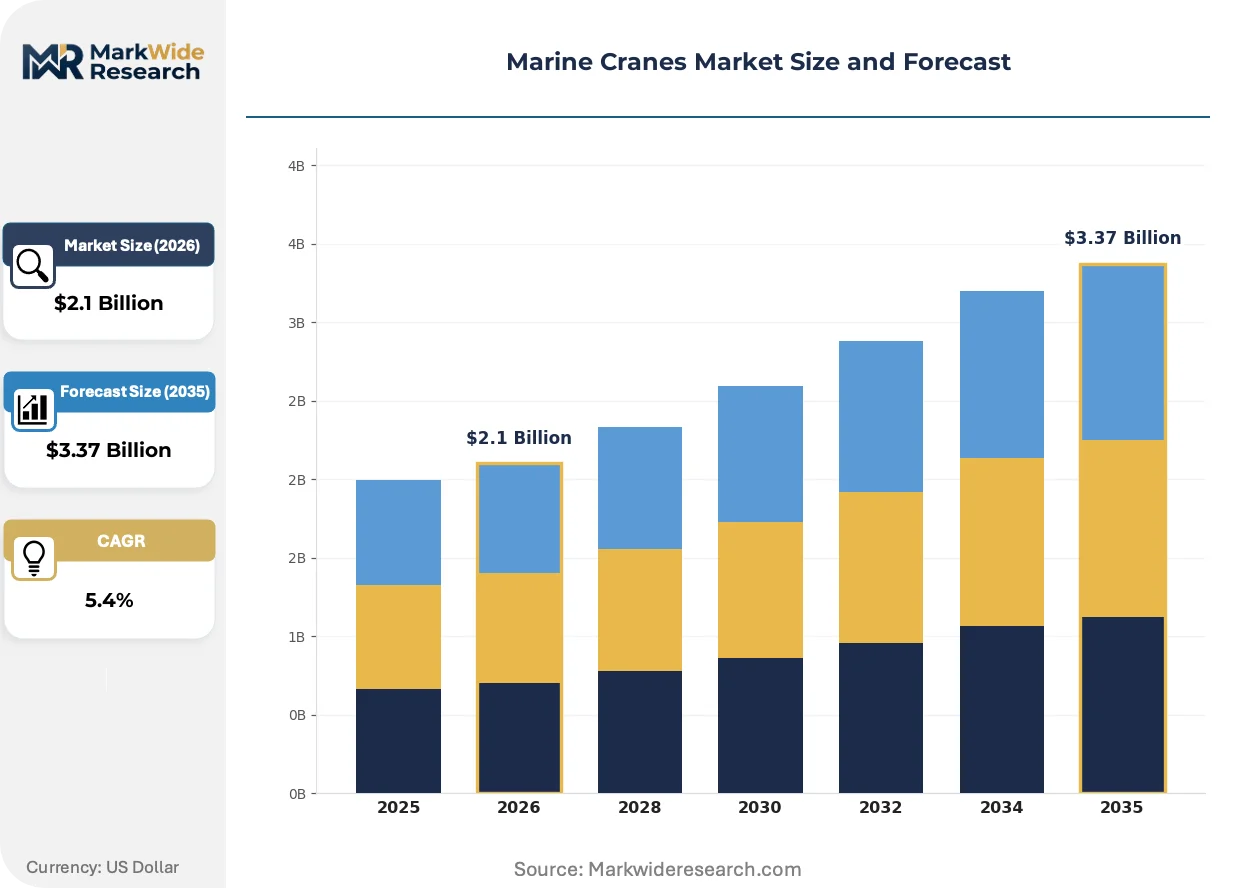
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crane Type: Knuckle Boom, Crawler, Tower, Gantry, Telescopic Technology: Hydraulic, Electric, Pneumatic, Manual, Wireless Control Application: Shipbuilding, Offshore Platforms, Port Handling, Salvage Operations End User: Shipyards, Port Operators, Oil & Gas Explorers, Marine Contractors |
| Companies Covered | KenzFigee Group B.V., DMW Marine Group LLC, Palfinger, Cargotec, Industriaguerra S.A, Hawboldt Industries, Techcrane International LLC, MacGregor, HS. Marine S.R.L, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Cranes Market Strategic Shifts & Innovations
Digitalization and electrification are fundamentally altering crane design philosophies and operational capabilities. This dual-front evolution is pushing the industry toward more intelligent, integrated, and environmentally compliant lifting solutions that address both regulatory mandates and the need for greater operational efficiency at sea.
Advanced control software is becoming a key differentiator. Active Heave Compensation (AHC) technology, which uses sophisticated sensors and actuators to nullify vessel motion, is a primary example. Offshore energy and subsea construction firms are adopting AHC to expand safe operational windows in challenging sea conditions. This technology is unifying crane mechanics, vessel dynamics, and mission planning into a single, intelligent system for safer, more precise lifts.
Stringent emissions regulations are forcing a technological pivot, particularly in port environments. Rules governing port-level air quality and broader frameworks like the EU's Carbon Border Adjustment Mechanism (CBAM) create direct financial incentives for decarbonization. The cargo handling segment is most affected, spurring investment in all-electric and hybrid-electric cranes to ensure continued access to major global trade hubs and avoid potential carbon-related tariffs.
Fleet operators are adopting new procurement models that prioritize asset lifecycle value over initial purchase price. This involves a move away from single-unit acquisitions toward comprehensive service agreements that bundle equipment with long-term maintenance, digital monitoring, and operator training. This trend is most visible in the North Sea offshore wind sector, where maximizing vessel and equipment uptime is directly tied to project profitability.
Marine Cranes Market Segmentation
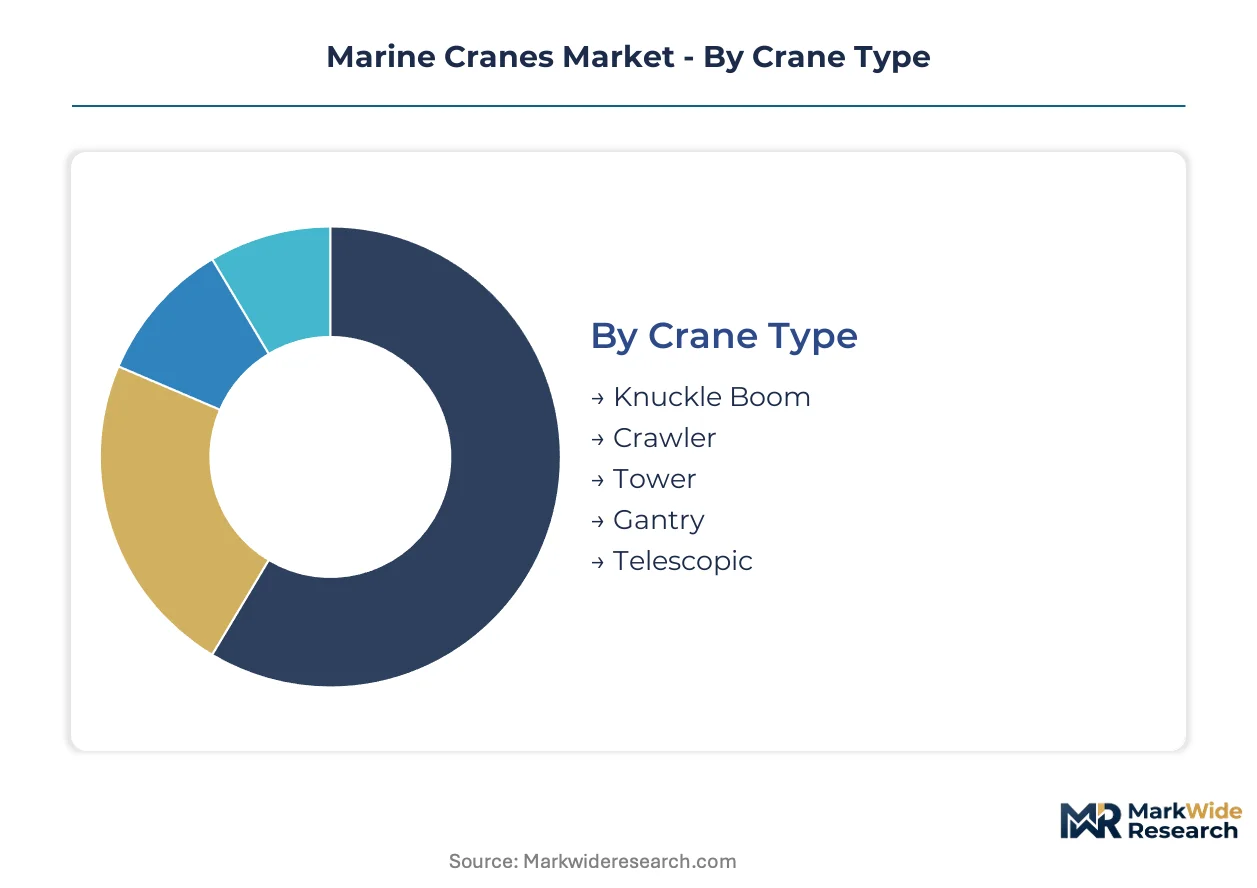
The marine cranes market segmentation provides a granular view of demand patterns and technological preferences across diverse operational environments. Understanding these categories helps stakeholders align product development and service offerings with evolving industry requirements. This detailed breakdown reveals where investment is concentrating and which solutions are gaining traction.
Crane Type:
The long operational lifecycle of marine crane assets drives procurement toward models offering longevity and adaptability. Operators evaluate new crane types based on their ability to replace aging fleets with efficient solutions. This upgrade cycle shapes demand.
- Knuckle Boom:These articulated cranes offer exceptional reach and precise load placement for complex subsea operations. Demand concentrates in offshore wind maintenance and aquaculture for versatile handling.
- Crawler:Crawler cranes provide high lifting capacities and mobility on land, used for port construction and wind component pre-assembly.
- Tower:Tower cranes offer significant height and reach, employed in shipyards for vessel construction and port expansion.
- Gantry:Gantry cranes operate on rails, offering high-volume, efficient cargo handling across berths and container yards. Adoption accelerates in Southeast Asian trade hubs due to modernization.
- Telescopic:Hydraulic boom sections provide compact storage and quick deployment, valued for general cargo handling.
Knuckle Boom cranes sit at the top of the volume ranking, with Gantry cranes climbing the fastest.
Technology:
Crane technology choice links to its intended application, with operational demands dictating the most suitable power source. Marine environments impose distinct performance requirements. This selection shapes technological investment.
- Hydraulic:Hydraulic systems remain the dominant power source, delivering high power density and precise control for heavy-lift operations. Demand is strong in offshore platforms for high-capacity lifts.
- Electric:Electric cranes utilize motors and drives, offering lower emissions and reduced noise, attractive for port environments. Investment accelerates in global trade hubs due to air quality regulations.
- Pneumatic:Pneumatic systems, powered by compressed air, are used for lighter lifting tasks or auxiliary explosion-proof functions.
- Manual:Manual cranes, relying on human power, serve niche applications requiring minimal lifting capacity.
- Wireless Control:This technology integrates remote operation, enhancing safety and flexibility by allowing operators to manage crane movements from optimal vantage points.
The market witnesses a significant shift towards electric and hybrid solutions, driven by global decarbonization mandates and port emission targets.
Application:
End-user profiles, from large port operators to specialized marine contractors, influence crane applications in demand. Each customer segment has unique operational priorities, safety, and budget considerations. This customer-centric
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea region's offshore wind development drives significant demand for marine cranes. Government mandates across Europe and North America accelerate construction of wind farms. This expansion creates a focused requirement for high-capacity lifting equipment.
Germany
Demand for heavy-lift cranes in Germany stems from extensive offshore wind farm construction. The EU Green Deal provides regulatory tailwinds for renewable energy projects. Wilhelmshaven and Emden ports are key hubs for wind turbine component logistics and pre-assembly.
United Kingdom
Offshore wind development in the UK generates substantial orders for advanced marine cranes. The UK government's commitment to net-zero targets supports extensive offshore energy investments. Hull and Teesside serve as vital operational bases for North Sea wind farm installation and maintenance.
Netherlands
The Netherlands experiences high demand for specialized marine cranes due to its prominent role in offshore energy. Dutch renewable energy policies encourage significant investment in wind turbine installation vessels. Rotterdam Port is a central logistics and service hub for large-scale offshore projects.
United States
The nascent US offshore wind industry creates a new demand pipeline for heavy-lift cranes. The Inflation Reduction Act (IRA) offers federal incentives for renewable energy infrastructure. The Northeast coast, particularly around New York and Massachusetts, is developing port facilities for turbine staging.
Vietnam
Port modernization efforts in Vietnam require new gantry and cargo handling cranes. Infrastructure investment programs support the upgrade of major trade facilities. Ho Chi Minh City and Hai Phong ports are expanding to accommodate growing trade volumes and larger vessels.
Marine Cranes Market Key Industry Players
Global majors compete with regional champions across product breadth and established global service network capabilities. The market structure reveals a tiered landscape, with large, diversified equipment manufacturers alongside specialized niche providers. Strategic archetypes include integrated solution providers, specialized subsea equipment manufacturers, and port infrastructure specialists. Companies pursue competitive advantage through strategic partnerships for technology co-development and continuous portfolio diversification, aiming to meet varied customer requirements across diverse operational environments.
Within the segment of integrated solutions providers, Cargotec and MacGregor exemplify firms offering comprehensive vessel and port handling operations. These entities focus on delivering end-to-end systems for complex marine environments, particularly in cargo and offshore applications. Palfinger represents a firm leveraging an extensive product range to capture varied customer needs across different vessel types, including versatile knuckle boom cranes. These companies anchor market offerings through their broad product portfolios and established global service networks, addressing diverse fleet requirements and complex operational demands.
| Leading Market Players |
|---|
| KenzFigee Group B.V. |
| DMW Marine Group LLC |
| Palfinger |
| Cargotec |
| Industriaguerra S.A |
| Hawboldt Industries |
| Techcrane International LLC |
| MacGregor |
| HS. Marine S.R.L |
Cost & Logistics Intelligence
The clear performance gap between high-capacity offshore wind installation cranes and standard port cargo handling equipment manifests in distinct pricing models and specialized supply chain configurations. This divergence reflects the varying engineering complexity and regulatory compliance required for each application.
Pricing Analysis
Input cost pass-through significantly influences pricing for specialized marine cranes, especially for marine-grade steel and high-strength alloys. Project-based pricing dominates for large offshore wind installation cranes, reflecting extensive customization and engineering. Price differentiation stems from the crane's load capacity and compliance with stringent certifications like API and CE marking. Pricing softness runs through general cargo handling segments due to increased competition and port modernization budgets. Offshore wind developers demonstrate lower price sensitivity for advanced heavy-lift equipment, prioritizing uptime and operational efficiency.
Supply Chain Analysis
Dual-sourcing requirements from major marine contractors now mandate multi-supplier qualification for critical components, mitigating single-source risks. Geographic supply concentration for specialized hydraulic systems and high-strength steel centers around Germany, the Netherlands, and East Asian producers. Raw material dependencies include marine-grade steel, specialized alloys, and advanced hydraulic components. Commodity price volatility for these inputs represents a structural supply chain risk. Downstream distribution typically runs through direct sales channels and project-specific logistics networks due for high-value offshore equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
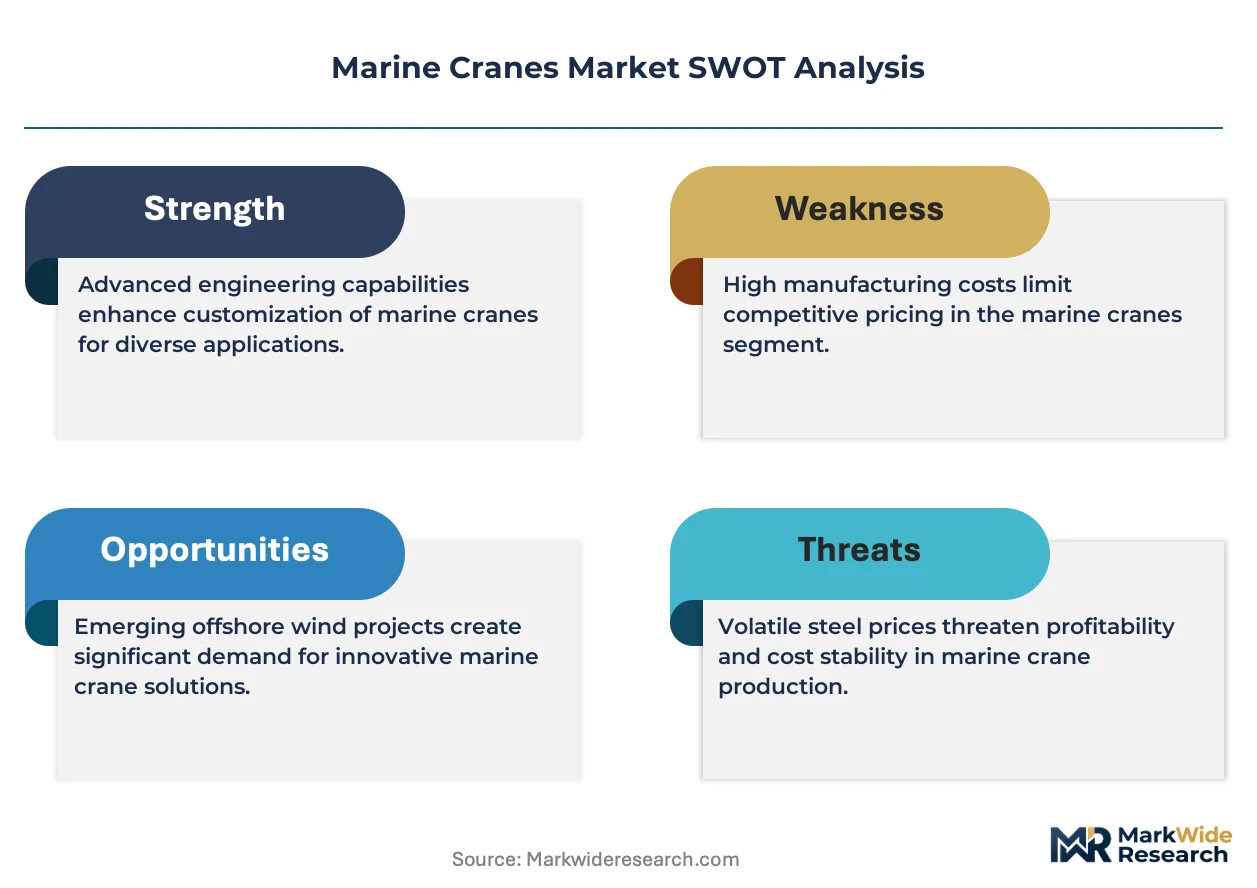
This market presents a compelling margin-expansion story, driven by the premium-tier shift toward high-capacity, technologically advanced cranes for offshore renewable energy projects.
For Market Incumbents:Deepen global service networks to leverage existing client relationships, particularly in the burgeoning US offshore wind market. Diversify product portfolios to include modular, adaptable solutions that meet varied vessel requirements. Invest in advanced control software R&D to maintain a competitive edge against emerging digital threats. Specialized skills gap for integrated systems remains a critical challenge.
For New Entrants and Emerging Players:The Inflation Reduction Act (IRA) in the United States opens a window for specialized crane manufacturers focused on heavy-lift installation and service operation vessels. Target niche applications like aquaculture or autonomous vessel deployment with versatile knuckle boom cranes. A go-to-market angle emphasizing modularity and digital integration for predictive maintenance services can capture early adoption.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized technological capabilities, particularly in electrification and advanced control systems, become critical for market access. Long-term viability rests on sustained government mandates for renewable energy and ongoing port modernization. Acquisition targets should include firms with proven expertise in electrification, AI-driven predictive maintenance, or strong regional service footprints. Growth in US offshore wind project awards is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop all-electric high-capacity cranes | Reduces operational emissions, meeting stringent port and offshore environmental regulations. |
| Expand global service and support networks | Ensures maximum equipment uptime for operators, crucial for project profitability. |
| Integrate AI for predictive maintenance | Optimizes maintenance schedules and minimizes costly unplanned vessel downtime. |
| Form strategic partnerships for software development | Enhances crane control systems and enables advanced operational capabilities. |
| Invest in specialized training programs | Addresses the critical skills gap for advanced hydraulic and digital systems. |
Research Approach
Bottom-up offshore wind capacity modeling reconciled against top-down marine equipment supply-side tracking forms the analytical core for this market study. Primary research involved in-depth interviews with marine contractors, port operators, offshore wind developers, and crane manufacturers' R&D leads. Secondary validation drew from industry association reports, maritime trade publications, government energy mandates like the EU Green Deal, and company annual reports, ensuring data triangulation.
An input-output matrix frames the forecast framework, projecting volume and value across the analysis window. Segmentation dimensions modeled include crane type, technology, application, and regional demand centers such as the North Sea and Southeast Asia. Compound annual growth rates derive from historical growth patterns, demand drivers, and the impact of regulatory frameworks. Key forecast inputs include projected offshore wind capacity additions and global port throughput projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme input cost volatility or significant geopolitical shifts impacting global trade. Forecasts reflect assumptions regarding technological adoption rates and the pace of regulatory enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market