
 Cable Laying Vessel Market | 2026-2036
Cable Laying Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Laying Vessel Market Intelligence
The direct chartering channel for specialized cable laying assets is narrowing as large project developers and cable manufacturers seek dedicated, long-term vessel control. This shift favors vertically integrated companies that own both manufacturing and installation assets. Prysmian Group leverages its extensive fleet to secure turnkey project contracts for inter-array and export cables. Nexans differentiates through its focus on high-voltage direct current (HVDC) cable installation capabilities. Meanwhile, Jan De Nul operates a versatile fleet that serves both the energy and telecommunications sectors.
A cable laying vessel is a purpose-built ship designed for the subsea installation, maintenance, and repair of power and telecommunication cables. These vessels are equipped with specialized machinery, including large-capacity cable carousels or drums, tensioners, and advanced Dynamic Positioning (DP) systems that ensure precise station-keeping during sensitive operations. The primary purpose is to connect offshore energy assets to onshore grids and to deploy the data infrastructure underpinning global communications. Demand for Dynamic Positioning vessels is escalating for Deep Water and Ultra-Deep Water projects. The Power Cable segment is expanding rapidly due to offshore wind farm construction.
The regulatory environment is shaped by both maritime safety and environmental protection mandates. The International Maritime Organization (IMO) sets baseline standards for vessel construction and operation under SOLAS. In Europe, directives related to the EU Green Deal influence project permitting for offshore renewable energy, indirectly driving vessel demand. In the United States, operations must comply with Jones Act provisions and OSHA safety regulations. Vessel operators must navigate a complex matrix of international and national rules to secure contracts and maintain compliance.
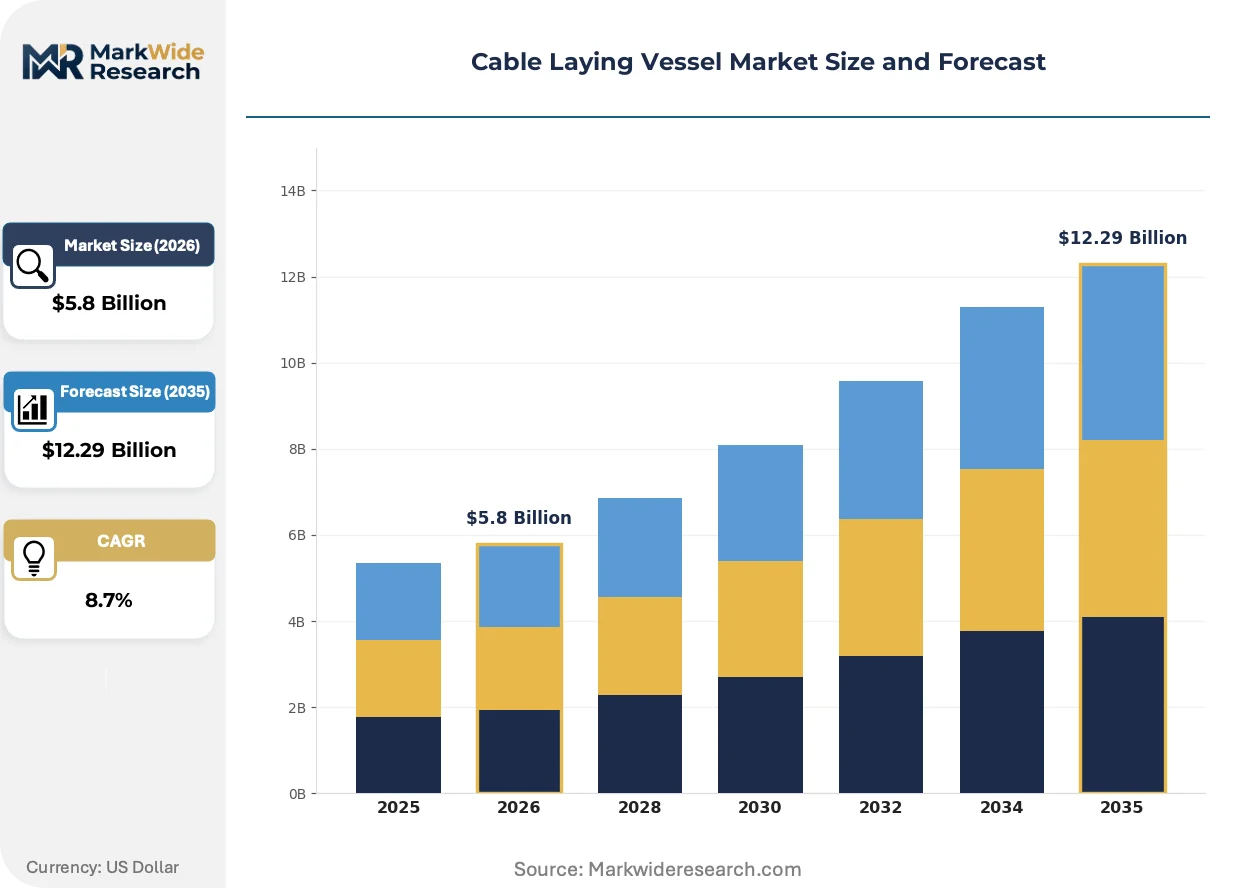
Market Dynamics
The expansion of offshore energy infrastructure, driven by national decarbonization mandates and the build-out of large-scale wind farms, represents the central force shaping the cable laying vessel market. This creates sustained, project-based demand for high-specification installation and maintenance assets.
Growth Catalysts
- EU Green Deal:This regulatory framework mandates significant expansion of renewable energy capacity, directly stimulating demand for vessels to install inter-array and export cables for new offshore wind farms across Europe, particularly in the North Sea.
- Intercontinental Data Routes:The construction of new subsea fiber-optic cables to support global data traffic, cloud computing, and 5G networks requires specialized telecommunication cable laying vessels for trans-oceanic deployments.
- China's Decarbonization Goals:China's dual carbon objectives are accelerating the development of massive offshore wind projects, concentrating vessel demand and creating a major regional market for both domestic and international fleet operators.
Market Restraints
- High Newbuild Costs:The substantial capital expenditure and long lead times required to construct advanced vessels, particularly those with DP3 systems, limit the pace of fleet expansion and create barriers to entry for new operators.
- Specialized Shipyard Scarcity:A limited number of shipyards worldwide possess the technical expertise and facilities to build high-specification cable laying vessels, leading to production bottlenecks and constrained global supply.
- Operational Complexity:Deep-water cable installation is inherently complex and highly sensitive to adverse weather conditions, which can cause significant project delays, operational risks, and budget overruns for contractors.
Strategic Opportunities
- Floating and Tidal Energy:The emerging floating offshore wind and tidal energy sectors represent a new frontier, requiring innovative installation methodologies and vessel designs adapted for dynamic mooring and foundation systems.
- New Geographical Markets:Nascent offshore wind markets in the United States and Taiwan are creating significant deployment opportunities as these countries build out their renewable energy infrastructure, requiring Jones Act-compliant solutions in the US.
- AUV Integration:The convergence of cable laying operations with autonomous underwater vehicles (AUVs) for seabed surveys and post-lay inspections offers a path to greater efficiency, reduced costs, and improved project timelines.
Industry Challenges
- Specialized Crew Shortage:A persistent shortage of qualified maritime professionals, especially those with advanced Dynamic Positioning (DP) certifications and experience in handling high-voltage power cables, constrains operational capacity.
- Complex Regulatory Navigation:Operators must manage a fragmented landscape of international and national rules, including cabotage laws like the US Jones Act, which complicates fleet deployment and crew management on a global basis.
- Asset Modernization Demands:The need to upgrade existing vessels with larger carousels, more powerful tensioners, and advanced burial tools to handle next-generation cables requires significant and continuous capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Laying Vessel Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Dynamic Positioning, Non-Dynamic Positioning, Hybrid Positioning, Plough Mount Operation Depth: Shallow Water, Intermediate Water, Deep Water, Ultra-Deep Water Cable Type Handled: Power Cable, Telecommunication Cable, Submarine Cable, Fiber Optic Cable End Use Industry: Subsea Energy Firms, Offshore Telecom Providers, Underwater Construction, Maritime Infrastructure |
| Companies Covered | Sumitomo Electric Industries, NKT, Jan De Nul, Hengtong, Southwire, Prysmian Group, LS Cable & System, PRV Engineering, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Laying Vessel Market Strategic Shifts & Innovations
Vessel design and operational strategy are evolving in response to the technical demands of next-generation energy and data projects. The market is defined by a push for higher-capacity assets and long-term contractual relationships that reduce project execution risk.
High-capacity cable carousels and burial systems are becoming standard requirements for newbuild vessels. Offshore wind developers and HVDC transmission system operators are specifying these capabilities to support larger, heavier export cables for multi-gigawatt projects. This demand for assets capable of handling the next generation of power cables is rendering obsolete older vessels originally designed for lighter telecommunication cables.
Stricter environmental regulations from the International Maritime Organization (IMO) are influencing vessel design and propulsion technology. Mandates such as the Energy Efficiency Existing Ship Index (EEXI) are forcing owners to invest in cleaner-burning fuels like LNG or methanol and explore battery-hybrid systems. The entire global fleet is impacted, but owners of older, less efficient vessels face the greatest pressure to retrofit or risk becoming uncompetitive for contracts in environmentally sensitive regions.
Chartering models are evolving from short-term, spot-market contracts to long-term framework agreements and dedicated vessel assignments. This shift is driven by large project developers seeking to secure installation capacity and de-risk complex construction schedules. This pattern disrupts the traditional charter market, favoring operators with modern, versatile fleets capable of fulfilling multi-year commitments, a trend most visible in Europe's offshore wind sector.
Cable Laying Vessel Market Segmentation
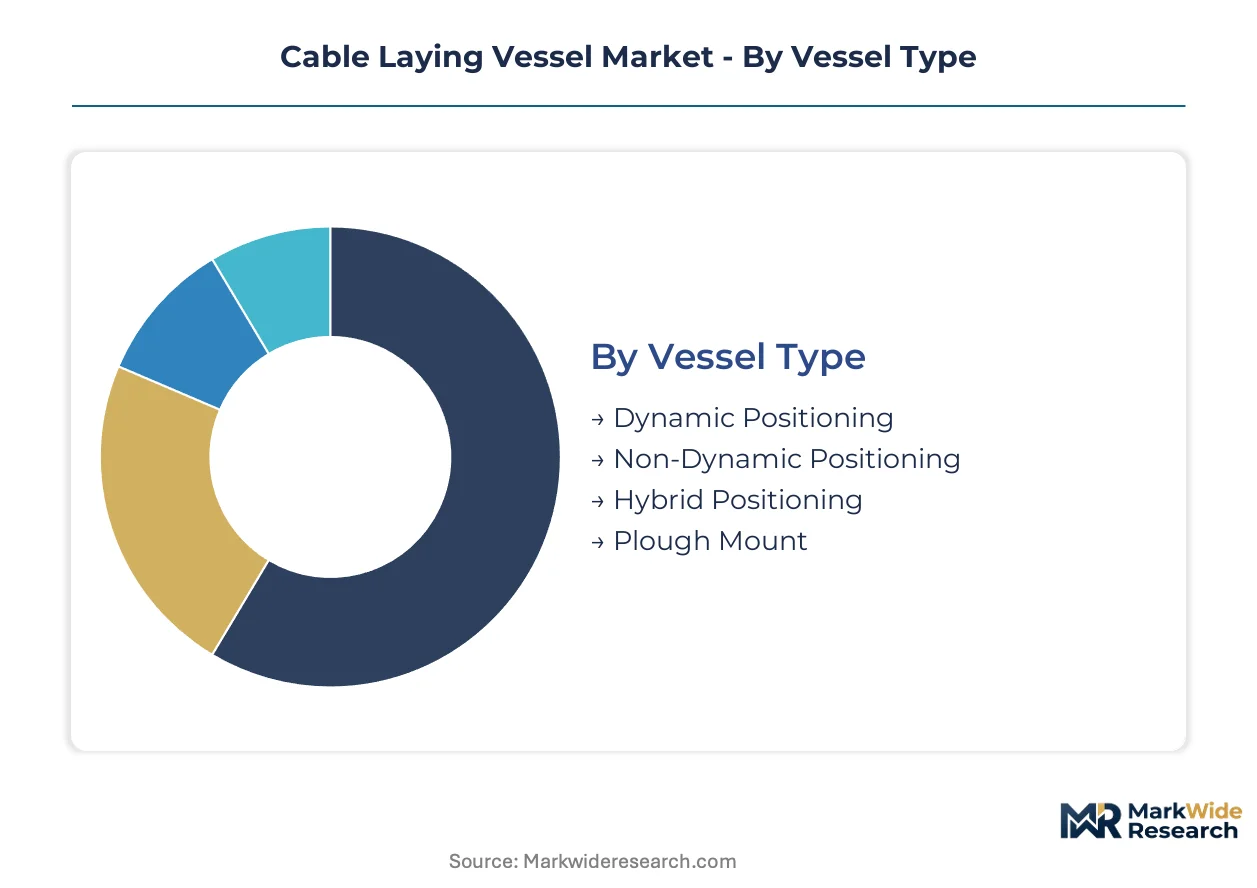
Market segmentation for cable laying vessels reveals the specialized capabilities required to meet distinct project demands across various subsea environments. This breakdown helps identify areas of concentrated investment and technological advancement within the industry.
Vessel Type:
The vessel type segment reflects a spectrum of operational maturity, from established basic designs to highly advanced, integrated systems.
- Dynamic Positioning:These vessels maintain precise position and heading using computer-controlled thrusters and propellers, essential for deep-water and ultra-deep water cable installations. Demand for DP vessels is escalating for complex offshore wind farm connections in the North Sea.
- Hybrid Positioning:Combining DP systems with conventional mooring, these vessels offer flexibility and efficiency for a range of operational depths and conditions. This blend of technologies supports diverse projects, including both power and telecommunication cable deployments.
- Non-Dynamic Positioning:These vessels rely on anchors and tugs for station-keeping, suitable for shallower waters and less complex cable laying tasks.
- Plough Mount:Specialized equipment attached to vessels, primarily used for burying cables on the seabed to protect them from external damage.
Dynamic Positioning vessels handle the majority of complex project throughput; Hybrid Positioning is the fastest mover on share.
Operation Depth:
Operational depth categorizes vessels by their suitability for specific subsea environments, directly impacting cable installation methodologies and equipment needs.
- Deep Water:These operations occur at depths typically ranging from 300 to 1,500 meters, requiring robust DP systems and specialized remotely operated vehicles for precise cable placement. Offshore energy projects often necessitate deep-water capabilities.
- Ultra-Deep Water:Extending beyond 1,500 meters, these challenging operations demand the most advanced vessel technology, including high-tension cable handling systems and sophisticated navigation. Trans-oceanic telecommunication cables frequently require ultra-deep water deployment.
- Shallow Water:Operations in depths up to 300 meters, often involving coastal connections and inter-array cables for nearshore wind farms.
- Intermediate Water:These depths, typically between 300 and 1,000 meters, represent a transition zone requiring adaptable vessel capabilities for varied projects.
Deep Water operations drive significant vessel demand; Ultra-Deep Water installations exhibit the steepest expansion trajectory.
Cable Type Handled:
The cable type handled defines the primary function of the installed infrastructure, with significant implications for vessel design and equipment specifications.
- Power Cable:These heavy, high-voltage cables connect offshore energy assets like wind farms to onshore grids, demanding vessels with large carousels and powerful tensioners. Offshore wind farm construction in Europe is a primary demand source.
- Telecommunication Cable:Lighter and more flexible, these cables form the backbone of global data networks, requiring precise laying and burial capabilities. Intercontinental data routes are driving demand for these specialized installations.
- Submarine Cable:This broad category encompasses any cable designed for underwater installation, often referring to both power and telecommunication types.
- Fiber Optic Cable:A specific type of telecommunication cable, characterized by its high data transmission capacity and delicate installation requirements.
Power Cable installations dominate new project awards; Telecommunication Cable projects maintain consistent global demand.
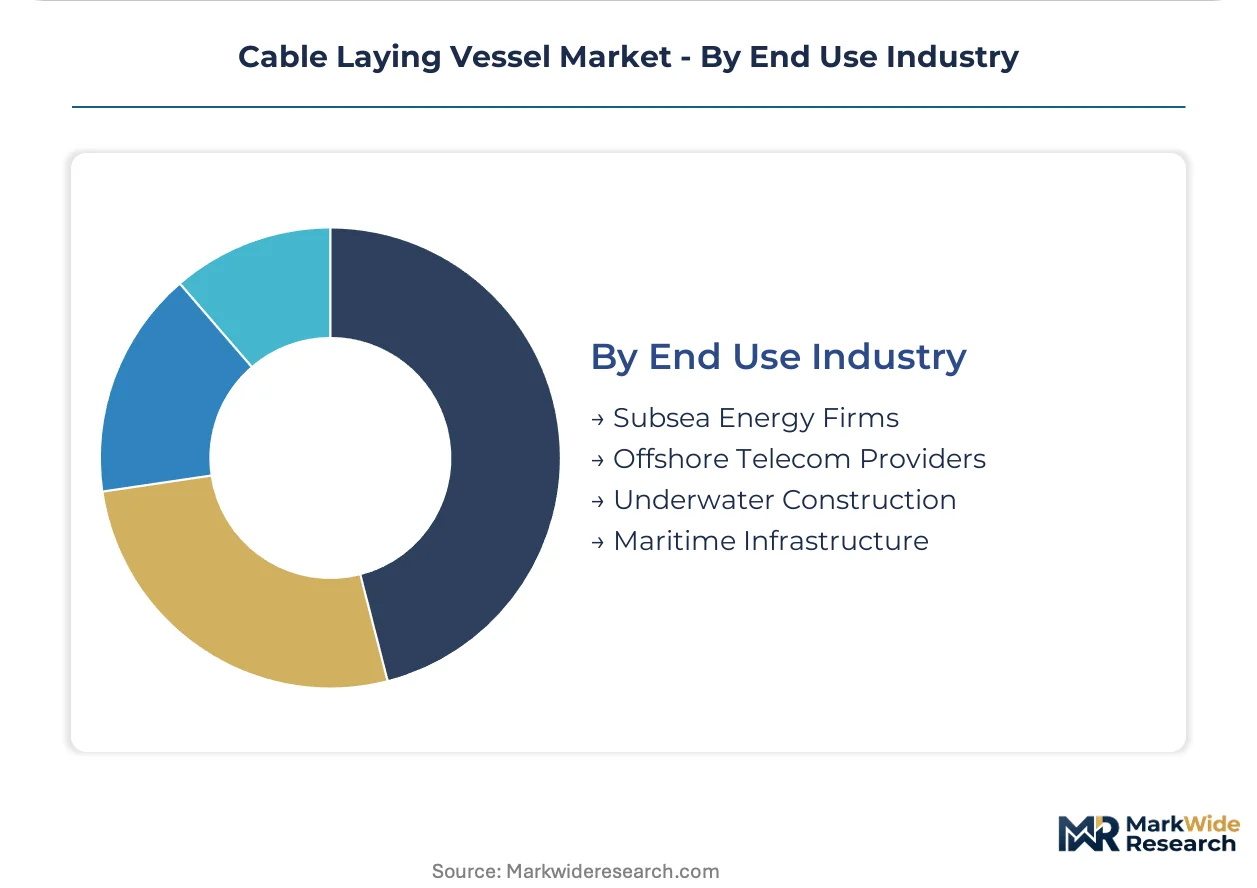
End Use Industry:
The end-use industry segment illustrates the diverse client base for cable laying services, each with distinct project requirements and regulatory landscapes.
- Subsea Energy Firms:These companies develop and operate offshore wind farms and oil & gas infrastructure, requiring vessels for inter-array and export power cable installations. National decarbonization mandates drive their investment in new projects.
- Offshore Telecom Providers:Responsible for deploying and maintaining the global fiber-optic network, these firms contract vessels for trans-oceanic and regional data cable installations. Cloud computing and 5G networks fuel their expansion.
- Underwater Construction:This segment includes projects like pipeline installations, foundation work, and other subsea engineering activities that may involve cable integration.
- Maritime Infrastructure:Encompasses a range of projects from port development to coastal protection, sometimes requiring specialized cable laying for power or communication systems.
Subsea Energy Firms represent the largest segment by project value; Offshore Telecom Providers focus on extensive network deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expansion of subsea grid interconnects and offshore energy infrastructure defines regional demand patterns for cable laying vessels. National decarbonization targets and growing data traffic are concentrating investment in specific coastal zones. This creates distinct operational landscapes across key maritime regions.
United Kingdom
Offshore wind farm development, requiring extensive inter-array and export cables, drives significant vessel demand in the United Kingdom. The UK's national decarbonization targets, alongside broader EU Green Deal influences, mandate substantial renewable energy infrastructure build-out. The North Sea and Scottish waters are focal points for large-scale wind projects, attracting specialized installation fleets.
China
China's massive offshore wind projects and the expansion of intercontinental data routes represent substantial demand for cable laying vessels. The country's dual carbon goals and national renewable energy mandates accelerate investment in these complex installations. The Yangtze River Delta and Pearl River Delta regions are key areas for major project build-outs and associated marine operations.
United States
Nascent offshore wind markets and deep-water project requirements are creating new opportunities for cable laying vessels in the United States. Jones Act provisions significantly influence fleet deployment and operational strategies for domestic projects. The Northeast US coast, particularly the New York Bight, is emerging as a critical region for new offshore wind farm development.
Germany
German North Sea offshore wind development and European grid integration projects consistently generate demand for high-specification cable laying vessels. Directives from the EU Green Deal and national energy transition laws support continued investment in subsea power infrastructure. The German Bight and Baltic Sea serve as active zones for extensive wind farm installations and grid connections.
Taiwan
Taiwan's emerging offshore wind sector and its role in regional data connectivity are spurring demand for specialized cable laying vessels. The nation's renewable energy targets and robust permitting frameworks facilitate new offshore project development. The western coast of Taiwan is a primary area for new wind farm construction, attracting international vessel operators.
Cable Laying Vessel Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few large, vertically integrated players and a broader base of specialized vessel operators. Strategic archetypes include integrated cable manufacturers leveraging their own installation assets and dedicated pure-play installation contractors focusing on specific operational niches. Dominant competitive moves involve significant capacity expansion through newbuild programs for high-specification vessels. Furthermore, strategic partnerships and long-term framework agreements are crucial for securing complex project contracts.
Specialists in comprehensive turnkey solutions include Prysmian Group, an Italian-based company, which leverages its extensive fleet for project contracts. Nexans, a French-based entity, differentiates through its focus on high-voltage direct current (HVDC) cable installation capabilities. Jan De Nul, a Belgian-based group, operates a versatile fleet that serves both the energy and telecommunications sectors, exemplifying a diversified operational archetype. These companies occupy positions that reflect significant capital investment in specialized assets and long-term project engagement.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| NKT |
| Jan De Nul |
| Hengtong |
| Southwire |
| Prysmian Group |
| LS Cable & System |
| PRV Engineering |
| Nexans |
| Others |
Cost & Logistics Intelligence
The scarcity of specialized shipyards and advanced component manufacturers directly influences the build costs and, consequently, the long-term charter rates and project margins for installation contractors. This upstream concentration dictates the pricing power downstream within the cable laying vessel market.
Pricing Analysis
Project-based, long-term contract pricing dominates the cable laying vessel market, often incorporating volume-based incentives for multi-year commitments. Price differentiation stems from vessel capabilities, such as DP3 systems or large carousel capacities, and the specific regulatory compliance required like Jones Act provisions. Pricing pressure stems from high newbuild costs and the need to secure long-term utilization for expensive assets. Offshore wind developers, seeking to de-risk complex construction schedules, exhibit lower price sensitivity compared to smaller, regional telecom providers.
Supply Chain Analysis
Export controls on advanced navigation and dynamic positioning systems, particularly from European and North American manufacturers, influence global vessel construction. Supply for high-specification cable laying vessels concentrates in a limited number of specialized shipyards in Europe, including Norway and the Netherlands, and increasingly, China. Key raw material dependencies include high-grade steel for hulls and specialized electronics for DP systems. Logistical chokepoints, such as port capacity for large vessel outfitting, represent a structural risk. Distribution of newbuild vessels runs directly from shipyards to large fleet owners or project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable laying vessel market is in an early-cycle expansion phase, driven by the accelerating build-out of global offshore wind farms. National decarbonization mandates provide a strong tailwind for continued investment and project development.
For Market Incumbents:
Harden long-term charter agreements with major offshore wind developers to secure asset utilization against emerging competition. Invest strategically in larger carousels and HVDC capabilities to counter asset modernization demands from next-generation cable specifications. Pursue targeted R&D into autonomous underwater vehicle (AUV) integration to reduce operational complexity and improve project timelines. This strengthens competitive positioning against new entrants offering specialized niche solutions.
For New Entrants and Emerging Players:
Pursue niche opportunities in emerging geographical markets like the United States, focusing on Jones Act-compliant solutions. Target the floating offshore wind sector, which requires innovative installation methodologies and vessel designs adapted for dynamic mooring systems. Develop specialized vessel designs for intermediate water depths, a segment requiring adaptable capabilities for varied projects. A go-to-market angle could involve offering integrated survey and installation packages for smaller, regional developers.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with specialized vessel operators lacking scale for next-generation projects. The market offers long-term viability, driven by sustained global energy transition initiatives over the next decade. Acquisition targets include mid-sized operators with modern, versatile fleets and strong regional operational footprints. A signal to watch is the consistent pipeline of multi-gigawatt offshore wind projects requiring dedicated installation capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adding newbuilds with larger carousels and DP3 systems addresses demand for heavier, longer cables. |
| Technology Integration | Integrating AUVs for seabed surveys and post-lay inspections enhances operational efficiency. |
| Long-term Charter Agreements | Securing multi-year contracts with major offshore wind developers de-risks asset utilization. |
| Geographic Market Entry | Establishing Jones Act-compliant operations in the United States unlocks a growing offshore wind market. |
| Fuel Transition Investment | Upgrading existing fleets to cleaner-burning fuels like LNG or methanol ensures regulatory compliance and competitiveness. |
Research Approach
A spread of perspectives from offshore wind project developers, vessel operators, cable manufacturers, and maritime logistics specialists converged on the working assumptions for the cable laying vessel market. Primary interviews with these industry stakeholders were combined with secondary validation from institutional reports and maritime trade publications. Data from IMO vessel databases, national renewable energy agency reports, and subsea cable project registries provided further context. This approach ensured bottom-up and top-down triangulation of market estimates.
The demand-supply balance for cable laying vessels was assessed through a comprehensive analytical framework across the projection horizon. This framework modeled market segments by vessel type, operation depth, cable type handled, and end-use industry. CAGRs were derived from historical growth trends, projected project pipelines, and anticipated technological advancements. Key forecast inputs included planned offshore wind capacity additions and subsea data cable deployment schedules.
Sensitivities concentrate around shifts in global energy policy and the pace of offshore wind farm permitting. Forecasts reflect assumptions regarding project timelines and vessel availability. Material shifts in regulatory frameworks or capital expenditure cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Bilge Pump Market