
 Mooring Bollards Market | 2026-2036
Mooring Bollards Market Size, Share, and Industry Trends Forecast 2026-2036
Mooring Bollards Market Insights
Preventive maintenance contracts and condition-monitoring subscriptions is decoupling hardware sales from pure capital expenditure cycles in marine fendering and mooring systems. Trelleborg leverages its polymer expertise to anchor long-term service agreements alongside bollard installations. Fendercare Marine competes through integrated lifecycle packages that sustain recurring revenue from port operators. ESC Marine Systems specializes in high-load double-bitt configurations for ultra-large container vessels, positioning its engineering capabilities at the premium tier of the market.
Mooring bollards are cast or forged marine fixtures, typically manufactured from ductile iron or carbon steel with specified SWL ratings, designed to secure vessels via mooring lines against wind, current, and tidal forces. Casted steel and ductile iron variants dominate commercial port installations due to their fatigue resistance under cyclic loading, while stainless steel and aluminium configurations serve marinas and recreational piers where corrosion aesthetics and lower structural loads govern selection. Application demand fragments across commercial ports absorbing the heaviest tonnage requirements, offshore platforms demanding specialized high-tension designs, and shipyards where temporary mooring flexibility takes priority over permanent berth fixtures.
ISO 3913 mooring equipment standards, PIANC guidelines for fendering and mooring systems, and classification society rules from DNV and Bureau Veritas collectively shape product certification requirements and market access conditions for bollard manufacturers. Port authorities in Rotterdam, Singapore, and Long Beach enforce these frameworks through procurement specifications that disqualify non-certified suppliers from tender participation. Stakeholders must monitor how decarbonization mandates at major harbors will rewrite load specifications as shore power infrastructure and alternative-fuel vessel designs alter vessel mooring profiles.
Market Dynamics
The International Maritime Organization's revised mooring safety guidelines are forcing wholesale equipment upgrades at aging port facilities, converting a steady replacement cycle into accelerated capital deployment across commercial harbors and offshore terminals.
Growth Catalysts
- Deep-water port expansion:Vietnam and Indonesia are prioritizing berth capacity for ultra-large container vessels along strategic shipping lanes, driving procurement of high-load bollard configurations.
- ISO 3913 certification mandates:Port authorities in Rotterdam, Singapore, and Long Beach now disqualify non-certified suppliers from tender participation, filtering demand toward compliant manufacturers.
- Shore power infrastructure rollout:Decarbonization mandates at major harbors are rewriting vessel mooring profiles as alternative-fuel designs alter load specifications and bollard placement requirements.
Market Restraints
- Scrap steel price volatility:Ductile iron and carbon steel input costs fluctuate with commodity cycles, compressing margin predictability for foundry-dependent producers.
- Foundry capacity concentration:Specialized marine casting capabilities cluster in select coastal manufacturing zones, creating supply bottlenecks during demand surges.
- Fatigue testing protocols:PIANC guidelines and classification society rules from DNV and Bureau Veritas impose extended certification timelines that delay revenue recognition.
Strategic Opportunities
- Condition-monitoring subscriptions:Preventive maintenance contracts decouple hardware sales from pure capex cycles, enabling recurring revenue streams from port operators.
- Marina aesthetic specifications:Stainless steel and aluminium configurations for recreational piers command premium positioning where corrosion resistance and visual standards govern selection.
- EU Green Deal port modernization:European decarbonization incentives accelerate berth electrification projects that require redesigned mooring systems for hybrid vessel fleets.
Industry Challenges
- Polymer engineering talent scarcity:Advanced composite bollard development requires specialized material science expertise that competes with broader industrial applications.
- Legacy berth retrofit complexity:Aging concrete infrastructure demands custom foundation solutions that extend project timelines and escalate installation costs.
- Dual certification burden:Manufacturers must simultaneously satisfy ISO 3913, PIANC, and multiple classification society rules to access priority procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mooring Bollards Market |
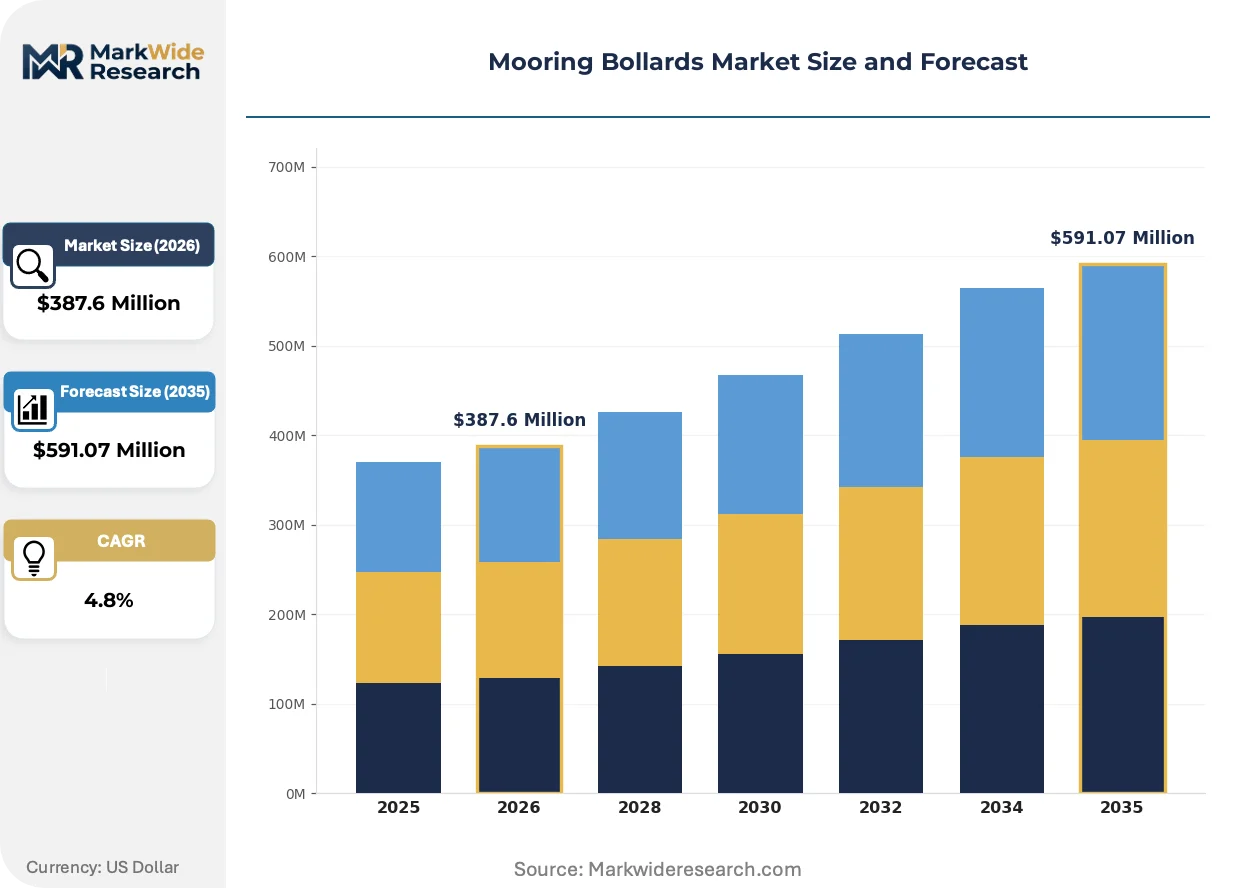
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bitt, Double Bitt, Cylindrical, Double Post, Quoin, Capstan Material: Casted Steel, Carbon Steel, Stainless Steel, Ductile Iron, Aluminium, Bronze Application: Commercial Ports, Naval Yards, Offshore Platforms, Marinas, Recreational Piers, Shipyards End User: Port Authorities, Maritime Contractors, Shipping Companies, Shipbuilders, Harbor Operators, Infrastructure Developers |
| Companies Covered | Trelleborg, Fendercare Marine, ESC Marine Systems, Prosertek Group, Walcon Marine, Mampaey Offshore Industries, ShibataFenderTeam, QuayQuip, Shanghai Haisan Marine Instrument, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mooring Bollards Market Trends and Innovations
Smart mooring systems and predictive maintenance architectures are reconfiguring how port operators manage vessel securing operations, shifting capital allocation from passive hardware toward integrated asset performance platforms.
Composite-reinforced bollard designs incorporating fiber-optic load sensing are electrifying real-time tension monitoring capabilities. Offshore platform operators in the North Sea and Gulf of Mexico are adopting these configurations fastest, enabling predictive failure alerts that compress unplanned downtime intervals and extend inspection cycles beyond traditional manual assessment protocols.
REACH substance restrictions and the EU F-Gas Regulation are tightening material composition standards for protective coatings and polymer components used in marine environments. Manufacturers serving European port authorities must reformulate surface treatments and gasket materials, with double-bitt configurations for container terminals facing the most intensive compliance recertification requirements.
Lifecycle service bundling is displacing discrete equipment sales at major harbor authorities. Port operators in Rotterdam and Singapore now specify ten-year performance contracts encompassing installation, inspection, and replacement scheduling, forcing traditional foundries to build field service organizations or partner with marine maintenance specialists to retain account access.
Mooring Bollards Market Segmentation
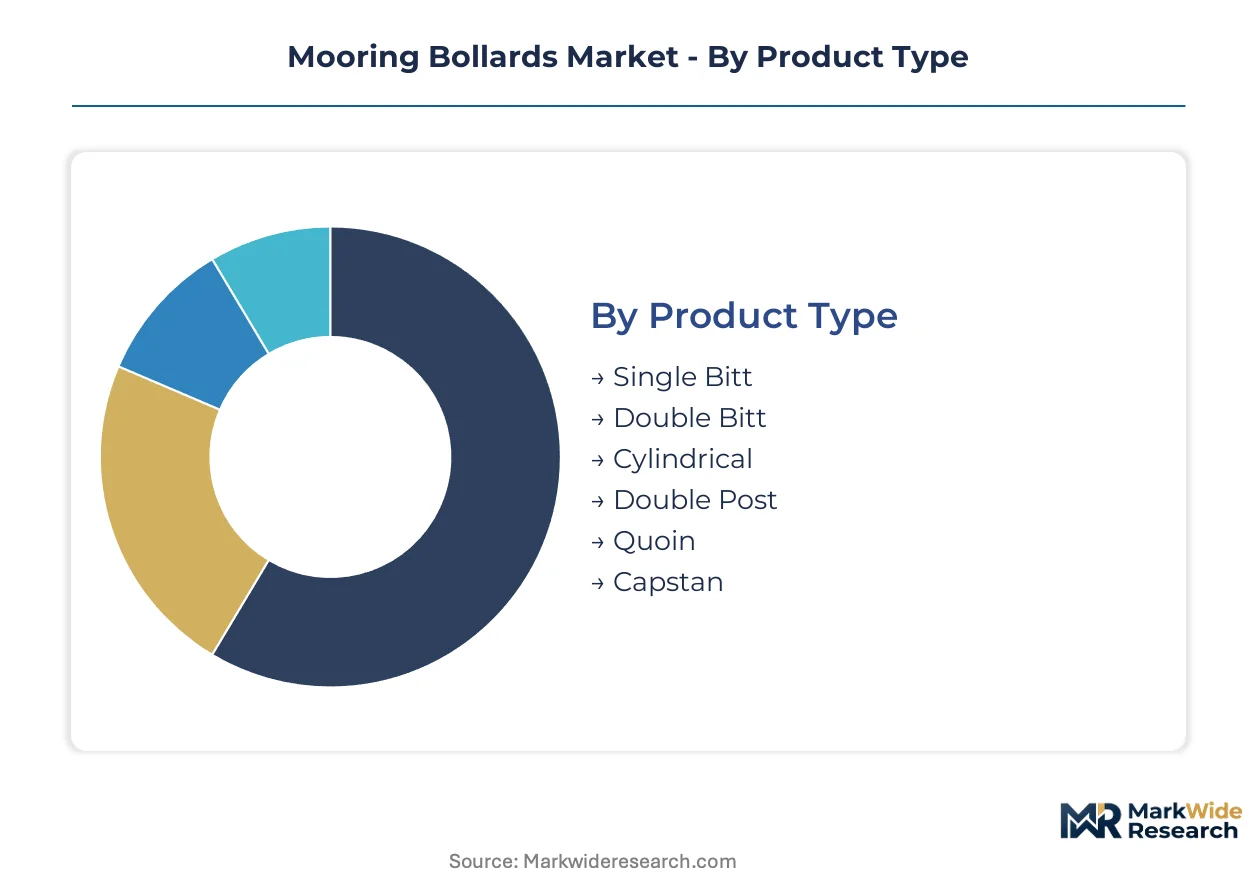
Mooring bollard specifications diverge sharply across operating environments, from the 200-tonne SWL demands of ultra-large container vessels to the aesthetic requirements of recreational marinas. Procurement patterns track capital deployment cycles at port authorities, shipyard expansion programs, and offshore platform commissioning schedules.
Product Type:
Capital intensity escalates with load rating complexity, as foundry capacity and metallurgical testing requirements concentrate in high-tonnage configurations.
- Double Bitt:Twin-post castings distribute extreme mooring loads across reinforced concrete foundations, accommodating multiple line angles simultaneously. Port authorities in Vietnam and Indonesia specify these for deep-water container berths handling 24,000 TEU vessels. IMO safety guideline revisions are accelerating replacement cycles at aging facilities.
- Single Bitt:Simpler geometry suits moderate-load applications with predictable line vectors, dominating shipyard temporary mooring and smaller commercial installations. Foundry tooling costs run lower, attracting mid-tier suppliers without specialized marine casting capabilities.
- Cylindrical:Continuous surface geometry permits 360-degree line attachment flexibility, serving offshore platforms where vessel positioning varies with weather windows.
- Double Post:Separated uprights enable independent line management for vessels with asymmetric mooring requirements, common in naval yard configurations.
- Quoin:Angled face plates guide lines into optimal load distribution angles, specified where space constraints limit bollard placement options.
- Capstan:Rotating drum mechanisms assist line handling, reducing manual labor requirements at high-traffic commercial terminals.
Most installed capacity flows through Single Bitt configurations. Expansion is steepest in Double Bitt as Southeast Asian port authorities scale for larger vessel classes.
Material:
Raw material selection governs fatigue performance under cyclic loading and total lifecycle cost, with alloy specifications tightly coupled to certification requirements from DNV and Bureau Veritas.
- Ductile Iron:Spheroidal graphite microstructure delivers superior fatigue resistance under millions of load cycles, making it the default for permanent commercial port installations. Rotterdam and Singapore procurement specifications mandate this grade for SWL ratings above 100 tonnes.
- Casted Steel:Higher tensile strength accommodates the most extreme load ratings, specified for ultra-large container vessel berths and offshore platform applications. Scrap steel price volatility compresses margin predictability for foundry-dependent producers.
- Carbon Steel:Cost-effective standard for moderate-load applications with protective coating systems, common in secondary port infrastructure.
- Stainless Steel:Corrosion resistance and aesthetic finish command premium positioning at marinas and recreational piers where visual standards govern selection.
- Aluminium:Lightweight properties simplify handling during installation, suited to temporary mooring systems and smaller craft facilities.
- Bronze:Traditional marine alloy specified for heritage restoration projects and specialized naval applications requiring non-sparking properties.
Volume concentrates in Ductile Iron and Casted Steel. Stainless Steel is gaining share fastest as marina aesthetic specifications tighten across European harbors.
Application:
Operating environment dictates structural load requirements, inspection protocols, and replacement cycles, with commercial ports absorbing the heaviest capital deployment.
- Commercial Ports:Permanent berth infrastructure requires 50-year design life with minimal maintenance interruption, driving specification of high-fatigue ductile iron configurations. ISO 3913 certification mandates now disqualify non-compliant suppliers from tender participation at Rotterdam, Singapore, and Long Beach.
- Offshore Platforms:Dynamic positioning environments and extreme weather exposure demand specialized high-tension designs with real-time load monitoring integration. North Sea operators are adopting fiber-optic sensing configurations fastest.
- Naval Yards:Security protocols and specialized vessel geometries require custom foundation solutions with extended project timelines.
- Marinas:Lower structural loads and corrosion aesthetics govern material selection, with stainless steel and aluminium commanding premium positioning.
- Recreational Piers:Visual integration with waterfront architecture drives specification of polished metal finishes and compact geometries.
- Shipyards:Temporary mooring flexibility takes priority over permanent fixtures, favoring modular and relocatable configurations.
Revenue concentrates in Commercial Ports. Offshore Platforms are climbing the fastest as predictive maintenance architectures reconfigure capital allocation.
End User:
Procurement authority and budget cycle timing fragment across public port authorities, private maritime contractors, and integrated shipping companies with captive terminal operations.
- Port Authorities:Public procurement frameworks emphasize lifecycle cost and certification compliance, with Rotterdam and Singapore now specifying ten-year performance contracts encompassing installation through replacement scheduling.
- Maritime Contractors:Project-based bidding for new construction and major retrofit programs concentrates demand during regional port expansion waves.
- Shipping Companies:Terminal operating divisions with captive berths prioritize rapid turnaround and minimal downtime, driving adoption of condition-monitoring subscriptions.
- Shipbuilders:New vessel construction schedules synchronize with launch facility requirements, creating lumped demand patterns.
- Harbor Operators:Third-party terminal management companies balance equipment standardization across multiple facility locations.
- Infrastructure Developers:Greenfield port projects in Vietnam and Indonesia are prioritizing deep-water berth capacity along strategic shipping lanes.
Contract value concentrates with Port Authorities. Maritime Contractors are expanding most quickly as Southeast Asian berth capacity scales up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam and Indonesia are outpacing mature European harbors in berth expansion investment, while Rotterdam and Singapore anchor certification standards that filter supplier access across procurement channels worldwide.
Vietnam
Deep-water port development along the Cai Mep-Thi Vai corridor is absorbing high-load double-bitt configurations for 24,000 TEU vessel classes. The Ministry of Transport's master plan prioritizes international transshipment hub status through 2030. Hai Phong and Ba Ria-Vung Tau provinces concentrate foundry-dependent fabrication capacity serving regional export demand.
Indonesia
Strategic shipping lane positioning is driving procurement of ultra-large container vessel infrastructure at Kuala Tanjung and Patimban terminals. The national port authority's modernization program mandates ISO 3913 compliance for all new berth installations. Java and Sumatra island clusters host the primary manufacturing and installation contractor networks.
Netherlands
Rotterdam's procurement specifications now disqualify non-certified suppliers from tender participation, filtering demand toward compliant manufacturers. EU Green Deal port modernization incentives accelerate berth electrification projects requiring redesigned mooring systems. The Rotterdam-Moerdijk industrial corridor concentrates lifecycle service bundling expertise.
Singapore
The Maritime and Port Authority enforces ten-year performance contracts encompassing installation through replacement scheduling. PSA International's terminal operating specifications prioritize condition-monitoring subscriptions over discrete hardware sales. The Tuas mega-port development is absorbing premium-tier ductile iron configurations with integrated load sensing.
United States
Long Beach and Los Angeles port authorities are retrofitting aging concrete infrastructure with custom foundation solutions for shore power integration. The EPA's port emissions reduction programs are rewriting vessel mooring profiles as alternative-fuel designs alter load specifications. Gulf Coast offshore platform operators in Texas and Louisiana are adopting fiber-optic sensing configurations fastest.
Mooring Bollards Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with foundry-dependent producers competing against polymer engineering houses on lifecycle cost metrics. The vendor base concentrates around three strategic archetypes: integrated marine fendering specialists, high-load configuration engineers, and regional fabrication contractors. Consolidation pressure is accelerating through strategic partnerships between European design houses and Asian foundry networks, while technology licensing agreements transfer composite sensing architectures across geographies.
Within the integrated marine fendering tier, Trelleborg exemplifies the polymer-to-service bundling model, anchoring long-term maintenance agreements alongside hardware installations. Fendercare Marine occupies a position emphasizing lifecycle packages that sustain recurring revenue streams. ESC Marine Systems represents the high-load engineering specialist archetype, with double-bitt configurations for ultra-large container vessels positioning its capabilities at the premium tier. These three patterns illustrate how competitive positioning is decoupling hardware sales from pure capital expenditure cycles across port authority procurement channels.
| Leading Market Players |
|---|
| Trelleborg |
| Fendercare Marine |
| ESC Marine Systems |
| Prosertek Group |
| Walcon Marine |
| Mampaey Offshore Industries |
| ShibataFenderTeam |
| QuayQuip |
| Shanghai Haisan Marine Instrument |
| Others |
Pricing and Supply Chain Analysis
Foundry metallurgist clusters in Hai Phong and Ba Ria-Vung Tau provinces anchor labor-cost differentials that widen pricing-tier spreads between premium ductile iron configurations and economy-grade carbon steel alternatives. Port authorities in Rotterdam and Singapore absorb these spreads through lifecycle contracting, while Southeast Asian infrastructure developers prioritize upfront capital efficiency.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for standard-grade bollard configurations as new foundry capacity absorbs regional demand surges. Three-tier pricing structure across premium, standard, and economy levels separates ISO 3913-certified ductile iron systems from PIANC-compliant carbon steel alternatives and uncoated economy grades. Cost compression in the standard tier is intensifying because scrap steel price volatility feeds directly into foundry quotations. Maritime contractors exhibit the highest price sensitivity due to project-based bidding cycles, whereas port authorities with ten-year performance contracts prioritize lifecycle cost over unit pricing.
Supply Chain Analysis
Direct-to-port-authority channels handle high-specification procurement for Rotterdam, Singapore, and Long Beach terminals, while maritime contractors aggregate demand through project-based tendering. Manufacturing gravity centers on Vietnam, Indonesia, and the Netherlands, with Hai Phong and Rotterdam-Moerdijk corridors concentrating specialized marine casting capabilities. Raw material feeds draw from spheroidal graphite iron foundries, scrap steel recyclers, and polymer composite suppliers. Single-source vulnerability concentrates in certified ductile iron ingot supply, where DNV and Bureau Veritas qualification requirements filter accessible suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mooring Bollards Market compounds steadily as port infrastructure renewal cycles synchronize with IMO safety guideline enforcement across commercial harbor networks.
For Market Incumbents: To counter polymer engineering talent scarcity, Trelleborg and Fendercare Marine should deepen backward integration into condition-monitoring software development, anchoring recurring revenue streams that offset hardware margin compression. ESC Marine Systems must defend its premium-tier positioning through accelerated certification investment in fiber-optic load sensing configurations before composite-reinforced designs commoditize. For New Entrants and Emerging Players: The pricing gap between premium ductile iron systems and economy carbon steel alternatives opens white-space targeting at mid-tier commercial ports in Malaysia and the Philippines, where ISO 3913 compliance pressures meet constrained capital budgets. Marina aesthetic specifications in Mediterranean harbors represent the most penetrable segment, with stainless steel configurations commanding premium positioning against visual standards. A go-to-market angle through harbor maintenance subcontractor partnerships bypasses incumbent port authority relationships. For Investors and Strategic Acquirers: Integrated marine fendering specialists are the most active acquirer in this space, consolidating regional fabrication contractors to capture Southeast Asian berth expansion cycles. Long-term viability over a decade-plus window rests on service revenue attachment rates rather than hardware shipment volumes. Acquisition target archetypes include foundry-dependent producers with dormant certification capabilities and field service organizations with port authority maintenance contracts. The signal to watch is ten-year performance contract penetration at Rotterdam and Singapore as a proxy for recurring revenue model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 3913 Certification Investment | Unlocks tender participation at Rotterdam, Singapore, and Long Beach port authorities. |
| Condition-Monitoring Platform Development | Transforms Trelleborg's polymer expertise into recurring service revenue streams. |
| Southeast Asian Foundry Partnership | Positions ESC Marine Systems to capture Vietnam and Indonesia deep-water port expansion. |
| Fiber-Optic Load Sensing Integration | Enables predictive maintenance architectures for North Sea offshore platform operators. |
| Lifecycle Service Bundling | Displaces discrete equipment sales at port authorities specifying ten-year performance contracts. |
Research Methodology
Multiple input streams — technical discussions with port authority procurement directors, foundry operations managers, and marine engineering consultants, alongside classification society certification officers — were reconciled against customs trade data, PIANC technical reports, and SEC filings from listed marine infrastructure suppliers. Secondary validation drew from ISO 3913 documentation, DNV and Bureau Veritas rule sets, and port modernization program disclosures. Bottom-up shipment estimates from foundry outputs and top-down port capital expenditure allocations were triangulated to anchor volume and value assessments.
Data-stream reconciliation across the projection horizon applied product type, material grade, application environment, and end-user procurement authority as segmentation dimensions. CAGRs were derived from elasticity-adjusted demand curves responding to berth capacity expansion schedules and regulatory compliance deadlines. Forecast inputs incorporated scrap steel price cycle assumptions, foundry capacity utilization trends, and shore power infrastructure rollout pacing at major harbors.
The model assumes a particular technology adoption path; alternative pathways for composite-reinforced bollard designs with embedded fiber-optic sensing would alter the outlook if North Sea offshore operators accelerate predictive maintenance architectures faster than base assumptions. Forecasts reflect documented assumptions about IMO guideline enforcement timing and EU Green Deal port modernization subsidy availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Cable Laying Vessel Market