
 United Kingdom White Cement Market | 2026-2036
United Kingdom White Cement Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom White Cement Market Analytics
Asset-light leasing arrangements for bulk grinding and blending equipment is rewriting competitive entry dynamics for smaller white cement blenders. CRH leverages its integrated quarry-to-distributor network across England and Wales to sustain volume commitments. Breedon Group plc anchors its position through specialized bagging operations serving Scottish precast producers. Hanson competes via captive limestone reserves that support consistent clinker whiteness grades.
White cement is a Portland cement variant manufactured with raw materials selected for low iron oxide content, yielding a product with L* whiteness values typically exceeding 85 and primary use in architectural concrete, terrazzo, and decorative mortar applications. Regular white cement occupies the largest volume share across UK distribution channels, while specialty white cement commands premium positioning in restoration projects requiring sulfate resistance or rapid-hardening performance. The artistic facades application segment demonstrates the fastest specification growth as London developers pursue distinctive exterior aesthetics.
The UK's Building Safety Regulator and British Standards Institution enforce material traceability and performance certification requirements that elevate compliance costs for imported white cement. BSI's EN 197-1 conformity assessment shapes product acceptance thresholds across commercial and residential construction. Specifiers must monitor evolving Part B fire-safety guidance and its cascading effects on cladding system material selection.
Market Dynamics
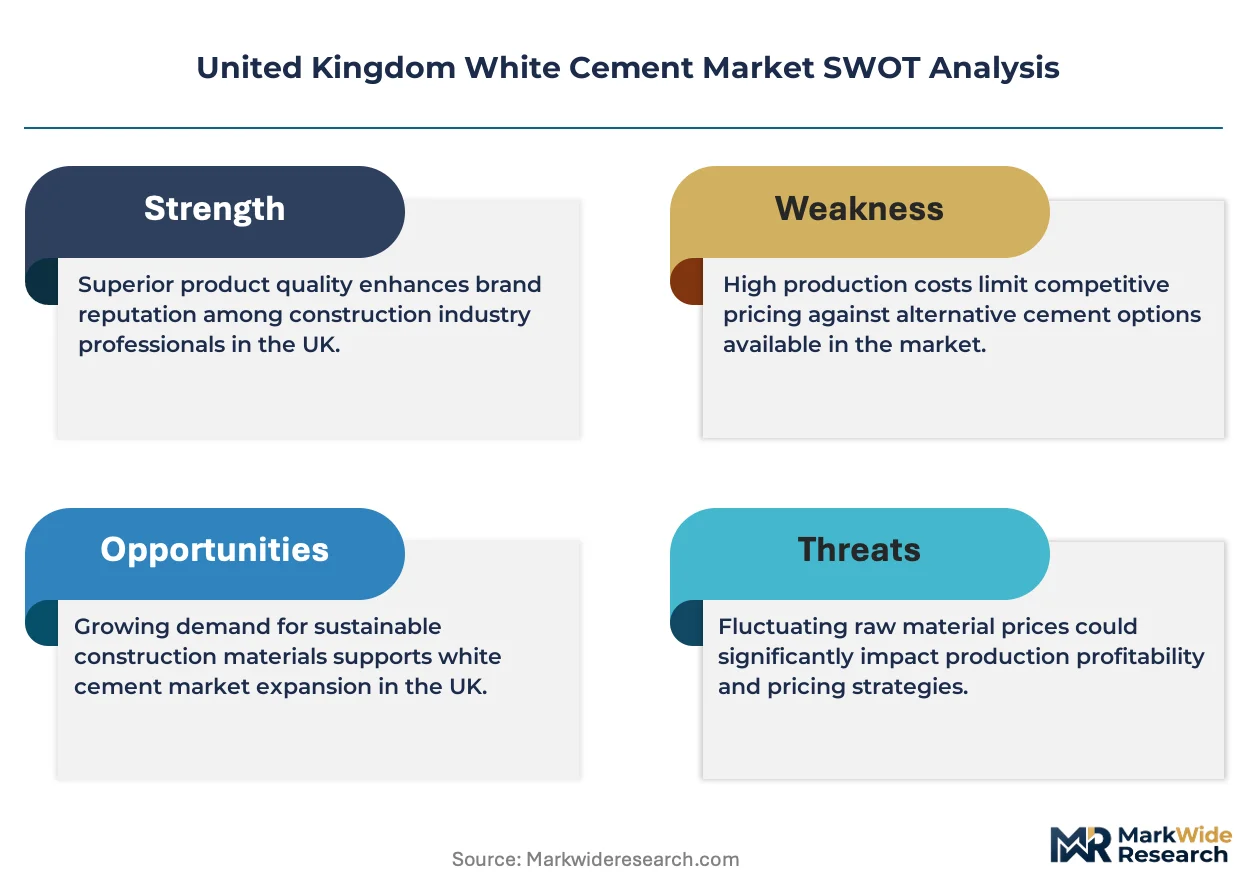
The UK's Building Safety Regulator enforcement of stricter fire-safety material standards is redirecting specification decisions toward certified white cement systems, compressing procurement timelines and elevating compliance documentation burdens across commercial facade refurbishment projects.
Growth Catalysts
- Fire-safety regulatory tightening:The Building Safety Regulator's Part B guidance revisions are mandating non-combustible cladding substrates, redirecting specification toward white cement-based architectural concrete in Greater London high-rise refurbishment.
- Decorative precast expansion:Manufacturers across Manchester and Birmingham are scaling terrazzo and artistic facade production, pulling bulk white cement volumes through specialized distributors.
- Low-iron raw material processing advances:Improved kiln atmosphere control and kaolin selection protocols are expanding consistent L* whiteness grade availability for restoration mortar applications.
Market Restraints
- Clinker import concentration:UK grinding capacity depends on seaborne white clinker from Mediterranean and Middle Eastern suppliers, exposing margins to freight rate volatility and currency fluctuation.
- Energy input cost exposure:Natural gas and electricity price spikes in Britain directly inflate calcination and finish grinding costs, compressing blender profitability at fixed-price contract volumes.
- Limestone reserve quality constraints:Captive carbonate deposits with iron oxide content below 0.5% are geographically scarce, limiting new entrant vertical integration options.
Strategic Opportunities
- Scottish precast specialization:Breedon Group plc's bagging operations demonstrate unmet demand among Aberdeen and Inverness architectural concrete producers for rapid-hardening white cement variants.
- Carbon capture integration:Emerging post-combustion capture retrofitting at existing kilns could position UK-produced white clinker within EU Carbon Border Adjustment Mechanism-compliant supply chains.
- Digital specification platforms:Building information modeling integration is enabling real-time whiteness grade matching between mortar producers and restoration architects, compressing sample approval cycles.
Industry Challenges
- Certification timeline compression:BSI EN 197-1 conformity assessment and Building Safety Regulator material traceability requirements are extending batch approval periods for imported clinker sources.
- Specialized blending technician scarcity:Precise pigment dosing and consistency control for restoration-grade sulfate-resistant white cement demands skills concentrated among aging workforce cohorts in Yorkshire and Midlands grinding facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom White Cement Market |
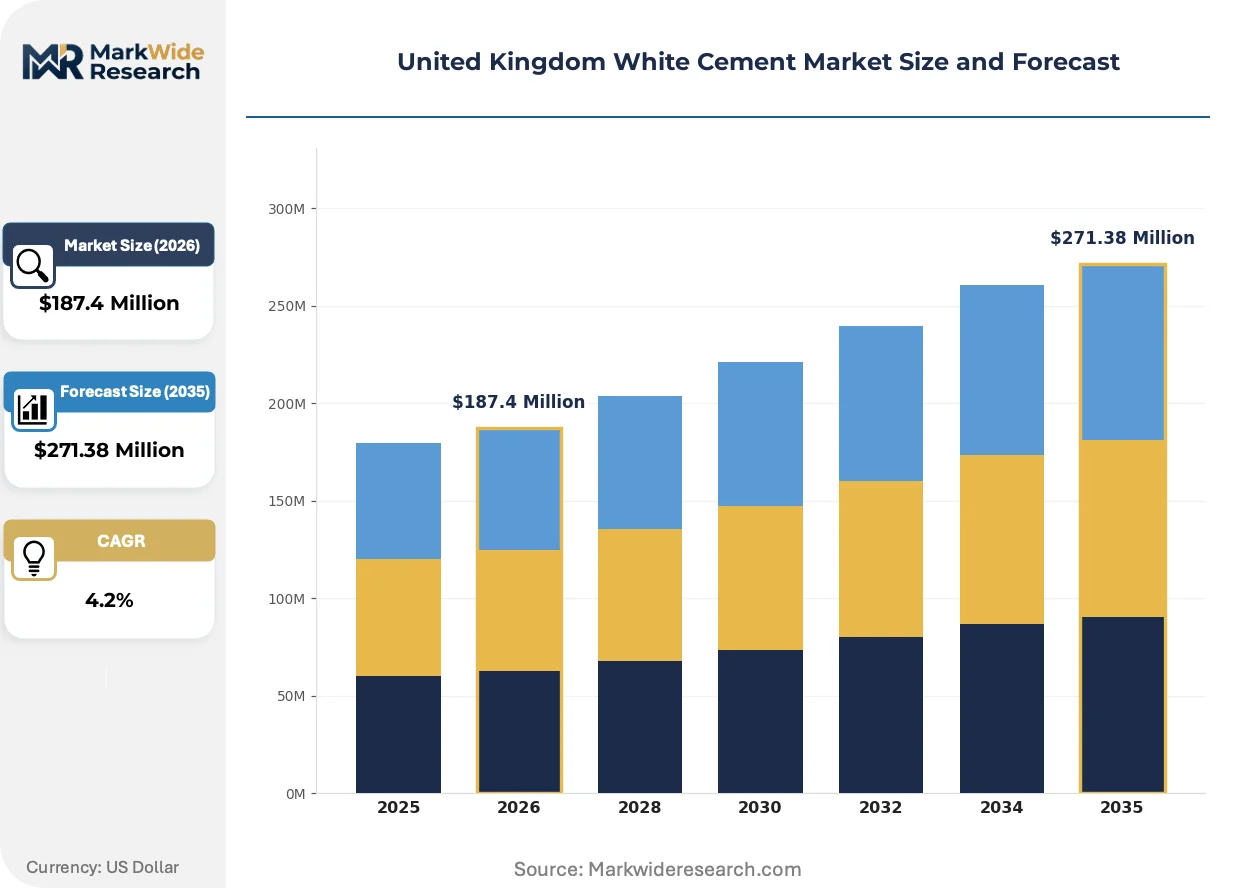
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular White Cement, High-Strength White Cement, Specialty White Cement, Decorative White Cement End Use Industry: Construction, Infrastructure, Precast Concrete, Architectural Designs Application: Residential Buildings, Commercial Structures, Road Construction, Artistic Facades Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Cementir Holding N.V., CRH, Breedon Group plc, Southern Cement Limited (CRH Company), Dragon Alpha Cement Ltd, Hanson (HeidelbergCement AG), Cemex S.A.B. de C.V., Tarmac, Aggregate Industries (Holcim Group), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom White Cement Market Evolving Landscape
Specification digitization and carbon accountability are compressing traditional procurement cycles while elevating material traceability requirements across UK white cement distribution channels.
Sensor-equipped grinding mills is digitizing real-time whiteness monitoring and particle size distribution control, enabling consistent L* grade output. Scottish and northern English precast producers are adopting these systems fastest, replacing manual sampling protocols. The technology is digitizing quality assurance labor, compressing batch release timelines from days to hours.
The Building Safety Regulator's consolidated fire-safety framework is mandating full material chain of custody documentation for cladding system components. This regulatory shift is elevating third-party certification costs for imported white cement while favoring domestic grinding operations with integrated quarry-to-distributor traceability systems. Commercial facade refurbishment contractors in southeast England are responding by consolidating supplier panels around BSI-audited domestic blenders.
Architects and developers are unbundling material specification from general contractor procurement, establishing direct white cement sourcing relationships with certified blenders. This disintermediation is displacing traditional merchant distributor roles in London commercial projects. The shift is most visible among heritage restoration specialists requiring rapid-hardening or sulfate-resistant grade consistency guarantees unavailable through standard distribution channels.
United Kingdom White Cement Market Segmentation
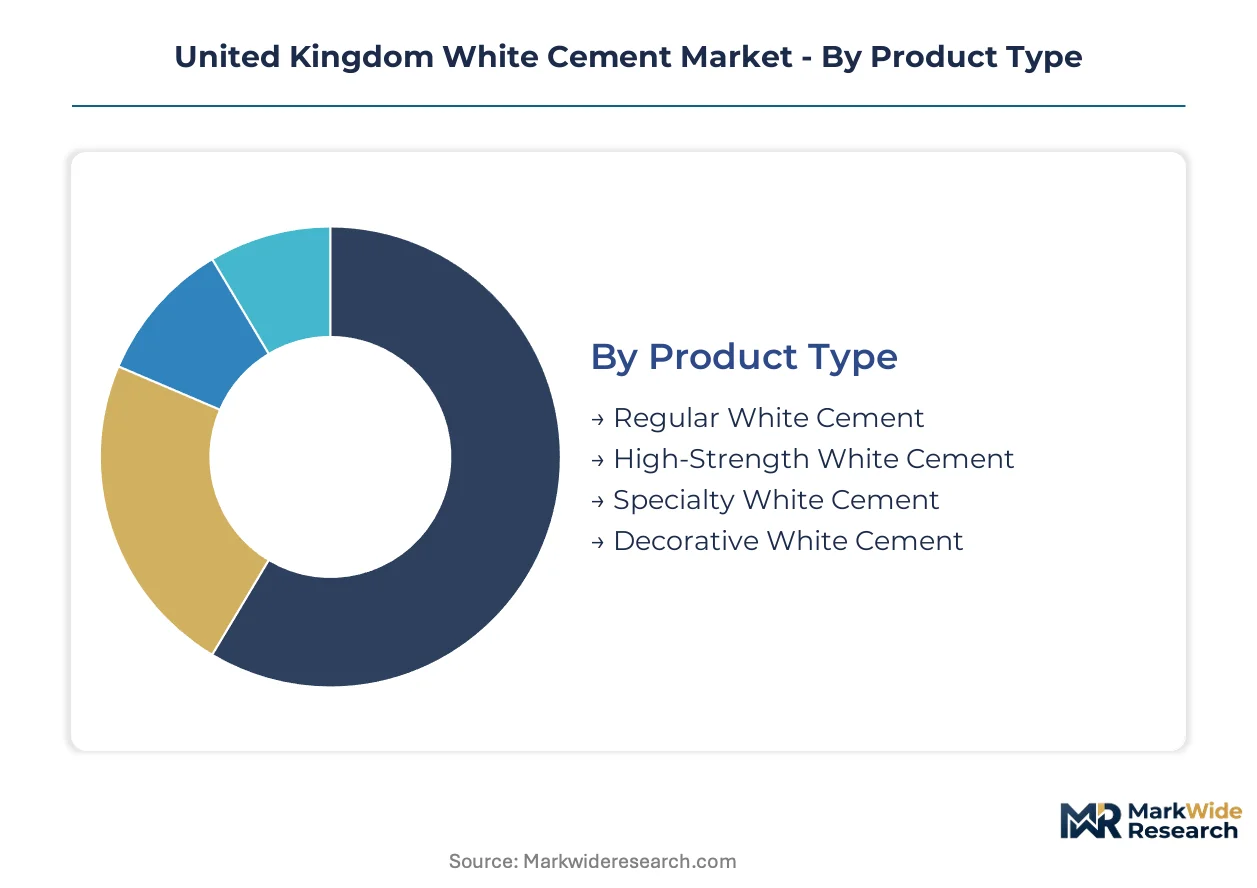
Segmentation in the UK white cement market exposes divergent procurement cycles across product grades and end-use specifications. Architects specify specialty grades months ahead of construction, while precast manufacturers turn regular white cement inventories weekly. Understanding these velocity differences shapes inventory positioning and margin capture strategies for domestic blenders.
Product Type:
Regular white cement rotates through distribution channels fastest, turning inventory in under fourteen days during peak construction seasons. Specialty and decorative grades sit longer, with specification-to-delivery cycles stretching sixty to ninety days as architects sample and approve whiteness consistency.
- Regular White Cement:Standard Portland cement variant manufactured with low-iron raw materials yielding L* whiteness values above 85. Greater London commercial facade refurbishment contractors specify this grade in bulk for architectural concrete cladding, driven by Building Safety Regulator fire-safety compliance deadlines compressing procurement timelines.
- Specialty White Cement:Engineered variants including sulfate-resistant and rapid-hardening formulations for heritage restoration mortar. Scottish precast producers in Aberdeen and Inverness specify these grades for exterior terrazzo installations requiring freeze-thaw durability certification under BSI EN 197-1 standards.
- High-Strength White Cement:Early-strength development formulations for structural precast elements demanding accelerated demolding cycles.
- Decorative White Cement:Pigment-compatible base formulations for colored architectural concrete and exposed aggregate finishes.
Regular white cement dominates installed base volume. Specialty white cement is where expansion concentrates as restoration architects seek performance guarantees unavailable through standard grades.
End Use Industry:
Cost tier differentiation separates commodity construction applications from premium architectural specifications. Infrastructure and precast concrete operate on thin margin, high-volume contracts, while architectural design projects absorb three-to-fivefold material cost premiums for certified whiteness consistency.
- Construction:General building sector encompassing structural concrete and masonry mortar applications. Southeast England residential developers specify white cement for premium facade finishes, constrained by energy input cost exposure compressing blender profitability at fixed-price contract volumes.
- Precast Concrete:Off-site manufactured architectural elements including cladding panels, terrazzo tiles, and decorative screens. Manchester and Birmingham manufacturers are scaling production capacity, pulling bulk white cement volumes through specialized distributors serving just-in-time delivery requirements.
- Infrastructure:Civil engineering applications including bridges, tunnels, and transportation facilities requiring durable exposed concrete finishes.
- Architectural Designs:Bespoke exterior and interior aesthetic applications demanding precise color matching and surface texture control.
Construction commands the largest volume share. Architectural designs is climbing the fastest as London developers pursue distinctive exterior aesthetics disintermediating traditional merchant distributors.
Application:
Geographic demand concentration within the UK creates divergent specification patterns. Southeast England commercial refurbishment drives premium grade absorption, while residential applications distribute more evenly across regional markets with lower per-project volume intensity.
- Commercial Structures:Office, retail, and hospitality buildings requiring fire-rated cladding substrates. Greater London high-rise refurbishment contractors specify white cement-based architectural concrete under Part B guidance revisions mandating non-combustible materials, redirecting procurement toward certified domestic blenders with integrated traceability systems.
- Artistic Facades:Sculptural exterior surfaces and decorative screen walls emphasizing visual distinction. London developers are specifying these applications fastest, creating direct sourcing relationships with certified blenders capable of rapid-hardening grade consistency guarantees.
- Residential Buildings:Single-family and multi-family housing with premium exterior finish requirements.
- Road Construction:Highway barriers, sound walls, and bridge elements requiring high-visibility white concrete.
Commercial structures absorb the majority of specification volume. Artistic facades represents the steepest expansion trajectory as aesthetic differentiation displaces standardized cladding solutions.
Distribution Channel:
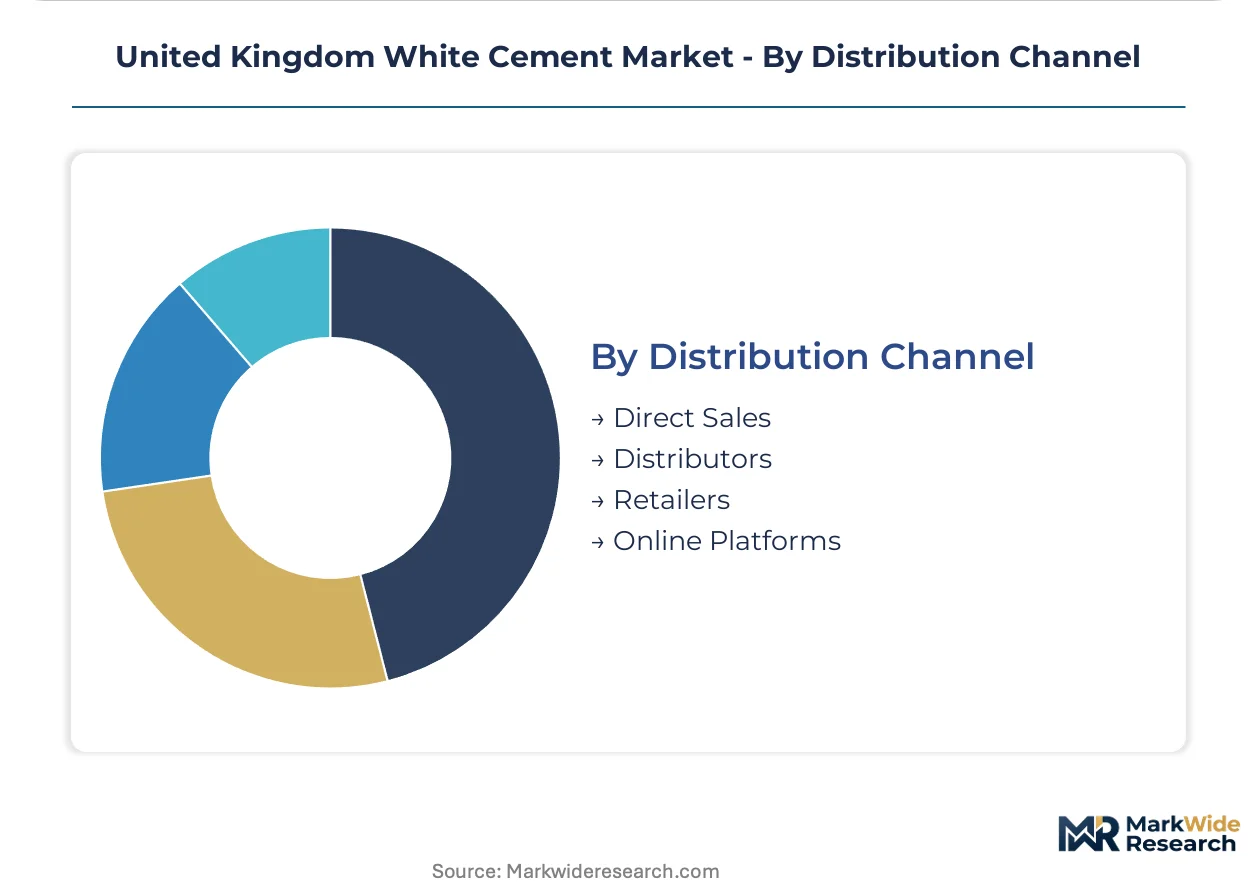
Customer type and order scale reshape channel economics. Large precast manufacturers bypass distributors entirely, while small restoration contractors depend on retailer availability with significant markup layers. Digital platforms are compressing these traditional tier structures.
- Direct Sales:Manufacturer-to-purchaser relationships for volume precast and commercial construction accounts. Heritage restoration specialists in London are establishing direct white cement sourcing relationships with certified blenders, displacing traditional merchant distributor roles in commercial projects.
- Distributors:Specialized construction material wholesalers carrying inventory and providing technical support. These intermediaries face margin compression as architects unbundle material specification from general contractor procurement and consolidate supplier panels around BSI-audited domestic blenders.
- Retailers:Local builders merchants serving small contractors and renovation specialists with bagged product.
- Online Platforms:Digital procurement channels enabling specification-grade product discovery and sample ordering.
Direct sales captures the largest volume flows. Distributors is where channel restructuring concentrates as digital specification platforms compress traditional procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Building Safety Regulator's Part B fire-safety guidance is redirecting specification decisions toward certified white cement systems across England's commercial refurbishment corridors. Scotland's precast specialization and Wales' infrastructure pipeline create divergent demand profiles that reshape regional procurement patterns.
Greater London and Southeast England
High-rise commercial facade refurbishment contractors specify white cement-based architectural concrete under stricter non-combustible cladding mandates. The Building Safety Regulator enforces material traceability requirements that elevate compliance costs for imported clinker. London developers pursuing distinctive exterior aesthetics are establishing direct sourcing relationships with certified blenders, displacing traditional merchant distributor roles.
Midlands
Manchester and Birmingham decorative precast manufacturers are scaling terrazzo and artistic facade production capacity. The region's grinding facilities depend on seaborne white clinker from Mediterranean suppliers, exposing margins to freight rate volatility. Specialized distributors serving just-in-time delivery requirements are consolidating supplier panels around BSI-audited domestic blenders.
Scotland
Aberdeen and Inverness architectural concrete producers generate unmet demand for rapid-hardening white cement variants in exterior terrazzo installations. Scottish precast producers adopt sensor-equipped grinding mills for real-time whiteness monitoring faster than southern counterparts. Breedon Group plc anchors regional supply through specialized bagging operations.
Wales
Infrastructure projects requiring durable exposed concrete finishes absorb steady volumes of regular white cement. CRH leverages integrated quarry-to-distributor networks across England and Wales to sustain volume commitments. The region's captive limestone reserves with iron oxide content below 0.5% are geographically scarce, limiting new entrant integration options.
Northern England
Yorkshire and Midlands grinding facilities harbor specialized blending technician skills concentrated among aging workforce cohorts. Precise pigment dosing and consistency control for restoration-grade sulfate-resistant white cement demands expertise that is becoming harder to replace. Heritage restoration specialists in the region require performance guarantees unavailable through standard distribution channels.
United Kingdom White Cement Market Competitive Landscape
On the supply side, the industry is consolidating around integrated quarry-to-distributor networks and specialized regional bagging operations. Three archetypes dominate: multinational building materials conglomerates with captive limestone reserves, regional specialists with targeted precast relationships, and asset-light blenders leasing bulk grinding equipment. Competitive moves concentrate on vertical integration into clinker sourcing and certification-driven supplier panel consolidation by major contractors.
Among UK-based operators, CRH and Breedon Group plc exemplify divergent strategic positions within the market structure. CRH occupies the integrated network archetype through quarry-to-distributor control across England and Wales. Breedon Group plc represents the regional specialization model through Scottish bagging operations serving Aberdeen and Inverness precast producers. Cementir Holding N.V. anchors the multinational specialist tier with European white cement expertise. These three operators collectively demonstrate how scale, geography, and end-use focus shape competitive positioning under tightening Building Safety Regulator compliance requirements.
| Leading Market Players |
|---|
| Cementir Holding N.V. |
| CRH |
| Breedon Group plc |
| Southern Cement Limited (CRH Company) |
| Dragon Alpha Cement Ltd |
| Hanson (HeidelbergCement AG) |
| Cemex S.A.B. de C.V. |
| Tarmac |
| Aggregate Industries (Holcim Group) |
| Others |
Value Network & Pricing Analysis
Greater London's grinding and blending capacity concentration shapes downstream pricing power for white cement across southeast England's commercial facade refurbishment corridor. The Building Safety Regulator's Part B fire-safety compliance deadlines compress procurement timelines, elevating premium capture for BSI-audited domestic blenders with integrated traceability systems.
Pricing Analysis
Certification level under BSI EN 197-1 conformity assessment creates the primary spread between regular and specialty white cement grades. Three-tier pricing structure across restoration-grade, standard architectural, and bulk construction tiers reflects iron oxide content thresholds and rapid-hardening performance guarantees. Cost compression in the standard tier intensifies because energy input cost exposure inflates calcination and finish grinding expenses. Precast concrete manufacturers demonstrate highest price sensitivity due to thin-margin, high-volume contract structures, while heritage restoration specialists absorb premiums for sulfate-resistant grade consistency unavailable through distribution channels.
Supply Chain Analysis
Extended payment terms from seaborne white clinker suppliers in Turkey, Egypt, and Saudi Arabia strain working capital for UK grinding facilities dependent on Mediterranean and Middle Eastern feedstock. The supply chain draws from captive limestone reserves with iron oxide content below 0.5% in Wales and England, alongside imported clinker for finish grinding. Single-source vulnerability concentrates in seaborne freight lanes exposed to currency fluctuation and vessel availability constraints. Distribution runs through specialized construction material wholesalers consolidating supplier panels around BSI-audited domestic blenders, with direct sales capturing volume flows from large precast manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building Safety Regulator enforcement fragments procurement authority, creating niches for certified blenders as architects unbundle material specification from general contractor relationships.
For Market Incumbents: Harden market position through backward integration into captive limestone reserves with sub-0.5% iron oxide content, defending against asset-light entrants leasing bulk grinding equipment. CRH's quarry-to-distributor network across England and Wales exemplifies channel control leverage. Certification investment in EN 197-1 conformity assessment infrastructure raises compliance barriers for imported clinker competitors. For New Entrants and Emerging Players: Northern England's Yorkshire and Midlands grinding facilities harbor aging specialized blending technician cohorts whose pigment dosing expertise is becoming irreplaceable. This capability scarcity creates white-space for rapid-hardening and sulfate-resistant grade production serving heritage restoration mortar demand. Scottish precast specialization in Aberdeen and Inverness offers the most penetrable geography, with digital specification platform integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational building materials conglomerates seeking to divest non-core regional white cement operations. Long-term viability hinges on carbon capture retrofitting positioning UK-produced white clinker within EU Carbon Border Adjustment Mechanism-compliant supply chains. Watch for Building Safety Regulator material traceability requirements extending batch approval periods as the inflection indicator compressing imported clinker competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofitting | Post-combustion capture at existing kilns positions UK clinker within EU CBAM-compliant supply chains. |
| Specialized Bagging Operations | Breedon Group plc's Scottish facilities demonstrate regional precast relationship anchoring through rapid-hardening variants. |
| Digital Specification Platform Integration | Building information modeling compresses sample approval cycles between mortar producers and restoration architects. |
| Sensor-Equipped Grinding Mill Deployment | Real-time whiteness monitoring digitizes quality assurance labor, compressing batch release timelines from days to hours. |
| Direct Sourcing Relationship Development | London developers establishing certified blender relationships displace traditional merchant distributor roles in commercial projects. |
Research Methodology
The analysis maps regular white cement, specialty formulations, high-strength variants, and decorative grades, each validated through technical directors at precast manufacturers, procurement leads at commercial refurbishment contractors, restoration architects, and BSI certification officers. Primary interviews with grinding facility operators and distribution channel partners combined with secondary validation from UK trade data, Building Safety Regulator guidance documents, SEC filings of listed building materials groups, and EN 197-1 conformity assessment records. Bottom-up volume triangulation across end-use segments reconciled with top-down market sizing.
Assumptions held fixed include Building Safety Regulator enforcement trajectory and EU Carbon Border Adjustment Mechanism implementation scope, while energy input cost volatility and freight rate fluctuation were modeled as scenario variables. Segmentation dimensions encompass product grade tier, end-use industry, application type, and distribution channel structure. CAGRs derived from regression analysis of historical volume patterns and projected specification shifts. Industry-specific forecast inputs include commercial facade refurbishment pipeline data and precast capacity expansion announcements.
Practitioners should monitor regulatory timeline compression for BSI EN 197-1 conformity assessment and seaborne clinker freight rate volatility for early signals of margin pressure. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Metal Cladding Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Building and Construction Sheets Market
Building Materials
Blended Cement Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
United States Construction Materials Market
Building Materials
Cement Tiles Market
Building Materials
Building and Construction Plastics Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Italy Facade Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Cement Market
Building Materials
Steel Slag Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Exterior Doors Market
Building Materials
Dutch Brick Market