
 Subsea Trencher Market | 2026-2036
Subsea Trencher Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Trencher Market Intelligence
The divergence between high-specification, deep-water trenching systems and standardized shallow-water equipment is repositioning the competitive landscape. Helix Energy Solutions Group leverages its integrated vessel and robotics fleet for complex deep-water projects. DeepOcean specializes in remote operations and soil remediation for the offshore renewables sector. Meanwhile, Prysmian focuses on cable installation solutions, integrating trenching as part of a turnkey service offering.
A subsea trencher is a remotely operated or autonomous underwater vehicle designed for excavating trenches on the seabed. These machines operate at significant depths to achieve precise burial depths required for asset protection. Cable installation for offshore wind and interconnectors drives demand for jet trenchers and compact trenchers. Within applications, pipeline burial remains a mature segment, while umbilical protection shows steady requirements from the oil and gas sector.
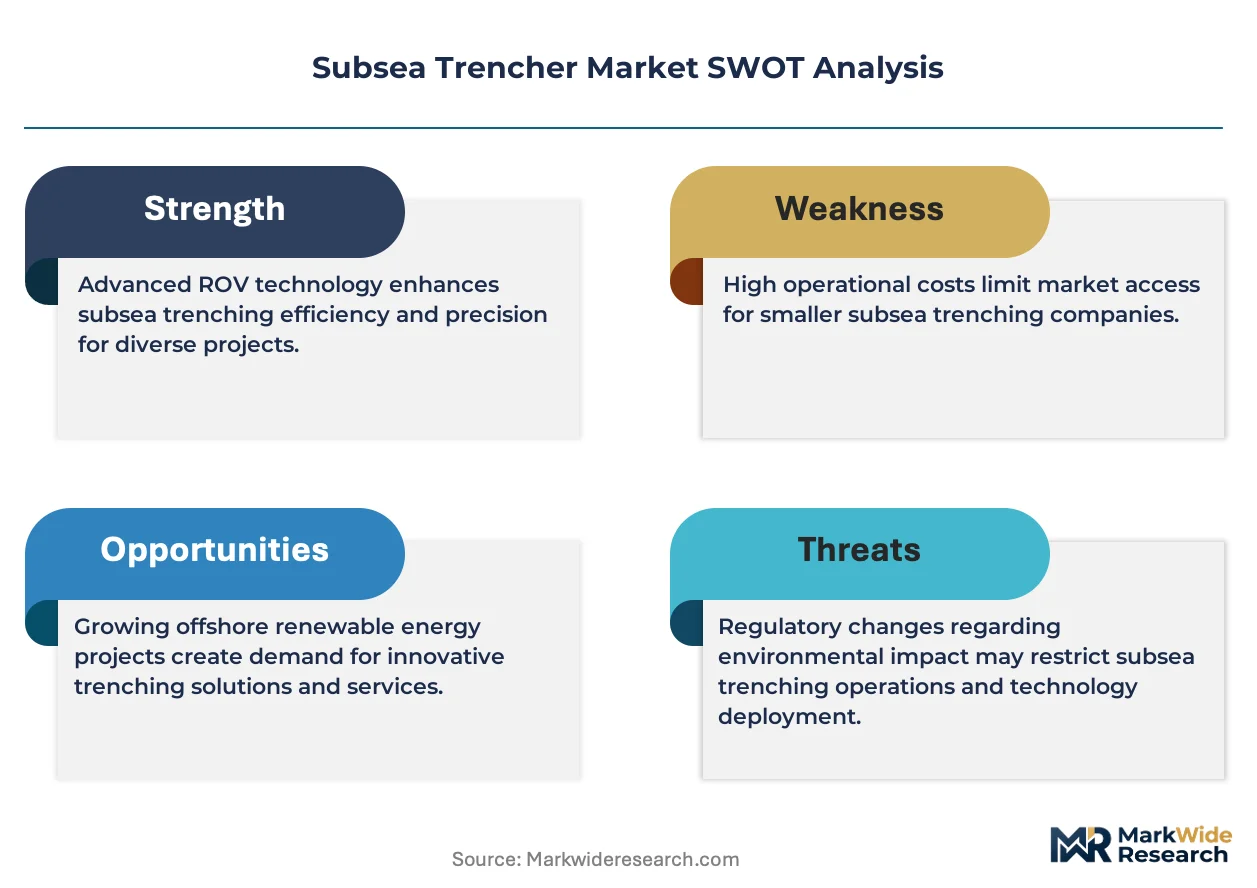
Environmental regulations, such as the EU's Marine Strategy Framework Directive and stipulations from the US Bureau of Safety and Environmental Enforcement, govern seabed disturbance. These frameworks mandate minimal ecological impact during trenching operations, influencing equipment design and operational procedures. Stakeholder success will depend on adapting equipment capabilities to meet both deeper water challenges and stricter environmental compliance.
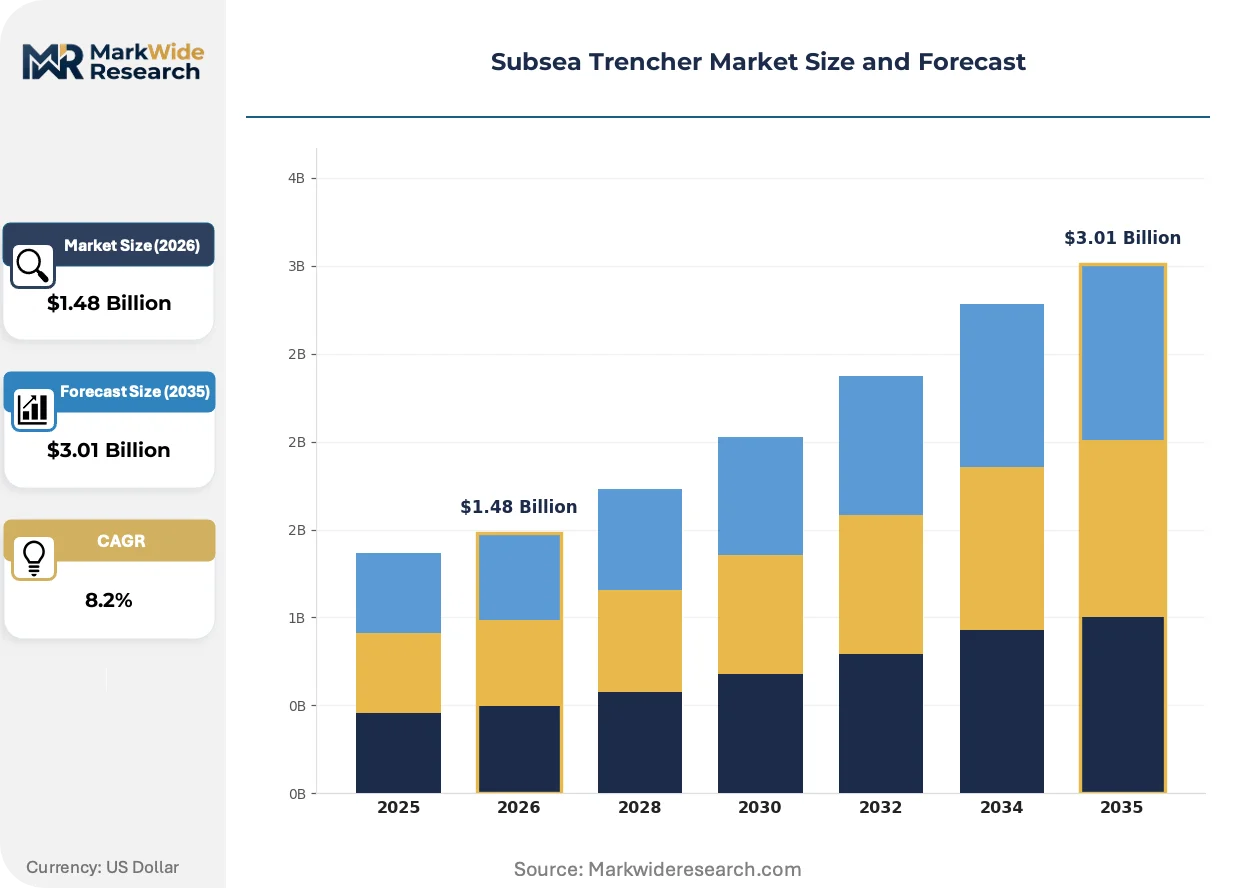
Market Dynamics
The central structural force shaping the subsea trencher market is the rapid build-out of offshore renewable energy infrastructure. This demand, accelerated by policy frameworks like the EU Green Deal, concentrates activity and technological development around cable burial for wind farms.
Growth Catalysts
- Offshore Wind Farm Expansion:The development of large-scale wind projects, particularly in the deeper waters of the North Sea, requires extensive cable trenching for both inter-array and export power transmission, directly stimulating equipment demand.
- HVDC Interconnector Projects:Construction of high-voltage subsea power lines to link national electricity grids across regions like the Baltic Sea and Mediterranean necessitates deep and secure burial, creating a consistent demand pipeline for specialized trenchers.
- Favorable Energy Policies:Government mandates and incentives in Europe and Asia-Pacific are fast-tracking permits for subsea infrastructure projects, reducing lead times and encouraging investment in advanced trenching capabilities.
Market Restraints
- High Vessel Day Rates:The operational cost of specialized support vessels required for trencher deployment and operation remains a significant project expense, making project economics highly sensitive to vessel availability and charter rates.
- Challenging Seabed Geologies:Hard and unpredictable ground conditions, including rock formations and boulder fields common in key development zones, pose a high risk of equipment damage and project delays, limiting operational efficiency.
- Skilled Personnel Shortages:A limited global pool of experienced ROV pilots and trencher technicians creates a critical bottleneck, constraining the ability of contractors to staff the growing number of concurrent offshore projects.
Strategic Opportunities
- Emerging Asia-Pacific Markets:Nations such as Taiwan, South Korea, and Vietnam are initiating ambitious offshore wind programs, creating significant new geographic markets for trenching services outside of the traditional European hub.
- Floating Offshore Wind Infrastructure:The need to secure mooring lines and bury dynamic power cables for floating wind installations represents a novel application requiring specialized trenching solutions to ensure system stability.
- Autonomous and Remote Operations:Investing in fully autonomous trenching systems can reduce dependency on large crews and support vessels, offering a pathway to lower operational costs, increased safety, and wider weather windows.
Industry Challenges
- Strict Environmental Permitting:Navigating complex regulations governing seabed disturbance, such as the US Bureau of Safety and Environmental Enforcement (BSEE) stipulations, adds considerable time and cost to project planning and execution.
- Intensive Capital Expenditure:The significant upfront investment required to build and certify new high-specification, deep-water trenching assets acts as a substantial barrier to entry and limits fleet expansion for many operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Trencher Market |
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Trencher, Jet Trencher, Wheel Trencher, Chain Trencher, Compact Trencher Technology: Hydraulic, Pneumatic, Electric, Electro-Hydraulic, Mechanical Application: Pipeline Burial, Cable Installation, Umbilical Protection, Subsea Soil Remediation End User: Subsea Construction Firms, Offshore Engineering Companies, Marine Contractors, Energy Producers |
| Companies Covered | Helix Energy Solutions Group, Prysmian, NKT, Enshore Subsea, OSBIT, Helix Robotic Solutions, DeepOcean, Mastenbroek, Global Marine Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Trencher Market Strategic Shifts & Innovations
The evolution of subsea trenching is driven by the dual pressures of increasing project complexity in deeper waters and tightening environmental regulations. This dynamic fosters innovation in automation, remote operation, and low-impact excavation technologies, particularly for the offshore renewables sector.
Remote-controlled and semi-autonomous trenching systems integrate real-time soil analysis and advanced sensor suites to optimize burial parameters. Offshore energy contractors are adopting these systems to improve operational efficiency and reduce reliance on large offshore crews. This shift toward data-driven, remote operation is overtaking traditional manually-piloted trenching methods, especially in complex deep-water projects requiring precise execution.
The European Union's Marine Strategy Framework Directive (MSFD) establishes strict criteria for maintaining the environmental health of marine waters. This directive compels operators to minimize physical seabed disturbance, underwater noise, and sediment plumes generated during trenching. Equipment manufacturers are responding by developing low-impact jetting tools and advanced environmental monitoring systems to ensure compliance in sensitive ecosystems.
A transition from standalone equipment rental to integrated, turnkey service contracts is altering procurement patterns. This model bundles the trencher, support vessel, crew, and survey services into a single package, displacing the fragmented approach previously favored by project developers. The trend is most prominent in the European offshore wind sector, where developers seek to de-risk project execution by transferring interface management to specialized contractors.
Subsea Trencher Market Segmentation
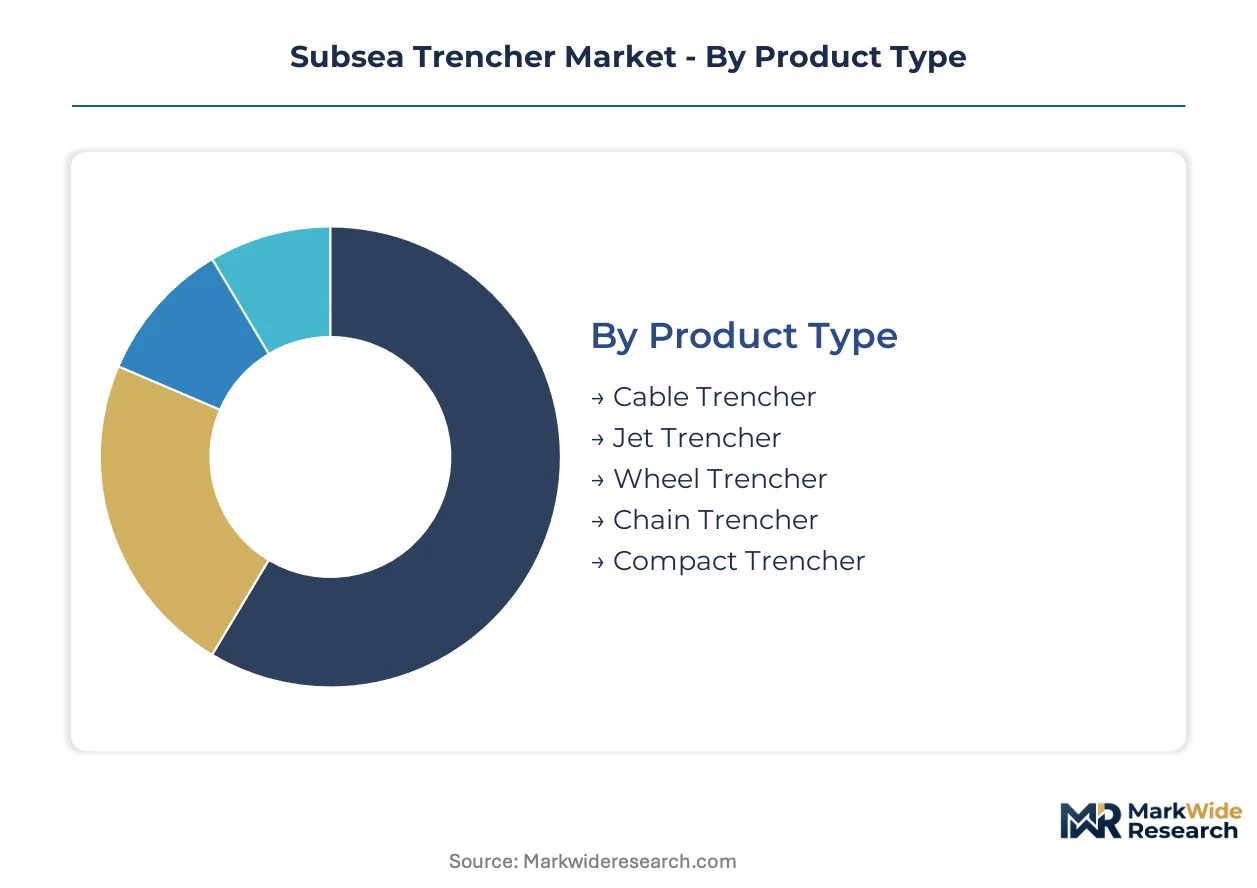
The subsea trencher market categorizes equipment and services based on their operational capabilities and intended applications. Understanding these distinctions is crucial for stakeholders to align their offerings with specific project requirements and optimize resource deployment. This segmentation highlights the diverse technical demands across various subsea infrastructure developments.
Product Type:
Buyer decisions for subsea trenchers often hinge on the specific burial depth, soil conditions, and asset type requiring protection. Each product type offers distinct advantages for different operational environments.
- Jet Trencher:This system uses high-pressure water jets to fluidize and excavate seabed material, creating a trench for cables or pipelines. Demand concentrates in soft to medium soil conditions for offshore wind farm cable installation in the North Sea.
- Cable Trencher:Designed specifically for burying subsea power and communication cables, these systems often integrate jetting and mechanical cutting tools. Expanding offshore wind projects in the Baltic Sea drive significant demand for these specialized units.
- Wheel Trencher:Featuring a rotating wheel equipped with cutting teeth, this trencher excels in harder seabed materials, including rock and consolidated clay. It provides precise trenching for pipeline protection.
- Chain Trencher:This robust system utilizes a continuous chain with cutting tools to excavate trenches in challenging and mixed ground conditions. It offers versatility for various subsea infrastructure projects.
- Compact Trencher:Smaller and more agile, compact trenchers are suitable for shallow water operations, inter-array cable burial, and projects with restricted access. They support nearshore wind farm developments.
Volume sits with Jet Trenchers; growth tilts toward Cable Trenchers.
Technology:
Cost tiers often differentiate subsea trencher technologies, reflecting varying levels of power, precision, and operational complexity. The choice of technology impacts both initial investment and long-term operating expenses.
- Electro-Hydraulic:These systems combine electric power for propulsion and control with hydraulic power for trenching tools, offering high efficiency and precise control. Demand for these advanced systems is strong in deep-water projects requiring meticulous execution.
- Hydraulic:Relying on hydraulic power for all operational functions, these trenchers are robust and widely deployed for various subsea excavation tasks. They offer proven reliability across diverse seabed conditions.
- Pneumatic:Utilizing compressed air, pneumatic trenchers are generally employed for lighter excavation tasks or in specific environmental conditions where hydraulic fluid contamination is a concern. They provide a specialized solution for delicate operations.
- Electric:Fully electric trenchers are emerging as a more environmentally friendly option, reducing reliance on hydraulic fluids and offering quieter operation. Their adoption is increasing for projects with strict environmental mandates.
- Mechanical:These trenchers use direct mechanical force, often with blades or plows, to excavate trenches, suitable for shallower waters and specific soil types. They offer a straightforward approach to seabed preparation.
Efficiency gains drive adoption in Electro-Hydraulic systems; specialized needs sustain Hydraulic technology.
Application:
The volume of subsea trenching activity is heavily influenced by the specific application, with some segments representing mature markets and others experiencing rapid expansion. Each application presents unique technical challenges.
- Cable Installation:This segment involves burying power and communication cables for offshore wind farms, interconnectors, and telecommunications networks. The rapid build-out of offshore renewable energy infrastructure in Europe drives significant demand.
- Pipeline Burial:Trenching for subsea oil and gas pipelines ensures their protection from anchors, fishing gear, and environmental hazards. This remains a mature segment with consistent demand for asset integrity in the North Sea.
- Umbilical Protection:Umbilicals, which supply power, data, and chemicals to subsea production systems, require precise burial for operational reliability. The oil and gas sector maintains steady requirements for this critical infrastructure.
- Subsea Soil Remediation:This application involves modifying seabed conditions for foundation preparation, debris removal, or environmental restoration. Specialized trenchers support marine construction and ecological projects.
Investment priorities align with Cable Installation due to offshore wind growth; mature requirements sustain Pipeline Burial.
End User:
Customer type defines the procurement patterns and scale of subsea trencher deployment, ranging from large integrated service providers to specialized niche players. Each end-user group has distinct operational needs.
- Subsea Construction Firms:These companies specialize in large-scale underwater infrastructure projects, including trenching, often operating integrated fleets of vessels and ROVs. They require high-specification equipment for complex deep-water assignments.
- Offshore Engineering Companies:Providing design, planning, and project management for offshore developments, these firms often procure trenching services as part of broader engineering, procurement, construction, and installation (EPCI) contracts. They prioritize reliability and technical expertise.
- Marine Contractors:Offering a range of marine services, these contractors undertake trenching for various clients, often providing support vessels and operational crews. They serve diverse project scales and requirements.
- Energy Producers:Oil and gas companies and offshore wind developers utilize trenching services for their own infrastructure projects, either directly or through contracting specialist firms. They focus on project timelines and cost efficiency.
Market share consolidation occurs among Subsea Construction Firms; specialized services support Offshore Engineering Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aberdeen, a hub for North Sea offshore operations, drives significant demand for subsea trenching services. This region benefits from extensive offshore wind farm developments and critical interconnector projects. European policy frameworks, like the EU Green Deal, accelerate investment in subsea infrastructure.
United Kingdom
Offshore wind projects, particularly Dogger Bank, require extensive cable trenching for export and inter-array cables. The UK's Crown Estate leasing rounds encourage new offshore energy developments and associated subsea work. Humberside and the East Coast are seeing increased activity for turbine foundation and cable installation projects.
Germany
North Sea wind farm expansion, including projects like Gode Wind, creates sustained demand for specialized trenchers. Germany's Renewable Energy Sources Act (EEG) provides a stable regulatory environment for offshore investments. Emden and Wilhelmshaven ports serve as key logistics bases for offshore wind construction.
Taiwan
Ambitious offshore wind programs, such as those off Changhua County, necessitate significant cable trenching for inter-array and export cables. Taiwan's Bureau of Energy policy supports the localization of offshore wind supply chains and infrastructure development. Taichung Port is developing as a major staging area for wind farm construction and maintenance activities.
United States
East Coast offshore wind projects, including Vineyard Wind, are driving initial demand for subsea trenching. The Bureau of Ocean Energy Management (BOEM) oversees leasing and permitting for these developments. New Bedford and Port of Virginia are emerging as critical ports for offshore wind logistics.
South Korea
Floating offshore wind pilot projects and large-scale fixed-bottom developments require advanced trenching solutions. The government's Green New Deal targets significant expansion of renewable energy capacity. Ulsan is positioned as a key industrial cluster for floating wind technology and subsea infrastructure.
Subsea Trencher Market Key Industry Players
Premium-margin players sit above commodity-margin players across operational complexity and deep-water capability in the subsea trencher market. The competitive landscape features a mix of vertically integrated service providers, specialized equipment manufacturers, and niche remote operations specialists. These distinct archetypes focus on either turnkey project execution or advanced technology solutions. Strategic partnerships and targeted capacity expansion are common competitive moves to secure market share.
Specialists in integrated services like Helix Energy Solutions Group exemplify the high-end segment, combining vessel fleets with advanced robotics for complex deep-water assignments. DeepOcean occupies a position as a leader in remote operations and soil remediation, particularly for the offshore renewables sector. Prysmian, a global cable manufacturer, represents a unique approach by integrating trenching as part of its comprehensive, turnkey cable installation solutions. These companies demonstrate diverse strategies, from asset ownership to specialized service delivery, shaping the market's competitive dynamics.
| Leading Market Players |
|---|
| Helix Energy Solutions Group |
| Prysmian |
| NKT |
| Enshore Subsea |
| OSBIT |
| Helix Robotic Solutions |
| DeepOcean |
| Mastenbroek |
| Global Marine Group |
| Others |
Cost & Logistics Intelligence
The clear performance gap between high-specification deep-water trenching systems and standardized shallow-water equipment drives distinct pricing and supply chain configurations. This divergence reflects the varying capital intensity and technical expertise required for different operational environments.
Pricing Analysis
Project-based pricing, anchored to successful asset protection and precise burial depths, dominates the subsea trencher market. Price differentiation stems from deep-water operational capability, compliance with environmental certifications, and the integration of specialized vessels. Pricing pressure is currently upward due to high vessel day rates and a limited pool of skilled personnel. Energy producers, particularly offshore wind developers, exhibit lower price sensitivity for critical, time-sensitive projects.
Supply Chain Analysis
Skilled workforce availability in key operational hubs like the United Kingdom and Germany directly influences equipment deployment and service costs. The supply chain for advanced trenching systems draws from specialized component manufacturers across Europe and North America. Single-source vulnerability for highly specialized robotics and high-pressure jetting systems represents a structural risk. Downstream, distribution runs through direct sales from equipment manufacturers to subsea construction firms or as part of integrated turnkey service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with key players pursuing the in-house production of specialized vessels and robotics to control project execution.
For Market Incumbents:Deploy advanced automation solutions to mitigate the impact of skilled personnel shortages and high operational costs. Expand specialized deep-water fleet capacity to secure long-term contracts in the growing offshore wind sector. Invest in R&D for low-impact excavation technologies to address stricter environmental permitting requirements. This strategy defends against new entrants offering agile, remote-first models.
For New Entrants and Emerging Players:Begin with targeted penetration into emerging Asia-Pacific markets, such as Taiwan and South Korea, which offer significant new offshore wind opportunities. Focus on compact trencher solutions for shallow water or inter-array cable burial, emphasizing environmental compliance. Offer specialized, remote-operated systems as a go-to-market angle, reducing reliance on large offshore crews and support vessels.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized technology providers with proven deep-water capabilities or unique low-impact trenching solutions. The long-term viability of this market remains strong, driven by the persistent build-out of offshore renewable energy infrastructure. A key signal to watch as an inflection indicator is the increased regulatory mandates for autonomous operations and stringent environmental impact reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Deep-Water Fleet | Secures market share in complex offshore wind projects. |
| R&D in Autonomous Trenching Systems | Reduces operational costs and addresses skilled personnel shortages. |
| Strategic Partnerships for Turnkey Solutions | De-risks project execution for energy developers. |
| Geographic Expansion into Asia-Pacific | Captures demand from ambitious new offshore wind programs. |
| Low-Impact Excavation Technology Development | Ensures compliance with strict environmental regulations like the MSFD. |
Research Approach
Document review covered industry reports, company filings, and government policy documents, complemented by interviews with subsea construction firm executives, offshore wind project managers, ROV pilots, and environmental regulators. This primary research was triangulated with secondary data from marine energy association publications, offshore wind project databases, and academic journals on subsea engineering. Both bottom-up and top-down approaches were utilized to ensure comprehensive market sizing.
The quantitative model produced volume and value projections by integrating supply-side capacity with demand-side project pipelines across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and key regional markets like the North Sea and Asia-Pacific. Compound annual growth rates were derived from historical growth trends and projected offshore wind capacity targets and interconnector project timelines.
Geopolitical instability, global economic downturns, and unforeseen technological breakthroughs are the dominant revision risks for these forecasts. Forecasts reflect assumptions documented regarding current policy environments and project development rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market