
 Bilge Pump Market | 2026-2036
Bilge Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Bilge Pump Market Analytics
Marine aftermarket distribution through specialty chandleries and direct OEM supply contracts is reshaping how bilge pump manufacturers reach end users. DESMI leverages its Danish engineering heritage to sustain premium positioning in commercial fishing and offshore vessel segments. SEAFLO competes aggressively on cost-engineered electric models for recreational boat builders across Asia-Pacific. Xylem extends its dewatering expertise from industrial markets into marine applications through controlled distribution partnerships with major shipyards.
A bilge pump is a fluid-handling device engineered to evacuate accumulated water, oil residues, and effluent from the lowest interior compartments of vessels and industrial installations, typically operating at flow rates from 300 to 3,700 gallons per hour with head pressures up to 20 feet; its primary purpose is to prevent flooding, structural corrosion, and regulatory violations in maritime and heavy industrial environments. Automatic electric units dominate commercial marine procurement due to integrated float-switch reliability and minimal crew intervention, while solar-powered configurations represent the fastest-expanding power source category among remote mooring and aquaculture operators. Stainless steel construction commands the material premium tier in saltwater applications, though glass-reinforced thermoplastic composites are displacing bronze in mid-range recreational segments on weight and galvanic compatibility grounds.
The US Coast Guard enforces bilge pump capacity and automatic operation standards under 46 CFR subchapter requirements, while the EU Marine Equipment Directive mandates CE-marked conformity for products sold within member state waters. ISO 8849 and ISO 15083 testing protocols govern submersible performance certification, creating compliance thresholds that filter out uncertified suppliers. Stakeholders must monitor evolving ballast water management crossovers and electrification mandates in major flag-state jurisdictions to anticipate product specification shifts before design lock-in cycles conclude.
Market Dynamics
Automatic float-switch integration and sealed motor architectures are compressing replacement cycles while elevating performance benchmarks across commercial and recreational marine segments. Mediterranean boatbuilders and offshore vessel operators now specify corrosion-resistant alloys as baseline requirements, not premium upgrades.
Growth Catalysts
- EU F-Gas Regulation:Mandates for reduced refrigerant leakage are accelerating sealed-system pump designs in commercial fishing fleets operating within European Economic Area waters.
- Aquaculture expansion:Remote mooring installations across Southeast Asian archipelagos are specifying solar-powered bilge evacuation systems to eliminate generator dependency.
- Glass-reinforced thermoplastics:Saltwater recreational builders are specifying these composites over traditional bronze to eliminate galvanic corrosion in multi-material hull assemblies.
Market Restraints
- Stainless steel input volatility:Marine-grade 316L alloy pricing fluctuations compress margin stability for mid-tier pump assemblers dependent on spot-market sourcing.
- Turkish manufacturing concentration:Coastal production clusters around Izmir and Istanbul create single-point vulnerability for European OEM supply continuity.
- Ballast water management crossover:Competing treatment system technologies threaten to subsume standalone bilge pump specification in deep-sea tanker retrofit programs.
Strategic Opportunities
- Greek island ferry electrification:Domestic short-sea routes are mandating zero-emission auxiliary systems, opening specification windows for high-efficiency electric pump packages.
- Outcome-based maintenance contracts:Commercial fleet operators are unbundling pump replacement from integrated vessel management agreements, creating recurring revenue streams for certified service networks.
- ISO 15083 convergence:Harmonized submersible testing protocols across flag-state jurisdictions are reducing certification duplication costs for multi-market suppliers.
Industry Challenges
- Marine electrical technician scarcity:Specialized knowledge of IP68 sealing validation and float-switch calibration is concentrating among aging workforces in Italian and Croatian shipyards.
- Legacy 12V system integration:New 24V and 48V pump architectures require voltage converter retrofits that complicate warranty coverage and installation liability.
- CE marking timeline compression:EU Marine Equipment Directive notified body backlogs are extending product launch cycles by four to six months for non-EU manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bilge Pump Market |
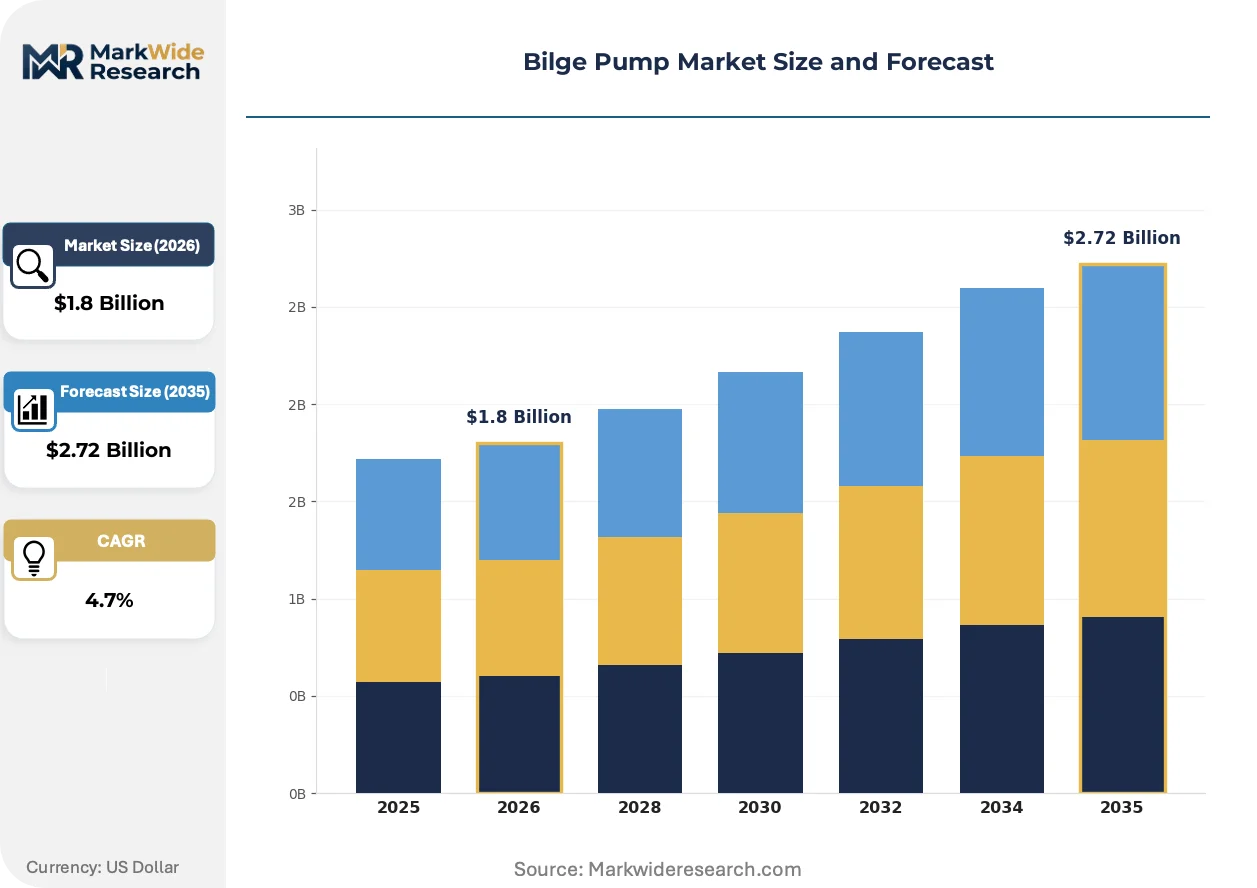
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Automatic, Manual, Submersible, Diaphragm Power Source: Electric, Solar, Hydraulic, Pneumatic Application: Marine, Industrial, Recreational, Commercial Material: Plastic, Stainless Steel, Bronze, Composite |
| Companies Covered | Whale Pumps, DESMI, Rule Industries, Pentair Shurflo, Xylem, Johnson Pump (SPX Flow), SEAFLO, Vetus, Attwood Marine (Brunswick Corporation), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bilge Pump Market Evolving Landscape
Electrification of auxiliary marine systems and convergence of industrial dewatering expertise with maritime specifications are redefining pump architecture priorities. Material science advances and procurement model evolution are simultaneously reshaping competitive positioning.
Brushless DC motor technology with integrated electronic commutation is eliminating mechanical wear points in high-cycle automatic operation. Offshore supply vessel operators are specifying these units for 10,000-hour maintenance intervals. Traditional brushed-motor rebuild programs are rendering obsolete across North Sea and Gulf of Mexico fleets.
EU F-Gas Regulation phase-down schedules are prohibiting certain refrigerant-based cooling systems in vessel engine rooms. Pump manufacturers must now certify thermal management compatibility with alternative cooling architectures. Italian and Greek commercial builders are front-loading sealed-motor specifications to preempt compliance deadlines.
Recreational boatbuilders are consolidating vendor lists from twelve-plus suppliers to three approved pump platforms per hull category. Direct OEM supply contracts are displacing traditional chandlery distribution for new-build specification. Turkish production facilities are capturing disproportionate share of this concentrated procurement through integrated logistics hubs.
Bilge Pump Market Segmentation
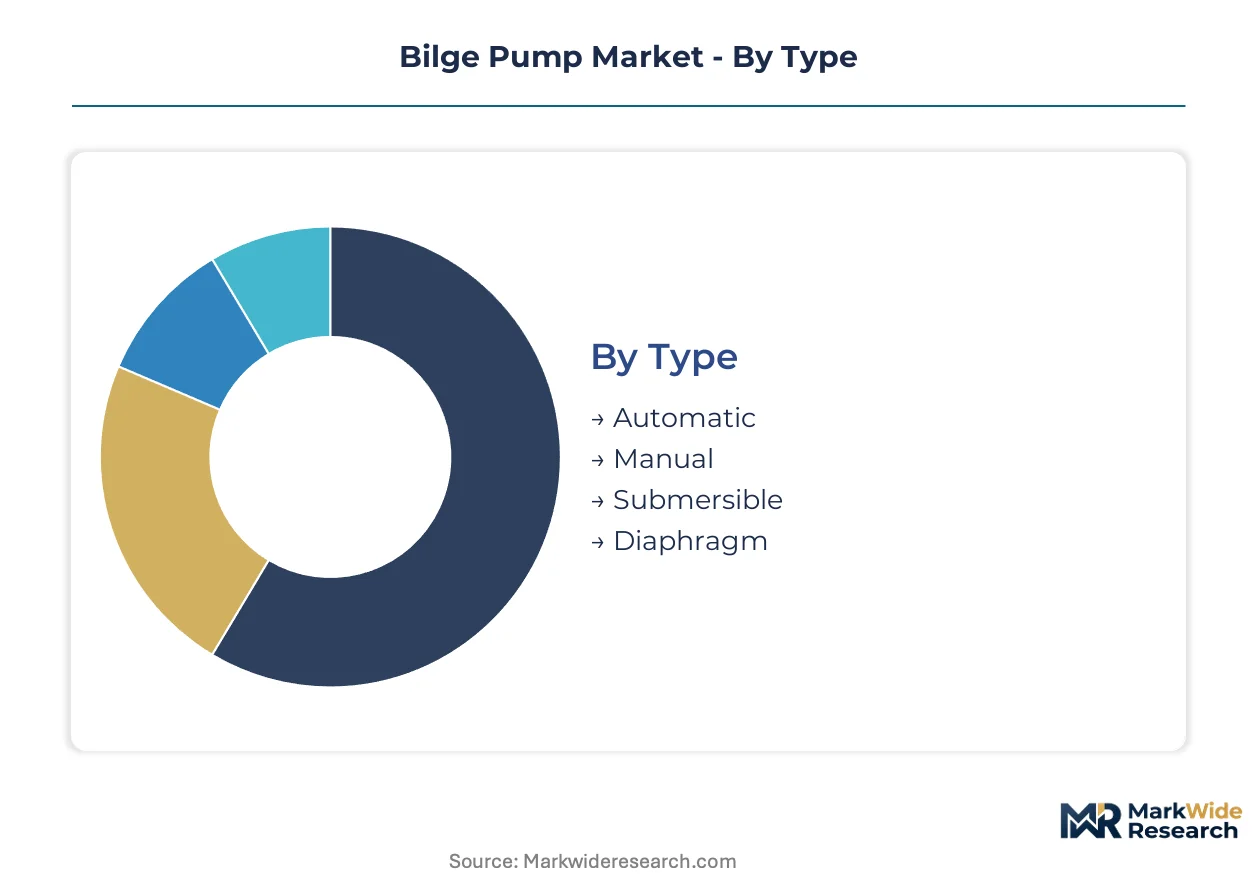
Bilge pump procurement varies sharply by operational intensity and service interval predictability. After-sales service requirements differ fundamentally between automatic float-switch systems and manual backup units, reshaping distributor inventory strategies and manufacturer warranty structures across marine and industrial channels.
Type:
After-sales intensity peaks with automatic variants requiring periodic float-switch calibration and seal inspection protocols.
- Automatic:Integrated float-switch mechanisms activate without crew intervention, demanding scheduled maintenance to prevent fouling failure. Mediterranean recreational builders specify these units for new-build installations to meet ISO 15083 compliance with minimal owner training.
- Submersible:IP68-rated motor housings operate fully immersed, eliminating priming requirements but requiring sealed-bearing replacement at defined intervals. North Sea offshore operators favor these for engine room redundancy where space constraints prohibit above-deck mounting.
- Manual:Hand-operated lever or rotary mechanisms serve as regulatory-mandated backup systems with negligible electronics maintenance. Coastal fishing fleets in Turkey and Greece retain these for emergency flooding scenarios when electrical systems fail.
- Diaphragm:Positive-displacement action handles viscous effluent and oil-water mixtures without impeller clogging. Italian commercial shipyards specify these for bilge-water processing ahead of oily water separator units.
Automatic units hold the largest share; momentum sits with submersible configurations as sealed-motor reliability improves.
Power Source:
Cost tier separation between grid-dependent and autonomous power architectures determines total ownership economics across vessel categories.
- Electric:DC motor variants dominate with standardized 12V and 24V architectures, though 48V systems are penetrating electrified auxiliary platforms. Greek island ferry operators specify high-efficiency electric packages for zero-emission route compliance.
- Solar:Photovoltaic panel integration eliminates generator dependency for remote mooring and aquaculture installations. Southeast Asian archipelago operators specify these for off-grid evacuation systems where fuel logistics prove prohibitive.
- Hydraulic:Engine-driven power take-off units deliver high flow rates without electrical ignition risk in hazardous zones. Offshore supply vessels deploy these for cargo hold dewatering where ATEX certification is mandatory.
- Pneumatic:Compressed-air operation suits explosive atmosphere installations with no spark potential. Chemical tanker retrofits specify these for pump room compliance with IECEx standards.
Electric systems command the dominant position; solar configurations are climbing the fastest as battery storage costs decline.
Application:
Volume concentration varies by regulatory enforcement intensity and fleet replacement cycles across end-use sectors.
- Marine:Commercial shipping, fishing vessels, and cargo carriers constitute the procurement core with class-society certification requirements. US Coast Guard 46 CFR enforcement drives specification uniformity across US-flagged fleets.
- Recreational:Yacht and pleasure craft builders consolidate vendor lists to three approved platforms per hull category. Turkish production facilities capture disproportionate share through integrated logistics hubs serving Mediterranean builders.
- Industrial:Mining, construction, and wastewater facilities adapt marine-rated pumps for aggressive dewatering duty. Xylem leverages industrial dewatering expertise into marine applications through controlled distribution partnerships.
- Commercial:Harbor services, tug operators, and coastal transport fleets balance reliability against capital constraints. Croatian and Italian shipyards face technician scarcity for specialized IP68 sealing validation.
Marine applications retain the largest share; recreational demand is expanding most quickly amid Mediterranean boatbuilder expansion.
Material:
Margin structure stratifies sharply by corrosion resistance requirements and raw material input volatility.
- Stainless Steel:Marine-grade 316L alloy construction commands premium positioning in saltwater immersion applications. Spot-market pricing fluctuations compress margin stability for mid-tier assemblers dependent on non-contract sourcing.
- Composite:Glass-reinforced thermoplastic formulations displace bronze in mid-range recreational segments on weight and galvanic compatibility grounds. Multi-material hull assemblies specify these to eliminate electrolytic corrosion between dissimilar metals.
- Plastic:Injection-molded housings serve cost-engineered freshwater and light-duty marine applications. Asian-Pacific recreational builders specify these for price-sensitive electric models.
- Bronze:Traditional cast alloys retain niche specification where historical marine standards persist. Legacy vessel maintenance programs sustain residual demand despite composite displacement trends.
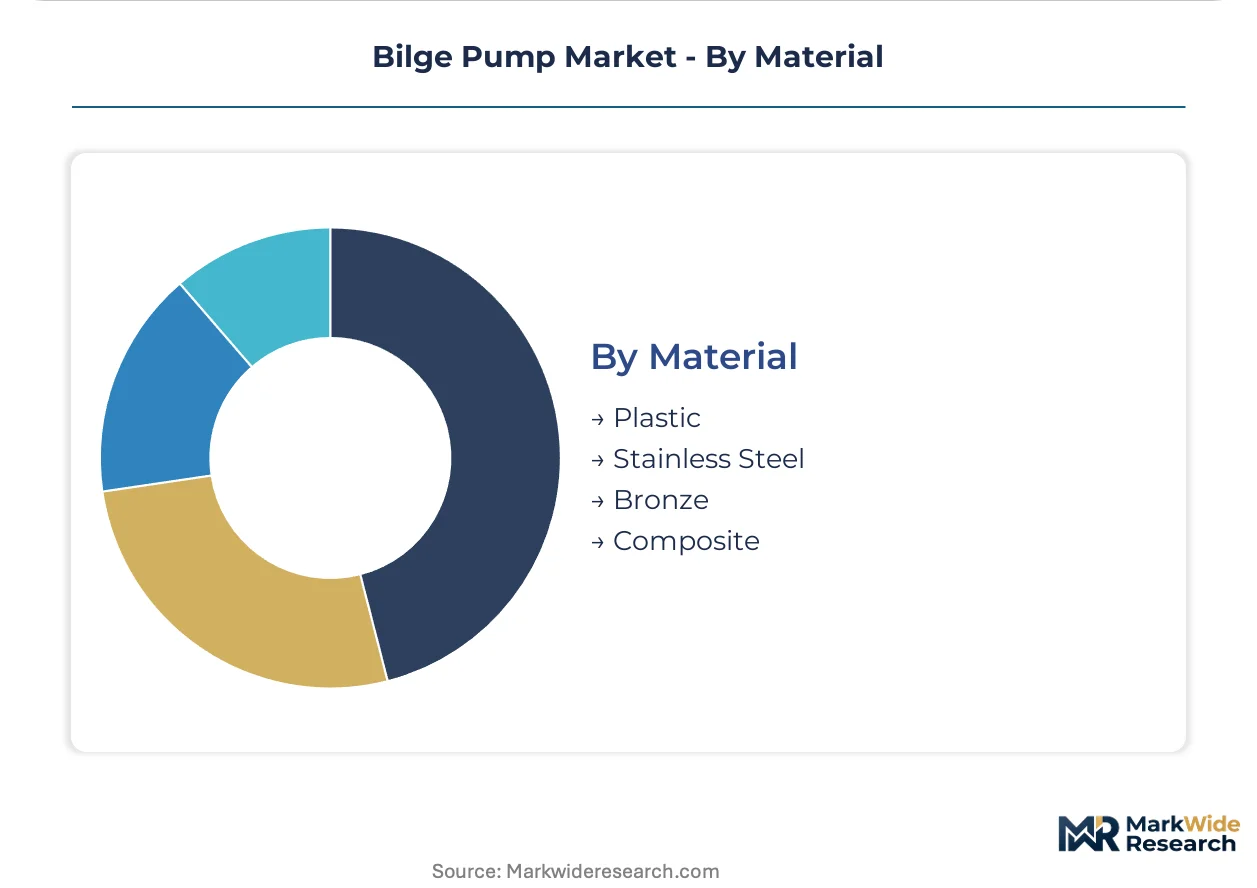
Stainless steel holds the largest share; composites are gaining share fastest as weight reduction priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal corridor underwrites Egypt's maritime logistics centrality, channeling Mediterranean-Red Sea traffic through the Bilge Pump Market's busiest commercial artery. Port infrastructure upgrades at Alexandria and Damietta drive specification demand for corrosion-resistant evacuation systems.
United States
Commercial fishing fleets operating from New Bedford, Massachusetts and Seattle, Washington require automatic bilge systems compliant with US Coast Guard 46 CFR subchapter standards. EPA vessel discharge regulations mandate oil-water separation compatibility. Gulf Coast shipyards in Louisiana concentrate retrofit activity for offshore supply vessels.
Germany
Industrial dewatering expertise from Ruhr Valley pump manufacturers migrates into marine applications through controlled distribution partnerships. CE marking under EU Marine Equipment Directive governs product launch timelines. Hamburg port cluster anchors North Sea commercial vessel specification activity.
Italy
Mediterranean recreational boatbuilders in Lombardy and Veneto consolidate vendor lists to three approved pump platforms per hull category. F-Gas Regulation phase-down schedules accelerate sealed-motor specifications. Viareggio yacht construction district drives premium automatic submersible procurement.
Turkey
Coastal manufacturing clusters around Izmir and Istanbul capture disproportionate European OEM supply share through integrated logistics hubs. MDR compliance requirements filter uncertified suppliers from EU-bound exports. Tuzla shipyard complex concentrates commercial vessel pump installation capacity.
Greece
Island ferry electrification mandates on Piraeus-Cyclades routes open specification windows for high-efficiency electric pump packages. Domestic short-sea zero-emission auxiliary requirements reshape procurement priorities. Perama ship repair zone concentrates technician scarcity challenges for IP68 sealing validation.
Bilge Pump Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base organizes around three strategic tiers: Danish and German engineering heritage anchors premium commercial marine positioning; Asia-Pacific cost-engineered specialists capture recreational volume; diversified industrial conglomerates leverage cross-sector dewatering expertise. Competitive moves concentrate on vendor list consolidation by major boatbuilders and sealed-motor certification racing against EU regulatory deadlines.
Among heritage-engineering specialists, DESMI and Johnson Pump occupy positions exemplifying premium-tier commercial marine focus. SEAFLO represents the cost-engineered electric model segment serving Asia-Pacific recreational builders. Xylem anchors the industrial-to-marine crossover archetype, extending dewatering capabilities through controlled distribution partnerships with major shipyards.
| Leading Market Players |
|---|
| Whale Pumps |
| DESMI |
| Rule Industries |
| Pentair Shurflo |
| Xylem |
| Johnson Pump (SPX Flow) |
| SEAFLO |
| Vetus |
| Attwood Marine (Brunswick Corporation) |
| Others |
Value Network & Pricing Analysis
Marine-grade 316L alloy spot-market volatility determines both margin compression in mid-tier pump assembly and the geographic clustering of European OEM supply around Turkish coastal manufacturing hubs. Stainless steel input fluctuations compress pricing power for non-contract assemblers while elevating premium-tier spreads for vertically integrated heritage suppliers.
Pricing Analysis
Volume-discount tiering separates sealed-motor automatic systems from manual backup units across Mediterranean recreational builder procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in economy electric models intensifies as Asian-Pacific manufacturers consolidate vendor lists. Charter fleet operators exhibit highest price sensitivity; offshore supply vessel operators prioritize maintenance-interval reliability over unit cost.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules act as export-control chokepoints limiting sealed-motor technology flows to non-compliant assemblers. Manufacturing gravity centers on Turkey, Italy, and Greece for European-bound production, with China anchoring cost-engineered electric assembly for Asia-Pacific recreational demand. Supply chains draw from marine-grade 316L alloy spot markets, glass-reinforced thermoplastic resin systems, and brushless DC motor component streams. Single-source vulnerability concentrates in Turkish Izmir-Istanbul coastal clusters. Distribution runs through direct OEM supply contracts displacing traditional chandlery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor list consolidation by major Mediterranean boatbuilders signals platform-economics inflection, with interoperability demands around ISO 15083 certification creating winner-take-most dynamics.
For Market Incumbents: Insulate premium positioning through captive supply of corrosion-resistant alloy castings and accelerated sealed-motor certification racing against EU F-Gas deadlines. Defend against cost-engineered Asian-Pacific entrants by locking three-platform vendor status with Tuzla and Viareggio shipyard complexes. For New Entrants and Emerging Players: Greek island ferry electrification mandates represent the most penetrable entry point for high-efficiency electric pump packages without legacy 12V system baggage. Southeast Asian aquaculture solar-powered installations offer second white-space target. Pursue direct OEM supply contracts rather than aftermarket chandlery distribution to bypass incumbent channel control. For Investors and Strategic Acquirers: EU Marine Equipment Directive notified body backlogs reshaping the acquisition landscape toward targets with existing CE marking infrastructure. Five-to-ten year viability favors vertically integrated specialists with in-house IP68 sealing validation capability. Watch Italian and Croatian marine electrical technician scarcity as inflection signal for service-network-dependent valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed-Motor Certification Investment | Preempts EU F-Gas Regulation phase-down deadlines for commercial fishing fleet compliance. |
| Backward Integration into Alloy Casting | Captures margin from marine-grade 316L volatility while securing supply continuity. |
| Direct OEM Supply Contract Expansion | Displaces chandlery intermediaries as Turkish production hubs consolidate vendor lists. |
| Outcome-Based Maintenance Partnership | Converts pump replacement into recurring revenue streams with commercial fleet operators. |
| Solar-Powered Product Line Extension | Addresses Southeast Asian aquaculture generator-elimination specifications. |
Research Methodology
Initial hypotheses were tested against primary input from marine equipment procurement managers, shipyard engineering directors, aftermarket service technicians, and regulatory compliance officers, then refined against customs trade data, EU Marine Equipment Directive filing records, class-society certification databases, and SEC filings from diversified industrial conglomerates. Bottom-up vessel fleet analysis and top-down macroeconomic triangulation anchored volume estimates.
Demand-supply-balance framing modeled bilge pump procurement across automatic, submersible, manual, and diaphragm type categories; electric, solar, hydraulic, and pneumatic power architectures; marine, recreational, industrial, and commercial applications; and stainless steel, composite, plastic, and bronze material tiers. CAGRs derived from replacement cycle compression analysis and regulatory mandate timing across the projection horizon. Flag-state electrification mandates and ballast water management crossover threats served as scenario inputs.
Stress conditions across stainless steel alloy pricing bands, Turkish manufacturing cluster disruption, and CE marking timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet replacement cycle timing. Material shifts in EU F-Gas Regulation implementation schedules or major flag-state electrification mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Global Seismic Vessels Market