
 Asia-Pacific Offshore Crane Market | 2026-2036
Asia-Pacific Offshore Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Offshore Crane Market Outlook
Electrification of drive systems is tilting the Asia-Pacific offshore crane technology stack toward hybrid and all-electric architectures. Huisman Equipment B.V. leverages its Dutch-Asian engineering footprint to dominate deepwater heavy-lift specifications. Liebherr Group anchors high-capacity platform crane production through its Singapore and China manufacturing bases. Konecranes competes on port-to-offshore technology transfer, while Haoyo Group specializes in cost-optimized mobile units for China's domestic fleet.
Asia-Pacific offshore cranes are heavy-lifting machines engineered for marine environments, typically rated above 50 tonnes with active heave compensation and corrosion-resistant steel construction, designed to transfer equipment, personnel, and subsea modules between vessels and fixed or floating structures. Platform cranes occupy the largest installed base across aging oil and gas infrastructure, while floating crane systems represent the fastest-growing category as Southeast Asian offshore wind projects multiply. Electric and hybrid technology segments command premium positioning due to fuel efficiency mandates, whereas hydraulic systems retain cost advantages in decommissioning and salvage applications where duty cycles are intermittent.
METI in Japan and China's MEE enforce escalating emission and safety standards that disqualify legacy hydraulic fleets from new project tenders, while Australia's national offshore safety regulator mandates third-party certification for all lifting operations in Commonwealth waters. South Korea's KOSHA frameworks and Taiwan's offshore wind auction rules further fragment compliance requirements across the region. Stakeholders must track how each national certification regime treats hybrid technology qualifications before committing capital to regional manufacturing or service networks.
Market Dynamics
Electrification mandates from Japan's METI and China's MEE are compressing the technology lifecycle for hydraulic crane fleets across Southeast Asian oil and gas infrastructure.
Growth Catalysts
- Offshore wind procurement acceleration:Vietnam and Taiwan auction rules mandate heavy-lift capacity thresholds that favor new electric-hybrid crane installations over refurbished hydraulic units.
- Dual carbon compliance deadlines:China's MEE emission standards disqualify legacy diesel-hydraulic systems from new tender eligibility, forcing fleet replacement cycles.
- Australia's maintenance backlog:Aging North West Shelf and Bass Strait platforms require specialized platform crane refurbishment and active heave compensation upgrades.
Market Restraints
- High-grade steel input volatility:Corrosion-resistant alloy plate prices fluctuate with nickel and molybdenum supply disruptions from Indonesian smelter consolidation.
- Certification fragmentation:Taiwan's offshore wind auction rules, South Korea's KOSHA frameworks, and Australia's NOPSEMA requirements create incompatible testing protocols for hybrid drive systems.
- Skilled technician scarcity:Deepwater crane commissioning requires certified riggers and electrical specialists concentrated in Singapore and Busan shipyard clusters.
Strategic Opportunities
- Philippines offshore wind pre-development:Early-stage lease rounds lack established heavy-lift supply chains, creating first-mover positioning for mobile fleet operators.
- Retrofit hybridization packages:Converting existing platform cranes to electric-hybrid drive extends asset life while meeting METI efficiency mandates.
- Subsea module installation growth:Floating crane demand multiplies as Vietnam and Taiwan wind farms require jacket foundation and turbine component lifts.
Industry Challenges
- Active heave compensation calibration:Real-time sensor integration with legacy vessel motion reference units demands specialized marine software engineers scarce in regional labor pools.
- Multi-jurisdiction certification timelines:Obtaining simultaneous KOSHA, NOPSEMA, and Taiwan Bureau of Energy approvals extends project mobilization schedules.
- Spare parts inventory fragmentation:Hydraulic component obsolescence and electric drive proprietary architectures force operators to maintain dual stocking strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Offshore Crane Market |
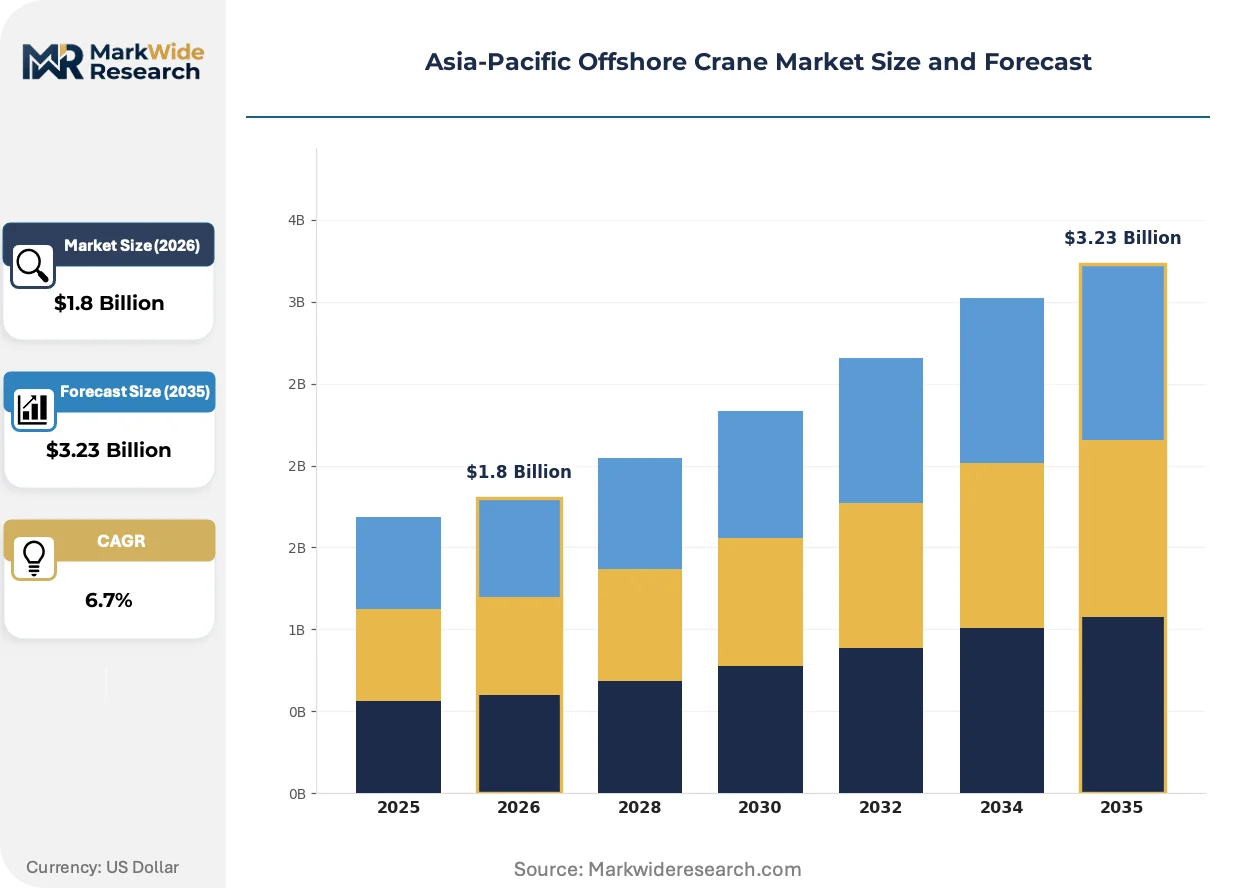
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floating, Platform, Fixed, Mobile Application: Construction, Maintenance, Decommissioning, Salvage End User: Oil & Gas, Renewable Energy, Marine Services, Mining Technology: Hydraulic, Electric, Pneumatic, Hybrid |
| Companies Covered | Liebherr Group, Heila Cranes SpA, Huisman Equipment B.V., Sparrows Offshore Group Limited, Konecranes, Haoyo Group, Robinson Equipment Limited, Tytan Marine Inc, Deyuan Marine, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Offshore Crane Market Strategic Shifts
Drive system architecture is the primary battleground as regional emission standards tighten and offshore wind developers demand fuel-efficient heavy-lift capacity.
Variable frequency drive technology with regenerative braking is hybridizing the Asia-Pacific offshore crane technology stack. Japanese floating production operators and Taiwanese wind farm developers are specifying electric-hybrid systems for all newbuild orders. This shift is compressing demand for conventional hydraulic power units while expanding the addressable market for battery-hybrid retrofit packages.
METI efficiency mandates and China's MEE emission standards are disqualifying pure hydraulic cranes from new project tenders. Equipment buyers must now demonstrate compliance with tiered carbon intensity thresholds to qualify for Japanese and Chinese state-backed financing. Platform crane operators in Australia's North West Shelf are responding by accelerating depreciation schedules for pre-2020 hydraulic assets.
Charter contracts now specify fuel consumption guarantees and emission intensity caps rather than day-rate pricing alone. Offshore wind developers in Vietnam and Taiwan are unbundling crane provision from vessel charter, creating standalone equipment lease markets. This pattern is most visible in the Taiwan Strait, where specialized heavy-lift vessel operators compete directly with integrated offshore construction contractors.
Asia-Pacific Offshore Crane Market Segmentation
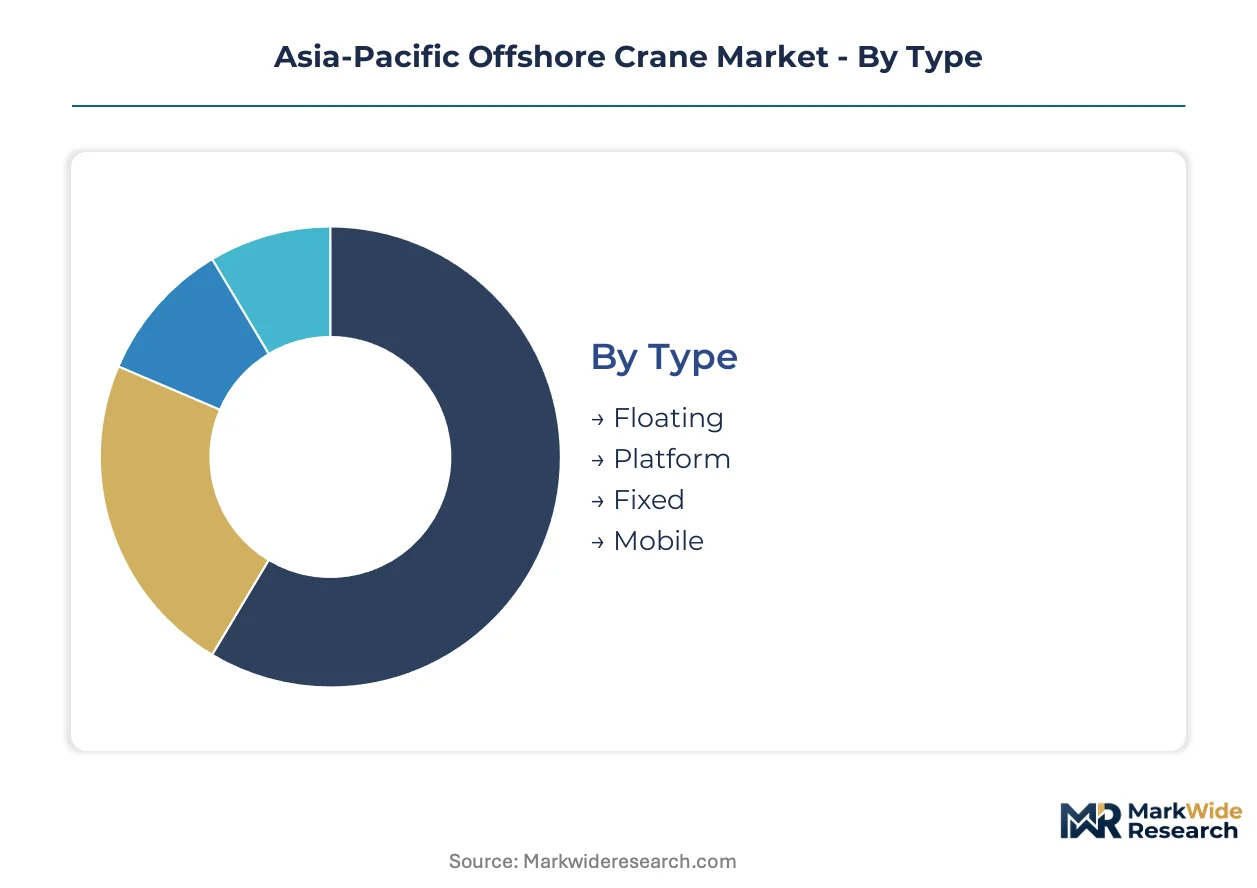
Offshore crane procurement in the Asia-Pacific region fragments across vessel-mounted configurations, operational duty cycles, and powertrain architectures. Each segmentation dimension carries distinct certification requirements and capital intensity profiles that shape tender eligibility across Vietnamese wind farms, Australian maintenance contracts, and Japanese platform retrofits.
Type:
Cost tier differentiation separates vessel-integrated systems from permanently installed infrastructure, with mobility premiums commanding distinct procurement channels.
- Floating:Heavy-lift vessels with dynamic positioning integrate cranes exceeding 1,000-tonne capacity for subsea module installation. Vietnam and Taiwan offshore wind developers are unbundling crane provision from vessel charter, creating standalone lease markets for these units.
- Platform:Permanently mounted on fixed offshore structures with active heave compensation for transfer operations. Australia's North West Shelf and Bass Strait maintenance backlog sustains refurbishment demand for aging installed base units.
- Fixed:Stationary boom configurations on jacket foundations and FPSO hulls. Japanese floating production operators specify these for predictable load cycles.
- Mobile:Self-propelled units for rapid deployment across multiple lease blocks. Philippine offshore wind pre-development rounds lack established supply chains, creating positioning opportunities for these assets.
Platform cranes hold installed capacity across aging oil and gas infrastructure. Floating systems are rotating up the share rankings as Southeast Asian offshore wind projects multiply.
Application:
Maturity stages across the offshore asset lifecycle create divergent technology specifications, from precision installation to intermittent salvage duty.
- Construction:Heavy-lift operations for jacket foundation placement and turbine component assembly. Taiwan's offshore wind auction rules mandate capacity thresholds that favor new electric-hybrid crane installations.
- Maintenance:Routine equipment transfer and platform crane refurbishment. Australia's NOPSEMA mandates third-party certification for all lifting operations in Commonwealth waters.
- Decommissioning:Reverse installation of subsea infrastructure with intermittent duty cycles. Hydraulic systems retain cost advantages here where fuel efficiency mandates are less stringent.
- Salvage:Emergency recovery and wreck removal operations. South Korea's KOSHA frameworks govern certification for these high-risk deployments.
Maintenance commands recurring revenue visibility. Construction is climbing the fastest as Vietnam and Taiwan auction volumes accelerate.
End User:
Customer type concentration determines specification rigor, with state-backed renewable developers imposing stricter emission standards than marine service contractors.
- Oil & Gas:Legacy platform operators in Australia's North West Shelf accelerating depreciation schedules for pre-2020 hydraulic assets under China's MEE emission standards influence.
- Renewable Energy:Offshore wind farm developers in Vietnam and Taiwan specifying fuel consumption guarantees and emission intensity caps in charter contracts.
- Marine Services:Third-party vessel operators competing directly with integrated offshore construction contractors in the Taiwan Strait.
- Mining:Deep-sea mineral exploration support with specialized subsea module handling requirements.
Oil and gas retains the largest installed base. Renewable energy is gaining share fastest as dual carbon compliance deadlines force fleet replacement cycles.
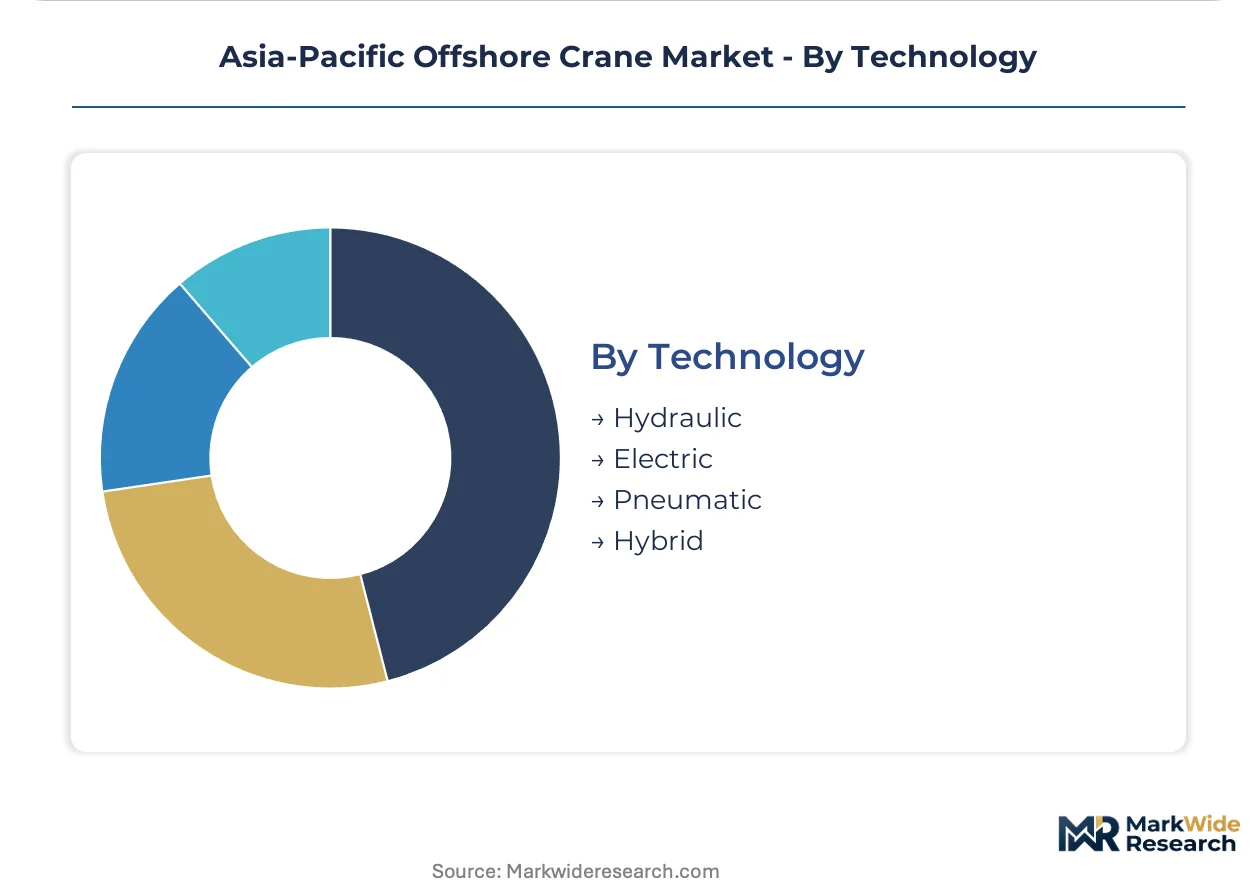
Technology:
Powertrain architecture defines competitive positioning as METI efficiency mandates and China's MEE emission standards compress the technology lifecycle for conventional hydraulic fleets.
- Hydraulic:Conventional diesel-powered systems with established maintenance networks. Legacy fleets face disqualification from new Japanese and Chinese state-backed financing eligibility.
- Electric:Variable frequency drive systems with regenerative braking specified by Taiwanese wind farm developers for all newbuild orders.
- Pneumatic:Compressed air actuation for explosion-risk environments on certain platform configurations.
- Hybrid:Battery-electric retrofit packages extending asset life while meeting METI mandates. Japanese floating production operators and Taiwanese developers are specifying these for new installations.
Hydraulic systems retain cost advantages in decommissioning and salvage applications. Hybrid configurations are expanding most quickly as tiered carbon intensity thresholds become tender prerequisites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards export floating crane systems to Vietnamese offshore wind developers, establishing the dominant trade-flow corridor for heavy-lift marine equipment across Southeast Asia.
China
Domestic fleet operators are replacing pre-2020 hydraulic cranes to comply with MEE emission standards that now govern state-backed financing eligibility. The dual carbon goals are accelerating depreciation schedules for legacy diesel-hydraulic assets. Manufacturing concentrates in the Yangtze River Delta, where Haoyo Group and domestic fabricators supply cost-optimized mobile units for coastal construction.
Japan
Floating production operators are specifying hybrid drive systems for all newbuild orders under METI efficiency mandates that disqualify pure hydraulic configurations. The country's offshore maintenance sector demands active heave compensation upgrades for aging platform infrastructure. Industrial activity clusters around Nagoya and Yokohama, where engineering firms calibrate sensor integration with vessel motion reference units.
South Korea
Shipyard clusters in Busan and Ulsan dominate fabrication of heavy-lift vessels exceeding 1,000-tonne capacity for export to Taiwan Strait wind projects. KOSHA frameworks govern certification for high-risk salvage and decommissioning deployments. Domestic operators face skilled technician scarcity as deepwater crane commissioning requires electrical specialists concentrated in these southeastern industrial zones.
Australia
Aging North West Shelf and Bass Strait platforms are driving specialized platform crane refurbishment demand under NOPSEMA third-party certification requirements for all Commonwealth waters lifting operations. The maintenance backlog sustains recurring revenue for active heave compensation upgrades. Service providers concentrate in Perth and Melbourne, where offshore construction contractors coordinate with Singapore-based rigging specialists.
Vietnam
Offshore wind auction rules mandate heavy-lift capacity thresholds that favor new electric-hybrid crane installations over refurbished hydraulic units. Developers are unbundling crane provision from vessel charter, creating standalone equipment lease markets. Pre-development activity concentrates in southern coastal provinces, where mobile fleet operators position assets ahead of formal lease round awards.
Asia-Pacific Offshore Crane Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers differentiated by engineering depth and geographic reach. European-headquartered specialists with Asian manufacturing footprints dominate deepwater heavy-lift specifications, while regional fabricators compete on cost-optimized mobile units for domestic fleet replacement. The competitive dynamic centers on technology licensing partnerships and backward integration into corrosion-resistant steel supply chains.
Among European-Asian engineering groups, Liebherr Group and Huisman Equipment B.V. exemplify the premium-tier archetype with integrated manufacturing across Singapore, China, and continental European design centers. Konecranes occupies a position bridging port automation technology transfer and offshore heavy-lift applications. Haoyo Group represents the cost-optimized domestic specialist segment serving China's internal fleet replacement cycle under MEE emission mandates.
| Leading Market Players |
|---|
| Liebherr Group |
| Heila Cranes SpA |
| Huisman Equipment B.V. |
| Sparrows Offshore Group Limited |
| Konecranes |
| Haoyo Group |
| Robinson Equipment Limited |
| Tytan Marine Inc |
| Deyuan Marine |
| Others |
Value Chain & Pricing Dynamics
Busan-to-Ho Chi Minh City heavy-lift vessel charter rates transmit cost volatility directly into crane lease pricing tiers, compressing margins for operators without captive fabrication capacity while amplifying differentiation premiums for hybrid-electric fleet owners serving Vietnamese wind developers.
Pricing Analysis
Next-generation electric-hybrid crane configurations command 25-40% lease rate premiums over prior-generation hydraulic units, while refurbished pre-2020 assets face residual value collapse under China's MEE emission standards. Price differentiation hinges on KOSHA certification tier and active heave compensation specification grade, with Taiwanese wind farm developers showing lowest price sensitivity due to unbundled procurement mandates. Cost compression in the hydraulic refurbishment tier is intensifying because Indonesian nickel smelter consolidation disrupts corrosion-resistant alloy plate supply.
Supply Chain Analysis
Contract manufacturing for offshore crane drive systems concentrates in South Korean shipyard clusters around Busan and Ulsan, with secondary capacity in Singapore's Jurong marine engineering corridor. Raw material dependencies center on Indonesian nickel-molybdenum alloy plate, German-engineered variable frequency drives, and Chinese-manufactured battery cells for hybrid retrofit packages. Single-source vulnerability in active heave compensation sensor modules sourced from Japanese precision engineering houses creates procurement risk. Distribution runs through Singapore-based equipment lessors coordinating with Australian maintenance contractors and Vietnamese wind farm developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific offshore crane demand sits in early-cycle expansion as Vietnam and Taiwan offshore wind auction volumes force fleet replacement timelines faster than regional supply capacity can respond.
For Market Incumbents: Build certification moats by securing simultaneous KOSHA, NOPSEMA, and Taiwan Bureau of Energy approvals for hybrid drive systems before competitors complete multi-jurisdiction testing protocols. Anchor fabrication capacity in Busan shipyard clusters to capture South Korean export demand for Taiwanese wind projects. Defend against Chinese domestic fabricators by licensing European active heave compensation technology rather than developing proprietary architectures. For New Entrants and Emerging Players: Pursue Philippine offshore wind pre-development positioning before established mobile fleet operators deploy assets to southern coastal provinces. Target maintenance retrofit contracts for Australia's North West Shelf platform crane installed base, where NOPSEMA certification requirements create barriers for unqualified competitors. Enter through joint venture with Singapore-based rigging specialists who control scarce commissioning technician pools. For Investors and Strategic Acquirers: Carve-out targets emerge from European engineering groups seeking to monetize Asian manufacturing footprints amid energy transition capital reallocation. Five-to-ten year viability favors operators with hybrid technology licensing rights and established corrosion-resistant steel supplier relationships rather than pure fabrication assets. Monitor Taiwan Strait vessel charter rate spreads as early inflection indicator for lease market pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Drive System Certification | Simultaneous KOSHA and NOPSEMA approvals unlock Australian and South Korean tender eligibility. |
| Backward Integration into Alloy Supply | Captive nickel-molybdenum plate sourcing insulates margins from Indonesian smelter consolidation volatility. |
| Mobile Fleet Positioning | Early deployment to Philippine coastal provinces secures first-mover advantage before lease round formalization. |
| Active Heave Compensation Licensing | European technology partnerships accelerate Japanese floating production operator specifications. |
| Technician Training Consortium | Singapore-Busan certification programs address skilled rigger scarcity constraining deepwater commissioning. |
Study Parameters
Desk research of customs trade databases, shipyard order books, and national offshore wind auction filings preceded structured interviews with crane fleet operators, shipyard procurement directors, and marine engineering consultants. Primary fieldwork captured installation specifications from Vietnamese wind developers and Australian maintenance contractors, validated against secondary analysis of KOSHA certification records and Taiwan Bureau of Energy tender documents. Bottom-up crane deployment counts triangulated against top-down vessel charter market value estimates.
Assumptions held fixed include METI efficiency mandate enforcement timelines and Chinese MEE emission standard eligibility criteria, while variables included nickel alloy price trajectories and Philippines lease round acceleration scenarios. Segmentation modeling spanned crane type, powertrain architecture, application duty cycle, and end-user industry across the projection horizon. CAGRs derived from installed base replacement schedules and newbuild order intake patterns, with specific inputs from active heave compensation upgrade penetration rates and hybrid retrofit package adoption curves.
Sensitivities concentrate around Indonesian nickel export policy shifts and Taiwan Strait geopolitical risk premiums affecting vessel charter availability. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and shipyard capacity expansion timelines. Quarterly review of Busan-Ulsan shipyard order backlogs and Vietnamese wind farm financial closure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Offshore Pipeline Market