
 Middle East Offshore Crane Market | 2026-2036
Middle East Offshore Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Offshore Crane Market Foresight
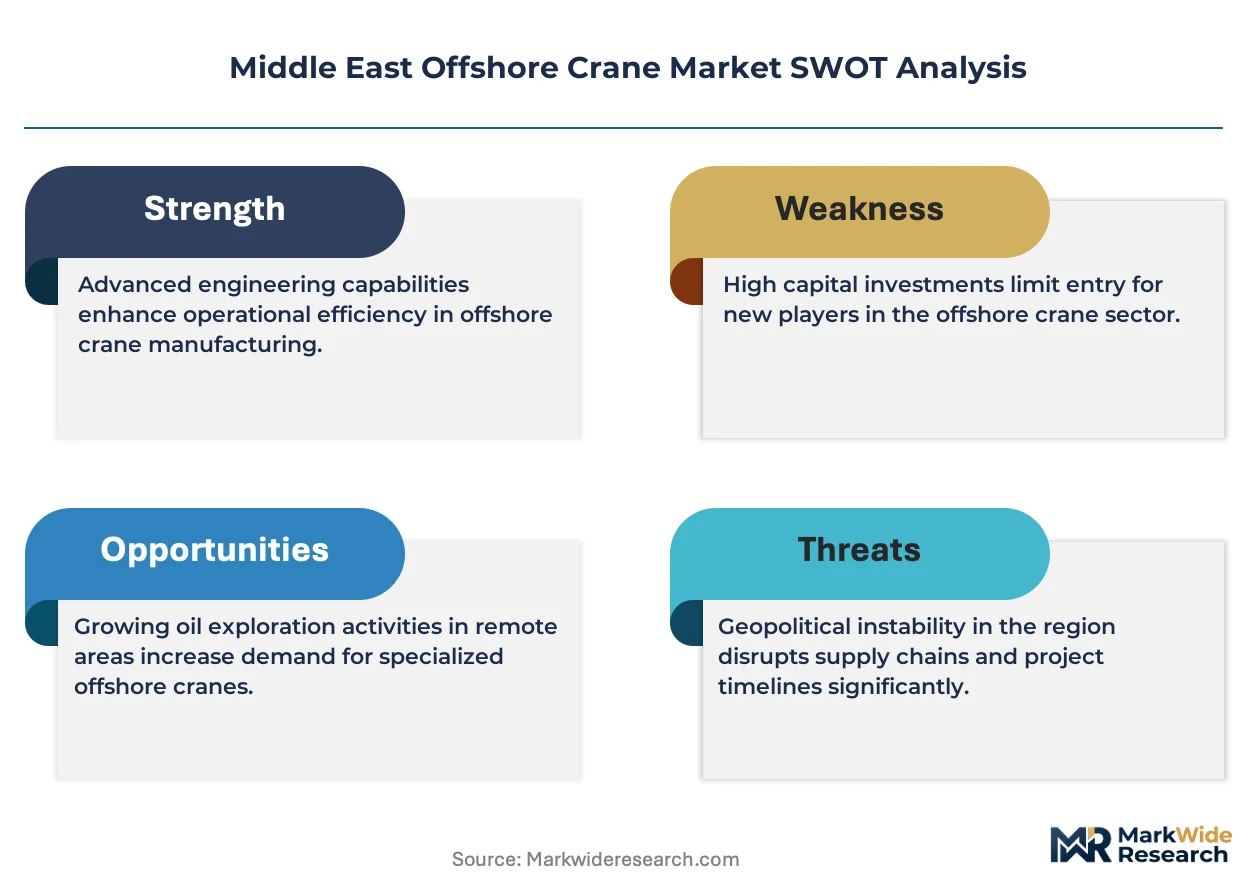
The capital-intensity divergence between integrated crane manufacturers and rental-dependent contractors is unwinding competitive dynamics across the Middle East. NOV Inc leverages its rig-integrated lifting systems to anchor deepwater project portfolios in the Arabian Gulf. Liebherr Group sustains manufacturing scale advantages through its Rostock facility, while Sparrows Offshore Group Limited competes on specialized maintenance and subsea deployment capabilities.
Offshore cranes are heavy-lifting machines engineered for marine environments, typically rated between 50 and 5,000 metric tons and built with corrosion-resistant alloys to withstand saltwater exposure and dynamic vessel motion. These systems transfer personnel, equipment, and subsea modules between vessels, platforms, and seabed installations across oilfield and renewable energy operations. Knuckle boom crane configurations dominate shallow-water maintenance where space constraints limit boom sweep, while floating crane systems capture margin pools in decommissioning and topside integration projects. Oilfield services firms favor project-based deployment models that match crane availability to well-completion schedules, whereas renewable energy firms increasingly specify all-terrain units for coastal wind farm staging.
Saudi Arabia's local content mandates from the Ministry of Energy and the country's national petroleum company require offshore crane suppliers to meet escalating domestic value-add thresholds. The UAE's civil defense and maritime safety codes, administered by the country's federal transport authority, enforce load-testing protocols that extend equipment certification cycles. Stakeholders must weigh fixed-asset commitments against the flexibility of rental and on-demand deployment structures as project pipelines fluctuate.
Market Dynamics
Saudi Aramco's In-Kingdom Total Value Add program is forcing offshore crane suppliers to restructure manufacturing footprints and joint-venture arrangements, compressing margins for foreign OEMs while creating captive demand for locally assembled lifting systems.
Growth Catalysts
- Red Sea coastal development:Saudi Arabia's giga-project pipeline requires heavy-lift marine infrastructure for artificial islands and offshore hospitality platforms, pulling demand for 1,000+ ton capacity units.
- SFDA equipment certification harmonization:Saudi Arabia's national regulator is streamlining type-approval processes for corrosion-resistant alloy components, reducing time-to-deployment for European and Asian crane systems.
- Subsea tieback engineering:Extended-reach drilling from existing platforms is displacing newbuild rig demand and concentrating lift requirements on intervention and maintenance fleets.
Market Restraints
- Specialized alloy input volatility:Nickel-molybdenum-chromium formulations for offshore-rated booms face price swings tied to Indonesian and Philippine ore export quotas.
- Fab yard concentration:Heavy-lift vessel construction clusters in South Korea and Singapore, creating single-source dependency for Middle East project timelines.
- Dynamic positioning system technical limitation:Current generation thruster controls struggle with combined crane load and Gulf current vectors above Beaufort scale 6.
Strategic Opportunities
- UAE offshore wind staging:Abu Dhabi and Dubai maritime zones lack dedicated marshalling infrastructure for floating turbine installation, creating first-mover advantage for mobile heavy-lift operators.
- IKTVA regulatory tailwind:Saudi Arabia's escalating domestic value-add thresholds reward joint-venture manufacturing with preferential tender scoring on Aramco and PIF-backed projects.
- Digital twin and predictive maintenance convergence:Real-time structural monitoring integrated with OEM service networks is compressing unplanned downtime and enabling performance-guarantee contracting.
Industry Challenges
- Offshore crane operator certification timeline:MOHAP in the UAE and Saudi Arabia's Technical and Vocational Training Corporation maintain non-harmonized competency frameworks, fragmenting crew mobility across Arabian Gulf projects.
- Legacy platform integration complexity:New knuckle-boom systems must interface with 1980s-era pedestal foundations on Saudi Safaniya and UAE Upper Zakum fields, requiring custom engineering that erodes standardization economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Offshore Crane Market |
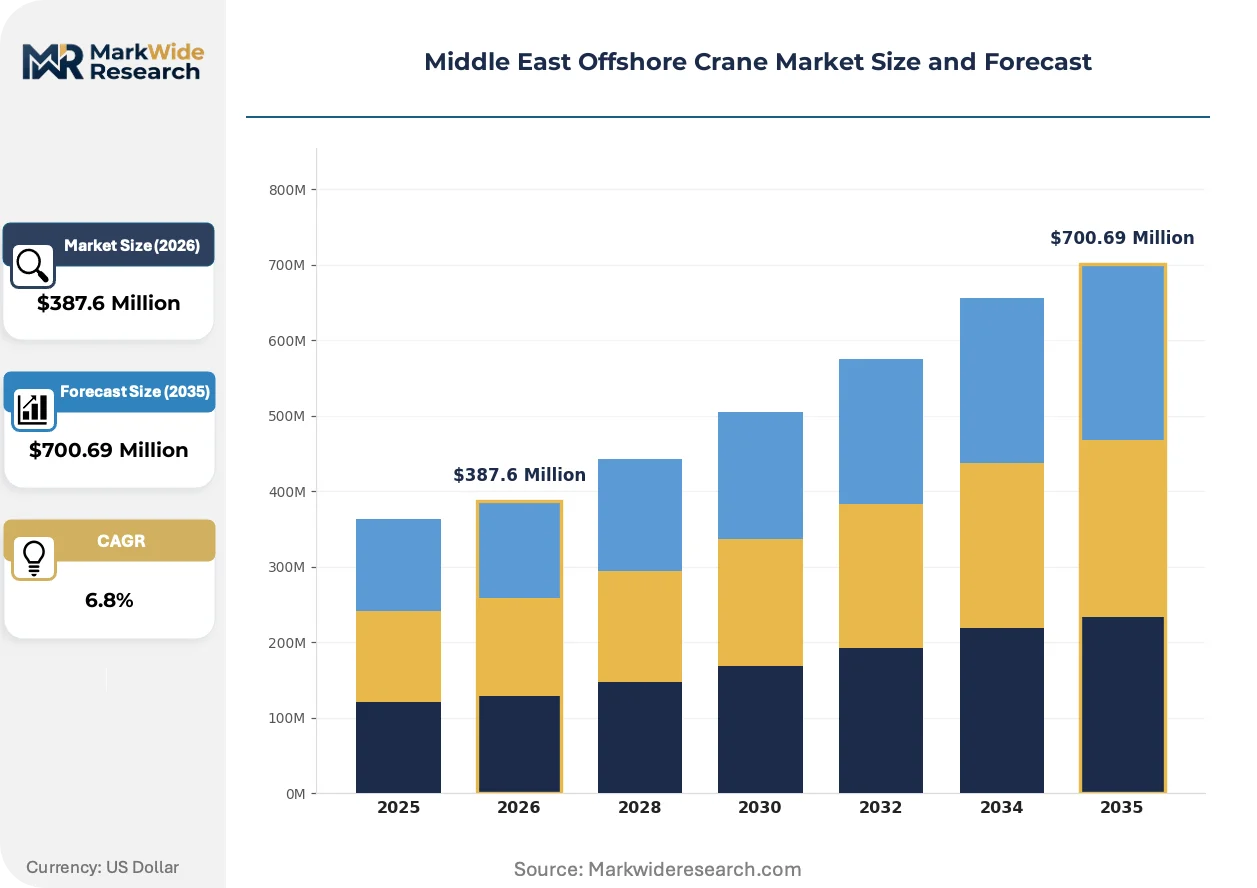
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floating Crane, All-Terrain Crane, Knuckle Boom Crane, Rough Terrain Crane Application: Offshore Construction, Oil & Gas Exploration, Marine Salvage, Wind Farm Installation Deployment: On-Demand, Project-Based, Contractual, Rental End User: Marine Contractors, Oilfield Services, Renewable Energy Firms, Shipping Companies |
| Companies Covered | NOV Inc, Liebherr Group, Kenz Figee Group B.V., Heila Cranes S.p.A., Sparrows Offshore Group Limited, Konecranes Plc, Cargotec Corporation, Terex Corporation, Palfinger AG, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Offshore Crane Market Shifts & Advancements
Active heave compensation and autonomous load handling are compressing the skill premium for offshore crane operations while extending operational weather windows in the Arabian Gulf's summer high-temperature periods.
Electrification of auxiliary crane systems is displacing hydraulic powerpack architectures on newbuild offshore support vessels. Saudi Aramco's marine division specifies all-electric auxiliary drives for its 2025+ fleet renewal, citing reduced fire risk and maintenance intervals. This shift is compressing demand for traditional hydraulic component suppliers and redirecting procurement toward integrated motor-drive vendors with marine certification.
SFDA and MOHAP are converging on unified load-testing protocols for subsea deployment equipment, eliminating the prior dual-certification burden for suppliers operating across Saudi Arabia and UAE maritime zones. The harmonized framework accelerates equipment rotation between Red Sea and Arabian Gulf projects. European OEMs with existing EU-type examination documentation capture fastest approval timelines under mutual recognition principles.
Charter-rate volatility is compressing contractor appetite for owned crane assets and expanding the addressable market for bareboat and fully-crewed rental structures. Saudi offshore construction firms now specify availability-based contracts with uptime penalties, transferring operational risk to equipment lessors. This pattern is most visible in Saudi Arabia's Red Sea developments where project phasing uncertainty discourages capital deployment.
Middle East Offshore Crane Market Segmentation
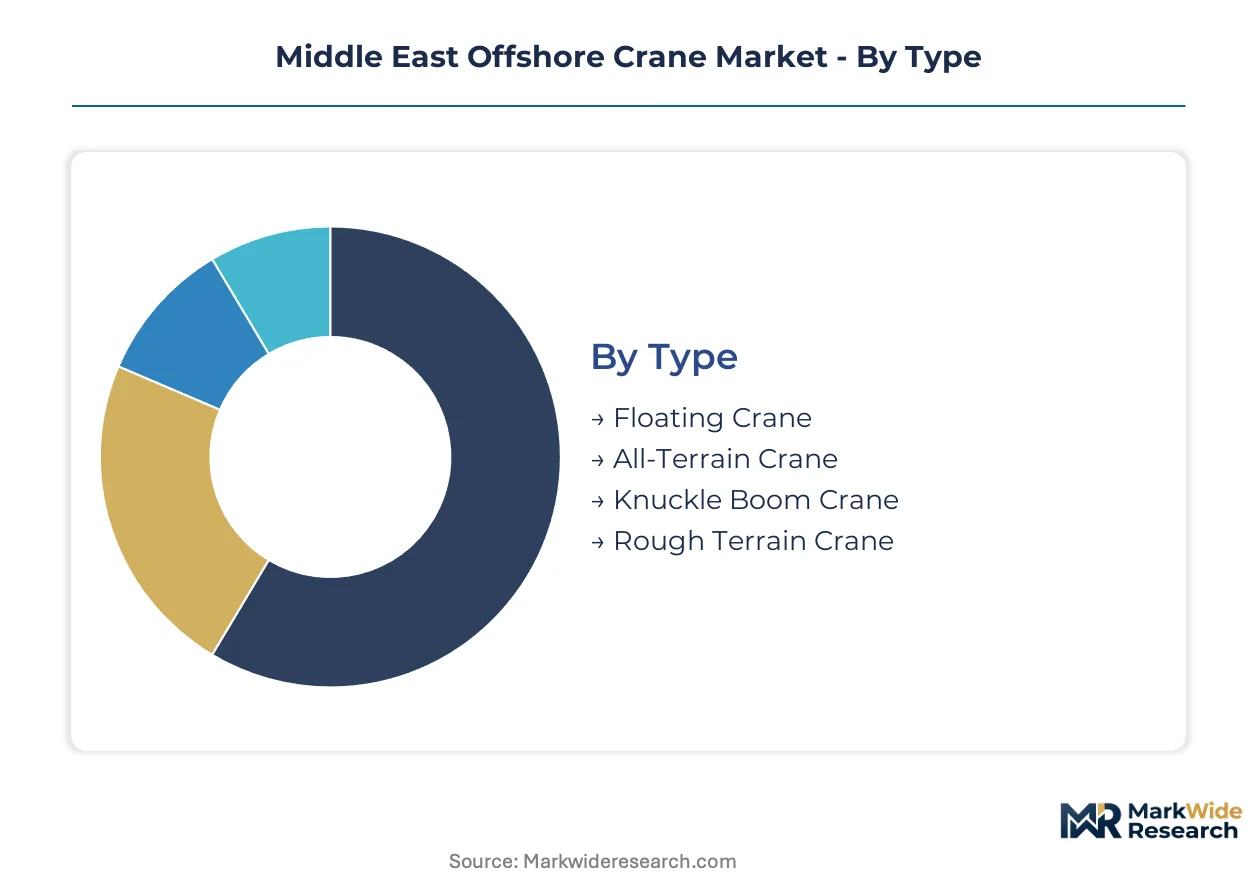
Crane specification and deployment structure determine procurement economics across Saudi Arabia's Red Sea giga-projects and UAE offshore construction zones. Equipment mix varies sharply between Aramco-contracted oilfield services and PIF-backed coastal developments.
Type:
Channel distribution splits between OEM direct sales for large-capacity units and rental fleet operators for mid-range maintenance fleets.
- Floating Crane:Heavy-lift vessels rated above 1,000 metric tons anchor decommissioning and topside integration contracts. Demand concentrates in UAE offshore zones where Upper Zakum field upgrades require combined crane and dynamic positioning capability.
- Knuckle Boom Crane:Articulated boom systems with compact footprint dominate platform maintenance where pedestal space constraints limit boom sweep. Saudi Arabia's Safaniya and Manifa field intervention fleets specify these units for 24-hour turnaround operations.
- All-Terrain Crane:Self-propelled units with multi-axle mobility serve coastal wind farm staging and onshore marshalling yards. Abu Dhabi Ports specifications favor 500-ton capacity models for turbine component handling.
- Rough Terrain Crane:Outrigger-stabilized crawlers access unmaintained coastal construction sites. Dubai's artificial island developments deploy these for causeway and breakwater rock placement.
Knuckle boom systems dominate installed base across existing Saudi offshore platforms. Floating crane capacity is where expansion concentrates for Red Sea hospitality and industrial island construction.
Application:
Cost tier stratification separates capital-intensive newbuild construction from recurring maintenance expenditure cycles.
- Offshore Construction:Heavy-lift operations for platform installation, subsea infrastructure, and artificial island development. Saudi PIF-backed giga-projects in the Red Sea pull demand for 2,000+ ton capacity units with active heave compensation.
- Oil & Gas Exploration:Drilling support, well completion, and intervention lifting from jack-up rigs and platform supply vessels. Aramco's extended-reach drilling programs concentrate lift requirements on intervention fleets rather than newbuild rigs.
- Marine Salvage:Wreck removal and emergency response operations requiring rapid deployment capability. UAE-flagged emergency response vessels maintain pre-positioned crane packages under federal transport authority certification.
- Wind Farm Installation:Turbine component lifting and floating foundation placement. Abu Dhabi and Dubai maritime zones lack dedicated marshalling infrastructure, creating specification pull for mobile heavy-lift units.
Oil & Gas Exploration commands the largest equipment inventory. Wind Farm Installation is climbing the fastest as UAE and Saudi Arabia advance offshore renewable targets.
Deployment:
Customer type determines contract structure, with oilfield services favoring availability-based terms and marine contractors preferring asset ownership.
- Project-Based:Crane availability matched to discrete construction timelines with milestone-based payment terms. Saudi Red Sea developers specify these structures to manage phasing uncertainty across multi-year island construction.
- Rental:Bareboat and fully-crewed structures transfer operational risk to equipment lessors. Charter-rate volatility has compressed contractor appetite for owned assets in UAE offshore construction.
- Contractual:Long-term agreements with performance guarantees and uptime penalties. SFDA harmonized certification accelerates equipment rotation between Saudi and UAE maritime zones under unified terms.
- On-Demand:Spot-market activation for emergency response and unplanned maintenance. Limited penetration due to crane operator certification fragmentation between MOHAP and Saudi Technical and Vocational Training Corporation frameworks.
Project-Based deployment holds the majority of committed capacity. Rental structures are gaining share fastest as capital discipline tightens across Saudi construction firms.
End User:
Supply concentration varies by user sophistication, with oilfield services demanding OEM-integrated service networks and shipping companies prioritizing acquisition cost.
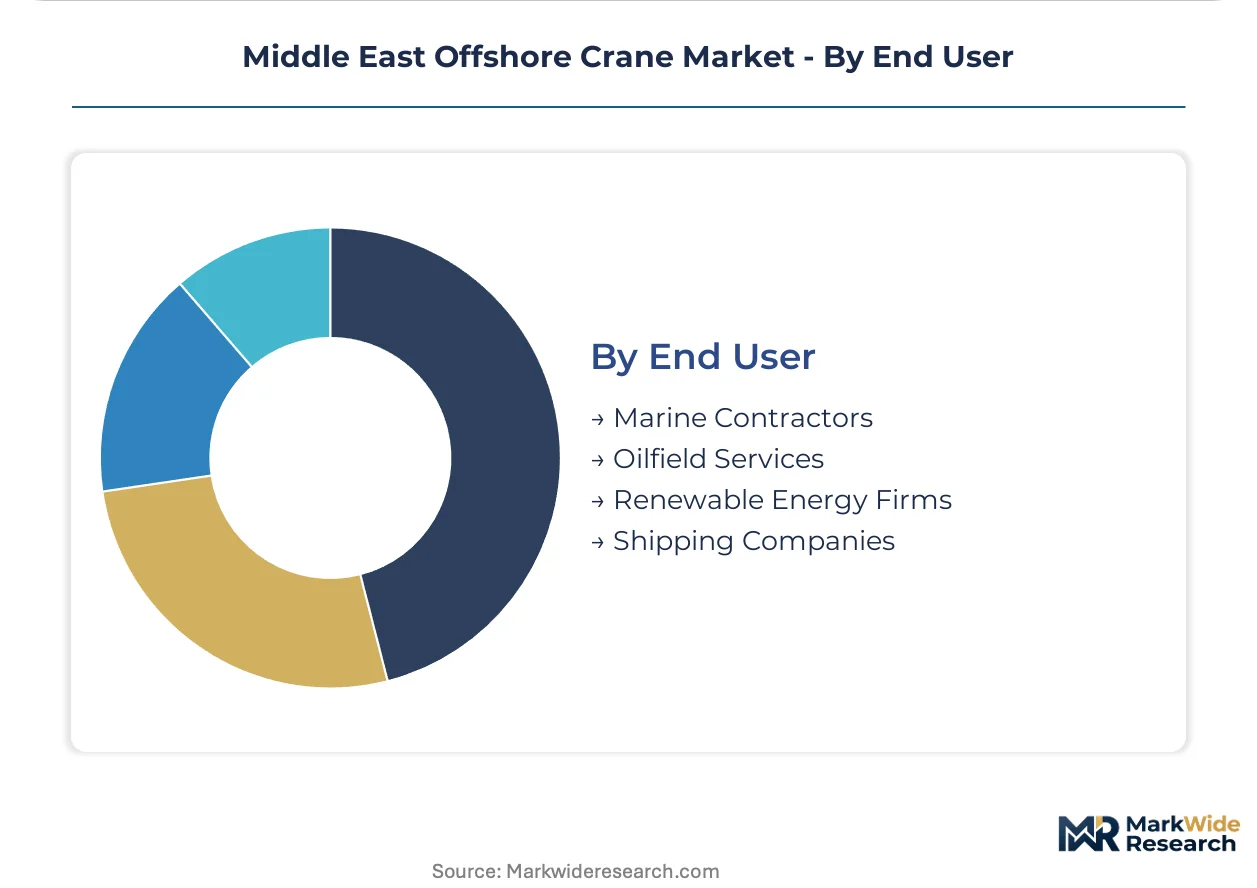
- Oilfield Services:Integrated drilling and intervention contractors specifying crane systems compatible with existing rig fleets. Aramco IKTVA requirements force joint-venture manufacturing arrangements for preferred vendor status.
- Marine Contractors:Heavy-lift specialists bidding EPCI contracts for offshore infrastructure. South Korean and Singaporean fab yard concentration creates single-source dependency for project timeline execution.
- Renewable Energy Firms:Wind developers specifying all-terrain and floating units for coastal staging. Saudi Arabia's renewable energy procurement framework lacks mature marine infrastructure standards.
- Shipping Companies:Vessel owners retrofitting cargo and offshore support fleets. SFDA and MOHAP convergence on unified load-testing protocols reduces dual-certification burden for cross-border operations.
Oilfield Services anchor the premium equipment segment. Renewable Energy Firms represent the steepest expansion trajectory as Gulf offshore wind pipelines advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Middle East offshore crane market. Saudi Arabia's state-backed megaprojects absorb premium pricing for IKTVA-compliant equipment, while UAE marine contractors negotiate aggressively on rental rates amid charter-market volatility.
Saudi Arabia
Saudi Aramco's Red Sea giga-projects and Safaniya field upgrades drive demand for 1,000+ ton floating crane capacity. The Ministry of Energy's escalating IKTVA thresholds force foreign OEMs into joint-venture manufacturing arrangements to secure preferred vendor status. NEOM's northwest coastal zone concentrates heavy-lift marine infrastructure deployment for artificial island construction.
United Arab Emirates
Upper Zakum field decommissioning and offshore wind staging in Abu Dhabi maritime zones pull demand for dynamic positioning-integrated crane systems. MOHAP's unified load-testing protocols with Saudi SFDA reduce dual-certification burdens for cross-border equipment rotation. Dubai's Jebel Ali maritime cluster anchors emergency response vessel pre-positioning for marine salvage contracts.
Qatar
North Field expansion maintenance fleets require compact knuckle-boom systems for 24-hour platform turnaround operations. The country's national petroleum regulator enforces corrosion-resistant alloy certification standards aligned with Gulf Cooperation Council harmonization efforts. Ras Laffan Industrial City concentrates offshore support vessel retrofit activity for crane fleet modernization.
Kuwait
Burgan field aging platform intervention programs concentrate lift requirements on rental-based maintenance fleets rather than newbuild rig investment. Kuwait Oil Company's local content directives mirror Saudi IKTVA frameworks but with lower domestic value-add thresholds. Ahmadi's marine services corridor hosts regional equipment lessors serving cross-border Arabian Gulf projects.
Oman
Duqm Special Economic Zone heavy-lift port infrastructure and offshore block development create specification pull for all-terrain crane staging capabilities. The country's transport and communications ministry administers maritime safety codes requiring active heave compensation documentation for offshore crane certification. Sohar's industrial port cluster attracts fabrication subcontractors serving UAE and Saudi project timelines.
Middle East Offshore Crane Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East offshore crane market. Integrated rig-system specialists command premium positioning through OEM-embedded service networks, while rental fleet operators compete on asset utilization and availability-based contract structures. Three archetypes dominate: full-system integrators with manufacturing scale, specialized maintenance and subsea deployment providers, and capital-light rental intermediaries. Competitive moves concentrate on joint-venture manufacturing partnerships to satisfy IKTVA compliance and predictive maintenance technology licensing to secure long-term service contracts.
Within the full-system integrator tier, NOV Inc and Liebherr Group represent contrasting geographic anchors for technology positioning. Sparrows Offshore Group Limited occupies a specialist position exemplifying the maintenance-focused archetype. These three entities illustrate the market's structural segmentation between rig-integrated lifting systems, European manufacturing scale advantages, and subsea deployment capabilities.
| Leading Market Players |
|---|
| NOV Inc |
| Liebherr Group |
| Kenz Figee Group B.V. |
| Heila Cranes S.p.A. |
| Sparrows Offshore Group Limited |
| Konecranes Plc |
| Cargotec Corporation |
| Terex Corporation |
| Palfinger AG |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-month delivery windows for nickel-molybdenum-chromium alloy booms concentrate pricing power with South Korean and Singaporean fabrication yards serving Saudi Aramco and PIF-backed projects. Extended lead times compress contractor negotiating leverage and expand rental premium capture for equipment lessors holding available inventory.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value beyond initial hardware sales. Three-tier pricing structure across IKTVA-compliant premium systems, standard European-manufactured units, and economy-grade Asian imports dominates procurement. Price differentiation rests on certification tier and active heave compensation capability. Cost compression in mid-range knuckle-boom segments is intensifying because Saudi construction firms are consolidating fleet orders. Oilfield services contractors show least price sensitivity due to uptime penalty clauses, while shipping companies retrofitting vessels exhibit highest sensitivity.
Supply Chain Analysis
Strategic stockpiling of corrosion-resistant alloy plate has displaced just-in-time preferences following Indonesian and Philippine ore export quota volatility. Manufacturing gravity centers on Germany, South Korea, and China for boom fabrication and motor-drive assemblies. Raw material flows draw from Indonesian nickel mines, Chinese chromium processing, and German precision gearing. Single-source vulnerability concentrates in South Korean heavy-lift vessel construction. Distribution runs through Aramco-certified OEM direct channels for large-capacity units and regional rental intermediaries for maintenance fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because predictive maintenance and digital twin subscriptions are expanding faster than crane hardware sales across Saudi and UAE maritime zones.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance technology into OEM service networks before rental operators capture aftermarket share. Deepen backward integration into corrosion-resistant alloy supply through joint-venture arrangements with Saudi industrial partners. Prioritize SFDA-MOHAP harmonized certification investment to accelerate equipment rotation across Red Sea and Arabian Gulf projects.
For New Entrants and Emerging Players: Differentiate on mobile heavy-lift availability for UAE offshore wind staging where dedicated marshalling infrastructure remains absent. Target renewable energy firm procurement as the most penetrable segment given immature marine infrastructure standards. Pursue bareboat rental structures with uptime guarantees to bypass capital-intensive manufacturing barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because IKTVA escalation creates captive demand for locally assembled lifting systems. Acquisition focus should center on European OEMs with EU-type examination documentation enabling fastest SFDA approval timelines. Watch Saudi Aramco fleet renewal specifications for all-electric auxiliary drives as inflection indicator for motor-drive vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Manufacturing Partnership | IKTVA compliance unlocks preferred vendor status on Aramco and PIF tenders. |
| Predictive Maintenance Technology Licensing | Real-time structural monitoring compresses unplanned downtime for offshore operators. |
| SFDA-MOHAP Harmonized Certification Investment | Unified load-testing protocols accelerate equipment rotation between Saudi and UAE zones. |
| Active Heave Compensation Capability Expansion | Extended weather windows capture premium pricing in Arabian Gulf summer periods. |
| All-Electric Auxiliary Drive Development | Saudi Aramco marine division specifications redirect procurement from hydraulic suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from offshore crane procurement managers, Aramco supply chain executives, UAE marine contractor operations directors, and SFDA certification specialists and refined through secondary validation. Primary fieldwork combined structured interviews with fleet operators and OEM service heads. Secondary sources included customs trade data for alloy component flows, Saudi Aramco IKTVA disclosure filings, SFDA and MOHAP regulatory registers, and offshore vessel construction databases. Bottom-up equipment deployment counts were triangulated against top-down project pipeline valuations.
Variance decomposition across crane type, application, deployment structure, and end-user sophistication shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included lifting capacity tier, active heave compensation integration, and IKTVA compliance status. CAGRs were derived from equipment deployment trajectories matched to project timeline phasing. Forecast inputs incorporated Saudi PIF giga-project announcement schedules and UAE offshore wind procurement framework development.
Forecasts assume regulatory continuity in Saudi IKTVA escalation and UAE-MOHAP certification convergence; material policy shifts would require re-modeling. Nickel-molybdenum alloy price volatility and South Korean fab yard capacity constraints represent specific revision triggers. Revision becomes warranted when Indonesian ore export quotas or Aramco fleet electrification timelines cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market