
 Ship-To-Shore Cranes Market | 2026-2036
Ship-To-Shore Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Ship-To-Shore Cranes Market Intelligence
Buyer concentration among terminal operators is broadening as global port privatization draws independent logistics providers and shipping lines into direct crane procurement. Konecranes plc leverages its automation software to capture orders from operators retrofitting legacy terminals. Shanghai Zhenhua Heavy Industries Co. Ltd. anchors Asian supply through integrated steel fabrication and marine transport capabilities. Liebherr Container Cranes Ltd. differentiates via custom engineering for high-wind and seismic port environments.
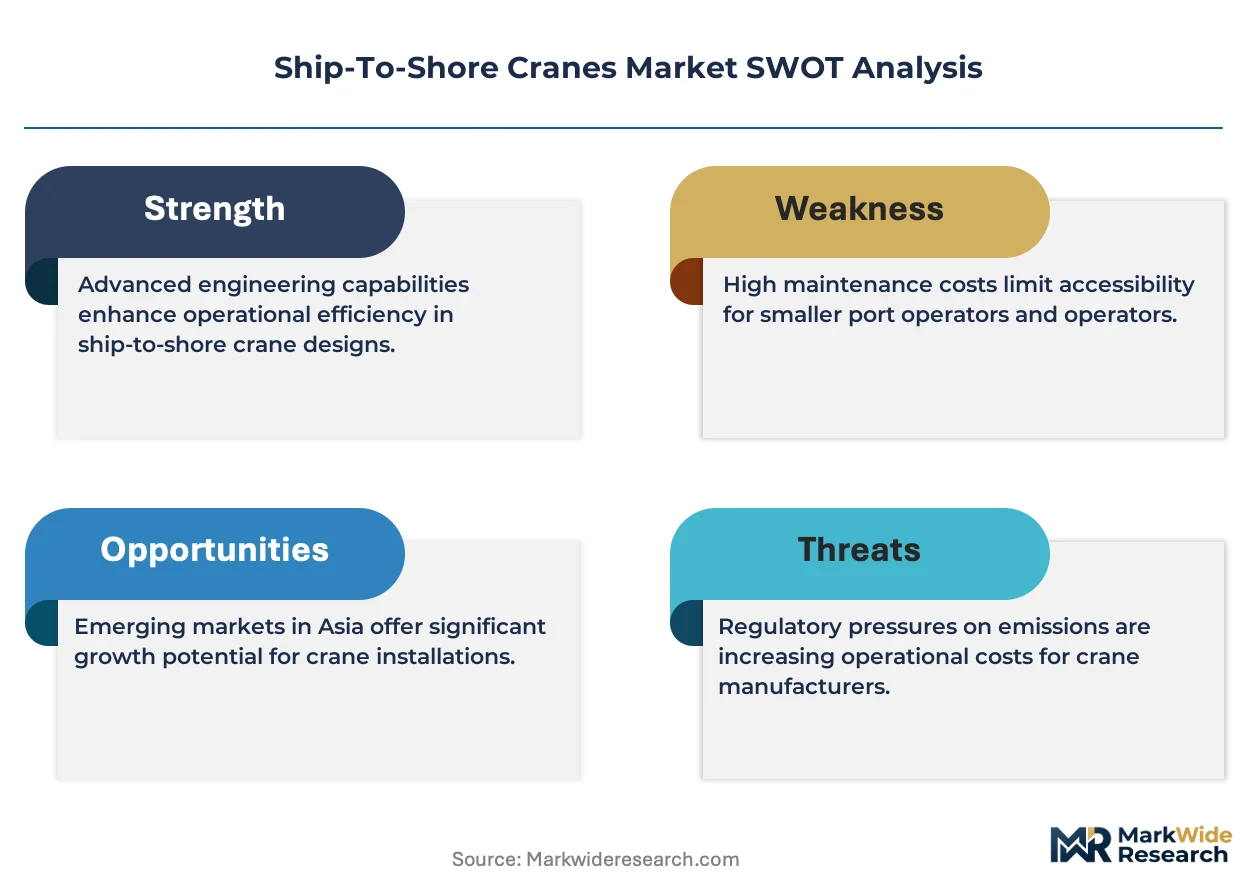
Ship-to-shore cranes are portal-frame lifting machines mounted on rails along quay walls, designed to transfer containers between vessels and dockside transport with outreach lengths exceeding seventy meters and lifting heights surpassing fifty meters for ultra-large container ships. Container cranes dominate procurement volumes as megaship deployment forces port infrastructure scaling, while modernized systems represent the fastest-growing technology segment as electromechanical retrofits displace hydraulic drives for energy recovery and precision positioning. High-capacity and ultra-high-capacity classes command premium pricing due to specialized bogie designs and active load-sway damping requirements.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index standards that indirectly pressure ports to reduce vessel dwell time and corresponding auxiliary power consumption, while China's Ministry of Ecology and Environment imposes emission controls in key port zones that accelerate electric crane adoption. The EU Green Deal's Fit for 55 package extends carbon pricing to maritime transport, creating compliance-driven investment timelines for European terminal operators. Stakeholders must weigh electrification capital cycles against residual value risks from emerging ammonia and hydrogen supply chains for port equipment.
Market Dynamics
Electrification mandates from the EU Green Deal and China's Ministry of Ecology and Environment are forcing terminal operators to compress capital replacement cycles for diesel-hydraulic crane fleets, reshaping procurement timelines and vendor selection criteria across major port clusters.
Growth Catalysts
- IMO Decarbonization Pressure:The International Maritime Organization's Energy Efficiency Existing Ship Index standards push ports to minimize vessel dwell time, accelerating orders for high-throughput electric cranes that reduce auxiliary power consumption during cargo operations.
- Megaport Expansions:Terminal developments in Singapore, South Korea, and China concentrate demand for ultra-high-capacity cranes with outreach exceeding seventy meters to service 24,000+ TEU vessels.
- Automation Software Integration:Terminal operators retrofit legacy quays with sensor-equipped crane management systems that enable remote operation and predictive maintenance, extending asset lifecycles while meeting labor efficiency targets.
Market Restraints
- Specialized Steel Supply Concentration:High-strength quenched and tempered plate for crane booms and portal frames concentrates among integrated mills in China and South Korea, exposing procurement to alloy surcharge volatility and export license delays.
- Seismic Engineering Costs:Ports in high-risk zones like Japan and Chile face structural reinforcement requirements that add fifteen to twenty-five percent to crane capital costs compared to standard designs.
- Residual Value Uncertainty:Emerging ammonia and hydrogen fuel pathways for port equipment create stranded asset risk for electrified crane investments with twenty-five-year depreciation schedules.
Strategic Opportunities
- Secondary Port Electrification:Medium-sized terminals in Vietnam, Indonesia, and Brazil lack grid infrastructure for full electrification, creating demand for hybrid diesel-electric systems with shore power compatibility.
- Retrofit Services:Electromechanical conversion of hydraulic drive systems represents a white space as operators seek to avoid full crane replacement while meeting EU Green Deal compliance deadlines.
- Wind-Load Engineering Specialization:Custom active load-sway damping for high-wind environments opens premium pricing in exposed coastal locations like the North Sea and Gulf of Mexico.
Industry Challenges
- Commissioning Engineer Scarcity:The specialized workforce for crane erection, load testing, and automation calibration concentrates among aging technicians in Germany, Finland, and Japan, constraining deployment velocity for large orders.
- Grid Connection Coordination:Port electrification projects require synchronized upgrades to substations, cable trenches, and reactive power compensation that extend project timelines beyond crane manufacturing lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship-To-Shore Cranes Market |
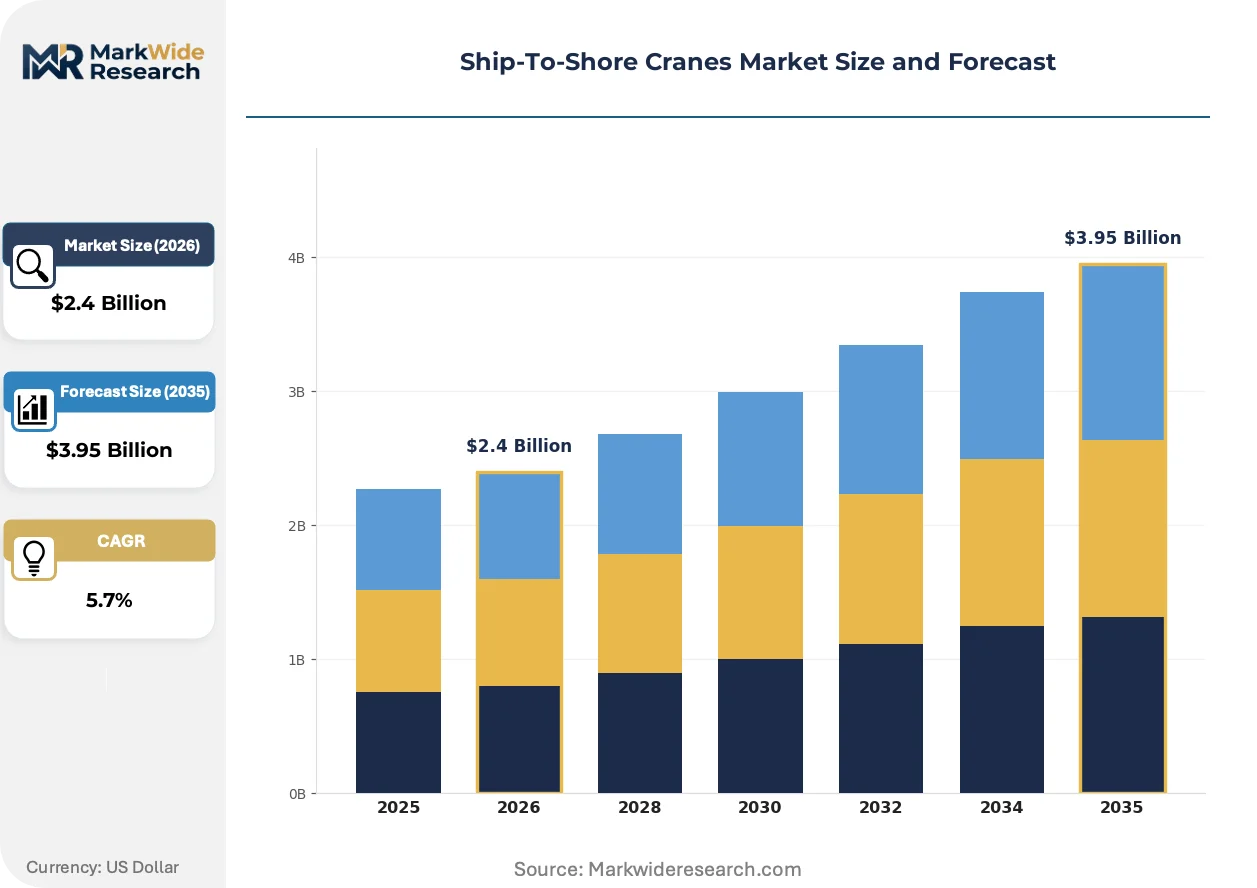
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
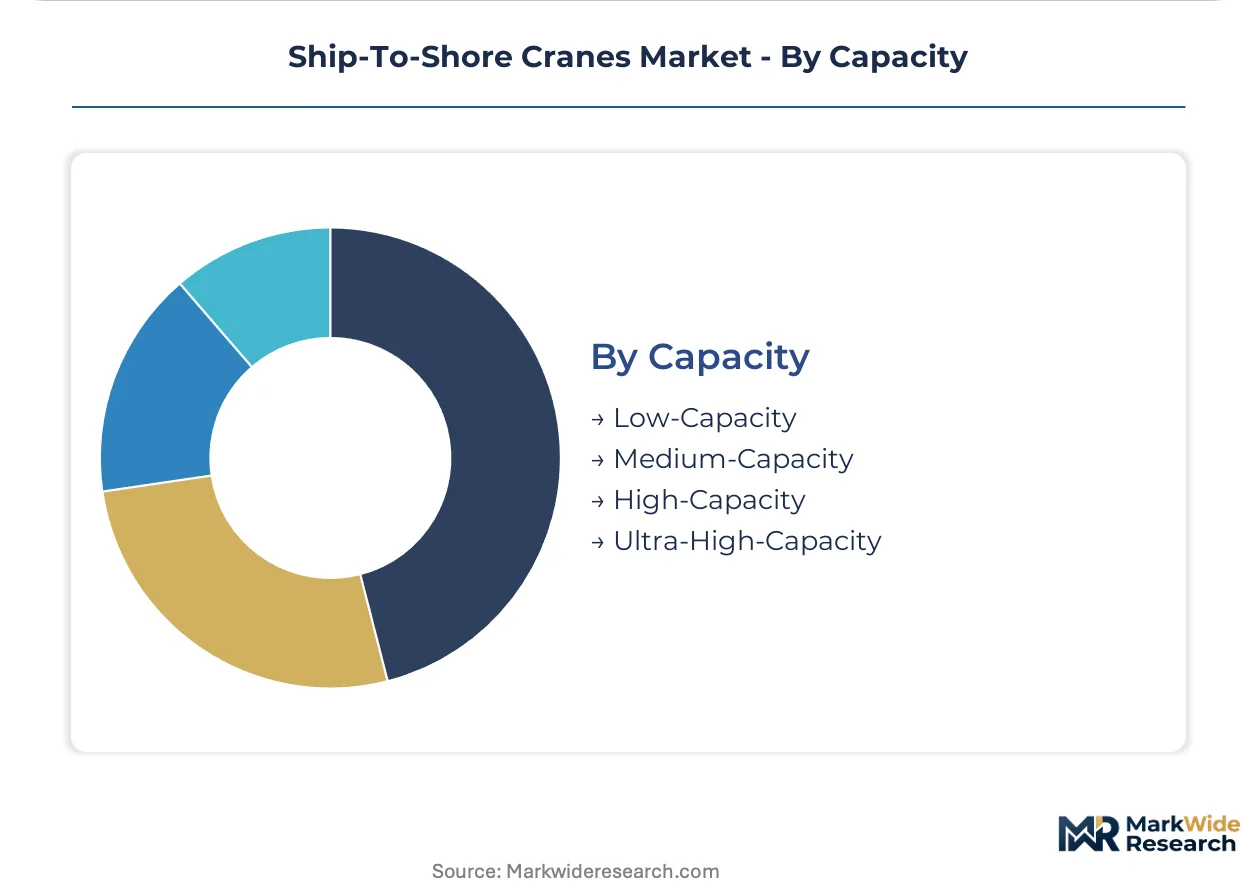
| Segmentation | Product Type: Container Cranes, Bulk Cranes, Gantry Cranes, Fishing Cranes End User: Port Authorities, Shipping Companies, Logistics Providers, Terminal Operators Technology: Electromechanical, Hydraulic, Pneumatic, Modernized Systems Capacity: Low-Capacity, Medium-Capacity, High-Capacity, Ultra-High-Capacity |
| Companies Covered | Shanghai Zhenhua Heavy Industries Co. Ltd., Liebherr Container Cranes Ltd., Konecranes plc, Cargotec Corporation, SANY Heavy Equipment Co. Ltd., PACECO Corp., Doosan Heavy Industries & Construction Co. Ltd., Anupam Industries Limited, Manitowoc Cranes Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship-To-Shore Cranes Market Strategic Shifts & Innovations
Digital twin technology and predictive maintenance platforms are converging with electromechanical drive systems to redefine crane lifecycle economics, compressing the traditional divide between equipment vendors and terminal operators.
Regenerative electromechanical drive systems with energy recovery capability are consolidating market preference over traditional hydraulic configurations. European terminal operators at Rotterdam and Hamburg mandate these systems for new orders to satisfy EU Green Deal carbon accounting requirements. The technology is consolidating vendor portfolios as engineering resources shift from hydraulic component sourcing to power electronics and motor control integration.
The EU Green Deal's Fit for 55 package extends carbon pricing to maritime transport and associated port operations, forcing terminal operators to document equipment emissions through certified measurement protocols. This regulatory pressure compresses procurement timelines for electric cranes as operators seek to lock in capital expenditures before carbon border adjustments take full effect. Mediterranean and Baltic port authorities are responding with accelerated tender schedules and co-financing mechanisms for grid infrastructure.
Long-term service agreements are displacing traditional spare parts purchasing as the dominant aftermarket relationship model. Independent terminal operators in Southeast Asia and the Middle East now bundle crane procurement with ten to fifteen-year maintenance contracts that guarantee availability rates and energy consumption thresholds. This shift is most visible among privatized port concessions in Saudi Arabia and the UAE, where operating lease structures transfer residual value risk to equipment vendors.
Ship-To-Shore Cranes Market Segmentation
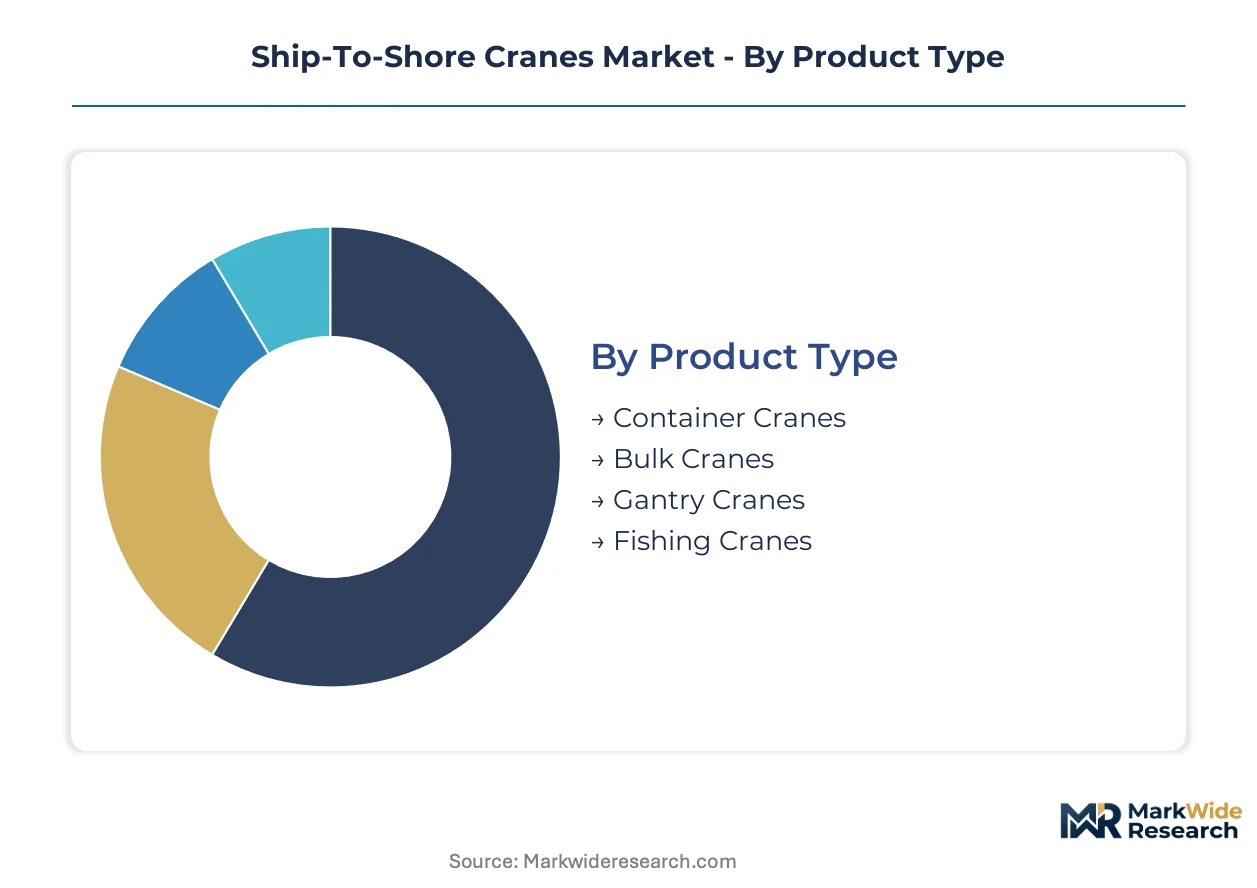
Ship-to-shore crane procurement patterns diverge sharply across operational contexts, with vessel size profiles and regulatory exposure dictating technology choices and capacity specifications. Understanding these segment boundaries clarifies where vendor specialization creates pricing power versus where commoditization pressures dominate.
Product Type:
Terminal operators select crane architectures based on cargo mix flexibility and quay space constraints, with container specialization commanding premium engineering investments.
- Container Cranes:Portal-frame structures with outreach exceeding seventy meters and dual-hoist configurations for simultaneous twin-lift operations. Demand concentrates at Singapore's Tuas megaport and Rotterdam's Maasvlakte expansion, where 24,000+ TEU vessels require rapid turnaround times under IMO decarbonization pressure.
- Bulk Cranes:Heavy-lift grab cranes with rotating turrets for ore, coal, and grain handling. Mining-linked ports in Western Australia and Brazil's northern corridor drive replacement cycles as commodity export volumes recover.
- Gantry Cranes:Rubber-tired or rail-mounted variants for intermodal yards and secondary cargo handling. Flexibility requirements at medium-sized Southeast Asian terminals sustain steady procurement.
- Fishing Cranes:Compact boom configurations for seafood processing vessels and coastal landing facilities. Nordic and North Pacific fleet modernization supports niche demand.
Volume sits with Container Cranes; growth tilts toward Bulk Cranes as mineral export infrastructure expands.
End User:
Ownership structure determines procurement sophistication, with privatized operators leveraging long-term concession financing against public authorities' budget-cycle constraints.
- Terminal Operators:Privatized port concessionaires in Saudi Arabia, UAE, and Indonesia bundle crane procurement with availability-based maintenance contracts. These buyers prioritize automation integration and energy consumption guarantees over upfront capital minimization.
- Port Authorities:Public entities at major Chinese and European gateways specify technical standards and environmental compliance thresholds. EU Green Deal mandates force accelerated replacement timelines at Rotterdam, Hamburg, and Antwerp-Bruges.
- Shipping Companies:Container lines securing dedicated terminal capacity order direct to ensure berth priority. Mediterranean Shipping Company and Maersk Line investments at Algeciras and Tanjung Pelepas illustrate this pattern.
- Logistics Providers:Third-party operators entering port concessions through privatization waves seek standardized equipment for multi-terminal fleets. DP World and PSA International procurement strategies emphasize interoperability.
Procurement volume clusters with Terminal Operators; shipping company direct orders are climbing fastest as vertical integration deepens.
Technology:
Drive system selection now carries regulatory compliance implications, with electromechanical architectures displacing hydraulic configurations under emission control mandates.
- Electromechanical:AC motor drives with regenerative braking and energy recovery to port grid infrastructure. China's Ministry of Ecology and Environment emission controls and EU Green Deal carbon accounting make this the default specification at new megaport developments.
- Modernized Systems:Retrofit packages converting hydraulic cranes to electromechanical operation with sensor integration for predictive maintenance. European terminal operators facing compressed compliance deadlines favor this path over full replacement.
- Hydraulic:Traditional fluid power systems with established maintenance protocols. Residual demand persists at secondary ports with limited electrical infrastructure and long depreciation schedules.
- Pneumatic:Compressed air actuation for specialized bulk handling and hazardous cargo environments. Niche applications at chemical terminals and LNG facilities sustain minimal procurement.
Electromechanical systems dominate new orders; Modernized Systems are expanding most quickly as retrofit demand accelerates.
Capacity:
Lift ratings correlate directly with vessel size accommodation and structural engineering complexity, creating tiered pricing bands that separate commodity from specialty procurement.
- Ultra-High-Capacity:Systems rated for 80+ metric tons with specialized bogie designs and active load-sway damping for 24,000+ TEU vessels. Singapore, South Korea, and China's megaport expansions concentrate orders for these specifications.
- High-Capacity:50-80 metric ton ratings serving 15,000-20,000 TEU vessel classes. Major European and Chinese gateway ports require these for mainline vessel calls without megaship accommodation.
- Medium-Capacity:30-50 metric ton systems for regional feeder vessels and secondary cargo flows. Secondary ports in Vietnam, Indonesia, and Brazil represent the addressable market.
- Low-Capacity:Sub-30 metric ton configurations for inland terminals, fishing ports, and specialized cargo. Limited growth prospects outside replacement cycles.
Revenue concentrates in Ultra-High-Capacity systems; Medium-Capacity orders show steepest expansion trajectory as emerging port infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for ship-to-shore cranes concentrates at megaport clusters in China, Singapore, and South Korea, where terminal operators race to accommodate 24,000+ TEU vessels. European and Middle Eastern ports follow with electrification-driven replacement cycles. Procurement patterns diverge sharply between mature markets facing regulatory deadlines and emerging economies scaling greenfield infrastructure.
China
Shanghai Zhenhua Heavy Industries anchors domestic supply through integrated steel fabrication and marine transport capabilities. The Ministry of Ecology and Environment imposes emission controls in key port zones that accelerate electric crane adoption at Tianjin and Ningbo-Zhoushan. Yangtze River Delta megaports are expanding orders for ultra-high-capacity systems to service the largest container vessels.
Singapore
Tuas megaport development drives concentrated demand for cranes with outreach exceeding seventy meters and active load-sway damping. The Maritime and Port Authority coordinates grid infrastructure upgrades alongside crane procurement to meet IMO decarbonization timelines. PSA International's terminal investments exemplify the shift toward automation-integrated, availability-based contracting models.
South Korea
Busan port authority and Busan New Port operators are expanding capacity to capture transshipment volume from China. The Ministry of Oceans and Fisheries supports electrification through port infrastructure financing programs. Ulsan and Gwangyang industrial ports require specialized high-wind engineering for exposed coastal locations.
Germany
Hamburg and Bremerhaven terminal operators face compressed compliance deadlines under the EU Green Deal's Fit for 55 package. The KBA and federal port authorities mandate certified emission measurement protocols for equipment procurement. Rotterdam-facing North Sea ports are accelerating tender schedules to lock in capital expenditures before carbon border adjustments take full effect.
United Arab Emirates
DP World and Abu Dhabi Ports are bundling crane procurement with long-term maintenance contracts in privatized concessions. The MOHAP and federal transport authorities are aligning port electrification with national decarbonization targets. Jebel Ali and Khalifa Port clusters represent the Gulf's most sophisticated demand for hybrid diesel-electric systems with shore power compatibility.
Ship-To-Shore Cranes Market Key Industry Players
Chinese producers anchor the scale-driven tier; European specialists hold the premium-engineering segment. The market structures around three to five dominant system integrators with captive steel fabrication or automation software capabilities. Strategic archetypes include integrated heavy-industry conglomerates, crane-specific engineering houses, and port-automation platform vendors. Competitive moves concentrate on electromechanical retrofit service expansion and ten-to-fifteen-year availability contracting.
Among Asian fabricators, Shanghai Zhenhua Heavy Industries Co. Ltd., SANY Heavy Equipment Co. Ltd., and Doosan Heavy Industries & Construction Co. Ltd. occupy positions defined by steel supply integration and domestic megaport relationships. Liebherr Container Cranes Ltd. and Konecranes plc exemplify the European engineering-specialist archetype, with the former representing custom high-wind and seismic design capabilities and the latter anchoring automation software integration for legacy terminal retrofits.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries Co. Ltd. |
| Liebherr Container Cranes Ltd. |
| Konecranes plc |
| Cargotec Corporation |
| SANY Heavy Equipment Co. Ltd. |
| PACECO Corp. |
| Doosan Heavy Industries & Construction Co. Ltd. |
| Anupam Industries Limited |
| Manitowoc Cranes Group |
| Others |
Cost & Logistics Intelligence
Sovereign-backed heavy-industry conglomerates in China and South Korea anchor crane fabrication through captive steel supply and state-financed megaport relationships, compressing margin competition for European engineering specialists while elevating pricing power for electromechanical retrofit services and automation-integrated contracts.
Pricing Analysis
Volume concentrates in standard ultra-high-capacity container cranes where Chinese integrated producers compete on delivery scale, while margins accrue to electromechanical modernization packages and high-wind seismic engineering specialties. Price differentiation hinges on automation software integration and active load-sway damping certification tiers. Pricing pressure intensifies in the standard crane tier as South Korean fabricators expand capacity for Vietnam and Indonesia port developments. Terminal operators in privatized Middle Eastern concessions show lowest price sensitivity through availability-based contracting, while secondary port authorities in Brazil and Southeast Asia remain highly price-sensitive with limited concession financing.
Supply Chain Analysis
High-strength quenched and tempered steel plate for crane booms and portal frames rests on integrated mills in China, South Korea, and Japan, with specialized alloy grades tethered to export licensing protocols from Chinese state-owned producers. Critical inputs span high-tensile structural steel, electromechanical drive systems from German and Finnish specialists, and automation sensor arrays. Supply chain risk centers on alloy surcharge volatility and concentrated sourcing of quenched plate grades. Distribution runs through direct vendor-terminal operator relationships for megaport projects, with regional fabricators serving secondary ports through local agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized commissioning engineer scarcity constrains deployment velocity for large crane orders, propping pricing for electromechanical retrofit services and long-term availability contracts as terminal operators face compressed EU Green Deal compliance timelines.
For Market Incumbents: Anticipate margin compression in standard crane fabrication as South Korean producers deepen backward integration into high-strength steel supply. Defend position through captive automation software development and predictive maintenance platform integration. Prioritize long-term service contract bundling with privatized terminal operators in Saudi Arabia and UAE to lock in residual value capture. For New Entrants and Emerging Players: Electromechanical retrofit technology for legacy hydraulic crane fleets offers the most penetrable entry wedge. Target European terminal operators at Rotterdam, Hamburg, and Antwerp-Bruges facing compressed compliance deadlines under EU Green Deal mandates. Pursue white-label partnerships with established automation software vendors to bypass commissioning engineer scarcity constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor crane-specific engineering houses with electromechanical drive integration capabilities in Germany and Finland. Long-term viability over a five-to-ten-year horizon depends on automation software recurring revenue streams displacing transactional equipment sales. Watch for EU carbon border adjustment implementation as the inflection trigger for accelerated European terminal operator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Retrofit Service Expansion | Captures EU Green Deal compliance-driven demand from Rotterdam and Hamburg terminal operators. |
| Automation Software Platform Integration | Enables remote crane operation and predictive maintenance for PSA International's Tuas megaport deployment. |
| Long-term Availability Contracting | Transfers residual value risk to vendors in DP World and Abu Dhabi Ports privatized concessions. |
| High-wind Engineering Specialization | Commands premium pricing for Busan New Port and North Sea exposed coastal locations. |
| Grid Infrastructure Co-financing | Accelerates tender timelines for Mediterranean and Baltic port authorities under Fit for 55 pressure. |
Research Approach
Document review covered customs trade data, EU Green Deal regulatory filings, and port authority procurement records, complemented by interviews with terminal operations directors, crane maintenance heads, OEM procurement teams, and aftermarket service managers. Secondary validation drew from IMO decarbonization protocols, China's Ministry of Ecology and Environment emission control directives, and SEC filings from listed equipment vendors. Bottom-up order book analysis and top-down port capacity expansion modeling were triangulated to derive market estimates.
Historical crane deployment patterns were cross-referenced against expert panel input from commissioning engineers and automation integration specialists across the projection horizon. Segmentation modeling spanned product type, capacity tier, technology architecture, and end-user ownership structure. CAGRs were derived from regression analysis of megaport expansion timelines and regulatory compliance deadline clustering. Industry-specific forecast inputs included vessel size deployment curves and grid infrastructure upgrade coordination lag times.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity steel price spikes and export license disruption scenarios. Forecasts reflect documented assumptions regarding IMO implementation timelines and EU carbon border adjustment phasing. A small set of triggers warrants ongoing watch: ammonia and hydrogen fuel pathway commercialization for port equipment, and commissioning engineer workforce demographics in Germany and Finland.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Offshore Pipeline Market