
 Mooring Compensators Market | 2026-2036
Mooring Compensators Market Size, Share, and Industry Trends Forecast 2026-2036
Mooring Compensators Market Foresight
Asset-light leasing models for offshore mooring equipment are reshaping competitive dynamics by lowering capital barriers for mid-tier field developers. Unimer Marine leverages its specialized manufacturing footprint in Nordic waters to sustain premium positioning for harsh-environment systems. Trelleborg anchors its market presence through backward integration into elastomer compound development, controlling critical material specifications. SBM Offshore differentiates by bundling compensators within integrated FPSO mooring packages, reducing interface risk for operators.
Mooring compensators are elastomeric or metallic energy-absorption devices installed within anchor chains or synthetic rope assemblies to dampen peak loads from vessel motion, wave action, and tidal surge; hydraulic variants typically operate at working pressures exceeding 200 bar with stroke capacities up to several meters depending on vessel displacement class. Their primary purpose is protecting subsea infrastructure and deck fittings from snap loads that exceed design limits during severe sea states. Mechanical and hydraulic product types dominate current deployment volumes across mature North Sea fields, while hybrid systems combining passive damping with active tension control represent the fastest-expanding margin pool as operators push into ultra-deepwater. Application demand clusters around offshore platforms where station-keeping reliability directly ties to production uptime, though aquaculture systems emerge as a volume growth corridor as salmon farming expands into more exposed coastal sites.
DNV classification rules for offshore mooring systems and ISO 19901-7 station-keeping standards shape product certification requirements, creating compliance moats around established suppliers. The EU Marine Strategy Framework Directive and national offshore safety regulators in Norway and the UK enforce environmental risk assessments that influence compensator material selection and inspection intervals. Stakeholders must weigh exposure to synthetic rope wear versus chain fatigue as hybrid mooring architectures gain share in next-generation floating installations.
Market Dynamics
Floating production installations in water depths exceeding 1,500 meters now require active tension-control mooring architectures that fundamentally alter compensator specification criteria. DNV classification rules for offshore mooring systems and ISO 19901-7 station-keeping standards are tightening certification thresholds just as field developers consolidate procurement around integrated mooring packages.
Growth Catalysts
- Ultra-deepwater field development:Pre-salt discoveries off Brazil and West Africa demand hybrid compensator systems with stroke capacities exceeding four meters to accommodate FPSO motion envelopes in 2,000-meter-plus depths.
- EU Marine Strategy Framework Directive:Environmental risk assessment mandates for subsea infrastructure are accelerating replacement cycles for legacy elastomeric compensators with certified low-temperature-grade compounds.
- Salmon aquaculture expansion:Norwegian and Scottish operators are deploying mooring compensators at exposed coastal sites previously considered too energetic for cage farming, creating incremental volume demand.
Market Restraints
- Specialized elastomer supply concentration:HNBR and fluorocarbon compound production for harsh-environment seals concentrates among three European chemical suppliers, exposing compensator manufacturers to input cost volatility.
- Technical limitation in synthetic rope interfaces:Current hydraulic compensator designs exhibit accelerated seal wear when paired with high-modulus polyethylene mooring lines due to differential stiffness transmission.
- REACH substance restrictions:ECHA regulatory friction around legacy plasticizers in elastomer formulations is forcing reformulation timelines that extend product qualification cycles by 18-24 months.
Strategic Opportunities
- Floating offshore wind:Pre-commercial arrays in the Celtic Sea and off California require station-keeping systems adapted from oil and gas architectures, opening white-space demand for scaled compensator platforms.
- Leasing-based procurement models:Mid-tier field developers in Southeast Asia are adopting equipment-as-a-service contracts that bundle compensators within integrated mooring spreads, reducing upfront capital barriers.
- Digital twin integration:Convergence of sensor-embedded compensators with predictive maintenance software enables condition-based inspection intervals, differentiating premium suppliers from commodity competitors.
Industry Challenges
- DNV type-approval timelines:Certification processes for novel hybrid compensator architectures now extend 14-18 months, compressing product launch windows and freezing design iterations.
- Subsea robotics integration:Remote installation and retrieval protocols for deepwater compensators demand specialized ROV tooling that few installation contractors maintain, constraining deployment flexibility.
- Legacy FPSO retrofit compatibility:Active tension-control upgrades require structural modifications to aged turret mooring systems that were not engineered for dynamic load modulation, complicating brownfield deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mooring Compensators Market |
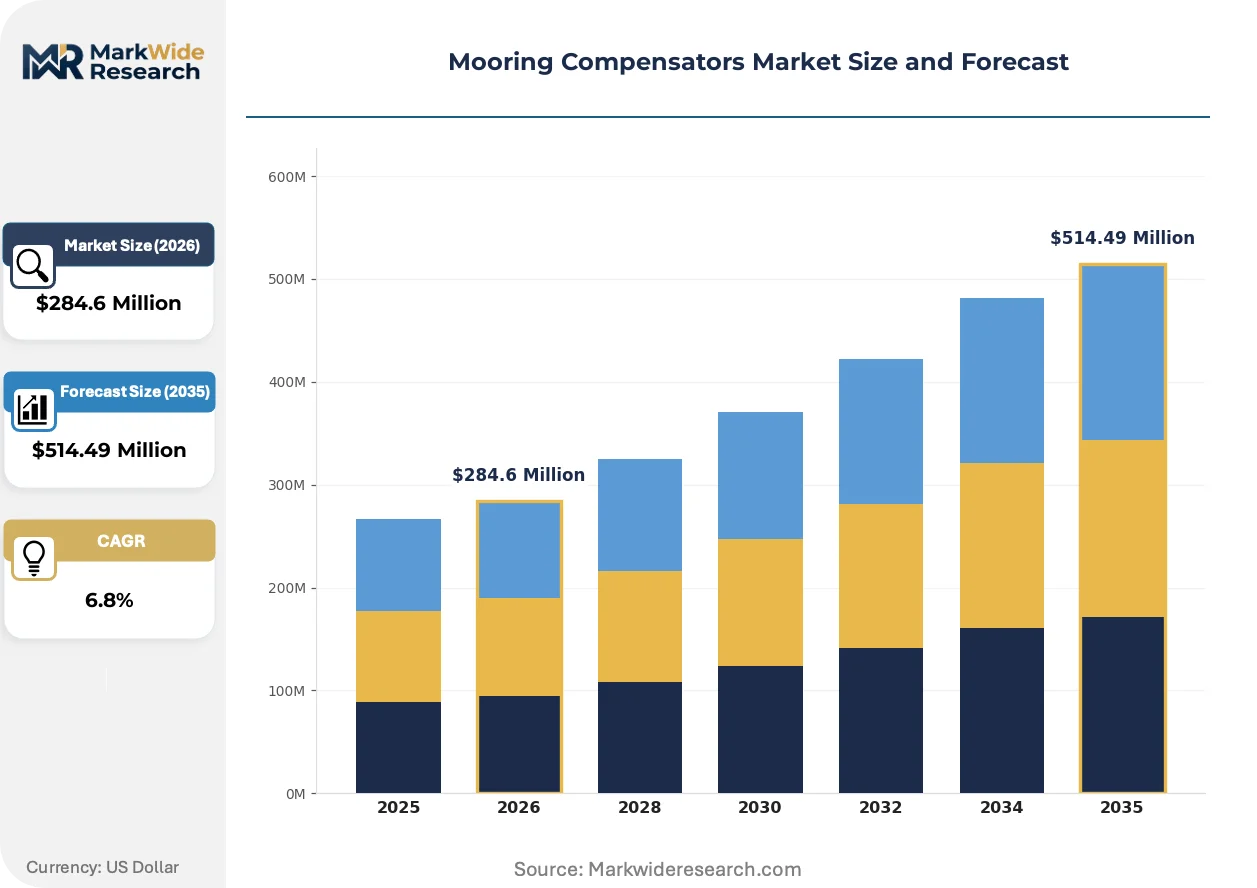
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electric, Mechanical Application: Offshore Platforms, Shipping Vessels, Floating Docks, Aquaculture Systems End User: Oil & Gas Industry, Maritime Industry, Fishing Industry, Research Institutions Technology: Active Systems, Passive Systems, Hybrid Systems, Automated Solutions |
| Companies Covered | Unimer Marine, Trelleborg, SBM Offshore, Mampaey Offshore Industries, Delmar Systems, Mooring Systems, BW Offshore, MODEC, Balltec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mooring Compensators Market Shifts & Advancements
Sensor-embedded compensator systems are collapsing the distinction between passive damping hardware and active station-keeping control, enabling real-time load modulation that was previously impossible with mechanical architectures alone.
Digital twin technology is virtualizing compensator performance prediction by creating physics-based simulations that replicate elastomer fatigue accumulation and hydraulic seal degradation under actual sea-state spectra. North Sea operators with mature FPSO fleets are deploying these virtual models to extend inspection intervals from fixed schedules to condition-triggered maintenance events. The technology is virtualizing traditional warranty structures by enabling outcome-based service contracts where suppliers retain operational risk for mooring system reliability.
DNV classification rules for offshore mooring systems are mandating probabilistic analysis of extreme load events rather than deterministic safety factors, forcing compensator manufacturers to generate extensive sea-state response databases. This regulatory shift elevates documentation burdens for smaller suppliers lacking hydrodynamic simulation capabilities. Norwegian and UK continental shelf projects now require DNV-certified compensator designs with documented performance envelopes across full vessel motion spectra, compressing the qualified supplier base.
Integrated procurement of complete mooring spreads is displacing component-level purchasing as major field developers seek single-point accountability for station-keeping performance. SBM Offshore and Modec are bundling compensators within turnkey FPSO delivery contracts, marginalizing standalone compensator vendors that lack vessel integration capabilities. This pattern concentrates most visibly in Brazilian pre-salt developments where Petrobras mandates integrated contractor responsibility for mooring system integrity across 25-year lease periods.
Mooring Compensators Market Segmentation
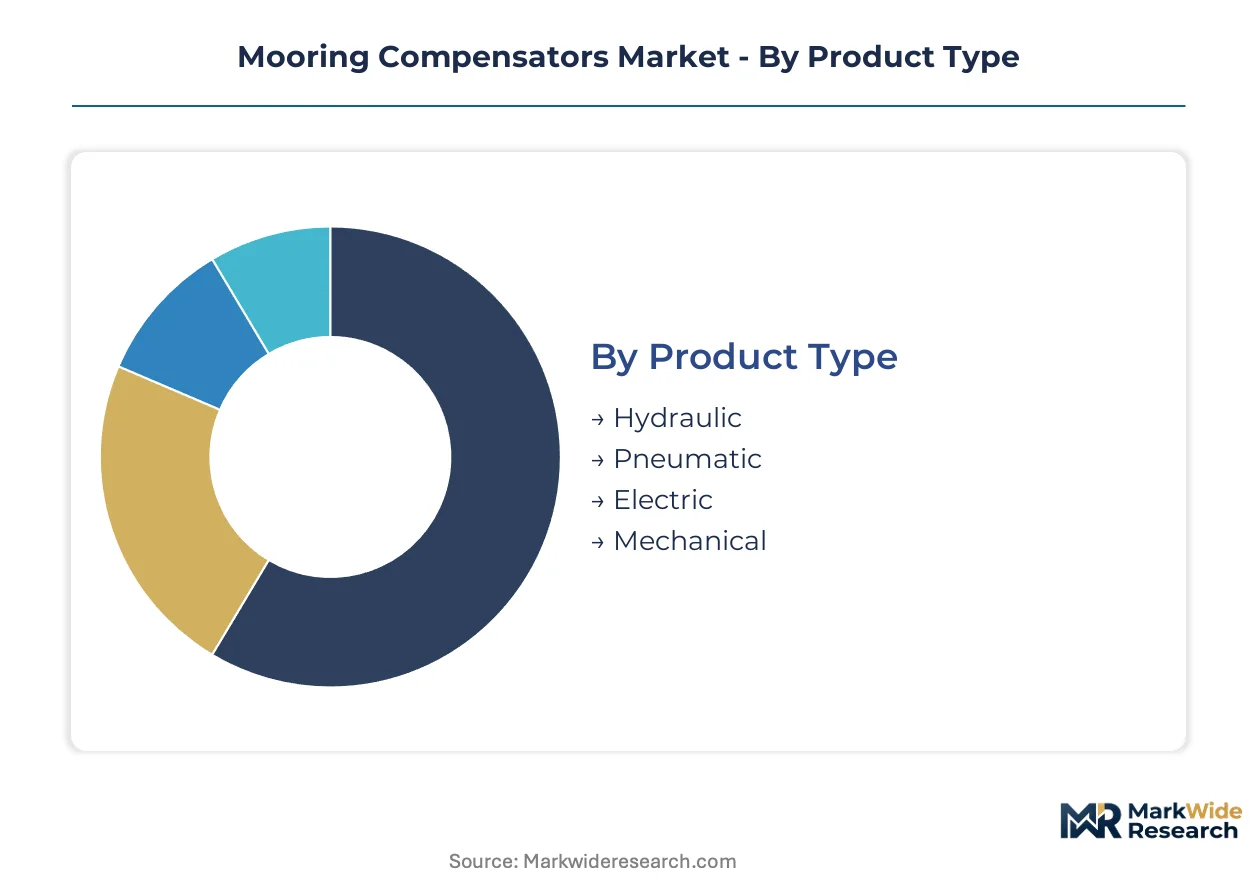
Mooring compensator procurement splits sharply between mature offshore oil and gas installations and emerging floating infrastructure categories. Technical specification requirements diverge fundamentally across water depth, vessel displacement class, and regulatory jurisdiction.
Product Type:
Cost tier differentiation separates high-specification active systems from passive mechanical alternatives in procurement budgets.
- Hydraulic:These systems operate at working pressures exceeding 200 bar with stroke capacities scaling to several meters for large vessel classes. Norwegian North Sea operators specify hydraulic compensators for FPSO installations in water depths beyond 1,500 meters where active tension control proves essential.
- Mechanical:Elastomeric or metallic energy-absorption devices dampen peak loads through passive deformation without external power. Demand concentrates in legacy North Sea fields and coastal aquaculture sites where simpler maintenance protocols offset performance limitations.
- Pneumatic:Compressed air chambers provide load modulation for mid-size vessel classes in moderate sea states.
- Electric:Motor-driven actuation enables precise tension control with reduced hydraulic fluid environmental exposure.
Hydraulic systems command the established base. The steepest expansion runs through electric variants as environmental regulations tighten around hydraulic fluid discharge.
Application:
Volume concentration tracks floating production deployment intensity across deepwater basins and exposed coastal aquaculture frontiers.
- Offshore Platforms:Station-keeping reliability directly ties to production uptime for FPSO, semi-submersible, and spar platforms. Brazilian pre-salt discoveries and West African deepwater fields drive specification toward hybrid systems with four-meter-plus stroke capacities.
- Aquaculture Systems:Norwegian and Scottish salmon farming expansion into energetic coastal sites previously considered unsuitable for cage mooring creates incremental volume demand for compact elastomeric compensators.
- Shipping Vessels:Temporary mooring at single-point buoys requires rapid-deploy compensator solutions for tanker offloading operations.
- Floating Docks:Harbor infrastructure maintenance and vessel repair facilities utilize standardized mechanical compensator packages.
Offshore platforms absorb the majority of current procurement value. Aquaculture systems are climbing the fastest as regulatory pressure forces salmon farming into more exposed waters.
End User:
Customer type determines specification rigor, with oil and gas majors mandating certified designs against fishing operators prioritizing capital efficiency.
- Oil & Gas Industry:Integrated procurement of complete mooring spreads now dominates as Petrobras and similar operators seek single-point accountability for 25-year station-keeping performance. DNV type-approval and ISO 19901-7 compliance are non-negotiable entry requirements.
- Maritime Industry:Port authorities and shipping operators balance capital constraints against downtime risk in less severe sea state environments.
- Fishing Industry:Coastal fleet operators in Norway and Scotland adopt leasing-based equipment procurement to reduce upfront capital barriers.
- Research Institutions:Oceanographic monitoring platforms require specialized low-noise compensator designs for sensitive acoustic instrumentation.
Oil and gas operators dominate contract value. Maritime industry adoption is expanding most quickly as port infrastructure upgrades accelerate.
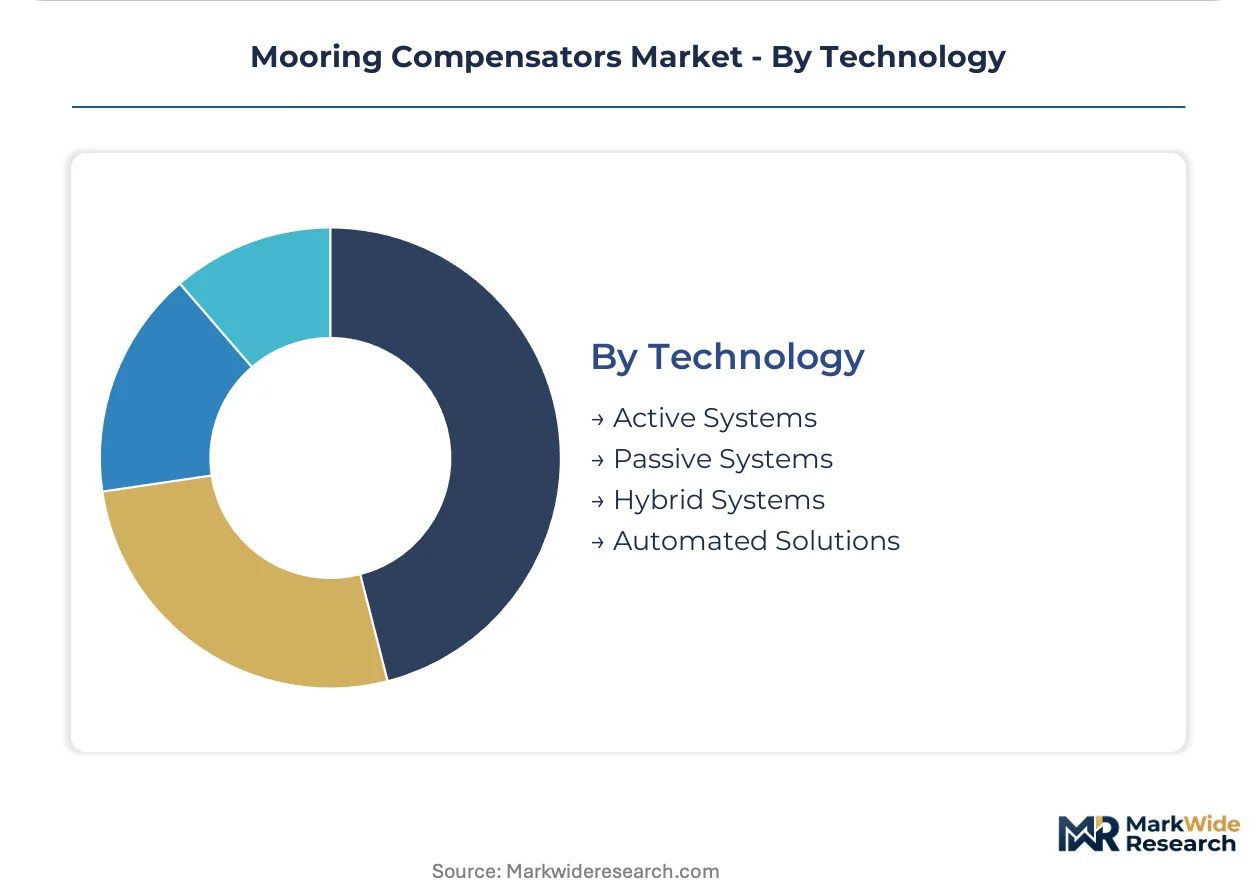
Technology:
Maturity curves separate field-proven passive damping from digitally integrated active architectures still navigating extended certification timelines.
- Hybrid Systems:Combining passive elastomeric damping with active tension control, these architectures represent the fastest-expanding margin pool as operators push into ultra-deepwater. DNV probabilistic analysis requirements for extreme load events elevate documentation burdens that favor established suppliers with hydrodynamic simulation capabilities.
- Passive Systems:Mechanical and elastomeric designs without external power input dominate current deployment volumes across mature North Sea fields where inspection intervals follow fixed schedules rather than condition-based triggers.
- Active Systems:Real-time load modulation through sensor feedback enables station-keeping precision impossible with mechanical architectures alone.
- Automated Solutions:Digital twin integration with predictive maintenance software collapses traditional warranty structures toward outcome-based service contracts.
Passive systems anchor installed base economics. Hybrid configurations gain share fastest as floating wind and ultra-deepwater oil projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Norway's North Sea cluster while Southeast Asian procurement favors leasing-based cost structures. Brazilian pre-salt developments command integrated system premiums. West African deepwater fields anchor mid-tier specification demand.
Norway
Equinor's Johan Castberg and Wisting field developments drive demand for certified harsh-environment compensator systems. The Norwegian Petroleum Safety Authority enforces functional requirements for station-keeping equipment that exceed ISO 19901-7 baselines. Stavanger and Bergen host engineering clusters where DNV type-approval processes create compliance moats around established suppliers.
Brazil
Petrobras pre-salt FPSO deployments in Santos Basin waters exceeding 2,000 meters require hybrid compensator architectures with four-meter stroke capacities. The National Petroleum Agency mandates integrated contractor responsibility for mooring system integrity across 25-year lease periods. Rio de Janeiro's CENPES research center anchors supplier qualification protocols for ultra-deepwater equipment.
United Kingdom
North Sea decommissioning schedules and marginal field redevelopments sustain replacement demand for mechanical compensator systems. The Health and Safety Executive enforces offshore installation safety case requirements that influence inspection intervals. Aberdeen maintains its position as Europe's primary procurement hub for brownfield mooring upgrades.
United States
Gulf of Mexico deepwater projects in Lower Tertiary formations drive specification toward active tension-control systems. The Bureau of Safety and Environmental Enforcement oversees well control and station-keeping equipment certification for outer continental shelf operations. Houston's energy corridor concentrates engineering procurement for floating production installations.
China
State-owned offshore operators expanding into South China Sea deepwater blocks drive localization requirements for mooring component manufacturing. The Ministry of Natural Resources oversees marine equipment certification through its offshore oil safety supervision system. Shenzhen and Tianjin host fabrication yards developing captive supply capabilities for FPSO mooring spreads.
Mooring Compensators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower specification scope. Market structure concentrates around turnkey FPSO contractors bundling compensators within integrated delivery contracts, marginalizing standalone vendors lacking vessel integration capabilities. Three archetypes dominate: Nordic harsh-environment specialists, diversified elastomer compounders with backward integration, and integrated floating production contractors. Competitive moves center on certification timeline acceleration and digital twin service bundling.
Among Nordic-based specialists, Unimer Marine and Trelleborg occupy positions anchored in North Sea regulatory familiarity. SBM Offshore exemplifies the integrated platform tier, representing contractors that internalize compensator procurement within vessel delivery scope. These three entities illustrate how geographic proximity to harsh-environment demand clusters, material science capabilities, and system integration breadth respectively define competitive positioning archetypes.
| Leading Market Players |
|---|
| Unimer Marine |
| Trelleborg |
| SBM Offshore |
| Mampaey Offshore Industries |
| Delmar Systems |
| Mooring Systems |
| BW Offshore |
| MODEC |
| Balltec |
| Others |
Supply & Pricing Matrix
European specialty elastomer production for HNBR and fluorocarbon compounds concentrates among three chemical suppliers in Germany and France, anchoring margin capture downstream at compensator manufacturers serving North Sea certification requirements. This feedstock bottleneck forces tiered pricing structures that separate DNV-certified harsh-environment systems from standard mechanical alternatives.
Pricing Analysis
Configured-to-order hydraulic systems for ultra-deepwater FPSOs command substantial premiums over catalog mechanical units for coastal aquaculture. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with active tension-control architectures priced highest due to extended DNV type-approval timelines. Price erosion runs through standard elastomeric segments as Chinese fabrication yards enter mechanical compensator production. Oil and gas majors show lowest price sensitivity given station-keeping failure costs, while Scottish salmon operators prioritize capital efficiency.
Supply Chain Analysis
HNBR compound feedstock draws from Germany, France, and limited Japanese specialty chemical production, creating concentrated upstream dependency for seal formulations critical to hydraulic compensator reliability. Steel forgings for load-bearing housings source from Sweden and South Korea, while high-modulus polyethylene mooring lines feed from the Netherlands and the United States. Single-source vulnerability around fluorocarbon elastomer grades exposes manufacturers to 18-24 month reformulation cycles under REACH restrictions. Distribution runs through integrated FPSO contractors bundling compensators within turnkey vessel delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as floating offshore wind and aquaculture applications diverge from oil and gas specification requirements, enabling specialist positioning outside integrated contractor dominance.
For Market Incumbents: Harden certification moats by accelerating DNV probabilistic analysis documentation for hybrid architectures before regulatory thresholds tighten further. Invest in captive elastomer compounding capabilities to offset European chemical supplier concentration and secure margin control against specialty compound price volatility. Prioritize digital twin service bundling to shift warranty structures toward outcome-based contracts that lock in long-term operator relationships. For New Entrants and Emerging Players: Southeast Asian leasing-based procurement for mid-tier field developers offers the most penetrable entry corridor, as equipment-as-a-service contracts reduce upfront capital barriers and bypass integrated FPSO contractor gatekeeping. Target compact electric compensator designs for floating offshore wind pre-commercial arrays in the Celtic Sea and California, where station-keeping architectures remain undefined and certification requirements are still stabilizing. Pursue aquaculture system partnerships with Norwegian salmon farming cooperatives expanding into exposed coastal sites. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Nordic component specialists possessing DNV type-approval libraries but lacking digital twin integration capabilities. Long-term viability across the analysis window favors acquisition targets with hybrid system engineering depth and established harsh-environment track records in Norwegian or Brazilian waters. Watch floating offshore wind project FID announcements as the critical inflection signal for compensator demand outside oil and gas cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| DNV Type-Approval Acceleration | Compresses 14-18 month certification timelines for hybrid architectures before competitors qualify. |
| Backward Integration into Elastomer Compounding | Mitigates HNBR supply concentration risk from German and French chemical suppliers. |
| Digital Twin Platform Development | Enables condition-based inspection intervals that differentiate premium suppliers from commodity competitors. |
| Floating Offshore Wind Partnership | Secures early-mover positioning in Celtic Sea and California pre-commercial arrays. |
| Equipment-as-a-Service Model Launch | Captures Southeast Asian mid-tier developers seeking reduced upfront capital barriers. |
Research Methodology
The analysis maps hydraulic, mechanical, pneumatic, and electric compensator sub-sectors, each validated through procurement directors at FPSO operators, mooring system engineers at classification societies, and aftermarket service managers at Nordic specialists. Primary interviews with plant managers at elastomer compounders, technical R&D directors at seal manufacturers, and project developers at floating wind consortia combined with secondary validation from DNV rule change documentation, ISO 19901-7 revision drafts, and customs trade data for mooring component shipments. Bottom-up unit economics triangulated against top-down sector spend estimates.
The analytical framework held fixed regulatory certification requirements and water depth deployment trends while varying floating wind adoption pace and aquaculture expansion rates across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user industry, and technology maturity tier. CAGRs derived from elasticity-adjusted demand curves incorporating FPSO orderbook visibility and salmon farming license allocations. Industry-specific inputs incorporated DNV probabilistic analysis adoption timelines and REACH substance restriction implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in offshore capital expenditure cycles, crude oil price bands, or marine construction vessel dayrates would shift the trajectory. Forecasts reflect assumptions about classification society rule stability and elastomer compound supply continuity. Cross-checking against IEA floating offshore wind deployment benchmarks and national petroleum agency field development schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market