
 Global Seismic Vessels Market | 2026-2036
Global Seismic Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seismic Vessels Market Foresight
Market Context
High-specification 3D and 4D acquisition capability is bifurcating the competitive landscape between premium tonnage and legacy fleets. PGS leverages its Ramform hull architecture to sustain super-wide tow spreads in the North Atlantic and West Africa. CGG differentiates through proprietary broadband seismic technology integrated across its fleet. SLB anchors its position via in-house production of seismic acquisition equipment paired with vessel operations.
Technical Definition and Segment Structure
Seismic vessels are purpose-built marine craft equipped with acoustic source arrays and hydrophone streamers or ocean-bottom sensor nodes, typically operating at survey speeds of 4-5 knots while towing equipment spanning 6-12 kilometers astern, to map subsurface geological structures for hydrocarbon identification and reservoir monitoring. Streamer vessels occupy the mature core of the fleet where utilization rates dictate day-rate stability, while ocean bottom nodes represent the fastest-growing vessel category as operators deploy autonomous retrieval systems for complex seabed geometries. Multi-client surveys concentrate margin pools in data licensing rather than acquisition contracting, shifting risk-return profiles toward pre-funded programs.
Regulatory Environment
IMO MARPOL Annex VI sulfur regulations and the EU Green Deal maritime decarbonization framework are reshaping newbuild specifications and engine retrofit schedules across fleets registered in Norway, the Netherlands, and Singapore. The US Coast Guard and Brazil's national petroleum regulator enforce safety and environmental compliance standards that determine market access for survey contractors operating in the Gulf of Mexico and Santos Basin pre-salt blocks. Stakeholders must monitor evolving carbon intensity indicators and regional cabotage enforcement to align fleet deployment with emerging compliance costs and local content requirements.
Market Dynamics
Fleet bifurcation between high-specification 3D/4D tonnage and aging legacy vessels is compressing day-rate spreads and forcing capital allocation decisions across the contractor base. IMO emissions mandates are accelerating engine retrofit cycles while frontier basin exploration concentrates contracting power in Norway, Brazil, and the US Gulf of Mexico.
Growth Catalysts
- IMO MARPOL Annex VI compliance deadlines:Norwegian-flagged fleets face accelerated retrofit schedules for dual-fuel propulsion systems, creating sustained demand for engine upgrade services and newbuild specifications through 2030.
- Pre-salt exploration intensity:Brazil's Santos Basin multiclient surveys are pre-funding vessel programs before acquisition, shifting risk-return profiles toward data licensing models with higher margin capture.
- Ocean-bottom node retrieval automation:Autonomous underwater vehicle integration is expanding addressable survey geometries in complex seabed environments previously inaccessible to conventional streamer spreads.
Market Restraints
- Steel and marine electronics cost volatility:Hull construction and seismic sensor array inputs face commodity price swings that compress newbuild margins and delay fleet replacement cycles.
- Contractor concentration in Norwegian registry:Three major operators control premium tonnage flagged in Norway, creating supply bottleneck risk for high-specification programs in the North Atlantic and West Africa.
- Streamed data substitution by reprocessing:Advanced computational reprocessing of legacy 3D surveys is displacing some new acquisition demand in mature basins with extensive historical coverage.
Strategic Opportunities
- Frontier basins offshore Namibia and Suriname:Underexplored Atlantic margins lack historical survey density, creating first-mover advantages for multiclient pre-funding models with extended licensing horizons.
- Carbon capture and storage site characterization:Offshore CCS reservoir monitoring requires 4D seismic baseline surveys, opening adjacent revenue streams using existing vessel capabilities with modified sensor configurations.
- EU Green Deal maritime decarbonization incentives:Fleet operators retrofitting to methanol or ammonia-ready propulsion can access preferential financing through European Investment Bank green lending facilities.
Industry Challenges
- Marine seismic geophysicist talent scarcity:Specialized processing and acquisition design expertise has atrophied during industry downturns, constraining operational scaling for complex 4D programs.
- Port state control inspection backlogs:Extended certification timelines for modified propulsion systems in Singapore and Rotterdam are delaying vessel redeployment and compressing effective utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seismic Vessels Market |
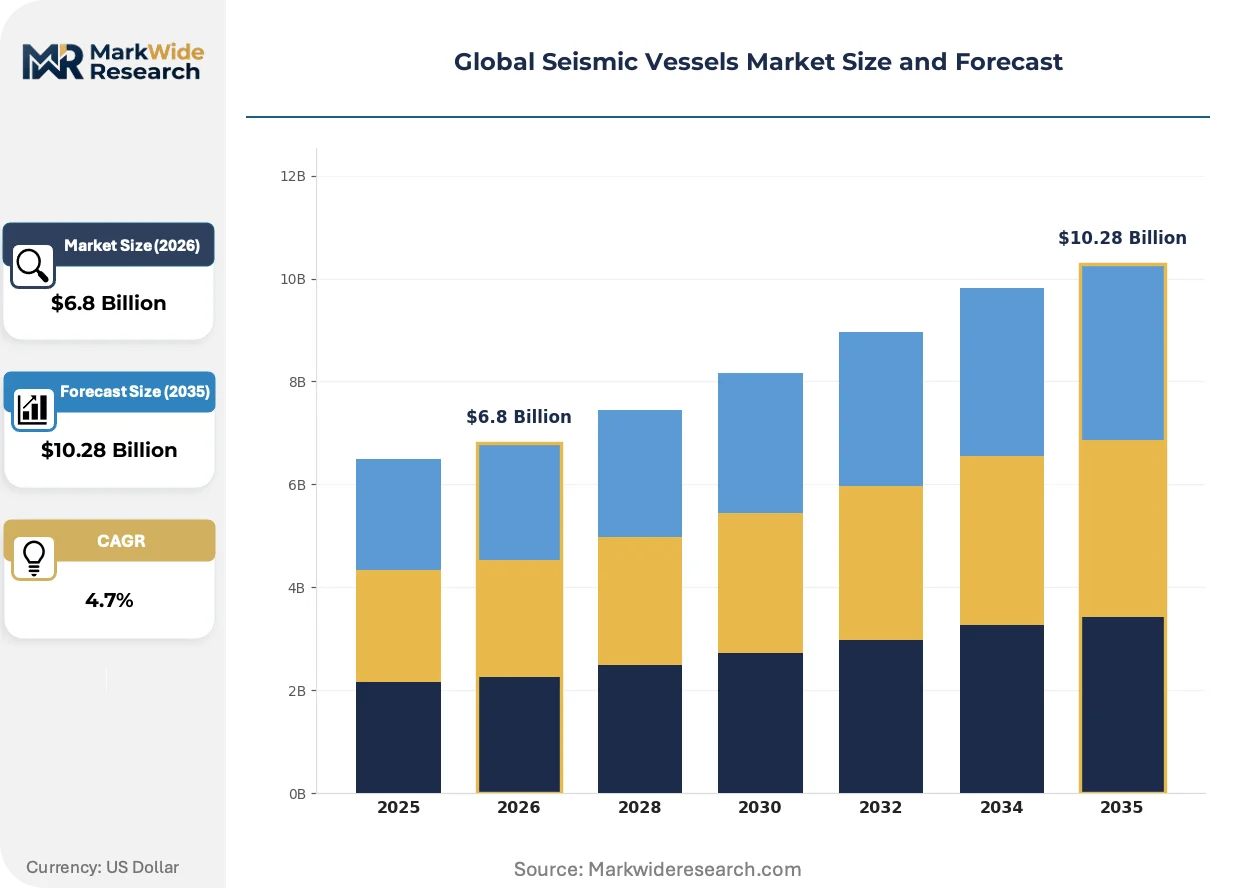
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Streamer Vessels, Ocean Bottom Nodes, Autonomous Underwater Vehicles, Towed Sensor Arrays, Cable Layer Ships, Support Vessels Technology: 2D Seismic Acquisition, 3D Seismic Acquisition, 4D Seismic Acquisition, Multi-Client Surveys, Electromagnetic Surveys, Hydrophone Arrays Application: Hydrocarbon Exploration, Subsea Mapping, Geological Surveying, Environmental Monitoring, Reservoir Characterization, Geophysical Research End User: Exploration Companies, Marine Geophysical Firms, Oilfield Service Providers, National Geological Institutes, Energy Consultants, Offshore Contractors |
| Companies Covered | PGS, CGG, SLB, TGS, Halliburton, Ulstein Group ASA, Damen Shipyards Group, Cemre Shipyard, Swire Pacific Offshore Operations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seismic Vessels Market Shifts & Advancements
Acoustic source and receiver technologies are converging with autonomous deployment systems to reshape acquisition economics and survey geometries. Regulatory pressure on maritime emissions is simultaneously forcing propulsion architecture changes and creating competitive differentiation through compliance timing.
Variable-depth streamer technology with calibrated broadband response is supplanting conventional flat-streamer spreads in high-resolution 3D programs. Frontier basin operators in Brazil and West Africa are adopting these configurations to resolve complex salt geometries and pre-salt reservoirs. The technology is compressing survey duration requirements while improving subsurface image fidelity, enabling contractors to bid shorter programs at equivalent data quality.
EU Green Deal maritime decarbonization frameworks are mandating carbon intensity indicator reporting for vessels calling at European ports. Fleet operators must document fuel consumption and operational efficiency metrics to maintain market access for North Sea and Mediterranean programs. Norwegian-registered contractors are responding with engine retrofit commitments announced ahead of regulatory deadlines to secure preferential charter terms.
Multiclient pre-funding models are displacing proprietary acquisition contracting as the dominant commercial structure for frontier basin programs. Exploration companies in Namibia and Suriname are pooling capital to license speculative survey data rather than commissioning exclusive vessel time. This pattern concentrates margin pools with contractors possessing balance sheet capacity to absorb pre-drilling risk and extended data sales cycles.
Global Seismic Vessels Market Segmentation
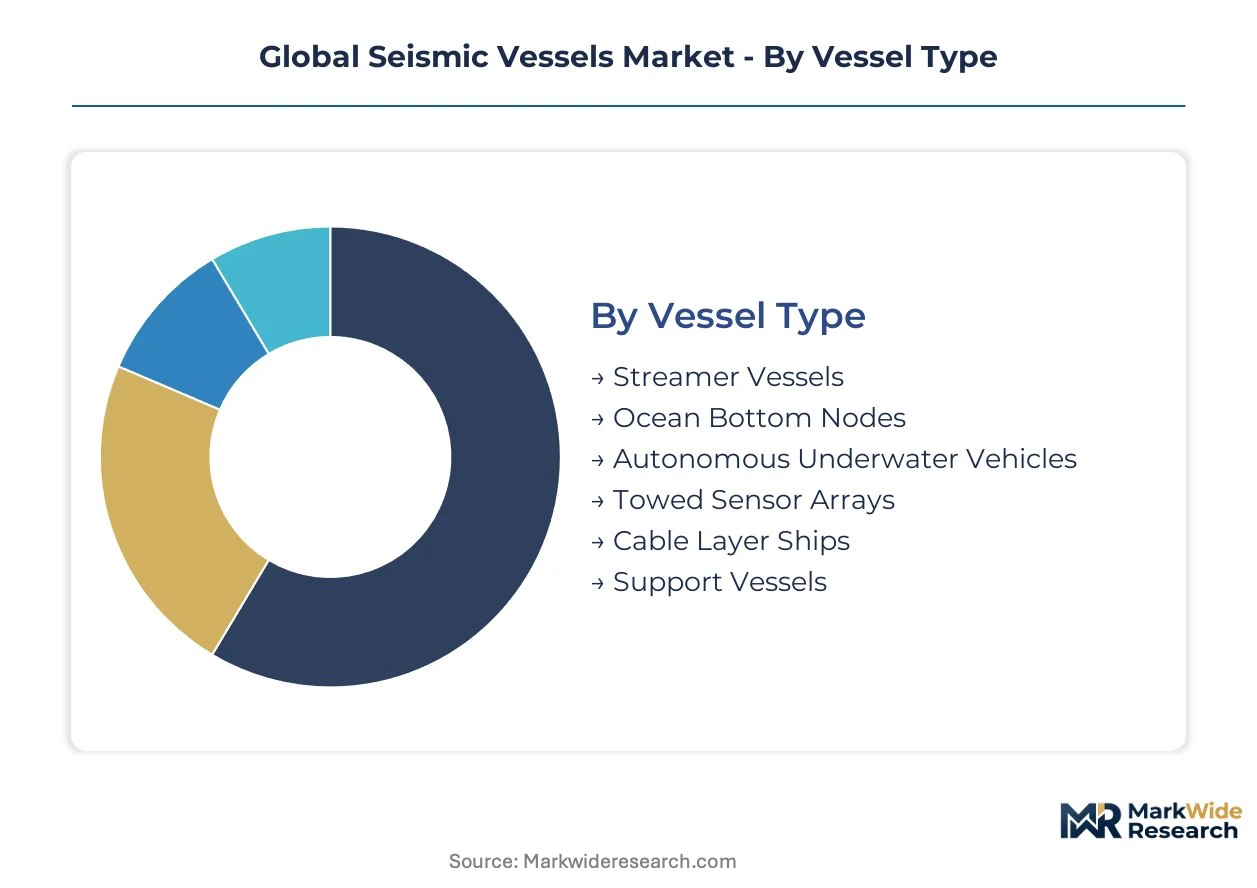
Seismic vessel segmentation reveals how acquisition economics bifurcate across technology tiers and commercial models. Channel pathways diverge sharply between proprietary contracting for oil majors and pre-funded multiclient licensing to exploration independents.
Vessel Type:
Channel concentration varies dramatically by hull specification, with premium tonnage flowing through long-term charter agreements while specialist vessels deploy through project-specific procurement.
- Streamer Vessels:Conventional hulls tow hydrophone arrays on cables extending 6-12 kilometers astern, operating at 4-5 knot survey speeds. Demand concentrates in Brazil's Santos Basin and Norway's North Atlantic licensing rounds where super-wide tow spreads justify premium day-rates for 3D/4D programs.
- Ocean Bottom Nodes:Autonomous sensor packages deploy to seabed for complex geometries inaccessible to streamer spreads. West Africa's pre-salt imaging and Gulf of Mexico salt canopy surveys in the United States are driving fastest adoption as autonomous retrieval systems compress deployment economics.
- Autonomous Underwater Vehicles:Self-propelled sensor platforms survey confined geometries without surface tethering.
- Towed Sensor Arrays:Variable-depth streamer configurations with calibrated broadband response.
- Cable Layer Ships:Hybrid hulls supporting both seismic and subsea infrastructure installation.
- Support Vessels:Supply and crew transfer craft enabling continuous offshore operations.
By volume, streamer vessels lead fleet deployment. By growth pace, ocean bottom nodes are expanding most quickly.
Technology:
Cost tier stratification separates mature 2D/3D acquisition from premium 4D and multiclient data licensing with fundamentally different margin structures.
- 3D Seismic Acquisition:Multi-azimuth source-receiver geometries generate volumetric subsurface models through dense spatial sampling. Norway's Barents Sea licensing and United States Gulf of Mexico lease sales sustain contracting velocity for high-specification 3D programs with shorter duration bids enabled by broadband streamer technology.
- 4D Seismic Acquisition:Time-lapse surveys repeat 3D geometries to monitor reservoir fluid movement during production. North Sea operators in Norway and United Kingdom field developments require repeat surveys for enhanced oil recovery optimization, creating recurring revenue streams distinct from exploratory acquisition.
- 2D Seismic Acquisition:Single-profile reconnaissance surveys for frontier basin screening.
- Multi-Client Surveys:Pre-funded speculative acquisition with post-survey data licensing.
- Electromagnetic Surveys:Controlled-source EM for resistivity contrast imaging.
- Hydrophone Arrays:Pressure-sensor streamers for acoustic signal detection.
By revenue concentration, 3D acquisition dominates current contracting. By margin expansion, multiclient surveys are climbing the fastest.
Application:
Customer type determines procurement channel, with national oil companies favoring proprietary contracting and independents accessing data through licensing pools.
- Hydrocarbon Exploration:Subsurface mapping for drillable prospect identification remains the core revenue driver. Brazil's ANP licensing rounds and Namibia's frontier basin activity concentrate demand for speculative survey programs with extended sales horizons.
- Reservoir Characterization:Detailed property modeling for field development planning and production optimization. North Sea mature basin operators in Norway and United Kingdom require repeat 4D surveys, creating annuity-like contracting distinct from exploratory volatility.
- Subsea Mapping:Bathymetric and shallow hazard surveys for route engineering.
- Geological Surveying:Academic and governmental crustal structure research.
- Environmental Monitoring:Baseline and operational impact assessment surveys.
- Geophysical Research:Academic and institutional pure science programs.
By contract value, hydrocarbon exploration leads. By recurrence reliability, reservoir characterization shows steepest expansion trajectory.
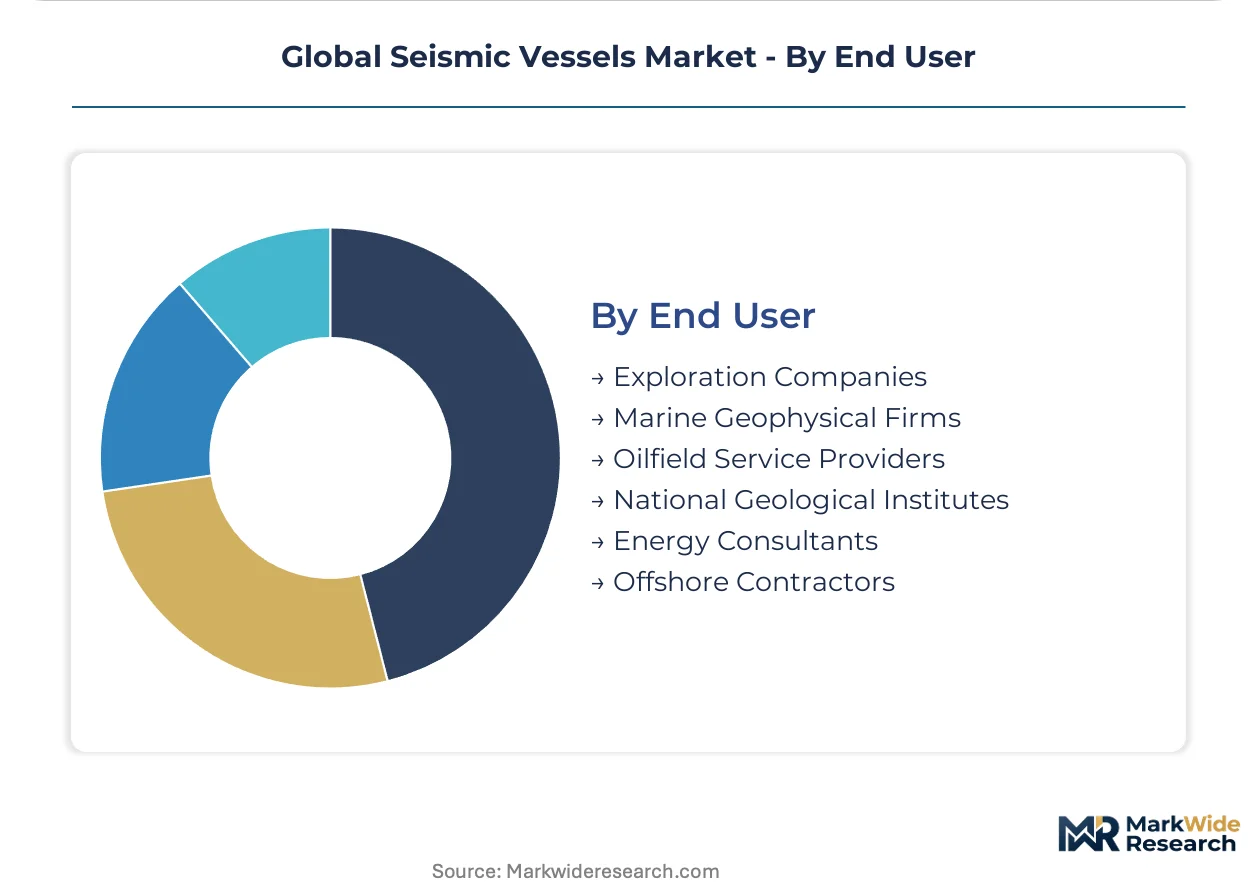
End User:
Supply concentration shapes channel access, with three Norwegian-flagged operators controlling premium tonnage distribution to major exploration companies.
- Exploration Companies:International and national oil companies commission proprietary surveys or license multiclient data. United States independents in the Gulf of Mexico and Brazilian operators in the pre-salt drive contracting velocity through ANP lease round timing.
- Marine Geophysical Firms:Specialist contractors operating owned or chartered vessel fleets. These firms concentrate in Norway's Stavanger and Bergen clusters, creating geographic supply bottlenecks for high-specification programs in West Africa and the North Atlantic.
- Oilfield Service Providers:Integrated energy service companies bundling seismic with drilling and completion.
- National Geological Institutes:Governmental survey organizations for resource assessment.
- Energy Consultants:Advisory firms commissioning targeted studies for client evaluation.
- Offshore Contractors:Installation companies requiring seabed characterization for engineering.
By vessel utilization, exploration companies absorb the majority of premium tonnage. By procurement innovation, marine geophysical firms are gaining share fastest through pre-funded multiclient structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in seismic vessel contracting tilt toward net service exporters, with Norway and the United States running structural surpluses in high-specification tonnage while Brazil and West African markets absorb chartered capacity through pre-salt and frontier basin programs.
Norway
Stavanger and Bergen harbor Europe's densest concentration of marine geophysical contractors, with Norwegian-flagged fleets commanding premium day-rates for 4D reservoir monitoring in the North Sea. IMO MARPOL Annex VI compliance deadlines are accelerating dual-fuel retrofit schedules at yards in Alesund and Ulsteinvik. The country's national petroleum regulator enforces strict environmental standards that determine market access for Barents Sea licensing rounds.
United States
Gulf of Mexico lease sales sustain contracting velocity for 3D acquisition programs, with Houston serving as the primary chartering hub for independents and majors alike. The US Coast Guard enforces safety and environmental compliance standards that filter contractor participation in federal waters. Port Fourchanel and Pascagoula concentrate vessel provisioning and crew rotation logistics for Caribbean and Atlantic-margin deployments.
Brazil
ANP licensing rounds for Santos Basin pre-salt blocks are pre-funding multiclient survey programs before acquisition commences. The country's national petroleum regulator mandates local content requirements that shape vessel chartering structures and crew composition. Rio de Janeiro anchors the operational coordination for Atlantic-margin programs extending into frontier basins offshore French Guiana.
United Kingdom
North Sea mature basin operators require repeat 4D surveys for enhanced oil recovery optimization, creating recurring revenue distinct from exploratory volatility. The North Sea Transition Authority oversees decommissioning and carbon storage site characterization that opens adjacent seismic demand. Aberdeen maintains its position as the primary technical services cluster for North Atlantic programs.
Singapore
The port city functions as the primary maintenance and retrofit hub for Asia-Pacific flagged tonnage, with drydock capacity supporting engine modifications for IMO compliance. Port state control inspection backlogs for modified propulsion systems are delaying vessel redeployment schedules. Jurong Shipyard and Sembcorp Marine facilities handle dual-fuel conversions for contractors operating across Southeast Asian and Australian waters.
Global Seismic Vessels Market Competitive Landscape
Listed leaders compete with private specialists across capital access and chartering flexibility, with publicly traded contractors leveraging balance sheet capacity for multiclient pre-funding while private operators optimize utilization through spot-market responsiveness. The competitive set fragments across three tiers: integrated energy service conglomerates with captive seismic equipment production, pure-play marine geophysical contractors with owned premium tonnage, and specialized shipyards with forward orderbooks for high-specification newbuilds. Dominant competitive moves include fleet modernization through engine retrofits and strategic positioning in frontier basin multiclient pre-funding.
Among Norway-based marine geophysical specialists, PGS and CGG exemplify the premium-tonnage archetype with differentiated hull architectures and proprietary acquisition technologies. SLB represents the integrated energy service model with in-house seismic equipment production paired with vessel operations. These three contractors anchor the high-specification segment where super-wide tow spreads and broadband streamer configurations command rate premiums in Brazil and West Africa.
| Leading Market Players |
|---|
| PGS |
| CGG |
| SLB |
| TGS |
| Halliburton |
| Ulstein Group ASA |
| Damen Shipyards Group |
| Cemre Shipyard |
| Swire Pacific Offshore Operations |
| Others |
Supply & Pricing Matrix
Dual-fuel propulsion retrofits replacing conventional marine diesel architectures are redrawing supply geography toward Norwegian and Singaporean shipyards while compressing day-rate premiums for legacy tonnage. Steel hull construction and seismic sensor array costs feed directly into newbuild pricing, with frontier basin operators in Brazil and Namibia absorbing higher charter rates to secure IMO-compliant vessels.
Pricing Analysis
Industrial OEM buyers anchor project-based contracting structures where day-rates stratify across premium, standard, and economy vessel tiers. Price differentiation hinges on broadband streamer capability and dual-fuel certification grade, with Norwegian-flagged premium tonnage commanding widest spreads. Cost compression in legacy streamer segments is intensifying as autonomous ocean-bottom node systems displace conventional spreads. National oil companies exhibit lowest price sensitivity due to pre-funded multiclient structures, while exploration independents in the Gulf of Mexico face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites sensor array logistics for Asia-Pacific fleet deployments. Hull construction draws from South Korean and Chinese shipyards, while specialized seismic equipment sources from Norway and the United States. Single-source vulnerability concentrates in Norwegian marine geophysicist talent pools for acquisition design. Distribution runs through Stavanger and Houston chartering hubs with regional provisioning at Port Fourchanel and Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seismic vessel market traces a cyclical recovery pattern anchored to offshore licensing round timing, with Brazil's ANP pre-salt auctions and Namibia's frontier basin activity driving chartering velocity.
For Market Incumbents: Compound fleet modernization advantages by accelerating dual-fuel retrofit commitments ahead of IMO MARPOL Annex VI deadlines. Secure long-term charter agreements with national oil companies in Brazil and Norway to lock in utilization rates against emerging spot-market volatility from autonomous node systems. For New Entrants and Emerging Players: Anchor in carbon capture and storage site characterization services using modified 4D vessel configurations, the least penetrated application segment with adjacent revenue potential. Target frontier basin multiclient pre-funding in Suriname and Guyana through speculative survey partnerships with exploration independents lacking proprietary vessel access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed marine geophysical specialists holding aging streamer fleets ripe for consolidation. Long-term viability across the analysis window favors contractors with balance sheet capacity for green financing access through European Investment Bank facilities. Watch autonomous retrieval system adoption rates as the inflection signal distinguishing premium from stranded tonnage.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Retrofit Program | IMO MARPOL Annex VI compliance secures market access for Norwegian-flagged fleets in European waters. |
| Multiclient Pre-Funding Model | Frontier basin speculation in Namibia shifts risk-return profiles toward data licensing margin pools. |
| Autonomous Node Integration | AUV deployment systems expand addressable survey geometries in West Africa's complex pre-salt environments. |
| Carbon Storage Service Line | 4D baseline surveys for CCS reservoir monitoring open adjacent revenue streams using existing vessel capabilities. |
| Green Financing Facility Access | European Investment Bank preferential lending supports methanol-ready propulsion investments ahead of regulatory deadlines. |
Research Methodology
Desk research of vessel registration databases, IMO compliance filings, and ANP licensing round documentation preceded structured interviews with fleet operations directors, chartering managers at exploration companies, marine geophysicists, shipyard project engineers, and port state control inspectors. Secondary validation drew from customs trade data, Lloyd's List intelligence, and national petroleum regulator disclosures. Bottom-up fleet utilization modeling triangulated against top-down multiclient revenue estimates.
Variance decomposition across vessel type, technology tier, application segment, and end-user category shaped the analytical framework over the projection horizon. CAGRs derived from segmented demand modeling incorporating frontier basin licensing schedules, engine retrofit cycle timing, and autonomous system adoption curves. Industry-specific inputs included day-rate elasticity estimates and pre-funding penetration rates by basin.
Material uncertainties — commodity steel price swings, port state control inspection backlogs, and regulatory acceleration of carbon intensity indicators — sit outside the modeled envelope. Forecasts reflect assumptions on fleet replacement timing and multiclient sales velocity. Practitioners should keep alternative scenarios live as IMO decarbonization enforcement timelines and frontier basin drilling results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Subsea Trencher Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market