
 Crawler Drilling Machine Market | 2026-2036
Crawler Drilling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Crawler Drilling Machine Market Intelligence
The EU Green Deal's embedded carbon benchmarking for capital equipment is pivoting procurement specifications across European tunneling consortia. Sandvik AB leverages its battery-electric drill platform to anchor premium positioning in Scandinavian infrastructure tenders. Atlas Copco competes through aftermarket service density, while Epiroc differentiates via autonomous drill rig integration for subterranean operations.
Crawler drilling machines are self-propelled tracked rigs engineered to deliver rotational torque and percussive force through telescoping masts, typically achieving bore diameters from 50 mm to 400 mm in consolidated rock formations. Hydraulic drilling configurations dominate mining excavations due to superior power-to-weight ratios in hard-rock penetration, whereas rotary percussion systems lead geotechnical investigations where rapid soil sampling drives contract economics. Electric drilling variants are gaining share in underground applications where ventilation constraints limit diesel deployment.
EPA Tier 4 Final emission mandates in the United States and MEE air quality standards in China are forcing engine retrofit cycles and accelerating electric platform development. REACH compliance for hydraulic fluids and RoHS material restrictions further constrain component sourcing across OECD supply chains. Stakeholders must monitor regulatory divergence between diesel phase-out timelines and charging infrastructure readiness in target mining jurisdictions.
Market Dynamics
The transition from diesel to battery-electric powertrains in underground mining is compressing equipment replacement cycles and forcing capital redeployment across fleet operators. Tightening particulate emission limits in Australia, Scandinavia, and Chile are rendering legacy rigs economically obsolete before mechanical end-of-life.
Growth Catalysts
- EPA Tier 4 Final mandates:US surface mining operators face accelerated fleet turnover as non-compliant diesel engines lose resale liquidity and financing access.
- Copper belt mechanization:Chilean state-owned miners are replacing pneumatic rigs with hydraulic crawler units to access deeper ore bodies with fewer ventilation constraints.
- Battery-electric tunneling:Scandinavian infrastructure consortia specify zero-emission drilling platforms for urban transit projects with confined ventilation shafts.
Market Restraints
- High-voltage battery supply concentration:Cell production for 300 kWh+ mining equipment packs clusters in China, exposing European and North American OEMs to tariff and logistics volatility.
- Hard-rock penetration limitations:Electric rotary-percussion systems still underperform diesel-hydraulic rigs in unconfined compressive strength formations above 250 MPa.
- REACH hydraulic fluid compliance:Biodegradable synthetic alternatives for closed-loop systems cost 40-60% more than mineral oil basestocks, inflating operating expenditure forecasts.
Strategic Opportunities
- EU Green Deal embedded carbon benchmarking:Tunneling contractors in Germany and Austria now score equipment procurement on lifecycle emissions, favoring suppliers with verified battery supply chains.
- Autonomous drill rig integration:Convergence of machine vision and drill string telemetry enables single-operator supervision of multiple units in subterranean operations.
- Indian hard-rock mining expansion:The country's national mining regulator is fast-tracking environmental clearances for underground zinc and copper projects, opening import demand for emission-compliant rigs.
Industry Challenges
- Electrification skill gaps:Maintenance technicians trained on diesel powertrains lack certification for high-voltage battery management and thermal runaway containment protocols.
- Charging infrastructure capex:Underground mine electrification requires megawatt-scale surface substations and trailing cable systems that extend project payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crawler Drilling Machine Market |
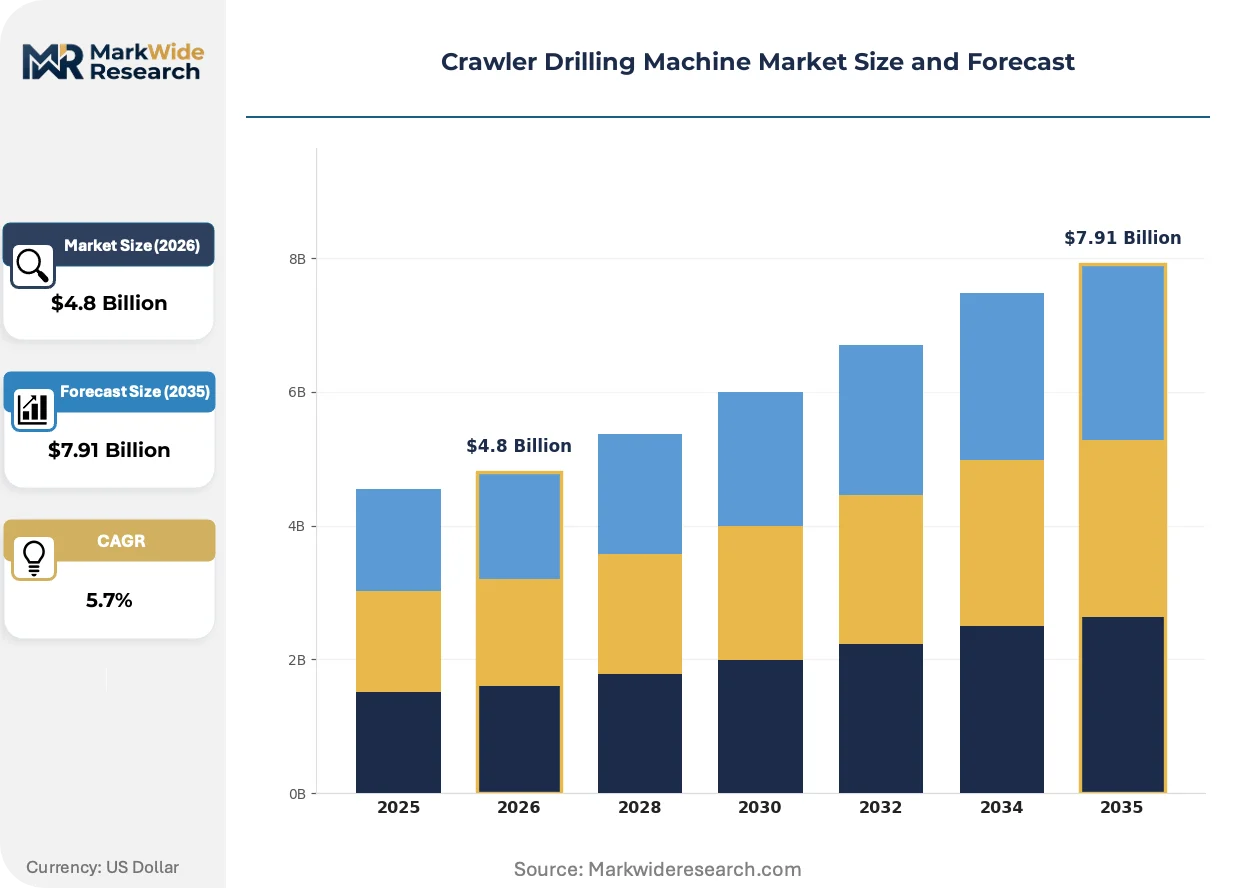
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Hydraulic Drilling, Pneumatic Drilling, Electric Drilling, Rotary Drilling, Top Hammer, Down The Hole Drilling Technology: Diamond Drilling, Rotary Percussion, Coring, Auger Drilling, Reverse Circulation, Sonic Drilling Application Area: Mining Excavations, Construction Projects, Quarrying Sites, Geotechnical Investigations, Oil & Gas Wells, Environmental Sampling End User Industry: Mineral Extraction Firms, Civil Engineering Companies, Energy Exploration Entities, Geological Survey Agencies, Infrastructure Developers, Research Institutions |
| Companies Covered | Sandvik AB, Atlas Copco, Caterpillar, Epiroc, SANY, Soilmec S.p.A., Furukawa Rock Drill, Jupiter Rock Drills, Acker Drill Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crawler Drilling Machine Market Strategic Shifts & Innovations
Powertrain electrification is fragmenting the competitive landscape between incumbent hydraulic specialists and battery system integrators. Control system digitization and remote operation capabilities are becoming baseline specifications rather than premium options.
Telematics-enabled predictive maintenance is overtaking scheduled interval servicing as the dominant fleet management paradigm. Mining contractors in Western Australia now demand continuous drill string vibration monitoring and bit-wear algorithms to eliminate unplanned downtime. This capability compression is forcing smaller rental fleet operators to outsource diagnostics to OEM service networks or exit the market entirely.
China's MEE air quality standards for non-road mobile machinery are tightening particulate matter limits in stages through 2025. Domestic mining equipment purchasers face import restrictions on engines above Stage IV emission equivalents. Local OEMs are responding with parallel hybrid architectures that pair downsized diesels with electric boost systems to maintain penetration rates in granite quarries.
Contracting structures for tunneling projects are unbundling equipment ownership from operational responsibility. Scandinavian infrastructure developers now procure drilled meters rather than machine hours, transferring utilization risk to drilling contractors. This shift concentrates demand among fleet operators with balance sheet capacity for asset-heavy positions and certified maintenance capabilities.
Crawler Drilling Machine Market Segmentation
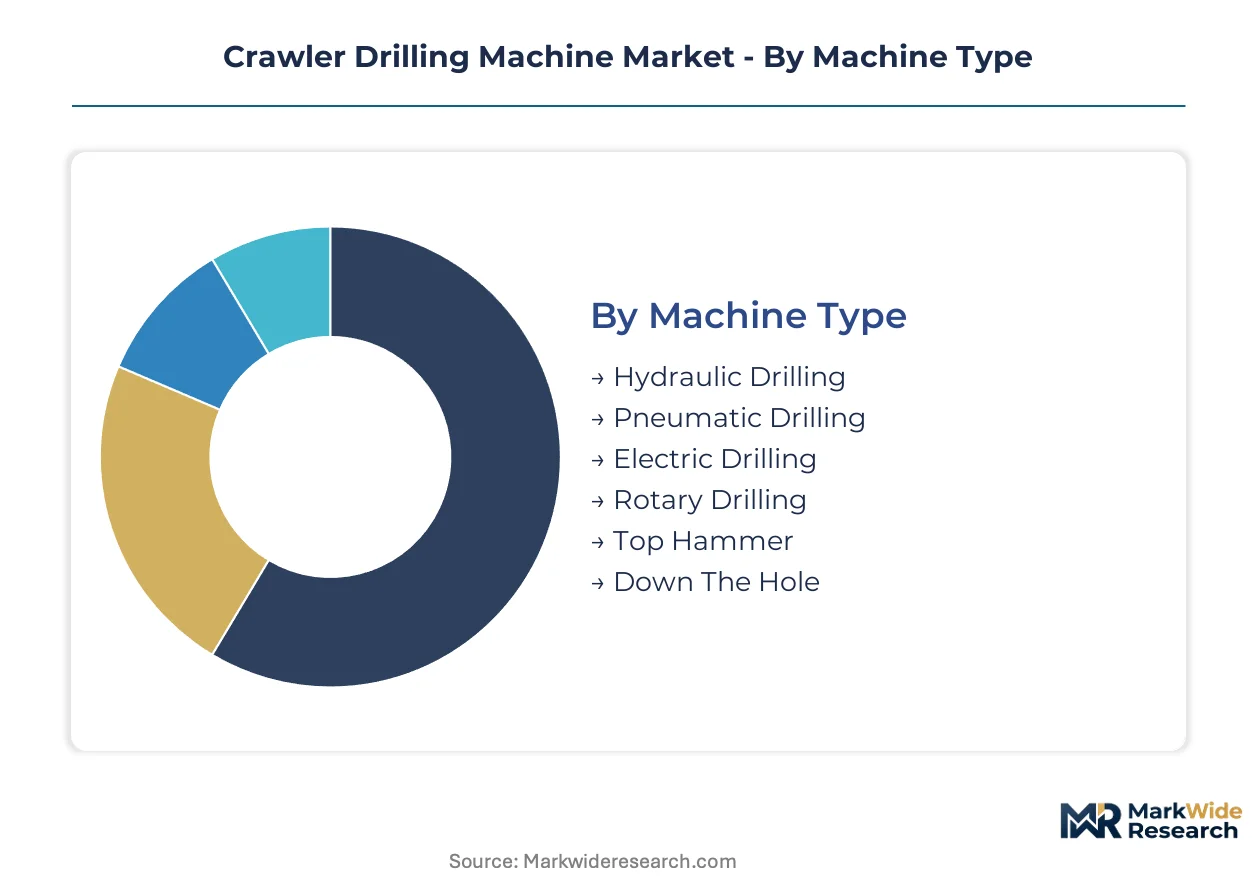
Crawler drilling machines segment across multiple technical and commercial dimensions that determine procurement specifications, operating economics, and regulatory compliance pathways. Understanding these divisions reveals where capital concentrates and which technologies command premium positioning.
Machine Type:
Certification burdens vary sharply by powertrain: EPA Tier 4 Final and EU Stage V compliance for diesel-hydraulic units demands exhaust after-treatment systems, while battery-electric platforms face IEC 62619 cell safety validation and mine-specific explosion protection ratings.
- Hydraulic Drilling:Diesel-hydraulic configurations deliver rotational torque through closed-loop piston pumps, achieving penetration rates exceeding 3 meters per minute in granite formations. Demand concentrates in Chilean copper belt expansions where Codelco and BHP prioritize emission-compliant fleet replacements over pneumatic legacy rigs. Tier 4 Final retrofit costs and resale liquidity constraints are compressing replacement cycles.
- Electric Drilling:Battery-electric platforms eliminate diesel particulate exposure in confined headings, using 300-600 kWh liquid-cooled packs with thermal runaway containment. Scandinavian tunneling consortia in Stockholm and Oslo metro extensions specify zero-emission platforms to avoid ventilation shaft construction delays. IEC 62619 certification and mine-specific explosion protection ratings add 12-18 months to type approval timelines.
- Pneumatic Drilling:Compressed-air systems retain niche deployment in shallow quarrying where ventilation is unrestricted and capital budgets are constrained.
- Rotary Drilling:Large-diameter rotary tables dominate water well and geothermal applications requiring continuous core recovery.
- Top Hammer:Percussive drilling through the drill string suits bench blasting in open-pit limestone and aggregate operations.
- Down The Hole:Hammer mechanisms at the bit face improve energy transfer efficiency in hard-rock blasthole drilling above 200 mm diameter.
Leading the category by volume: Hydraulic Drilling. Growing fastest: Electric Drilling.
Drilling Technology:
Technology selection follows formation hardness and sample integrity requirements, with cost tiers separating exploration-grade coring from production blasthole methods.
- Rotary Percussion:Combined rotation and percussive action fractures competent rock through tungsten carbide button bits, achieving penetration rates of 1-4 meters per minute depending on unconfined compressive strength. Australian iron ore miners in Western Australia's Pilbara region specify rotary-percussion rigs for 311 mm production blastholes, with autonomous drill rig integration reducing operator exposure to dust and noise hazards.
- Diamond Drilling:Impregnated or surface-set diamond bits cut continuous core samples for geological logging and resource estimation. Canadian gold exploration juniors in Quebec's Abitibi greenstone belt demand HQ and NQ wireline coring systems to minimize sample disturbance and maximize recovery percentages.
- Coring:Conventional and wireline retrieval methods preserve sample integrity for metallurgical testing and geotechnical characterization.
- Auger Drilling:Continuous flight augers suit unconsolidated overburden and soft soil investigations where sample disturbance is acceptable.
- Reverse Circulation:Dual-wall drill rods return cuttings through the inner tube for rapid sample collection in near-mine exploration.
- Sonic Drilling:High-frequency vibration enables continuous core recovery through unconsolidated formations and heaving sands.
Widest deployment: Rotary Percussion. Steepest expansion trajectory: Diamond Drilling.
Application Area:
Application segmentation tracks capital cycle timing, with mining excavations commanding multi-rig fleet orders and environmental sampling driving single-unit spot purchases.
- Mining Excavations:Production drilling for blasthole patterns, slot raises, and ore pass development requires rigs rated for 24-hour continuous operation in headings as narrow as 3.5 meters. Underground operations in Australia's Mount Isa and Kalgoorlie districts are expanding fleet renewals as state diesel particulate exposure standards tighten.
- Geotechnical Investigations:Standard penetration testing, cone penetration testing, and inclined boreholes for slope stability assessment demand portable rigs with rapid mobilization. Infrastructure developers in Germany's Stuttgart 21 rail project and Austria's Brenner Base Tunnel specify drilled-meter contracting rather than equipment rental to transfer utilization risk.
- Construction Projects:Foundation piling, anchor installation, and ground improvement drilling support urban high-rise and transportation infrastructure.
- Quarrying Sites:Bench blasting and aggregate production favor high-availability hydraulic rigs with simplified maintenance protocols.
- Oil & Gas Wells:Slim-hole exploration and geothermal gradient drilling use modified crawler carriers for remote pad locations.
- Environmental Sampling:Monitoring well installation and contaminated site characterization require hollow-stem auger and direct push methods.
Revenue concentration: Mining Excavations. Gaining share fastest: Geotechnical Investigations.
End User Industry:
Customer type determines procurement sophistication, with mineral extraction firms operating captive maintenance infrastructure and research institutions outsourcing all operational responsibility.
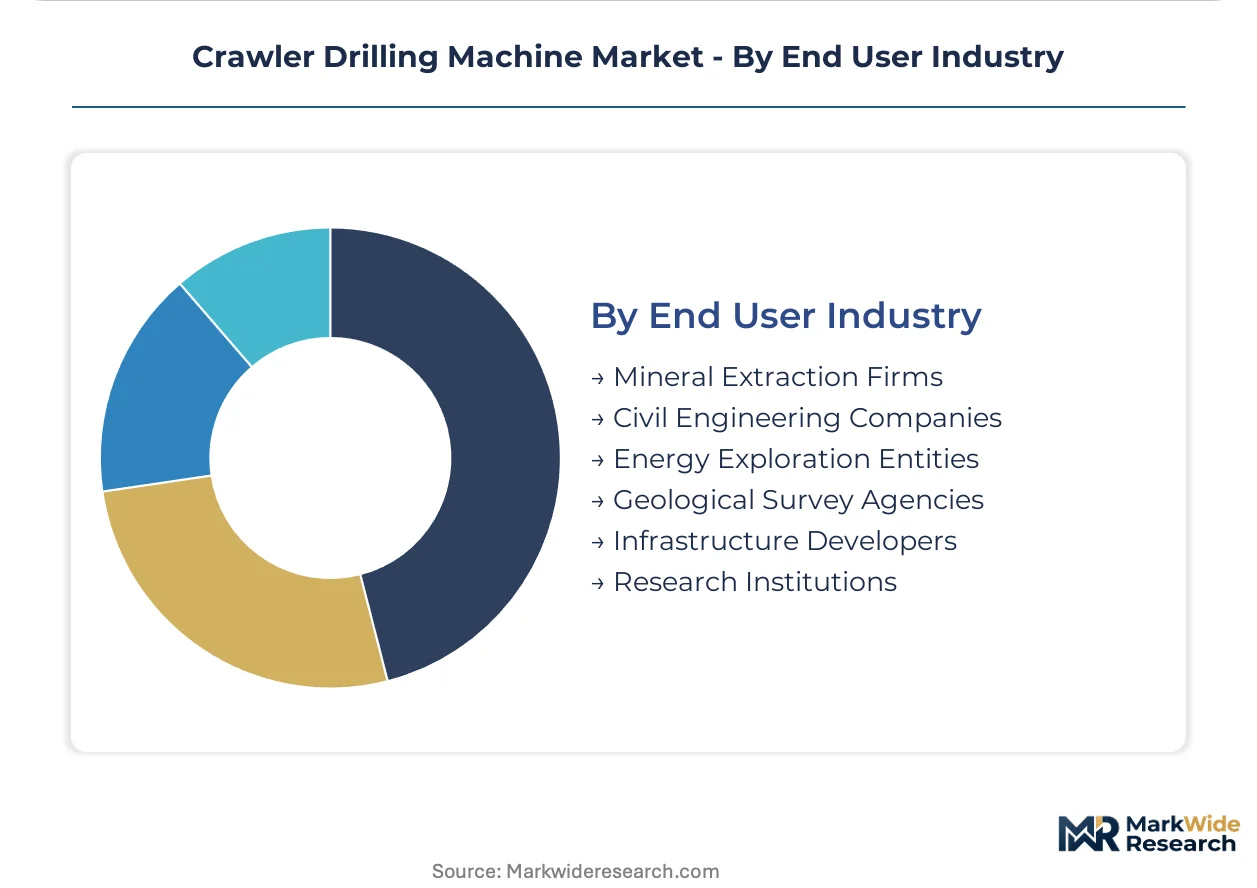
- Mineral Extraction Firms:Integrated miners and contract mining operators deploy fleets of 10-50 rigs with centralized maintenance facilities and OEM service agreements. Chilean state-owned Codelco prioritizes emission-compliant rig replacements in its Chuquicamata underground transition and El Teniente deep ore body access projects.
- Civil Engineering Companies:Tunneling contractors and foundation specialists balance equipment ownership against rental flexibility based on project pipeline visibility. Scandinavian urban transit consortia in Copenhagen and Helsinki specify zero-emission platforms to satisfy municipal procurement scoring on lifecycle emissions.
- Energy Exploration Entities:Geothermal developers and unconventional gas operators require hybrid drilling systems adaptable between slim-hole exploration and production well completion.
- Geological Survey Agencies:National mapping programs and groundwater resource assessments favor multi-purpose rigs with rapid reconfiguration between coring and percussion modes.
- Infrastructure Developers:Rail, road, and dam project sponsors increasingly procure drilled meters rather than machine hours, concentrating demand among fleet operators with certified maintenance capabilities.
- Research Institutions:University and government research programs prioritize sample integrity and data quality over penetration rate, accepting higher per-meter costs for specialized coring services.
Volume leadership: Mineral Extraction Firms. Fastest-climbing demand: Civil Engineering Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's copper belt dominates crawler drilling machine deployment, with state-owned operators driving fleet renewal cycles as diesel particulate regulations tighten across underground operations.
Chile
Codelco's Chuquicamata underground transition and El Teniente deep ore body access projects prioritize emission-compliant hydraulic rig replacements. The country's Ministry of Mining enforces progressive diesel particulate exposure limits in subterranean headings. Antofagasta and Calama mining corridors concentrate demand for 24-hour continuous operation rigs rated for narrow 3.5-meter headings.
Australia
Western Australia's Pilbara iron ore miners specify autonomous rotary-percussion rigs for 311 mm production blastholes. State diesel particulate exposure standards in Mount Isa and Kalgoorlie districts are accelerating fleet renewals. Perth-based mining contractors demand continuous drill string vibration monitoring and bit-wear algorithms to eliminate unplanned downtime.
Sweden
Scandinavian tunneling consortia specify zero-emission battery-electric platforms for Stockholm and Oslo metro extensions to avoid ventilation shaft construction delays. The EU Green Deal's embedded carbon benchmarking pivots procurement specifications across infrastructure tenders. Sandviken and Örebro industrial clusters anchor premium positioning for battery-electric drill platforms.
United States
EPA Tier 4 Final mandates force accelerated fleet turnover as non-compliant diesel engines lose resale liquidity and financing access. Surface mining operators in Arizona and Nevada face compressed replacement cycles for exhaust after-treatment retrofits. Elko and Tucson mining equipment distribution hubs concentrate aftermarket service density competition.
China
MEE air quality standards for non-road mobile machinery tighten particulate matter limits through 2025, restricting import engines above Stage IV emission equivalents. Domestic OEMs deploy parallel hybrid architectures pairing downsized diesels with electric boost systems. Zhengzhou and Xuzhou manufacturing clusters respond with localized production of emission-compliant mining rigs.
Crawler Drilling Machine Market Key Industry Players
The competitive structure tilts toward integrated mining equipment conglomerates with captive hydraulic system capabilities. Tiered specialization separates full-line underground specialists from surface-focused blasthole rig fabricators. Strategic archetypes include battery-electric platform pioneers, aftermarket service network operators, and autonomous drill rig integrators. Dominant competitive moves encompass geographic expansion into Indian hard-rock mining and strategic partnerships for high-voltage battery supply security.
Among Swedish-based mining technology groups, Sandvik AB and Epiroc occupy positions at the premium-tier battery-electric and autonomous integration vectors. Atlas Copco represents the aftermarket service density archetype. Chinese fabricators SANY and Zhengzhou Shuli Machinery Co., Ltd. exemplify scale-driven positioning in emission-compliant domestic market supply. Furukawa Rock Drill and Soilmec S.p.A. anchor regional specialization in hard-rock penetration and geotechnical investigation segments respectively.
| Leading Market Players |
|---|
| Sandvik AB |
| Atlas Copco |
| Caterpillar |
| Epiroc |
| SANY |
| Soilmec S.p.A. |
| Furukawa Rock Drill |
| Jupiter Rock Drills |
| Acker Drill Company |
| Others |
Cost & Logistics Intelligence
Chilean state-owned mining operators concentrate procurement power through multi-rig fleet tenders, anchoring value-based contracting where drilled-meter outcomes command premium positioning over equipment ownership. This buyer concentration compresses margins for rental fleet operators while elevating certified maintenance capabilities as the decisive pricing tier.
Pricing Analysis
Drilled-meter contracting anchors value-based pricing for Scandinavian tunneling consortia and Australian iron ore miners, with outcomes measured by penetration rate and uptime guarantees rather than machine-hour rates. Price differentiation separates Tier 4 Final emission-compliant hydraulic rigs from legacy diesel units facing resale liquidity collapse, while battery-electric platforms command 15-25% premiums justified by ventilation cost avoidance. Cost compression in the rental fleet tier intensifies as telematics-enabled predictive maintenance becomes baseline, forcing smaller operators toward OEM service outsourcing or exit. Mineral extraction firms show lowest price sensitivity given captive maintenance infrastructure, whereas geotechnical investigation contractors face acute margin pressure from drilled-meter risk transfer.
Supply Chain Analysis
Freight costs for 40-ton crawler carriers and telescoping masts constrain OEM distribution economics, favoring regional assembly hubs over centralized manufacturing. Hydraulic system production concentrates in Germany, Sweden, and China, while high-voltage battery cell supply for 300-600 kWh mining packs clusters in China and South Korea. Raw material dependencies span tungsten carbide for drill bits, high-strength steel for masts, and lithium-nickel-manganese-cobalt cathode chemistries. Single-source vulnerability in battery management system semiconductors exposes European and North American OEMs to allocation risk. Distribution runs through manufacturer-direct sales for fleet orders above five units, with rental channels and aftermarket service networks covering spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-voltage battery supply concentration props pricing power for OEMs with secured cell offtake, constraining fleet expansion for operators lacking balance sheet capacity for asset-heavy positions.
For Market Incumbents: Acquire certified high-voltage battery service capabilities to anchor aftermarket revenue streams as electrification displaces diesel-hydraulic maintenance demand. Secure IEC 62619 validation partnerships ahead of type approval timeline compression for European tunneling tenders. Backward integration into thermal runaway containment system production reduces exposure to Chinese BMS semiconductor allocation constraints. For New Entrants and Emerging Players: Begin with Indian hard-rock mining expansion where environmental clearance acceleration outpaces domestic OEM emission-compliant supply. Target geotechnical investigation contracting in Germany and Austria where EU Green Deal embedded carbon scoring favors new entrants with verified battery supply chains. Pursue drilled-meter risk-bearing partnerships with infrastructure developers to bypass capital-intensive fleet ownership barriers. For Investors and Strategic Acquirers: The window for entry favors autonomous drill rig integrators with machine vision and telemetry convergence capabilities. Long-term viability hinges on exposure to copper belt mechanization cycles and battery-electric tunneling specification adoption. Watch for IEC 62619 certification backlog duration as the inflection signal separating premium-positioned OEMs from compliance-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Certification | IEC 62619 validation unlocks Scandinavian infrastructure tenders specifying zero-emission drilling. |
| Autonomous Drill Rig Integration | Machine vision convergence enables single-operator supervision of multiple units in Australian Pilbara operations. |
| High-Voltage Battery Supply Security | Cell offtake agreements with South Korean producers reduce exposure to Chinese tariff volatility. |
| Aftermarket Service Network Expansion | Certified maintenance capabilities capture revenue as telematics displaces scheduled interval servicing. |
| Drilled-Meter Contracting Capability | Risk-bearing positioning concentrates demand among fleet operators with balance sheet depth. |
Research Approach
Multi-period observation of fleet renewal cycles, emission regulation enforcement stages, and battery-electric adoption rates anchored the trend analysis, supplemented by interviews with mining equipment procurement directors, underground maintenance technicians, tunneling project managers, and OEM aftermarket service heads. Secondary validation drew from EPA Tier 4 Final enforcement data, EU Green Deal procurement scoring frameworks, MEE air quality standard phase-in schedules, and Chilean Ministry of Mining diesel particulate exposure limits. Bottom-up rig deployment counts across copper belt operations and top-down capital expenditure triangulation from state-owned miner disclosures were cross-referenced.
The input-output matrix mapped powertrain technology penetration against regulatory compliance timelines, drilling technology performance specifications, and end-user industry procurement sophistication. Segmentation dimensions spanned machine type, drilling technology, application area, and end-user industry, with regional regulatory clusters modeled separately. CAGRs were derived from fleet replacement cycle compression analysis and battery-electric platform adoption curves. Forecast inputs incorporated copper price sensitivity for Chilean state-owned operator capital allocation and ventilation shaft construction cost escalation for Scandinavian tunneling economics.
Underlying measurement precision varies by segment; battery-electric platform forecasts carry tighter precision given visible tender specifications, whereas pneumatic drilling trajectory depends on quarry capital budget volatility. Forecasts reflect assumptions regarding diesel phase-out timeline adherence and charging infrastructure deployment pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Rock Duster Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Mining Drill Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Logging Cable Market
Mining Equipment
DTH Drill Rig Market