
 Off Grid Solar Market | 2026-2036
Off Grid Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Off Grid Solar Market Intelligence
The application mix for off-grid solar systems is shifting from primarily residential lighting to more productive uses in agriculture and small commercial enterprises. Jinko Solar leverages its large-scale solar panel manufacturing to supply this segment with cost-effective modules. Schneider Electric specializes in providing integrated inverter and power management solutions for these more complex systems. M-KOPA Kenya dominates the pay-as-you-go financing model for home solar systems in East Africa, enabling access for low-income households.
Off-grid solar systems function as self-contained power generation units, independent of any utility grid infrastructure. These systems typically integrate photovoltaic panels with a specific DC voltage rating, a charge controller, and a battery bank for energy storage. Their primary purpose is to provide reliable electricity to locations where grid connection is unfeasible or cost-prohibitive. Within the product mix, demand for high-capacity batteries and efficient inverters is growing faster than for solar panels alone.
Regulatory frameworks are critical for market development. The US Inflation Reduction Act (IRA) provides tax credits that benefit off-grid installations, while the EU's Green Deal initiatives support renewable energy adoption. In parallel, IEC technical standards for solar components ensure product safety and interoperability across different manufacturers. Component suppliers must now decide whether to focus on standardized, low-cost products or specialized, high-performance systems for niche applications.
Market Dynamics
The off-grid solar market's core dynamic is the demand pivot from basic residential lighting to productive-use applications in agriculture and small enterprises. This shift necessitates higher-capacity, more complex systems, influencing technology development, financing models, and regulatory priorities across developing economies.
Growth Catalysts
- Favorable Government Policies:India's Production Linked Incentive (PLI) scheme for solar manufacturing is lowering domestic module costs, directly supporting the expansion of off-grid projects for agricultural and rural electrification initiatives within the country.
- Productive Use Demand:The need for reliable power for agricultural irrigation pumps and cold storage facilities in sub-Saharan Africa creates strong demand for off-grid solutions that enhance food security and generate rural income.
- Financial Innovation:Pay-as-you-go (PAYG) financing models, particularly prevalent in East African nations, remove the barrier of high upfront costs, enabling millions of low-income households to access solar home systems for the first time.
Market Restraints
- High Upfront Capital Costs:The initial investment for systems, especially those incorporating high-capacity lithium-ion batteries and powerful inverters required for productive uses, remains a significant barrier for end-users in low-income regions.
- Supply Chain Concentration:A heavy reliance on China for key components, including photovoltaic cells and battery materials, exposes the global market to price volatility and potential supply disruptions stemming from geopolitical tensions or trade policy shifts.
- Technical Intermittency:The inherent variability of solar generation requires oversized battery storage to ensure consistent power for critical applications like healthcare or commercial operations, increasing system complexity and overall cost for end-users.
Strategic Opportunities
- Energy-as-a-Service (EaaS) Models:Developing subscription-based services for productive use applications, such as solar-powered milling or welding equipment, offers a recurring revenue stream and lowers the entry barrier for small businesses.
- System Integration with IoT:Integrating Internet of Things (IoT) sensors for remote monitoring and predictive maintenance of off-grid systems creates opportunities for value-added services, improved reliability, and optimized asset performance.
- Geographic Expansion in Southeast Asia:Archipelagic nations like the Philippines and Indonesia present significant untapped markets, where deploying off-grid and mini-grid systems is more economically viable than extending the national grid to thousands of remote islands.
Industry Challenges
- Last-Mile Distribution Logistics:Establishing efficient and cost-effective supply chains to deliver products and provide after-sales service to remote, dispersed communities remains a significant operational hurdle for companies operating in regions with poor infrastructure.
- Technical Skills Gap:A shortage of qualified local technicians capable of designing, installing, and maintaining the more complex off-grid systems required for commercial and agricultural applications hinders market growth in many developing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off Grid Solar Market |
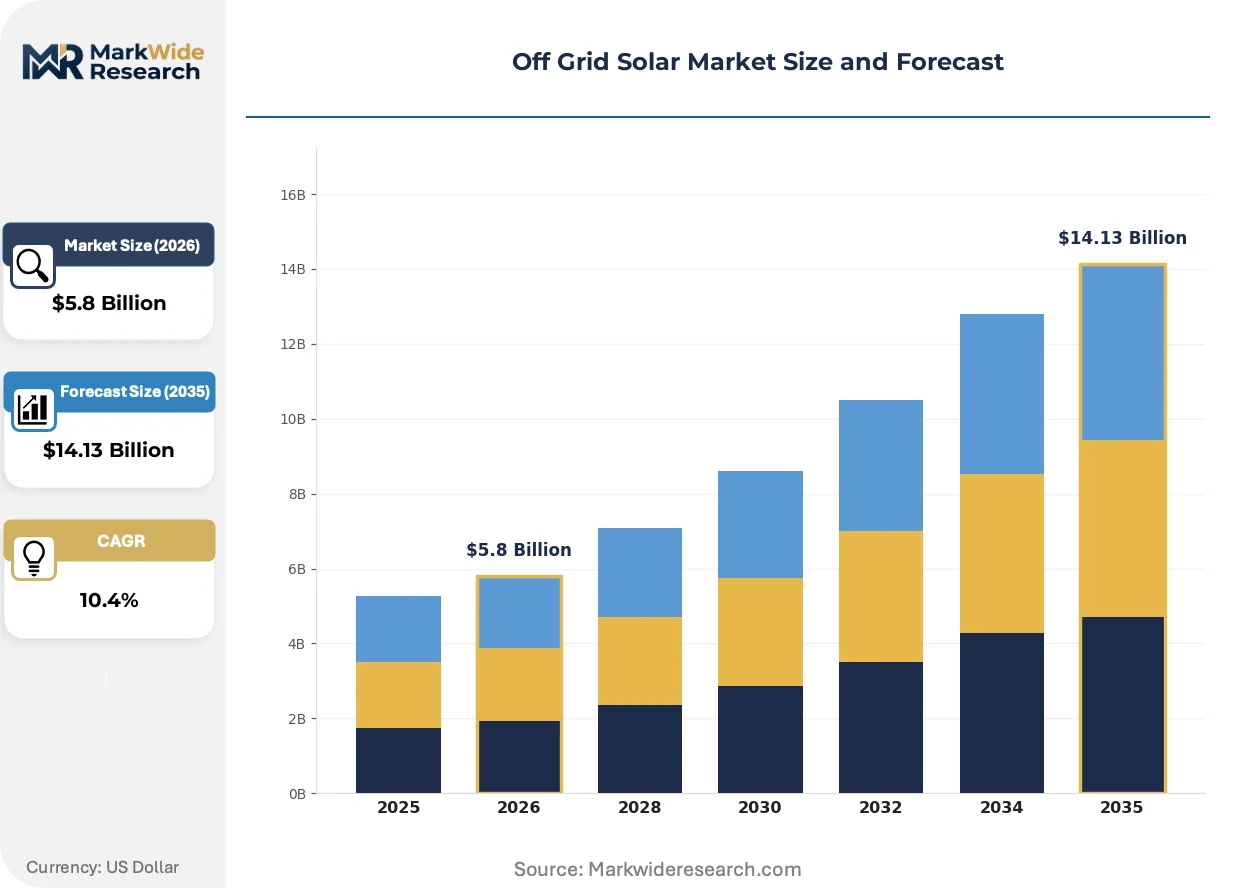
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $14.13 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Batteries, Inverters, Charge Controllers Application: Residential, Commercial, Agricultural, Remote Area Technology: Cubic Silicon, Thin-Film, Concentrated Solar, Hybrid Systems End User: Homeowners, Small Businesses, NGOs, Off-Grid Communities |
| Companies Covered | Jinko Solar Holding Co. Ltd., ABB, Hanwha Group, Schneider Electric, Canadian Solar, M-KOPA Kenya, SunPower Corporation, SMA Solar Technology Ag, Delta Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off Grid Solar Market Strategic Shifts & Innovations
System intelligence and component integration are defining the current wave of innovation. The market is evolving from selling discrete hardware components toward providing holistic energy solutions where software and advanced power electronics optimize performance, reliability, and user experience for a range of applications.
DC-coupled system architectures are a key product evolution, designed to maximize energy efficiency by minimizing power conversions between solar panels, batteries, and DC loads. Commercial installers and mini-grid developers are rapidly adopting these systems for their simplified design and lower balance-of-system costs. This integrated approach is absorbing the functions of separate charge controllers and inverters into a unified power management hub, which reduces installation complexity and potential points of failure.
The US Inflation Reduction Act (IRA) provides significant tax incentives for renewable energy, including standalone energy storage. This policy directly lowers the capital expenditure for off-grid solar-plus-storage systems in the United States, from residential homesteads to agricultural operations. The battery and power electronics segments are most affected, as manufacturers reorient supply chains to meet heightened North American demand for high-capacity, IRA-compliant energy storage solutions.
A notable behavioral shift is the move from one-time asset sales to ongoing service relationships, often structured as energy-as-a-service (EaaS) contracts. This model disrupts the traditional installer channel, as specialized energy providers retain ownership of the solar assets and sell guaranteed power or uptime to end-users. This trend is most prominent in sub-Saharan Africa, enabling small enterprises to access reliable power for income-generating activities without a large upfront investment.
Off Grid Solar Market Segmentation
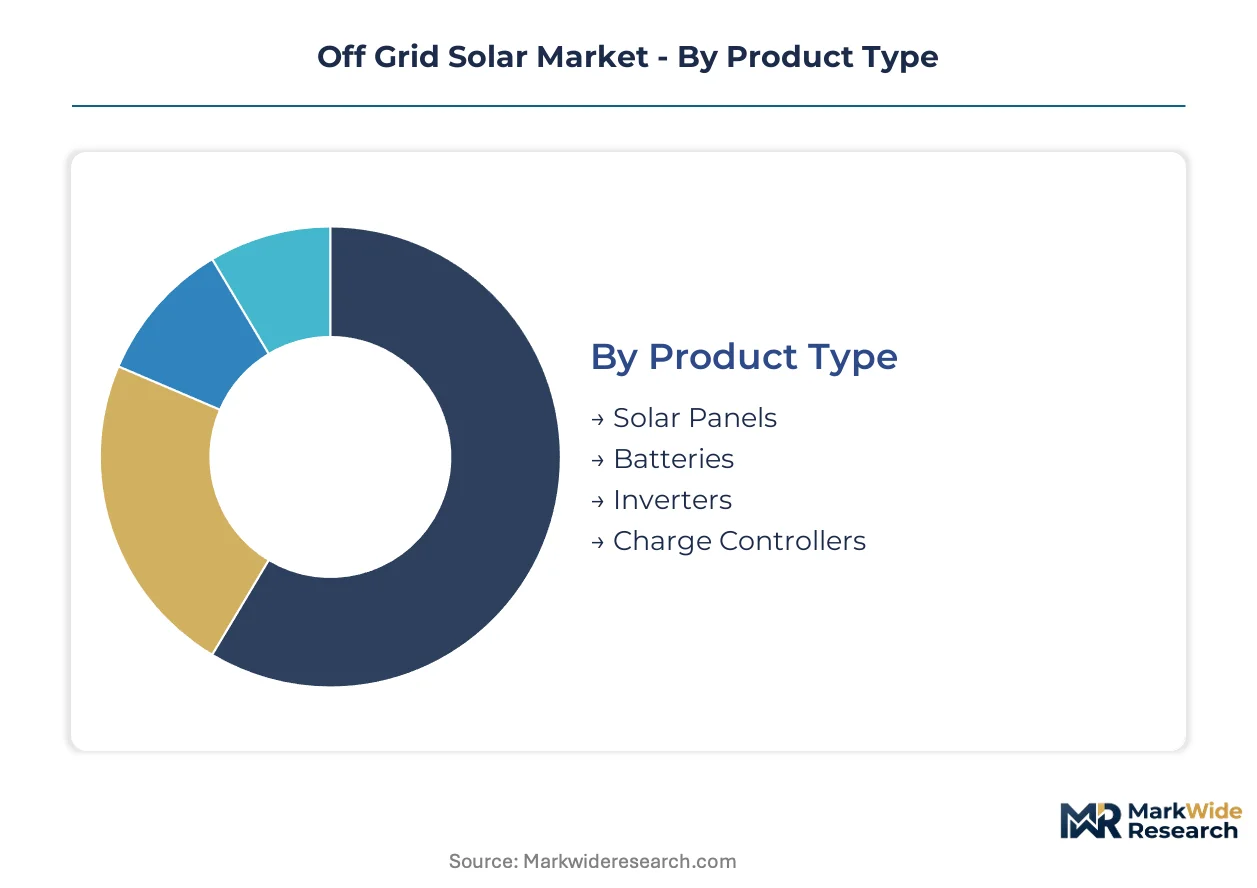
Understanding the Off Grid Solar Market requires a detailed segmentation to identify distinct demand patterns and technological requirements. This granular view helps stakeholders tailor product development, distribution strategies, and financing models to specific user needs. Market segmentation reveals how various system components and applications drive overall growth.
Product Type:
The upgrade and replacement cycle significantly influences demand across different product types within off-grid solar systems. Consumers often prioritize higher-performance components for capacity expansion. This dynamic drives innovation in energy storage and power conversion.
- Solar Panels:Photovoltaic modules convert sunlight directly into electricity. Demand concentrates in sub-Saharan Africa for rural electrification, driven by government incentives and agricultural uses.
- Batteries:These devices store electrical energy, ensuring continuous power supply during low solar irradiation. Demand is concentrating in agricultural applications across India for irrigation and cold storage.
- Inverters:Power electronics convert DC electricity into AC power for appliances and commercial equipment. Small commercial enterprises in Southeast Asia drive demand for efficient, grid-forming inverters.
- Charge Controllers:These components regulate voltage and current from solar panels to the battery bank, preventing overcharging. Remote communities utilize robust charge controllers to protect critical infrastructure.
Solar Panels sit at the top of the volume ranking, with Batteries climbing the fastest.
Application:
The functional application dictates the scale and complexity of off-grid solar deployments, influencing system design and financing requirements. Different end-uses present distinct power profiles, shaping component selection.
- Residential:These systems provide electricity for household needs like lighting and phone charging. Pay-as-you-go models in Kenya expanded residential access, overcoming initial capital barriers.
- Commercial:Off-grid solar powers small businesses, supporting critical operations like refrigeration and point-of-sale systems. Nigerian enterprises seek reliable commercial solutions to mitigate grid outages.
- Agricultural:This segment includes solar-powered irrigation pumps and cold storage facilities. India's PLI scheme accelerates agricultural deployments for enhanced food security.
- Remote Area:These applications electrify isolated villages, clinics, and telecom towers far from grid infrastructure. Island nations in Southeast Asia are a significant market for remote area electrification.
Agricultural applications are experiencing the steepest expansion trajectory, while Residential deployments maintain consistent volume.
Technology:
Technological choices for off-grid solar systems reflect a balance between cost-effectiveness, efficiency, and suitability for diverse environmental conditions. Material science advancements continually refine these options.
- Cubic Silicon:This crystalline silicon technology dominates the market due to its proven efficiency, durability, and manufacturing scalability. Jinko Solar leverages large-scale production to supply cost-effective modules.
- Thin-Film:These solar cells are made by depositing thin layers of photovoltaic materials, offering flexibility and better low-light performance. Portable off-grid devices explore thin-film solutions.
- Concentrated Solar:This technology uses mirrors or lenses to focus sunlight onto photovoltaic cells. High-power industrial applications in arid regions consider concentrated solar for its energy density.
- Hybrid Systems:These configurations combine solar power with other generation sources, ensuring greater reliability and energy security. Remote mining operations in Australia utilize hybrid systems to minimize fuel consumption.
Cubic Silicon technology holds the largest market share, with Hybrid Systems gaining share fastest due to enhanced reliability needs.
End User:
Understanding the varied needs and purchasing power of different end-user segments is crucial for effective market penetration and product design. Each user group presents unique challenges and opportunities regarding system complexity and financing.
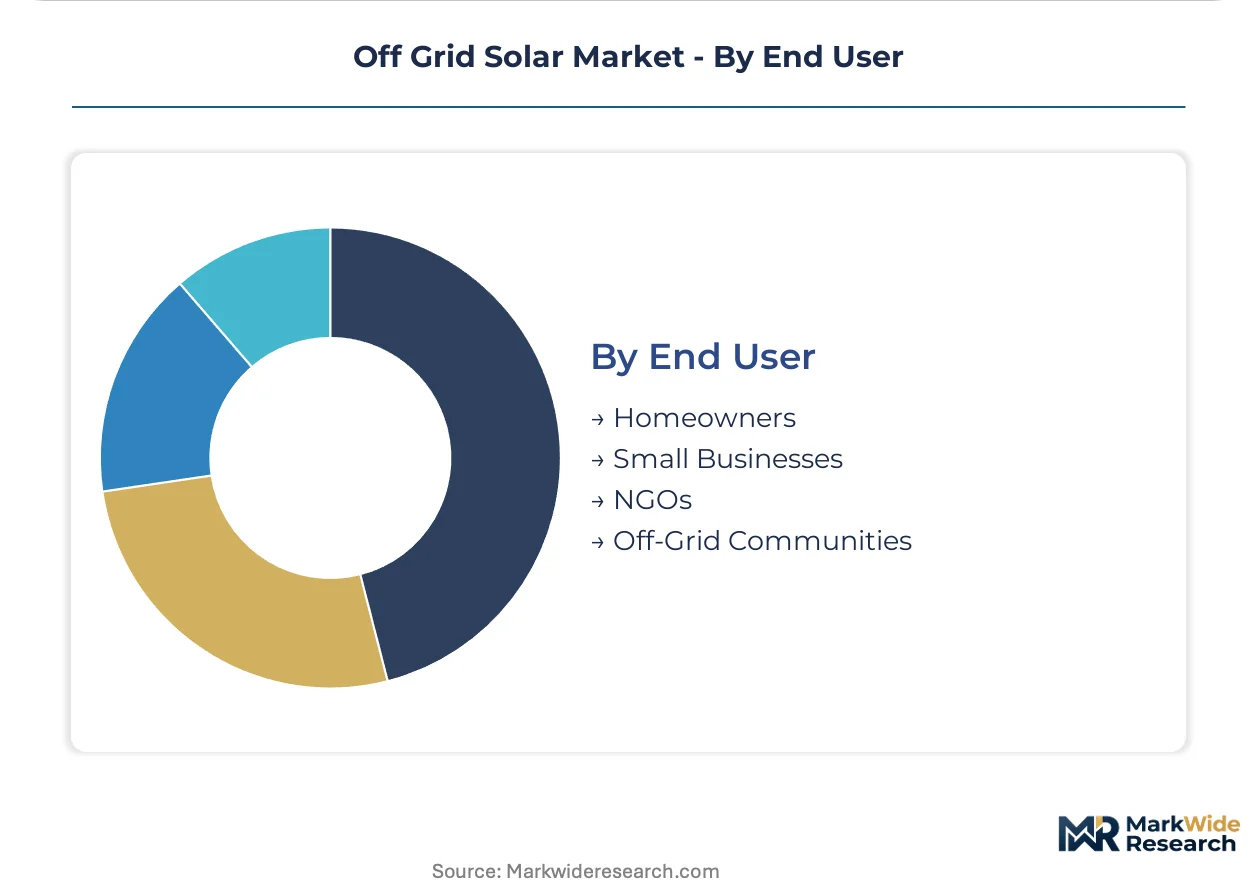
- Homeowners:Individual households in rural or remote areas, seeking basic electricity for lighting and phone charging. M-KOPA Kenya's PAYG model primarily serves homeowners across East Africa.
- Small Businesses:Micro, small, and medium enterprises requiring reliable power for productive uses like refrigeration or welding. Energy-as-a-Service models increasingly cater to small businesses in sub-Saharan Africa.
- NGOs:Non-governmental organizations deploy off-grid solar for humanitarian aid and community development. Organizations prioritize robust, easily deployable systems for critical infrastructure.
- Off-Grid Communities:Entire villages lacking grid access, benefiting from mini-grids or aggregated solar home systems. Governments in Indonesia invest in mini-grid solutions for remote archipelagic communities.
Homeowners represent the largest segment by volume, while Small Businesses are demonstrating accelerated procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global off-grid solar manufacturing dynamics reflect shifting policy landscapes that influence production location. Regulatory frameworks like India's Production Linked Incentive (PLI) scheme incentivize domestic output, creating cost advantages that impact component supply flows. This strategic localization impacts where solar components are manufactured and deployed, driving regional market shifts.
India
India's off-grid solar demand accelerates for agricultural irrigation pumps and cold storage facilities. The government's Production Linked Incentive (PLI) scheme for solar manufacturing significantly lowers module costs for domestic projects. Gujarat's burgeoning solar manufacturing hubs are expanding capacity to meet this national demand.
Kenya
Residential electrification drives off-grid solar growth across Kenya, particularly for low-income households. Pay-as-you-go (PAYG) financing models, like those pioneered by M-KOPA, remove upfront capital barriers. Nairobi's vibrant fintech sector continues to innovate new payment solutions for distributed energy access.
Philippines
Archipelagic nations like the Philippines seek off-grid solutions for remote island communities and basic electricity access. The government invests in mini-grid solutions to electrify thousands of isolated islands. Palawan's provincial efforts exemplify successful deployments for critical infrastructure.
United States
American off-grid installations benefit significantly from incentives for standalone energy storage. The US Inflation Reduction Act (IRA) provides tax credits that reduce capital expenditure for solar-plus-storage systems. California's agricultural regions increasingly adopt these systems for resilient farm operations.
Off Grid Solar Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the off-grid solar market. The industry structure features established component suppliers alongside agile system integrators and innovative service providers. Strategic archetypes include large-scale panel manufacturers, power electronics experts, and last-mile distribution innovators. Companies pursue geographic expansion and portfolio diversification to capture emerging opportunities.
Specialists in off-grid solar solutions exemplify distinct market approaches and strategic focus. Jinko Solar, a Chinese-based company, represents large-scale photovoltaic panel manufacturing, supplying cost-effective modules to various segments. Schneider Electric, a French multinational corporation, occupies a prominent position as an integrated inverter and power management solutions provider for more complex off-grid systems. M-KOPA Kenya, a leading East African entity, anchors the pay-as-you-go financing model, enabling broader access for low-income households across the region.
| Leading Market Players |
|---|
| Jinko Solar Holding Co. Ltd. |
| ABB |
| Hanwha Group |
| Schneider Electric |
| Canadian Solar |
| M-KOPA Kenya |
| SunPower Corporation |
| SMA Solar Technology Ag |
| Delta Electronics Inc. |
Cost & Logistics Intelligence
A clear performance divergence between basic residential solar home systems and complex productive-use solutions shapes both pricing strategies and supply chain configurations within the off-grid solar market. This bifurcation influences component sourcing and end-user affordability across diverse geographies.
Pricing Analysis
Distributor margins for off-grid components vary significantly based on regional logistics and market maturity. Pay-as-you-go (PAYG) models dominate residential segments, offering subscription-based access rather than outright purchase. Price differentiation stems from component quality grades, adherence to IEC technical standards, and the inclusion of comprehensive after-sales service packages. Pricing pressure stems from the influx of cost-effective modules from PLI-supported manufacturing in India. Homeowners in sub-Saharan Africa exhibit the highest price sensitivity, while NGOs procuring for critical infrastructure prioritize system reliability over lowest cost.
Supply Chain Analysis
Buyers mandating multi-supplier qualification for critical components mitigate single-source risks in the off-grid solar market. Geographic supply concentration for photovoltaic cells and battery materials centers heavily on China, with India also expanding its domestic manufacturing capacity. The market relies on key inputs like silicon for PV panels and lithium for high-capacity batteries. Geopolitical tensions and trade policy shifts present a structural risk, potentially disrupting the flow of essential components. Distribution channels traverse complex last-mile logistics networks, particularly in remote regions of sub-Saharan Africa and Southeast Asia, often leveraging local micro-entrepreneurs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The off-grid solar market presents a geographic-arbitrage play, leveraging low-cost component manufacturing in Asian hubs against high energy access demand in remote African and Southeast Asian communities that lack grid infrastructure.
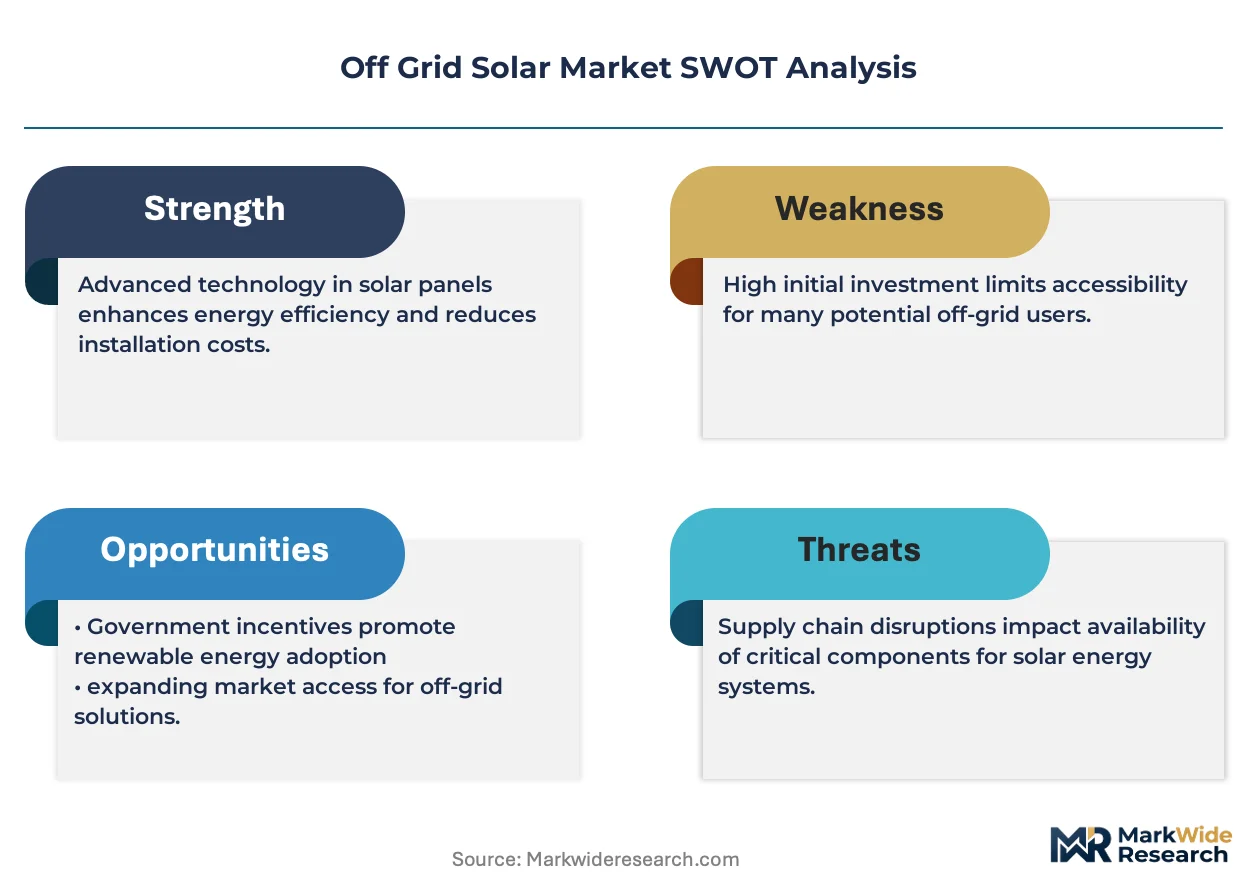
For Market Incumbents: Lock in long-term supply agreements for high-capacity batteries and efficient inverters to secure critical component availability. Deepen vertical integration into power electronics manufacturing to control quality and cost. This defends against margin erosion from commoditized solar panels and emerging local manufacturing threats, particularly those benefiting from schemes like India's PLI. Invest in R&D for advanced energy management software to optimize system performance and reliability.
For New Entrants and Emerging Players: IoT-enabled predictive maintenance systems represent a technology-first wedge into underserved markets. Focus on remote island communities in the Philippines and agricultural cold storage in India, which present significant white-space opportunities. Target small commercial enterprises with Energy-as-a-Service (EaaS) models, offering reliable power without large upfront investments. A strong go-to-market angle involves bundling advanced system monitoring with flexible payment solutions, addressing both technical and financial barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where last-mile distribution networks are fragmented and technical expertise is scarce. The long-term viability of off-grid solar for energy access and economic development over the next decade is robust. Target system integrators with proven track records in complex project deployment or fintech platforms specializing in PAYG financing models. The maturation of EaaS models into scalable, profitable ventures across sub-Saharan Africa serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Vertical Integration into Inverters | This move enhances control over power management technology for complex off-grid systems. |
| Expand Pay-as-You-Go Financing Platforms | Broader financial access enables millions of low-income households in Kenya to adopt solar solutions. |
| Invest in IoT-Enabled Remote Monitoring | Improved system reliability and predictive maintenance boost uptime for commercial enterprises. |
| Target Agricultural Cold Storage Deployments | Enhanced food security and reduced spoilage drive demand in India's rural economy. |
| Develop Mini-Grid Solutions for Archipelagic Nations | Electrification of remote islands in the Philippines becomes economically viable, addressing energy poverty. |
Research Approach
Direct dialogue with off-grid system integrators, component manufacturers, PAYG financing executives, and rural electrification program managers provided critical qualitative insights. This primary research was rigorously combined with secondary validation from IEA reports, national energy agency data, company financial statements, and academic research on rural electrification. A comprehensive bottom-up and top-down triangulation approach ensured data accuracy and consistency.
A bottom-up estimation of demand, derived from application-specific power requirements and end-user penetration rates, was validated by top-down market sizing across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, technology, end-user, and regional policy frameworks. Compound Annual Growth Rates were derived from historical growth analysis and future market drivers, incorporating inputs such as rural electrification targets and renewable energy policy incentives from the US IRA and India's PLI scheme.
The model holds under current macroeconomic and regulatory conditions; deviation in geopolitical stability, raw material price volatility, or shifts in government subsidy programs would shift the outlook materially. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Deviation in these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market