
 Power Battery Cells Market | 2026-2036
Power Battery Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Power Battery Cells Market Insights
UN 38.3 lithium battery transport certification is reorganizing supplier eligibility across the Power Battery Cells landscape, disqualifying smaller packagers from cross-border logistics. CATL leverages integrated mining-to-cell operations across Sichuan and Yichun to lock in lithium hydroxide supply. LG Energy Solution anchors its competitive stance through cylindrical 2170 dominance in North American EV programs. Samsung SDI specializes in high-nickel prismatic architectures for premium European automotive platforms.
Power battery cells are electrochemical energy storage devices comprising cathode, anode, separator, and electrolyte layers, typically delivering 3.2–4.3 V nominal potential and 150–300 Wh/kg gravimetric density, engineered for repetitive deep-discharge cycles in traction and stationary applications. Lithium-ion formats continue to absorb the majority of capital deployment, though solid-state chemistries are attracting pilot-scale investment as silicon-anode compatibility improves. Cylindrical form factors retain cost advantages in high-volume automation, while prismatic designs capture share in automotive platforms prioritizing pack-level volumetric efficiency. Energy Storage Systems represent the fastest-growing application vector as grid-scale deployments in Texas, California, and South Australia accelerate.
China's MIIT enforces GB/T cell safety and recycling standards that mandate domestic manufacturers achieve 25 kWh/cell traceability by 2028, tightening market access for uncertified imports. The EU Battery Regulation and ECHA REACH compliance together impose carbon footprint declarations and restricted substance thresholds that reshape cathode material sourcing from DRC cobalt and Indonesian nickel. Korea's MFDS and KATS coordinate with METI-aligned Japanese standards on thermal runaway propagation testing, creating a tripartite certification burden for Asian exporters. Stakeholders must monitor which jurisdiction's compliance timeline becomes the binding constraint for multi-destination product lines.
Market Dynamics
UN 38.3 lithium battery transport certification is reorganizing supplier eligibility across the Power Battery Cells landscape, disqualifying smaller packagers from cross-border logistics while favoring integrated manufacturers with captive testing facilities and certified packaging operations.
Growth Catalysts
- EU Battery Passport Mandate:Material traceability requirements under EU Battery Regulation are accelerating procurement of high-nickel cells by German EV manufacturers, tightening supply relationships with certified cathode suppliers.
- Silicon-Anode Compatibility:Pilot-scale investment in solid-state chemistries is expanding as silicon-anode interface stability improves, opening pathways beyond conventional lithium-ion energy density limits.
- Texas Grid Deployments:Energy Storage Systems demand is accelerating as utility-scale battery installations in ERCOT territory absorb surplus renewable generation and provide frequency regulation services.
Market Restraints
- Lithium Hydroxide Volatility:Concentrated spodumene processing in Western Australia and Chilean brine evaporation ponds creates input cost exposure for cathode manufacturers without backward integration into mining assets.
- DRC Cobalt Dependency:ECHA REACH restricted substance thresholds and carbon footprint declarations are forcing cathode material sourcing reconfigurations away from artisanal supply chains with limited traceability documentation.
- Thermal Runaway Propagation:Korea's MFDS and Japan's METI-aligned testing standards impose tripartite certification burdens that extend product qualification timelines for Asian exporters serving multiple destination markets.
Strategic Opportunities
- Prismatic Architecture Adoption:Premium European automotive platforms are prioritizing pack-level volumetric efficiency, creating white space for high-nickel prismatic cell specialists against cylindrical-dominant competitors.
- GB/T 2028 Traceability:China's MIIT mandates for 25 kWh/cell domestic traceability by 2028 are tightening market access, positioning certified local manufacturers to capture share from uncertified import competitors.
- Cylindrical Automation Scale:High-volume automation cost advantages in 2170 and 4680 formats are enabling new entrants to achieve competitive unit economics through dedicated production lines for North American EV programs.
Industry Challenges
- Electrolyte Formulation Talent:Scarcity of experienced solid-state electrolyte chemists and interface engineers is constraining R&D velocity for next-generation cell architectures.
- Dry Electrode Capex Intensity:Binder-free electrode manufacturing equipment requires substantial capital deployment before achieving yield parity with conventional slurry-coating processes.
- Multi-Jurisdiction Certification:Simultaneous compliance with UN 38.3, GB/T, and EU Battery Regulation creates timeline compression risks for product launches across China, Europe, and North American destinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Battery Cells Market |
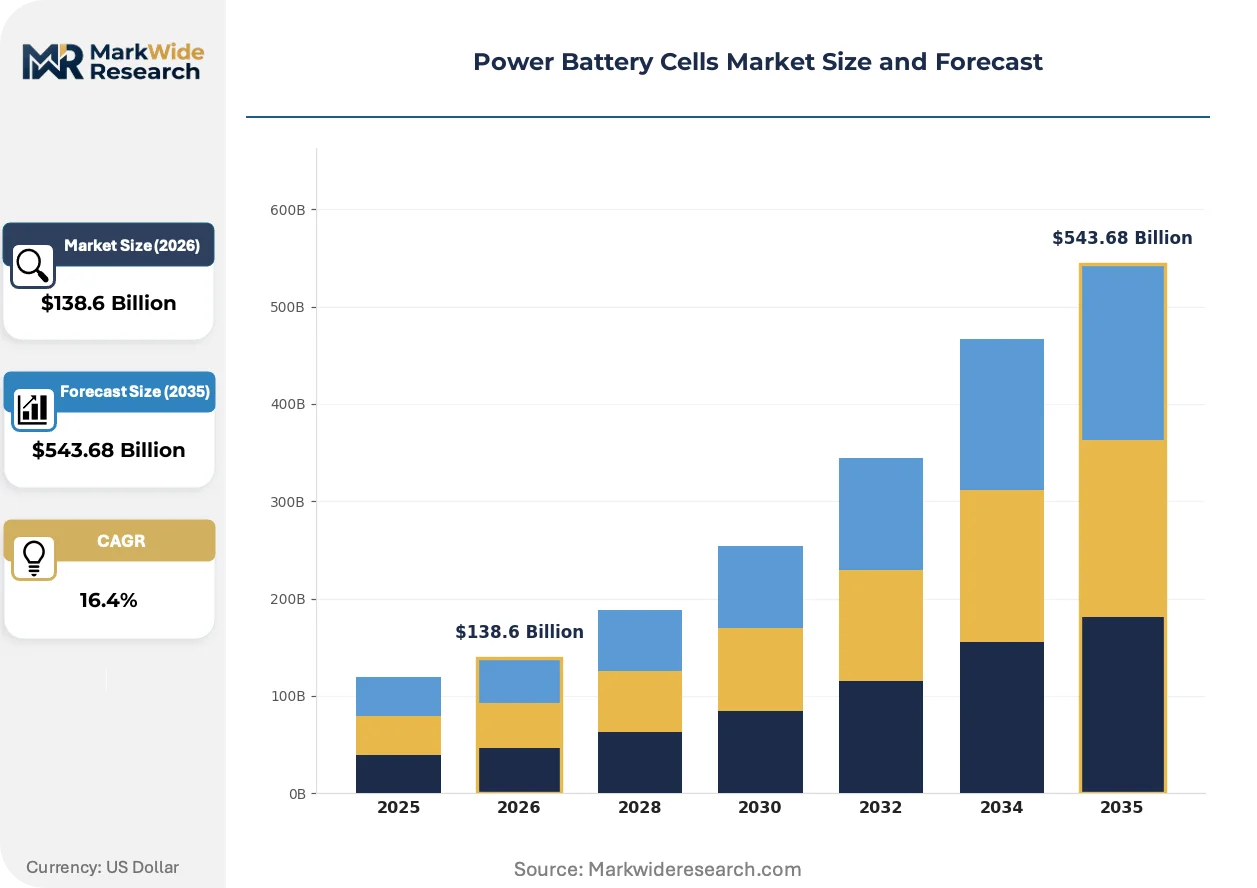
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $543.68 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Application: Electric Vehicles, Energy Storage Systems, Portable Devices, Power Tools Form Factor: Cylindrical, Prismatic, Pouch, Custom |
| Companies Covered | CATL, BYD, LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, SK Innovation, Gotion High Tech, Tianjin Lishen Battery, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Battery Cells Market Trends and Innovations
Cell chemistry and form factor evolution is fragmenting competitive positioning, with silicon-anode solid-state development running parallel to incremental lithium-ion improvements as manufacturers place diverging bets on technology readiness timelines.
Solid-state battery development is bifurcating the technology roadmap for next-generation energy storage. Silicon-anode compatibility improvements are enabling pilot production lines at specialized manufacturers targeting premium automotive applications. This technology trajectory is compressing investment windows for conventional liquid-electrolyte lithium-ion expansion as capital allocators weigh terminal technology displacement risks.
EU Battery Regulation carbon footprint declarations are restructuring cathode material procurement patterns. ECHA REACH compliance thresholds for restricted substances are forcing supply chain reconfigurations away from unverified cobalt sources. European automotive OEMs are responding by consolidating supplier relationships with integrated mining-to-cell operators capable of documenting full material provenance.
Integrated cathode-to-pack ecosystems in China's Jiangsu and Guangdong provinces are reshaping procurement geography for international cell buyers. Direct purchasing relationships with these manufacturing clusters are displacing traditional trading house intermediaries for volume EV programs. This channel compression is most visible among North American and European automakers establishing technical offices in Shenzhen and Suzhou to manage supplier qualification directly.
Power Battery Cells Market Segmentation
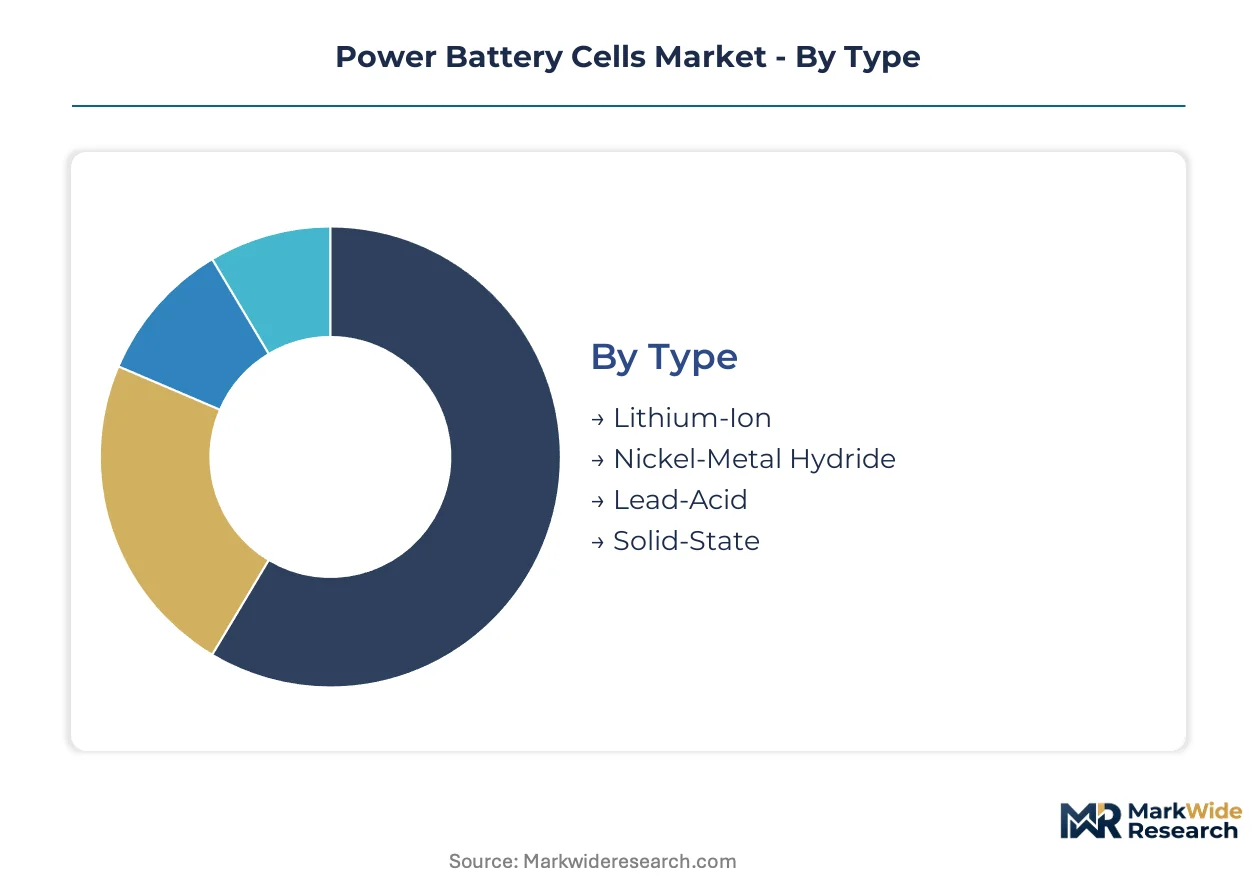
Power battery cell segmentation reveals how chemistry selection, form factor engineering, and end-use specifications create divergent compliance obligations and procurement economics. Manufacturers must align product architectures with jurisdiction-specific certification regimes to access premium customer segments.
Type:
UN 38.3 transport certification and EU Battery Regulation material declarations are fragmenting supplier eligibility across chemistry categories, favoring integrated operators with captive testing infrastructure.
- Lithium-Ion:Liquid electrolyte systems utilizing layered oxide cathodes and graphite anodes dominate current manufacturing scale. German EV programs are consolidating procurement around high-nickel NCM variants as ECHA REACH compliance tightens cobalt traceability requirements.
- Solid-State:Ceramic or sulfide electrolyte architectures with silicon-anode compatibility are advancing through pilot production. Pilot lines in Japan and South Korea are targeting premium automotive platforms as METI-aligned thermal runaway standards raise the safety performance threshold.
- Nickel-Metal Hydride:Rare earth hydride anode systems retain cost advantages in hybrid vehicle duty cycles with moderate energy density requirements.
- Lead-Acid:Mature flooded and AGM formats serve stationary backup and industrial starter applications with minimal regulatory complexity.
Lithium-Ion handles the majority of throughput; Solid-State is expanding most quickly on share as silicon-anode interface stability improves.
End User:
Customer procurement scale and certification burden intensity stratify margin profiles across end-use segments, with automotive buyers demanding the most extensive documentation packages.
- Automotive:OEM qualification programs require simultaneous compliance with UN 38.3, GB/T, and EU Battery Regulation timelines. Texas and California utility procurement is accelerating grid-scale storage deployments that absorb surplus renewable generation.
- Renewable Energy:Utility-scale battery installations in ERCOT territory and South Australia prioritize cycle life and warranty terms over energy density metrics.
- Consumer Electronics:Smartphone and laptop manufacturers specify pouch formats with aggressive volumetric density targets.
- Industrial:Forklift and material handling equipment favor lead-acid replacement cycles with established recycling infrastructure.
Automotive commands the dominant revenue concentration; Renewable Energy is climbing the fastest as grid interconnection queues clear.
Application:
Application-specific duty cycles—depth of discharge frequency, thermal operating windows, and calendar life requirements—drive divergent cell specification and pricing structures.
- Electric Vehicles:Traction applications demand 150-300 Wh/kg gravimetric density with 8-year warranty coverage. Prismatic architectures are capturing share in European platforms prioritizing pack-level volumetric efficiency against cylindrical-dominant competitors.
- Energy Storage Systems:Grid-scale deployments in California and Texas absorb surplus renewable generation while providing frequency regulation services to ISO markets.
- Portable Devices:Smartphone and tablet specifications prioritize thin-form pouch cells with rapid charge capability.
- Power Tools:High-discharge cylindrical formats serve professional construction equipment with robust mechanical tolerance requirements.
Electric Vehicles retains the largest installed base; Energy Storage Systems is gaining share fastest as interconnection backlogs resolve.
Form Factor:
Automation economics and pack integration geometry create divergent cost structures across physical cell architectures, with cylindrical formats retaining scale advantages in high-volume production environments.
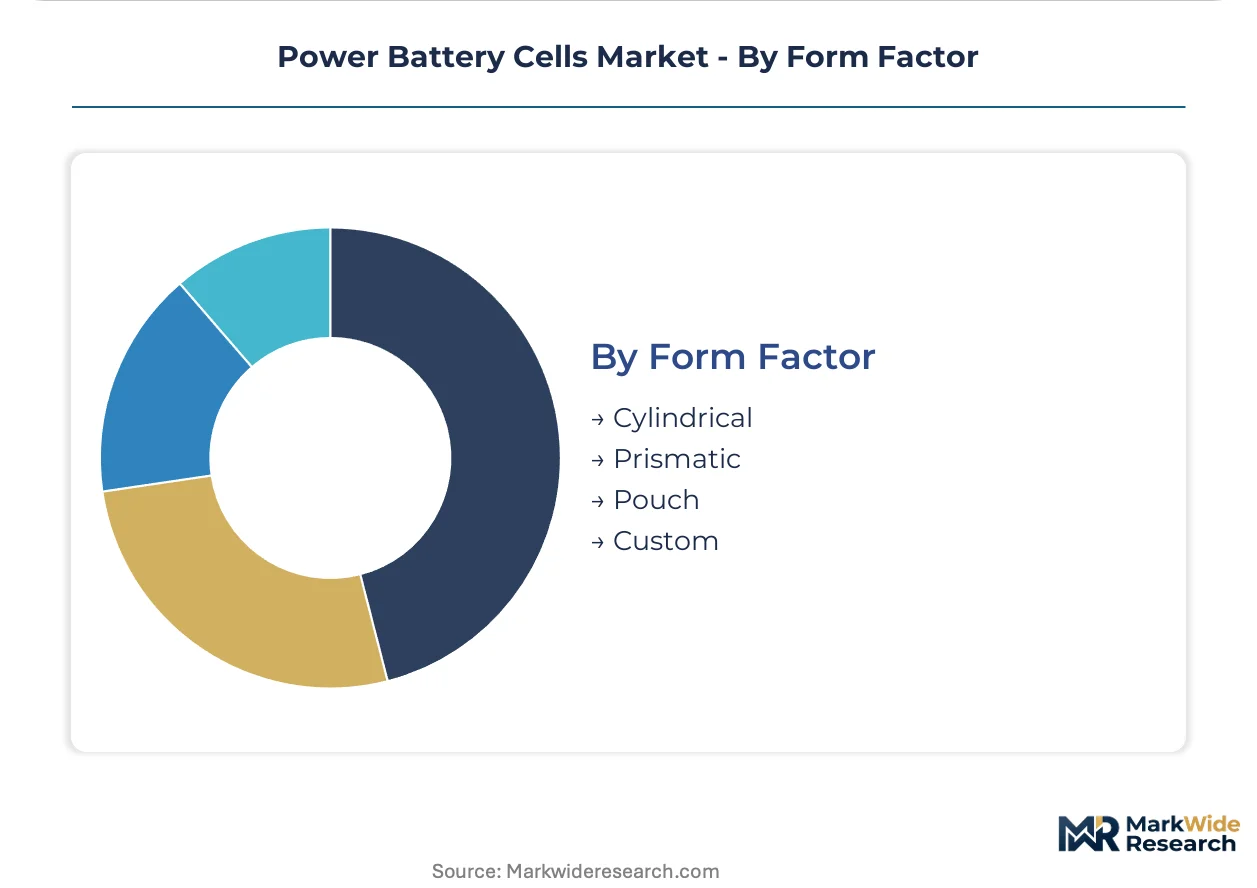
- Cylindrical:2170 and 4680 formats enable high-speed winding and laser welding automation that compresses unit costs. North American EV programs are standardizing around 2170 dominance for dedicated production lines.
- Prismatic:Aluminum-cased stacked electrode designs maximize volumetric packing efficiency at the module level. Premium European automotive platforms are consolidating procurement around high-nickel prismatic specialists.
- Pouch:Laminated film enclosures minimize dead space in consumer electronics applications with constrained thickness budgets.
- Custom:Specialty geometries serve aerospace and medical device applications with low-volume, high-margin procurement profiles.
Cylindrical handles the dominant production volume; Prismatic is advancing most quickly on share as European OEM pack designs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German EV manufacturers are scaling procurement of high-nickel cells as EU battery passport regulations tighten material traceability requirements. Chinese integrated cathode-to-pack ecosystems in Jiangsu and Guangdong provinces dominate cell output for international buyers. Utility-scale storage deployments in Texas and California absorb surplus renewable generation while providing frequency regulation services.
China
CATL leverages integrated mining-to-cell operations across Sichuan and Yichun to lock in lithium hydroxide supply for high-nickel cathode production. MIIT enforces GB/T cell safety and recycling standards mandating domestic manufacturers achieve 25 kWh/cell traceability by 2028. Jiangsu and Guangdong provinces host concentrated cathode-to-pack ecosystems that displace traditional trading house intermediaries for volume EV programs.
Germany
Premium automotive OEMs are consolidating supplier relationships with integrated mining-to-cell operators capable of documenting full material provenance under EU Battery Regulation requirements. ECHA REACH compliance thresholds for restricted substances are forcing supply chain reconfigurations away from unverified cobalt sources. Bavaria and Baden-Württemberg host technical offices for North American and European automakers managing direct supplier qualification.
United States
Texas and California utility procurement is accelerating grid-scale storage deployments that absorb surplus renewable generation and provide frequency regulation services to ISO markets. The Inflation Reduction Act domestic content provisions are reshaping cell sourcing patterns for automotive OEMs. The ERCOT territory in Texas represents the fastest-growing utility-scale battery installation geography.
South Korea
LG Energy Solution anchors competitive positioning through cylindrical 2170 dominance in North American EV programs. MFDS coordinates with METI-aligned Japanese standards on thermal runaway propagation testing, creating tripartite certification burdens for exporters. Samsung SDI specializes in high-nickel prismatic architectures for premium European automotive platforms requiring pack-level volumetric efficiency.
Japan
Pilot lines at specialized manufacturers are targeting premium automotive platforms as METI-aligned thermal runaway standards raise safety performance thresholds. Solid-state battery development with silicon-anode compatibility is advancing through pilot production facilities. The Kanto region around Tokyo maintains concentrated R&D infrastructure for next-generation cell architectures.
Power Battery Cells Market Competitive Landscape
Player mix skews toward integrated mining-to-cell operators with captive lithium hydroxide supply and certified testing infrastructure. The supplier base stratifies between high-volume cylindrical specialists and premium prismatic architects serving European automotive platforms. Two strategic archetypes dominate: backward-integrated resource owners with spodumene or brine assets, and technology licensors with proprietary electrolyte formulations. Competitive moves center on capacity expansion in Sichuan and Yichun mining corridors, plus strategic partnerships to secure cathode material traceability documentation.
Among Chinese integrated operators, CATL and BYD exemplify the backward-integrated archetype with captive lithium supply chains spanning Sichuan mining assets to Jiangsu manufacturing clusters. LG Energy Solution occupies a position within the cylindrical-format tier serving North American EV programs, while Samsung SDI represents the prismatic-specialist vector targeting premium European automotive platforms with high-nickel architectures. These three anchors illustrate how geography and form factor specialization stratify competitive positioning across procurement geographies.
| Leading Market Players |
|---|
| CATL |
| BYD |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| SK Innovation |
| Gotion High Tech |
| Tianjin Lishen Battery |
| EVE Energy |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lithium hydroxide inventory cycles at cathode manufacturers compress negotiation leverage against spodumene processors in Western Australia and Chilean brine operators, concentrating pricing power upstream while downstream cell producers absorb volatility through long-term offtake structures. This lead-time asymmetry rewards integrated mining-to-cell operators with captive hydroxide supply and certified packaging infrastructure under UN 38.3 transport protocols.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and Fastmarkets lithium hydroxide assessments dominate procurement between cathode suppliers and cell manufacturers. Price differentiation stratifies across automotive certification tiers, with EU Battery Regulation-compliant cells commanding premiums over uncertified imports. Pricing pressure stems from concentrated spodumene processing capacity in Western Australia, squeezing cathode margins. Automotive OEMs exhibit lowest price sensitivity due to qualification switching costs, while industrial buyers prioritize unit economics over traceability documentation.
Supply Chain Analysis
China, South Korea, and Japan anchor global cell manufacturing, with Jiangsu and Guangdong provinces hosting concentrated cathode-to-pack ecosystems. Raw material dependencies rest on Chilean and Australian lithium, Indonesian nickel, and DRC cobalt. Single-source vulnerability in hydroxide conversion capacity creates supply chain risk. Distribution runs through direct technical office relationships in Shenzhen and Suzhou, displacing traditional trading house intermediaries for volume EV programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power battery cells sit in early-cycle expansion as silicon-anode solid-state pilot lines attract capital commitments ahead of liquid-electrolyte lithium-ion terminal displacement risks. Grid-scale storage deployments in ERCOT and California ISO territories accelerate penetration beyond automotive traction applications.
For Market Incumbents: Secure captive lithium hydroxide supply through Sichuan and Yichun mining corridor investments before GB/T 2028 traceability mandates tighten domestic Chinese market access. Defend against cylindrical-format new entrants by accelerating prismatic automation for European OEM pack efficiency requirements. Prioritize EU Battery Regulation certification infrastructure to maintain premium tier access. For New Entrants and Emerging Players: Anchor in Texas utility-scale storage procurement as interconnection backlogs clear and frequency regulation revenue stacks improve project economics. Target ERCOT territory deployments with cylindrical 2170 or 4680 formats leveraging high-volume automation cost structures. Pursue direct supplier qualification relationships with California community choice aggregators seeking long-term battery service agreements. For Investors and Strategic Acquirers: Long-term, this sits as a resource-integrated technology play because terminal cell economics depend on upstream lithium and nickel control rather than pure manufacturing scale. Acquisition candidates include solid-state electrolyte specialists with silicon-anode interface patents and GB/T-certified Chinese manufacturers with established cathode-to-pack ecosystems. Watch METI-aligned thermal runaway testing standard adoption as inflection signal for next-generation safety performance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Mining | Captive spodumene assets in Sichuan and Yichun secure hydroxide supply against Chilean brine volatility. |
| EU Battery Regulation Certification | Carbon footprint declarations and material passports unlock premium automotive procurement in Germany. |
| Prismatic Architecture Scale-Up | Aluminum-cased stacked electrode designs capture European OEM pack volumetric efficiency requirements. |
| Silicon-Anode Pilot Production | Ceramic electrolyte compatibility positions for solid-state technology transition beyond liquid lithium-ion limits. |
| ERCOT Grid Storage Deployment | Texas utility-scale installations absorb renewable surplus while capturing frequency regulation revenue streams. |
Research Methodology
Desk research of customs trade databases, MIIT production filings, and ECHA REACH substance registrations preceded structured interviews with cathode procurement directors, cell manufacturing executives, utility storage developers, and automotive platform engineers. Primary fieldwork with Tier 1 supplier qualification teams validated secondary data on certification timeline compression. Bottom-up cell production estimates and top-down automotive demand projections were triangulated against EIA battery installation data and IEA stationary storage outlooks.
Variance decomposition across chemistry type, form factor, end-use segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates adjusted for technology substitution curves and jurisdiction-specific compliance phase-ins. Forecast inputs incorporated silicon-anode interface stability improvements, GB/T traceability mandate enforcement intensity, and ERCOT interconnection queue resolution patterns.
Material uncertainties — lithium hydroxide price volatility, DRC cobalt supply chain restructuring, and thermal runaway testing standard harmonization failures — sit outside the modeled envelope. Forecasts reflect assumptions on solid-state pilot line yield progression and EU Battery Regulation enforcement consistency. Recalibration cycles align with material shifts in cathode chemistry adoption and grid storage procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South Korea Rechargeable Battery Market
Batteries
Inverter Battery Market
Batteries
West Europe Battery Market
Batteries
North America Industrial Battery Market
Batteries
Military Battery Market
Batteries
West Africa Battery Market
Batteries
Global Marine Battery Market
Batteries
FORTELION Battery Module Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
18650 And 21700 Battery Market
Batteries
Submarine Batteries Market
Batteries
East Asia Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Home Inverter Battery Market
Batteries
Portable Battery Pack Market
Batteries
South America Battery Cell Market