
 Solar Photovoltaic (PV) Panel Market | 2026-2036
Solar Photovoltaic (PV) Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaic (PV) Panel Market Analytics
Utility procurement is shifting toward high-efficiency bifacial arrays as data center operators and green hydrogen developers enter as new volume buyers. JinkoSolar leverages its integrated wafer-cell-module capacity to anchor pricing power in N-type TOPCon supply. LONGi Green Energy Technology Co. Ltd. dominates p-type to n-type transition roadmaps through in-house silicon ingot R&D intensity.
Solar Photovoltaic (PV) Panels are semiconductor devices that convert sunlight into direct-current electricity through the photovoltaic effect, typically constructed from crystalline silicon wafers or thin-film semiconductor layers with power outputs ranging from residential rooftop modules to utility-scale arrays exceeding 600 W per panel. Monocrystalline silicon leads product type margins due to superior conversion efficiency above 22%, while thin-film CdTe sustains cost competitiveness in utility-scale desert installations where temperature coefficients matter. Floating installations represent the fastest-growing installation type as reservoir and coastal projects unlock land-constrained markets without competing for agricultural or real estate use.
FERC interconnection standards in the United States, the EU Green Deal's REPowerEU acceleration framework, and India's MNRE PLI scheme for domestic module manufacturing collectively shape demand pull and local content requirements across major demand centers. China's GB standards for module efficiency and recycling obligations under the EU's WEEE directive are tightening product specifications and end-of-life liability for exporters. Stakeholders must monitor policy continuity around domestic manufacturing incentives and grid access priority rules as these determine effective market access faster than pure cost curves.
Market Dynamics
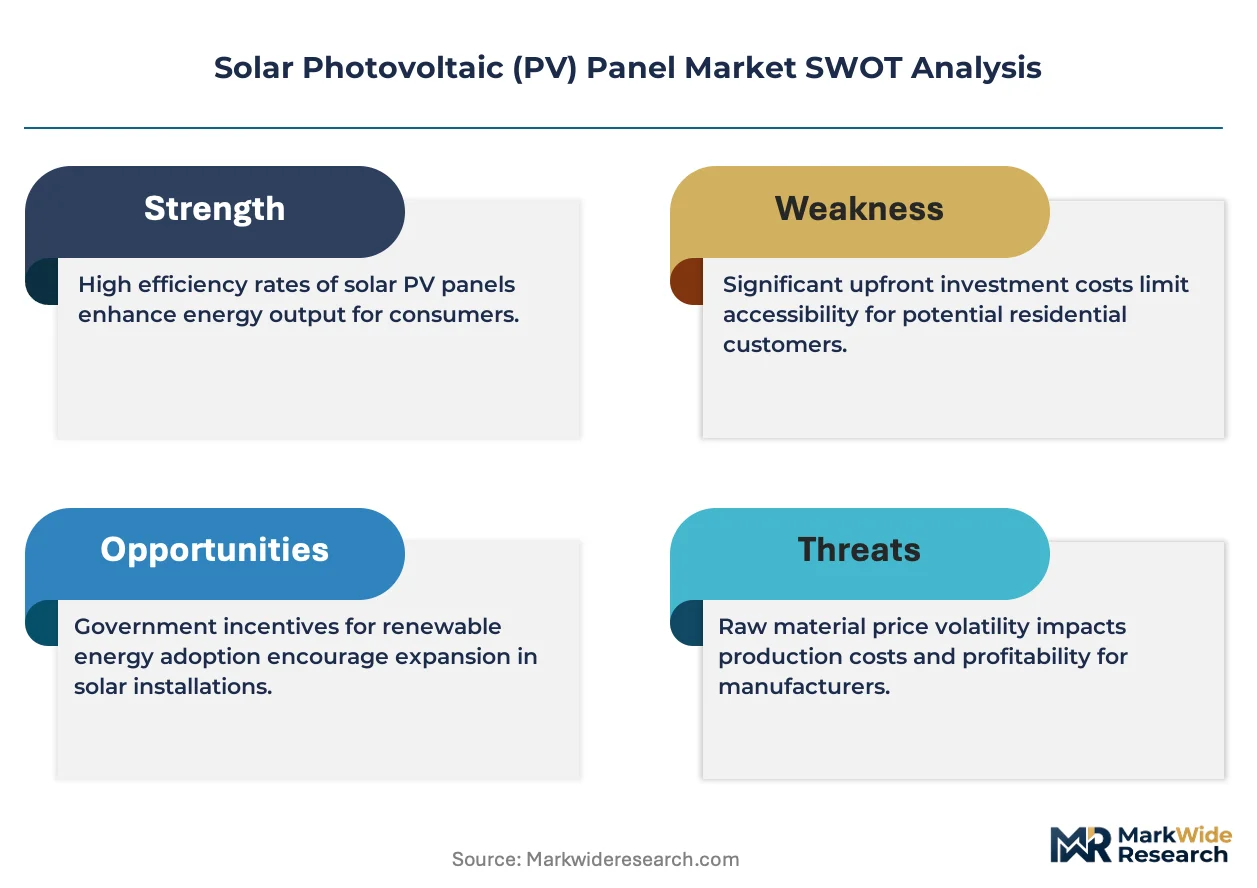
Cell architecture migration from p-type PERC to n-type TOPCon is compressing legacy capacity values and concentrating procurement power among integrated wafer-cell-module producers with captive polysilicon supply.
Growth Catalysts
- Data Center Power Demand:Hyperscale operators in the United States and Germany are contracting multi-gigawatt solar arrays to meet 24/7 carbon-free electricity commitments, pulling bifacial module volumes into utility-scale pipelines.
- EU Green Deal REPowerEU:The framework's accelerated renewable targets are concentrating module demand in Germany, Spain, and Poland while tightening local content requirements for project finance eligibility.
- Floating PV Technology Maturation:Reservoir and coastal installations in Japan and South Korea are unlocking land-constrained markets without competing for agricultural or real estate use, expanding addressable surface area.
Market Restraints
- Polysilicon Input Volatility:Metallurgical-grade silicon and polysilicon prices swing with electricity costs in Xinjiang and Inner Mongolia, transmitting margin pressure downstream to cell and module producers without captive ingot capacity.
- Supply Concentration Risk:China's dominance in wafer slicing and cell metallization equipment creates single-point vulnerability for non-Chinese module assemblers facing export credit restrictions.
- Grid Interconnection Queues:FERC Order 2023 implementation delays in the United States are extending project energization timelines beyond power purchase agreement tenors, stranding contracted capacity.
Strategic Opportunities
- Green Hydrogen Electrolyzer Co-location:Developers in Spain, Australia, and Saudi Arabia are pairing solar arrays with proton exchange membrane electrolyzers to produce export-bound ammonia, creating dedicated offtake for curtailed midday generation.
- Agrivoltaics Penetration:Dual-use installations combining elevated bifacial arrays with shade-tolerant crops are expanding in France and Japan, accessing agricultural subsidies while generating electricity revenue.
- India PLI Scheme Domestic Manufacturing:The production-linked incentive for polysilicon-to-module integrated capacity is attracting capital into Gujarat and Tamil Nadu, creating alternative supply nodes to Chinese exports.
Industry Challenges
- TOPCon Cell Process Engineering Talent:The shift from thermal to plasma-enhanced chemical vapor deposition for passivation layers requires specialists scarce outside China and Taiwan, constraining capacity ramp rates.
- Module Recycling Compliance:The EU WEEE directive's extended producer responsibility obligations are forcing manufacturers to fund collection and silicon recovery infrastructure without proven economic models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaic (PV) Panel Market |
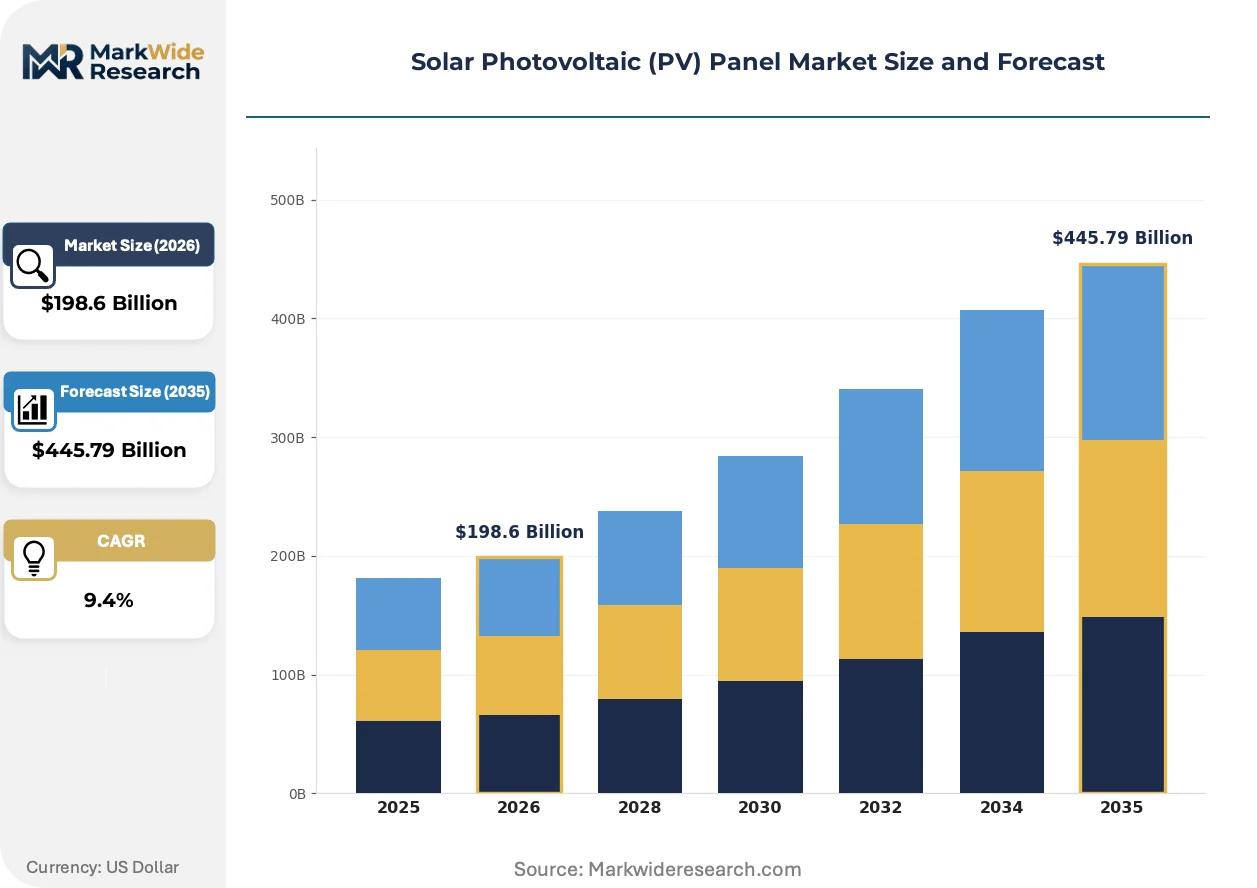
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $445.79 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial End User: Residential, Commercial, Industrial, Utility Installation Type: On-Grid, Off-Grid, Hybrid, Floating Technology: Silicon-Based, CdTe, CIGS, Concentrated PV |
| Companies Covered | JinkoSolar Holding Co. Ltd., JA Solar Technology Co. Ltd., Trinasolar, LONGi Green Energy Technology Co. Ltd., First Solar, Canadian Solar, Hanwha Qcells, Tongwei Co. Ltd., DMEGC Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaic (PV) Panel Market Evolving Landscape
Automation of cell fabrication and module assembly is compressing labor cost differentials between manufacturing regions while regulatory frameworks accelerate technology turnover and buyer consolidation reshapes contract structures.
TOPCon cell metallization is automating the transition from screen-printed silver to copper-plated fingers, reducing precious metal loading while maintaining contact resistance. Equipment suppliers in Germany and Japan are shipping laser transfer and plating tools to cell fabs in Vietnam and India, enabling these facilities to match Chinese cell efficiencies without silver paste supply dependencies. This metallization shift is automating cost parity across geographies previously disadvantaged by silver price exposure.
The EU's CSRD disclosure requirements and F-Gas Regulation phase-down are tightening supply chain traceability and fluorinated gas reporting for module manufacturers selling into European project pipelines. Module producers must now document polysilicon provenance and encapsulant fluorine content to maintain bankability, with enforcement concentrating on utility-scale tenders in Germany and the Netherlands. Developers are responding by pre-qualifying suppliers with third-party sustainability certifications before technical evaluation.
Corporate buyers are consolidating procurement through multi-year framework agreements that bundle engineering, module supply, and performance guarantees, displacing project-specific competitive tenders. This concentration is visible among technology and data center operators in the United States and Ireland, where sustainability teams now contract directly with integrated developers rather than through traditional EPC channels. The shift compresses supplier margins while locking in volume commitments across technology transition cycles.
Solar Photovoltaic (PV) Panel Market Segmentation
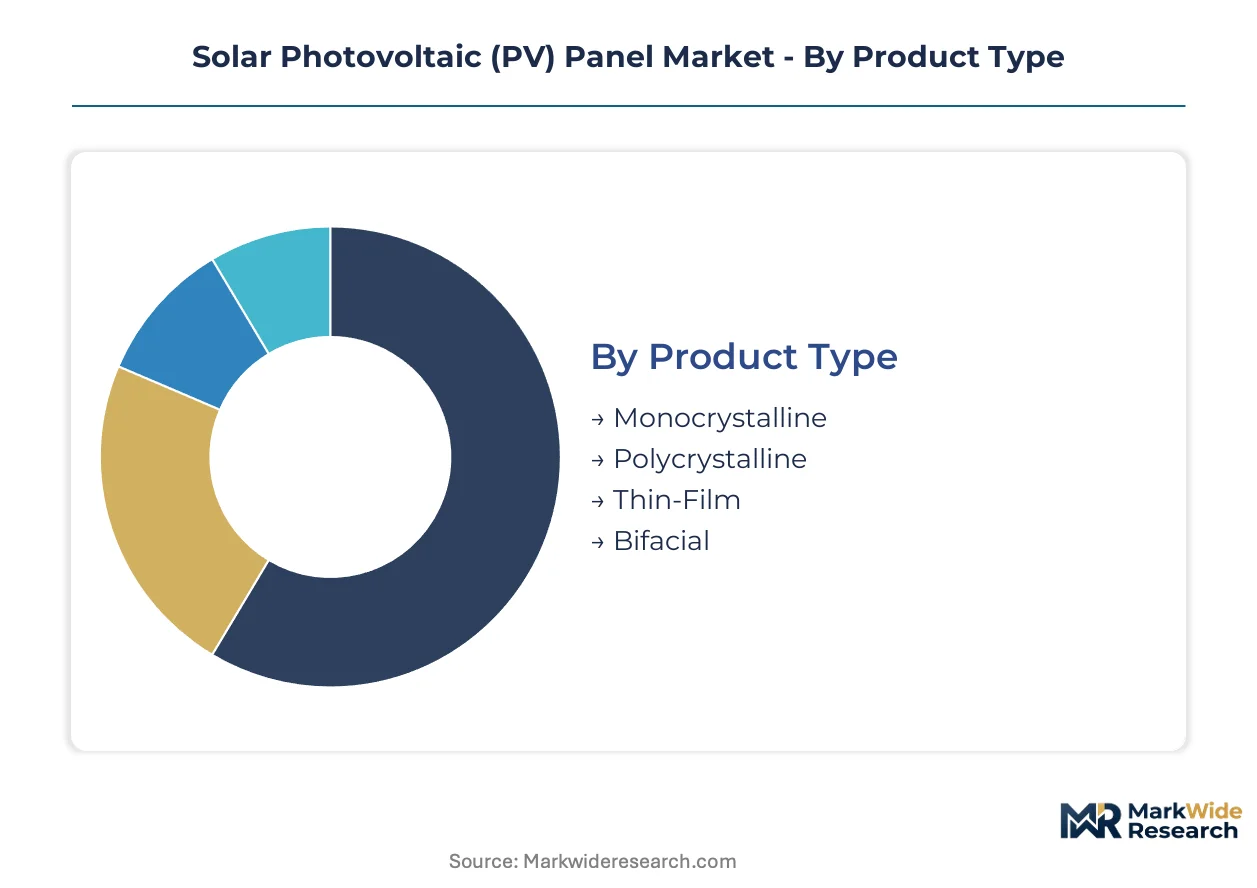
Segmentation in the Solar Photovoltaic (PV) Panel Market reveals how technology choices, installation constraints, and buyer procurement power reshape competitive positioning across cell architectures and deployment models.
Product Type:
Buyers differentiate primarily by conversion efficiency thresholds and temperature coefficient performance rather than upfront module cost alone.
- Monocrystalline:Constructed from single-crystal silicon ingots with conversion efficiency exceeding 22%. Data center operators in Germany and the United States specify monocrystalline bifacial variants for 24/7 carbon-free power procurement under corporate sustainability mandates.
- Thin-Film:Deposited semiconductor layers of CdTe or amorphous silicon on glass substrates. Utility-scale desert installations in Saudi Arabia and Australia favor thin-film CdTe where high ambient temperatures degrade crystalline silicon output.
- Polycrystalline:Multi-crystal silicon cells with lower manufacturing energy input. Distributed residential installers in India select polycrystalline modules where cost-per-watt dominates efficiency metrics.
- Bifacial:Dual-sided light capture with rear-side albedo gain. Floating reservoir projects in Japan and South Korea deploy bifacial glass-glass constructions for enhanced yield on reflective water surfaces.
Monocrystalline leads volumes today; bifacial is gaining share fastest.
End User:
Procurement scale and offtake contract duration separate these buyer categories more than technology preference.
- Utility:Multi-gigawatt array developers contracting 15-25 year power purchase agreements. Spain and Australia's green hydrogen electrolyzer co-location projects anchor dedicated offtake for curtailed midday generation.
- Industrial:Manufacturing facilities with 24-hour load profiles and rooftop or adjacent land availability. Chemical and semiconductor fabs in Taiwan and South Korea procure behind-the-meter solar to hedge volatile grid tariffs.
- Commercial:Office buildings, retail, and logistics centers with 500 kW to 5 MW deployment scales. France's agrivoltaics subsidies pull commercial developers toward dual-use elevated bifacial installations.
- Residential:Single-family and multi-unit rooftop systems under net metering or self-consumption regimes. California's NEM 3.0 transition and Germany's feed-in tariff reductions are compressing residential payback periods.
Utility procurement dominates absolute gigawatts; industrial self-consumption is climbing the fastest.
Installation Type:
Grid connection status and site constraints determine balance-of-system costs more than module selection.
- On-Grid:Direct interconnection to centralized transmission or distribution networks. FERC interconnection queue delays in the United States are extending project energization timelines beyond contracted power purchase agreement tenors.
- Floating:Pontoon-mounted arrays on reservoirs, quarry lakes, or coastal lagoons. Land-constrained markets in Japan and South Korea unlock surface area without competing for agricultural or real estate use.
- Off-Grid:Stand-alone systems with battery storage for rural electrification or remote industrial loads. Mining operations in Australia and Chile deploy off-grid solar-diesel hybrid configurations.
- Hybrid:Grid-connected systems with co-located battery storage enabling peak shaving and ancillary services. Texas ERCOT market participants pair solar with lithium-ion storage to capture price volatility.
On-Grid installations command the largest installed base; floating arrays are expanding most quickly.
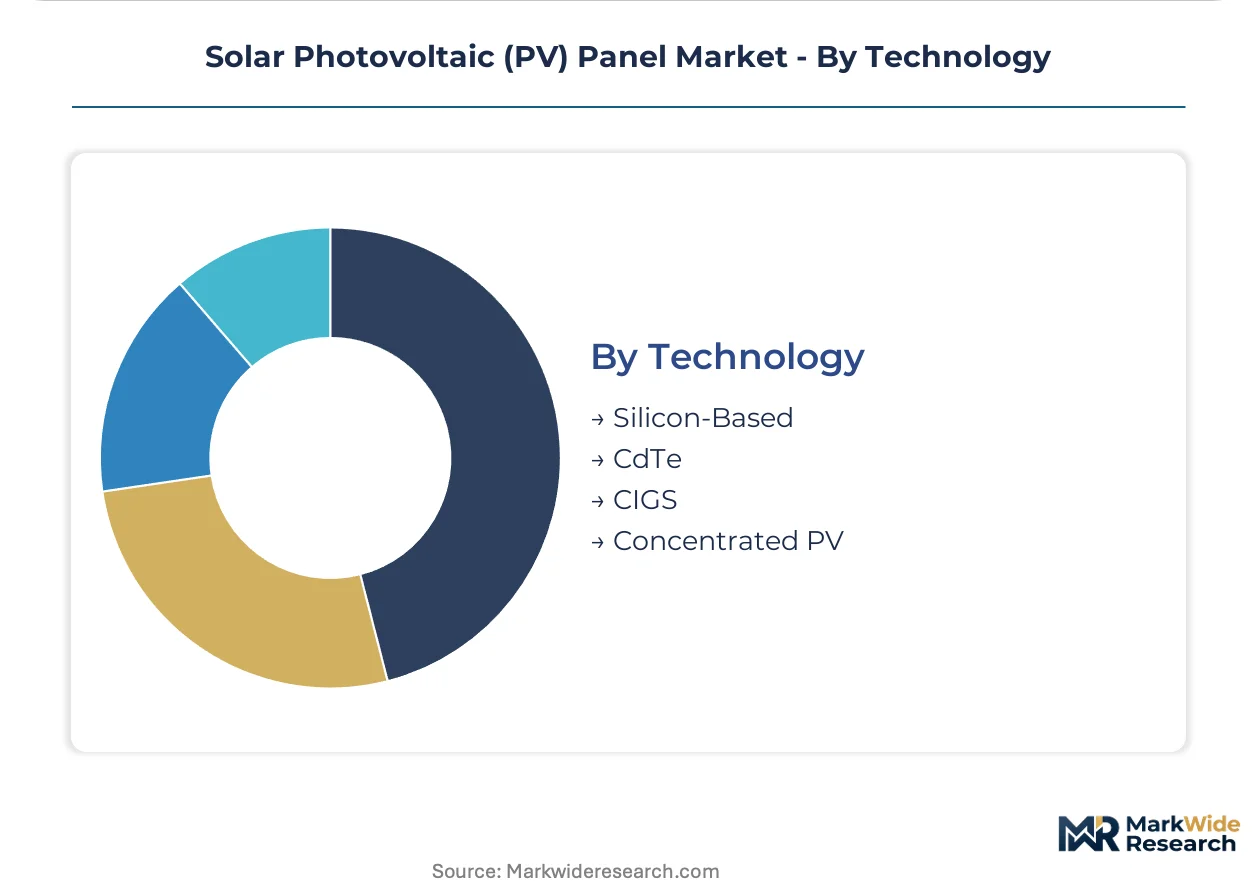
Technology:
Cell metallization and passivation layer chemistry separate these technology platforms in manufacturing capital intensity and efficiency roadmap.
- Silicon-Based:Crystalline silicon wafers in p-type PERC or n-type TOPCon architectures. China's N-type TOPCon capacity expansion is compressing legacy p-type PERC equipment valuations.
- CdTe:Cadmium telluride thin-film deposited at lower temperatures than silicon ingot growth. First Solar's integrated manufacturing in Ohio and Malaysia sustains cost parity for utility-scale procurement.
- CIGS:Copper indium gallium selenide flexible substrates for building-integrated and portable applications. Japanese and European manufacturers target niche architectural glass and consumer electronics segments.
- Concentrated PV:Multi-junction cells with optical concentration requiring dual-axis tracking. Saudi Arabia's high-direct-normal-irradiance desert sites host demonstration projects for concentrated PV thermal hybrid systems.
Silicon-Based technologies dominate manufacturing capacity; CdTe maintains share in specific utility-scale desert applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly migrates toward jurisdictions where electricity costs and environmental compliance burdens create arbitrage opportunities for polysilicon-to-cell production. China's GB standards and India's PLI scheme exemplify competing regulatory frameworks reshaping capacity location decisions.
China
Inner Mongolia and Xinjiang host polysilicon smelters powered by subsidized coal electricity, feeding N-type TOPCon cell expansions in Jiangsu and Anhui provinces. MIIT's GB standards for module efficiency tighten export specifications while MEE enforcement of dual carbon goals accelerates capacity relocation to western provinces with renewable energy bases. Hefei and Suzhou industrial clusters concentrate wafer slicing and cell metallization equipment manufacturing.
United States
Data center operators in Virginia and Texas contract multi-gigawatt solar arrays to meet 24/7 carbon-free electricity commitments, pulling bifacial module volumes into utility-scale pipelines. FERC interconnection standards and IRA domestic content bonus credits shape project finance structures, though Order 2023 implementation delays extend energization timelines. First Solar's integrated manufacturing in Ohio anchors thin-film CdTe supply for desert installations.
Germany
REPowerEU acceleration frameworks concentrate module demand in Bavaria and North Rhine-Westphalia while tightening local content requirements for project finance eligibility. Chemical and semiconductor fabs in Saxony and Baden-Württemberg procure behind-the-meter solar to hedge volatile grid tariffs. The EU's CSRD disclosure requirements and F-Gas Regulation phase-down tighten supply chain traceability for module bankability.
India
The MNRE PLI scheme for polysilicon-to-module integrated capacity attracts capital into Gujarat and Tamil Nadu, creating alternative supply nodes to Chinese exports. Distributed residential installers select polycrystalline modules where cost-per-watt dominates efficiency metrics. Rajasthan and Karnataka host utility-scale arrays with green hydrogen electrolyzer co-location projects anchoring dedicated offtake for curtailed midday generation.
Japan
Reservoir and coastal floating installations in Hyogo and Chiba prefectures unlock land-constrained markets without competing for agricultural or real estate use. METI's feed-in tariff reductions compress residential payback periods while accelerating commercial and industrial self-consumption adoption. Kyushu and Tohoku regions concentrate agrivoltaics deployments combining elevated bifacial arrays with shade-tolerant crops.
Solar Photovoltaic (PV) Panel Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated wafer-cell-module producers capturing procurement power in N-type TOPCon supply while thin-film specialists defend utility-scale desert niches. The vendor base concentrates among Chinese integrated producers with captive polysilicon supply, European equipment suppliers, and North American thin-film fabricators. Two archetypes dominate: scale-driven integrated manufacturers controlling upstream material flows, and technology specialists differentiating through cell architecture roadmaps. Competitive moves center on backward integration into polysilicon smelting and strategic partnerships with data center operators for multi-year offtake frameworks.
Among Chinese integrated producers, JinkoSolar Holding Co. Ltd. and LONGi Green Energy Technology Co. Ltd. occupy positions exemplifying the scale-driven archetype with in-house wafer and cell capacity. First Solar represents the thin-film specialist archetype with integrated manufacturing outside China. These three companies anchor the competitive structure by demonstrating how geographic production location and cell technology selection determine access to utility-scale procurement pipelines.
| Leading Market Players |
|---|
| JinkoSolar Holding Co. Ltd. |
| JA Solar Technology Co. Ltd. |
| Trinasolar |
| LONGi Green Energy Technology Co. Ltd. |
| First Solar |
| Canadian Solar |
| Hanwha Qcells |
| Tongwei Co. Ltd. |
| DMEGC Solar |
| Others |
Value Network & Pricing Analysis
Polysilicon smelting costs in Xinjiang and Inner Mongolia cascade through wafer slicing, cell metallization, and module assembly tiers, compressing margins at each handoff while integrated producers with captive ingot capacity capture pricing power unavailable to non-integrated assemblers facing silver paste and equipment import dependencies.
Pricing Analysis
Distributor margins on standard monocrystalline modules have compressed to single-digit percentages as direct procurement frameworks between data center operators and integrated manufacturers displace traditional channel structures. Three-tier pricing structure across premium N-type TOPCon, standard p-type PERC, and economy polycrystalline levels separates utility-scale offtake from distributed residential installers. Cost compression in the standard tier is intensifying because Chinese capacity expansion has outpaced demand absorption in European and Indian markets. Industrial self-consumption buyers in Taiwan and South Korea exhibit lowest price sensitivity due to grid tariff hedging motives, while Indian residential installers remain most price-sensitive and specify polycrystalline modules on pure cost-per-watt metrics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese wafer slicing and cell metallization equipment suppliers, constraining non-Chinese module assemblers facing export credit restrictions and technology transfer barriers. Manufacturing gravity centers on China, Vietnam, and India for cell and module assembly, with polysilicon feedstock drawn from Xinjiang, Inner Mongolia, and emerging Saudi Arabian smelters. Silver paste, high-purity quartz crucibles, and laser doping equipment constitute critical input dependencies with limited qualified supplier bases. Tariff exposure on Chinese-origin cells and modules entering the United States and European Union creates supply chain risk that developers mitigate through Southeast Asian tolling arrangements. Distribution runs through integrated developers contracting directly with hyperscale offtakers, bypassing traditional EPC and distributor channels for utility-scale volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar Photovoltaic Panel Market functions as a stable compounder anchored by irreversible corporate decarbonization commitments that institutionalize renewable procurement as a standard operating expense rather than discretionary sustainability spending.
For Market Incumbents: To counter margin compression from Chinese N-type TOPCon overcapacity, JinkoSolar and LONGi should deepen backward integration into metallurgical-grade silicon smelting in western China renewable energy bases while locking multi-year offtake frameworks with Virginia and Texas data center operators before competitors capture 24/7 carbon-free power procurement slots. Certification investment in EU CSRD traceability and F-Gas Regulation compliance will defend bankability positioning as European project finance eligibility tightens. For New Entrants and Emerging Players: The 15-20% price-point gap between premium N-type TOPCon and economy polycrystalline modules opens white-space targeting of India's distributed residential segment under MNRE rooftop subsidies and France's agrivoltaics dual-use installations accessing agricultural support payments. Floating PV reservoir projects in Japan and South Korea offer penetrable geography where land constraints block incumbent utility-scale developers. A go-to-market angle pairing module supply with performance guarantees and engineering services bundles can displace project-specific competitive tenders. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale EPC developers with established interconnection queue positions because FERC Order 2023 implementation delays have stranded contracted capacity that acquirers can energize through operational execution capabilities. Long-term viability over the next decade hinges on exposure to data center and green hydrogen offtake rather than merchant power price risk. The signal to watch is corporate buyer consolidation into multi-year framework agreements that displace project-specific tenders, indicating procurement power concentration favoring integrated developers with balance sheet capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Smelting | Captive supply from Xinjiang renewable energy bases insulates margin from electricity cost volatility. |
| Multi-Year Framework Agreements with Hyperscalers | Direct contracting with Virginia data center operators locks volume across technology transition cycles. |
| Copper-Plated Cell Metallization Adoption | Laser transfer tools from German equipment suppliers reduce silver paste dependency and cost exposure. |
| Floating PV Technology Licensing | Reservoir installations in Japan unlock land-constrained markets without agricultural land competition. |
| EU CSRD Traceability Certification | Polysilicon provenance documentation maintains bankability for German and Dutch utility tenders. |
Research Methodology
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each market combining structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators alongside secondary validation through EIA data, IEA renewable energy reports, FERC interconnection filings, and project development databases. Bottom-up capacity and demand modeling triangulates against top-down policy target analysis across the REPowerEU framework, India's PLI scheme, and China's dual carbon goals.
Rate-of-change decomposition separates volume growth from price trajectory and technology mix shift across the projection horizon, with segmentation modeling across cell architecture, installation type, end-user category, and regional regulatory framework. CAGRs were derived from installed base evolution and replacement demand analysis incorporating technology turnover timelines from p-type PERC to n-type TOPCon. Key inputs include corporate renewable procurement commitments from hyperscale data center operators and green hydrogen electrolyzer co-location project pipelines in Spain and Australia.
The model assumes a particular technology adoption path; alternative pathways for heterojunction or perovskite tandem cell commercialization would alter the outlook through accelerated obsolescence of incumbent capacity. Forecasts reflect assumptions around policy continuity for domestic manufacturing incentives and grid access priority rules that determine effective market access. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Philippines Solar Energy Market