
 Solar Charge Controller Market | 2026-2036
Solar Charge Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Charge Controller Market Intelligence
The firmware-level integration of advanced battery charging algorithms is reconfiguring the performance and cost dynamics of solar charge controllers. This shift allows for greater efficiency and battery longevity. Schneider Electric leverages its extensive industrial automation expertise to serve complex off-grid applications. Morningstar Corporation sustains its market position through a focus on high-reliability devices for critical remote power systems, while Victron Energy specializes in integrated solutions for mobile and marine environments.
A solar charge controller is an electronic device that manages the power flowing from a solar panel array into a battery bank. Its primary function is to prevent battery overcharging and deep discharging, often using multi-stage charging profiles to optimize battery health. The market features a clear differentiation between lower-cost Pulse Width Modulation (PWM) controllers and higher-efficiency Maximum Power Point Tracking (MPPT) units. MPPT technology dominates in larger residential and telecommunication systems where maximizing energy harvest is critical.
Product design and market access are shaped by international standards such as IEC 62109 for safety and the European Union's CE marking requirements. Compliance with directives like RoHS, restricting hazardous substances, is also essential for market entry in many regions. The central strategic decision for manufacturers involves balancing the cost of PWM units against the performance premium of MPPT controllers while deciding on the integration level of digital features.
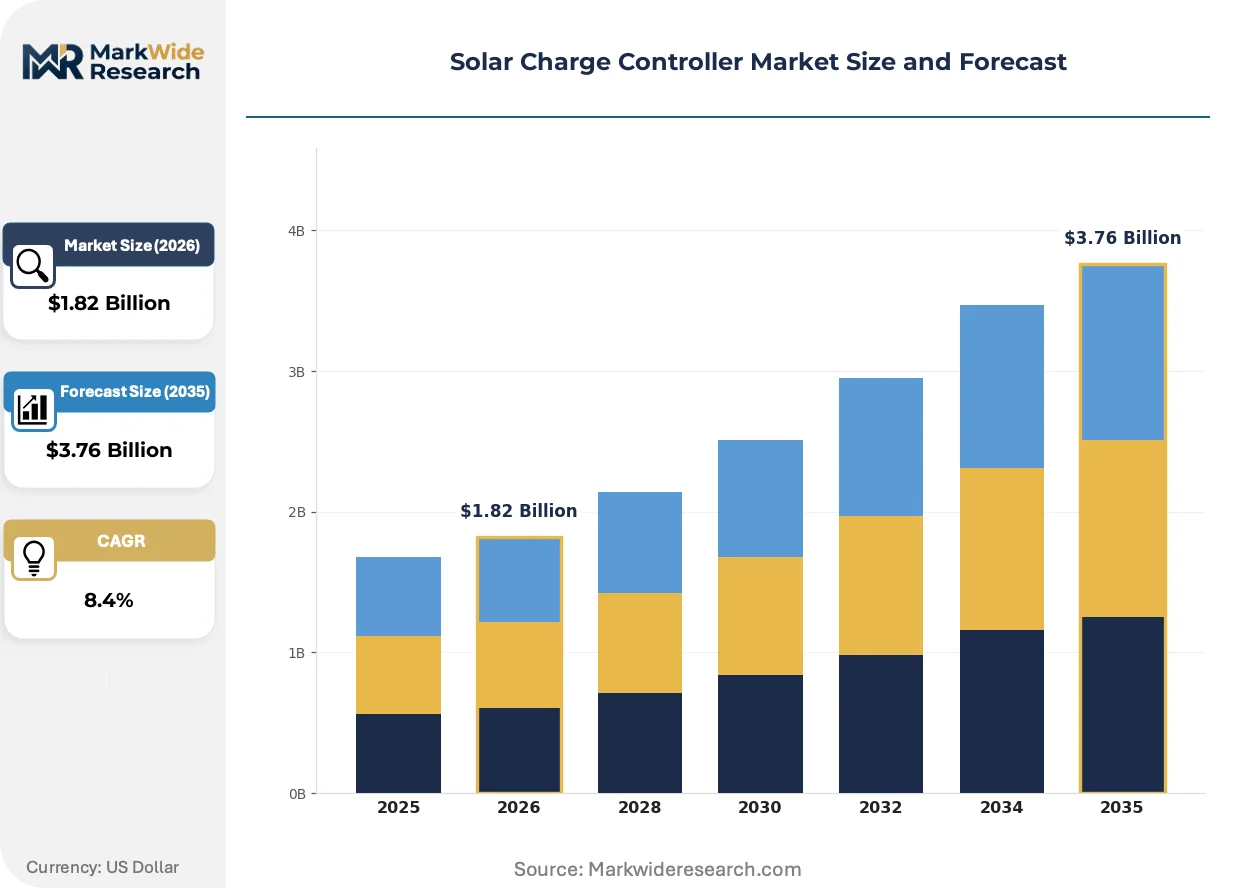
Market Dynamics
The primary force shaping the market is the performance-cost trade-off between Pulse Width Modulation (PWM) and Maximum Power Point Tracking (MPPT) technologies, amplified by escalating demand for reliable off-grid power in developing economies.
Growth Catalysts
- Government Initiatives:Rural electrification programs, particularly in India and parts of sub-Saharan Africa, provide subsidies and policy support for deploying off-grid solar systems, directly boosting controller demand.
- IoT Integration:The incorporation of Bluetooth and IoT connectivity allows for remote monitoring and management of solar systems, a feature increasingly sought in telecommunication and critical infrastructure applications.
- Battery Technology Advancement:The proliferation of diverse battery chemistries, including Lithium Iron Phosphate (LFP), necessitates more sophisticated charge controllers capable of executing complex, multi-stage charging algorithms.
Market Restraints
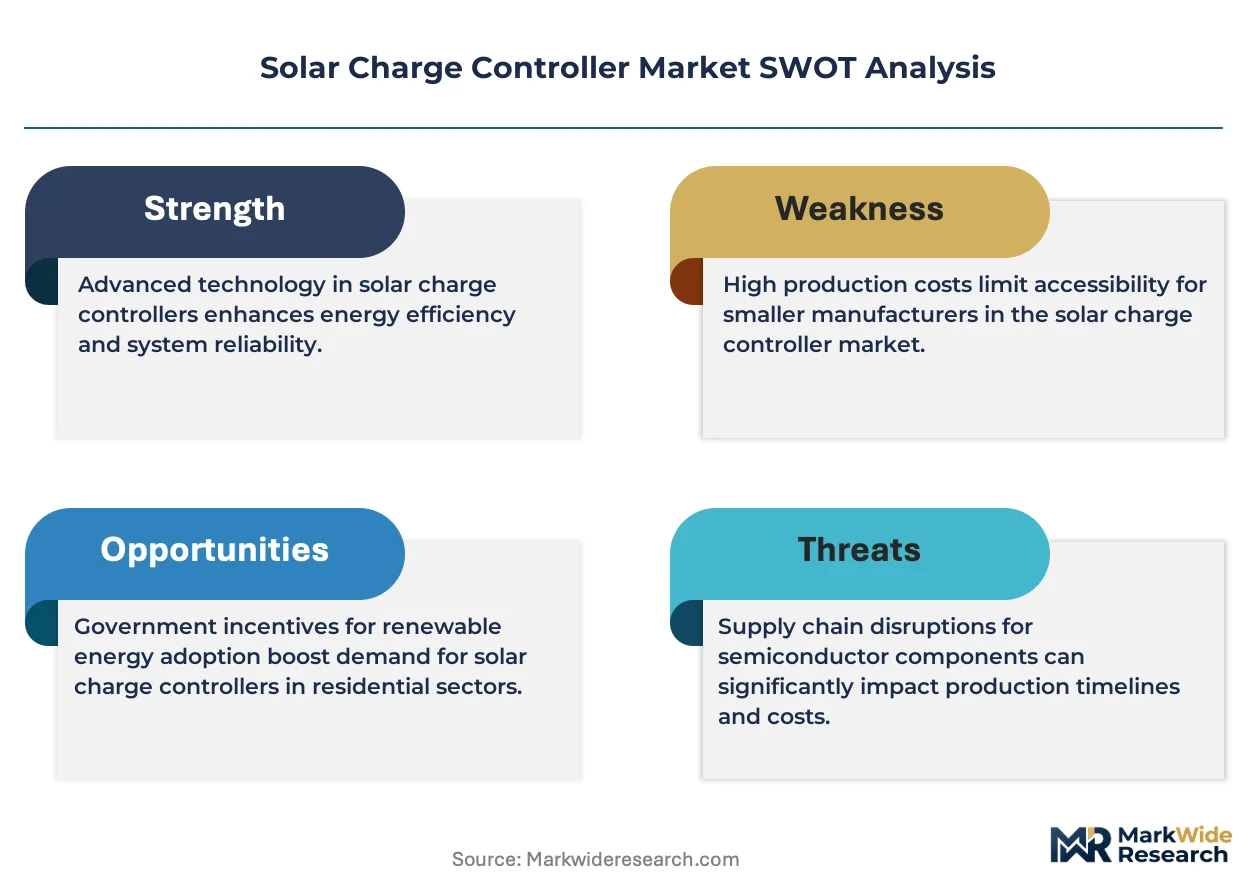
- MPPT Cost Premium:The significantly higher upfront cost of high-efficiency MPPT controllers compared to basic PWM units remains a barrier to adoption in price-sensitive residential and small-scale applications.
- Component Supply Volatility:The market's reliance on a concentrated base of semiconductor suppliers, primarily in East Asia, exposes manufacturers to price fluctuations and supply chain disruptions for critical microcontrollers.
- Threat from Integrated Systems:The rise of all-in-one solar generators and hybrid inverters with built-in charge control functions reduces the addressable market for standalone controller units, especially in the portable power segment.
Strategic Opportunities
- Mobile and Marine Applications:Expanding recreational vehicle (RV) and marine markets present a significant opportunity for compact, ruggedized controllers designed for mobility and harsh environmental conditions.
- Firmware as a Service:Manufacturers can develop new revenue streams by offering premium firmware upgrades that unlock advanced charging algorithms, diagnostics, or enhanced connectivity features for existing hardware.
- Agricultural Electrification:The agricultural sector in regions like Latin America and Southeast Asia represents an underpenetrated market for powering remote water pumps, irrigation systems, and electric fencing.
Industry Challenges
- Global Standards Compliance:Adhering to a fragmented landscape of international safety standards, such as IEC 62109, and regional directives like the EU's CE marking and RoHS, adds significant cost and complexity to product development.
- Interoperability with Legacy Systems:Ensuring seamless integration with older solar panels and various battery types presents an ongoing engineering challenge, particularly in retrofit projects for existing off-grid installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Charge Controller Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Width Modulation, Maximum Power Point Tracking, Series, Shunt Technology: Analog, Digital, Bluetooth Enabled, IoT Integrated, Wireless Application: Residential Solar Systems, Telecommunication Systems, Off-grid Power Systems, Agriculture Pumps, Marine Vessels End User: Homeowners, Telecom Operators, Farmers, Boat Operators, Remote Facility Managers |
| Companies Covered | SUNGROW, Morningstar Corporation, Schneider Electric, Beijing Epsolar Technology, Victron Energy, Phocos, SRNE, Renogy, OutBack Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Charge Controller Market Strategic Shifts & Innovations
Product evolution is defined by the embedding of digital intelligence, transforming the charge controller from a simple power regulator into a central hub for energy system optimization and battery health management. This shift prioritizes software-defined performance over hardware alone.
Advanced battery charging algorithms are a core product differentiator, using multi-stage profiles to optimize energy transfer and extend battery service life. Commercial and large residential users are the primary adopters, seeking to maximize return on investment. The market is migrating from static voltage cutoff systems toward dynamic, firmware-driven controllers that actively manage battery state-of-health.
The European Union's RoHS directive, restricting hazardous substances in electronic equipment, directly impacts material selection and manufacturing processes for charge controllers. This forces a redesign of circuit boards and component sourcing to achieve compliance for market access. The mandate most affects high-volume manufacturers targeting the European residential and light commercial solar markets.
A clear purchasing pattern shift is visible toward complete, pre-configured solar power kits rather than sourcing individual components. This model bypasses traditional electronics distributors, favoring system integrators and direct-to-installer channels that offer simplified logistics. This behavior is most prominent within the DIY and recreational vehicle segments in North America and Australia.
Solar Charge Controller Market Segmentation
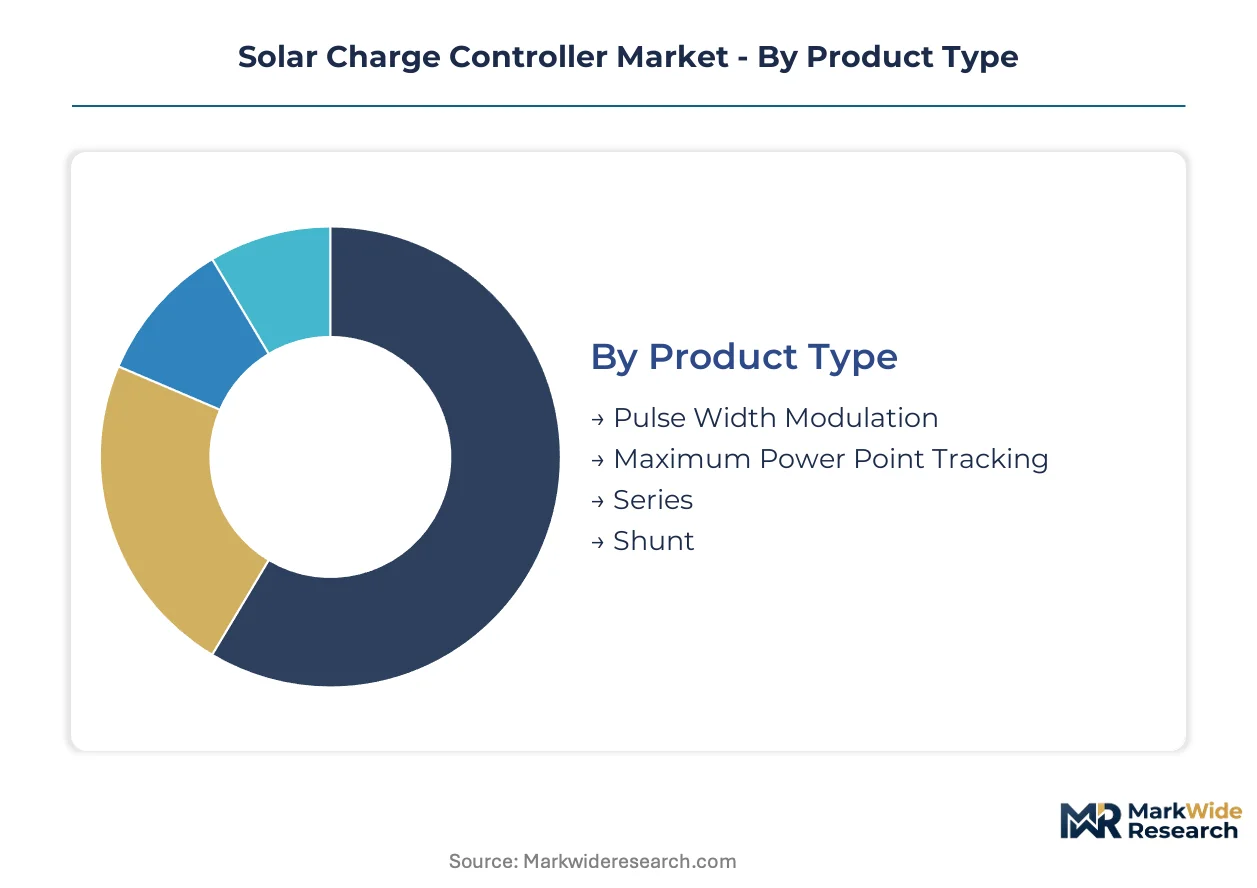
The market for solar charge controllers segments across diverse product types, technologies, applications, and end-users. This segmentation highlights the varied requirements for managing power from solar panels to battery banks, reflecting distinct performance needs and cost sensitivities. Understanding these divisions is crucial for manufacturers to tailor solutions effectively.
Product Type:
Product types in solar charge controllers exhibit varying replacement cycles, with advanced units seeing faster upgrades due to technological obsolescence.
- Maximum Power Point Tracking:These controllers dynamically adjust their input voltage to match the solar panel's maximum power point, maximizing energy harvest. Demand concentrates in larger residential and telecommunication systems where energy optimization is critical.
- Pulse Width Modulation:PWM controllers regulate battery charging by rapidly switching the current on and off, offering a cost-effective solution for smaller, less demanding applications. These units find widespread use in basic residential setups and rural electrification projects in India.
- Series:Series controllers interrupt the current path between the solar panel and the battery when the battery reaches a predefined voltage.
- Shunt:Shunt controllers divert excess current away from the battery once it attains a full charge state.
Pulse Width Modulation dominates the installed base. Maximum Power Point Tracking is where expansion concentrates.
Technology:
Technology segmentation reflects the functional capabilities and integration levels demanded by various applications, from basic power regulation to sophisticated system management.
- IoT Integrated:These controllers embed internet connectivity, enabling remote monitoring, diagnostics, and control of solar power systems from any location. Telecommunication infrastructure and critical off-grid sites are primary adopters, leveraging real-time data for operational efficiency.
- Bluetooth Enabled:Offering localized wireless communication, Bluetooth connectivity allows users to monitor and adjust controller settings via a smartphone or tablet within close proximity. Recreational vehicles and marine environments increasingly adopt these for convenient system management.
- Analog:Analog controllers use basic electronic components for simpler, less precise charge regulation, suitable for very low-cost systems.
- Digital:Digital controllers employ microprocessors for precise voltage and current regulation, often supporting multi-stage charging algorithms.
- Wireless:Wireless technology enables communication between system components without physical cables, simplifying installation and expanding monitoring options.
Digital technologies underpin most modern controllers. IoT Integrated and Bluetooth Enabled segments are expanding most quickly.
Application:
Application segments differentiate controllers based on the scale and complexity of the power system they serve, influencing unit volume and required features.
- Off-grid Power Systems:These applications rely entirely on solar power for electricity, serving remote homes, villages, or facilities without grid access. Government initiatives for rural electrification in India and sub-Saharan Africa significantly drive demand for these controllers.
- Telecommunication Systems:Solar charge controllers manage power for remote cell towers, base stations, and communication hubs where grid power is unreliable or unavailable. The need for continuous operation and remote monitoring drives demand for high-reliability MPPT units.
- Residential Solar Systems:Controllers in this segment manage power for grid-tied or off-grid homes, ranging from small rooftop arrays to larger battery backup systems.
- Agriculture Pumps:Solar-powered irrigation systems and water pumps in remote agricultural areas utilize controllers to manage energy for efficient water distribution.
- Marine Vessels:Boats and yachts employ ruggedized solar charge controllers to maintain onboard battery banks for navigation, communication, and auxiliary power.
Off-grid Power Systems represent a critical segment for social impact. Telecommunication Systems offer high-margin opportunities due to stringent reliability requirements.
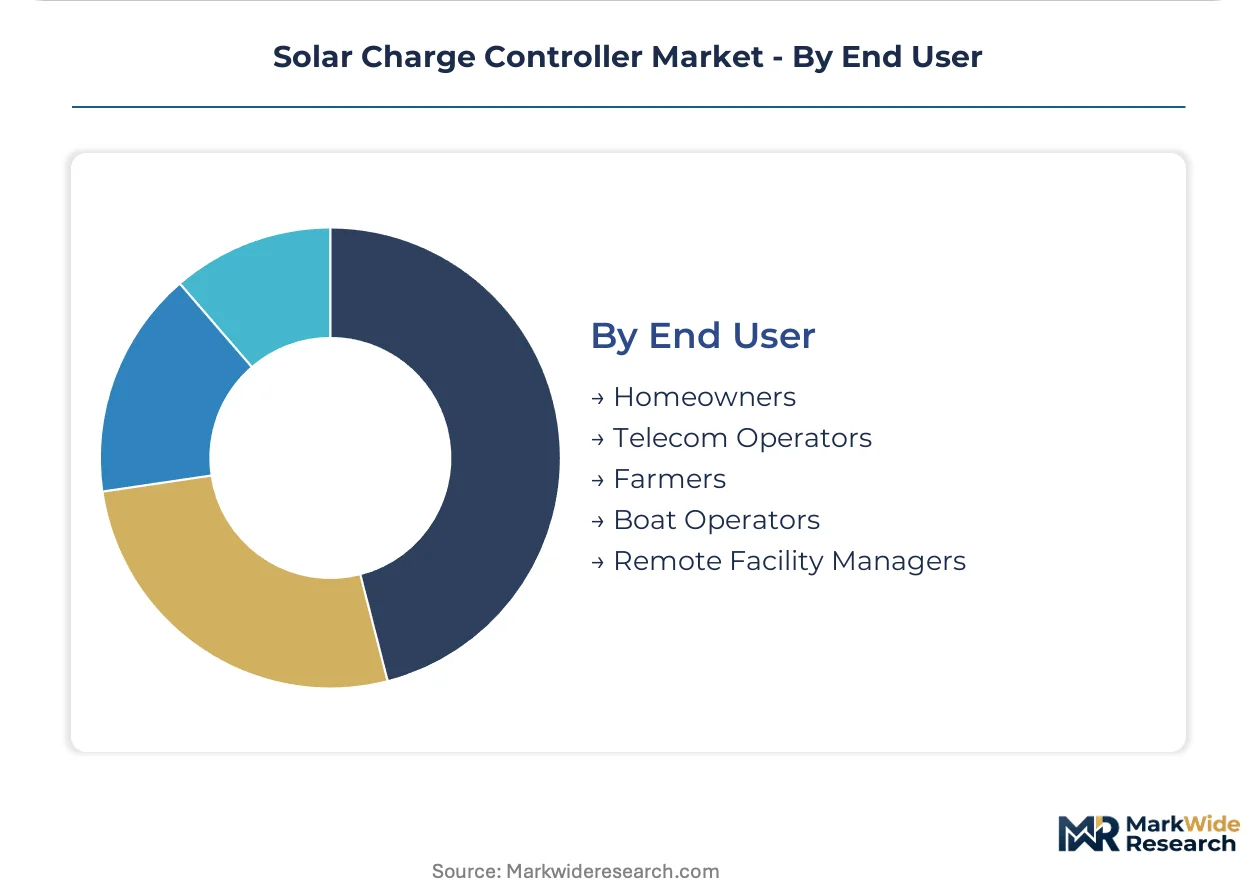
End User:
End-user categories reflect distinct customer needs and purchasing behaviors, from individual consumers to large-scale infrastructure operators.
- Remote Facility Managers:These users oversee power systems for isolated infrastructure, including scientific stations, environmental monitoring sites, and remote industrial operations. Their demand centers on robust, high-reliability controllers with advanced remote management capabilities.
- Telecom Operators:Telecommunication companies deploy controllers to ensure uninterrupted power for network equipment in areas with unreliable grid access or no grid at all. They prioritize durable, efficient units capable of integration into complex power management architectures.
- Homeowners:Individuals installing solar panels for residential use, ranging from small DIY projects to larger, professionally installed systems.
- Farmers:Agricultural professionals utilizing solar power for irrigation, livestock management, or remote facility power on their farms.
- Boat Operators:Owners of marine vessels, including recreational boats and commercial ships, who use solar power to charge onboard batteries.
Homeowners constitute a large volume segment. Remote Facility Managers and Telecom Operators represent specialized, high-value niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global flow of solar charge controllers increasingly originates from East Asian manufacturing hubs, catering to escalating off-grid power demands in developing economies. This trade corridor facilitates the deployment of essential energy management solutions. Rural electrification initiatives in particular drive significant volume across these regions.
India
Rural electrification programs significantly drive demand for solar charge controllers, particularly for basic residential setups. The government's PLI scheme for solar components supports domestic manufacturing and deployment. Regions like Uttar Pradesh and Bihar witness extensive deployment of off-grid solar systems.
Nigeria
Persistent energy access challenges create substantial demand for off-grid solar solutions and associated charge controllers. The Rural Electrification Agency (REA) implements projects to expand solar mini-grids across the country. Lagos and other urban centers are seeing increased adoption for commercial and residential backup power.
Germany
The European market, particularly Germany, emphasizes high-efficiency MPPT controllers for residential and commercial solar installations. Compliance with CE marking and RoHS directives is mandatory for market entry. Bavarian manufacturers often focus on advanced digital controllers and integrated energy management systems.
United States
Demand in the United States spans residential solar systems, recreational vehicles, and marine applications, with a strong preference for MPPT technology. Incentives under the Inflation Reduction Act (IRA) support broader solar adoption. California and Texas lead in residential and utility-scale solar deployments requiring robust charge management.
China
China serves as a critical manufacturing base for solar charge controllers, supplying both domestic and international markets. The country's dual carbon goals accelerate domestic solar installations, creating demand for various controller types. The Yangtze River Delta region is a hub for electronic component manufacturing, including microcontrollers for these devices.
Solar Charge Controller Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large diversified industrial conglomerates and specialized technology providers. Strategic archetypes include high-reliability specialists, integrated solution providers, and volume-focused manufacturers of cost-effective units. Companies actively pursue technology innovation and geographic expansion into underserved markets.
Specialists in high-reliability components, such as Morningstar Corporation, anchor the premium segment. Schneider Electric, leveraging its extensive industrial automation expertise, represents a major player in complex off-grid applications. Victron Energy occupies a distinct position by focusing on integrated solutions for mobile and marine environments.
| Leading Market Players |
|---|
| SUNGROW |
| Morningstar Corporation |
| Schneider Electric |
| Beijing Epsolar Technology |
| Victron Energy |
| Phocos |
| SRNE |
| Renogy |
| OutBack Power |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's substantial electronics manufacturing capacity directly influences downstream pricing power for solar charge controllers, particularly for volume-driven Pulse Width Modulation (PWM) units. This concentration affects global market accessibility and cost structures across various product tiers.
Pricing Analysis
The technology-generation pricing gap between advanced Maximum Power Point Tracking (MPPT) units and basic Pulse Width Modulation (PWM) controllers defines market pricing. A per-unit transactional model dominates, with price differentiation driven by energy conversion efficiency and compliance with international standards like IEC 62109. Pricing pressure stems from the rising availability of integrated solar power systems. Small-scale residential users remain the most price-sensitive segment, while telecommunication operators prioritize performance over cost.
Supply Chain Analysis
Export-control regimes on critical microcontrollers can limit the flow of advanced components, impacting solar charge controller manufacturing. Supply concentration centers heavily in East Asia, particularly China, for both finished goods and essential semiconductor inputs. The market relies on a concentrated base of semiconductor suppliers for critical microcontrollers. Component supply volatility represents a significant structural risk. Distribution runs through a blend of traditional electronics distributors, specialized system integrators, and direct-to-installer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story, primarily due to the high switching costs associated with integrating complex power management systems into existing off-grid infrastructure.
For Market Incumbents: Insulate core market share by continuously upgrading firmware with advanced charging algorithms. Invest in robust compliance with international standards like IEC 62109, creating a barrier against new entrants. This strategy mitigates the threat from integrated systems and component supply volatility. Control over key distribution channels, especially system integrators, strengthens market position.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated segments like agricultural electrification in Latin America. Focus on mobile and marine applications, which demand compact, ruggedized controllers. The DIY segment and small-scale residential applications offer the most penetrable entry points. A go-to-market angle centered on complete, pre-configured solar power kits simplifies customer adoption.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized technology providers with strong intellectual property in advanced charging algorithms. The long-term viability of solar charge controllers is assured by persistent off-grid power demand. Target acquisition archetypes include firms specializing in IoT integration or high-reliability devices for critical infrastructure. The primary signal to watch is the adoption rate of firmware-as-a-service models among commercial users.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Premium Firmware Upgrades | Unlock new revenue streams and enhance value for existing hardware users, particularly for Schneider Electric's industrial clients. |
| Expand into Agricultural Electrification | Capture demand in Latin America and Southeast Asia for powering remote water pumps and irrigation systems. |
| Invest in RoHS Compliance | Ensure market access and competitive advantage in the European Union and other regions with strict hazardous substance regulations. |
| Target Mobile and Marine Segments | Address the growing demand for ruggedized, compact solutions from Victron Energy's specialized customer base. |
| Optimize Semiconductor Sourcing | Mitigate supply chain risks and cost volatility for critical microcontrollers from East Asian manufacturers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Primary insights came from discussions with Remote Facility Managers, Telecom Operators, Homeowners, and R&D Engineers at manufacturing firms. Secondary data sources included IEC standards documentation, government rural electrification program reports from India and Nigeria, and relevant company financial filings. Both bottom-up and top-down triangulation methods were applied to ensure data consistency.
The forecast inputs considered a detailed analytical framework applied across the analysis window. Segmentation dimensions modeled included product type (MPPT/PWM), technology (IoT/Bluetooth), application (off-grid/telecom), end-user (homeowner/telecom operator), and regional policy support. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected adoption curves. Industry-specific inputs like rural electrification budgets and semiconductor availability significantly influenced the modeling.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or raw material costs would shift the trajectory. Forecasts reflect assumptions documented through expert consensus and historical data patterns. Material shifts in geopolitical stability or major technological breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Europe EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market