
 US Solar Tracker Market | 2026-2036
US Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar Tracker Market Insights
Utility-scale independent power producers are bifurcating from commercial and residential buyers as the dominant procurement channel for solar tracker systems. Nextracker leverages its vertical integration into domestic steel supply to capture IRA domestic content adders. Array Technologies anchors its position through wind-load engineering specialization for high-altitude desert installations. GameChange Solar competes on manufacturing scale with expanded Ohio production capacity serving Midwest utility pipelines.
A solar tracker is a mechanical mounting system that orients photovoltaic modules toward the sun throughout the day, typically achieving 20-35% additional energy yield over fixed-tilt configurations through single-axis or dual-axis rotation mechanisms. Ground-mounted utility applications dominate volume deployment where single-axis trackers command the largest installed base due to favorable levelized cost of energy economics. Smart trackers with machine-learning-driven backtracking algorithms represent the fastest-expanding product category as developers optimize for diffuse light and complex terrain. Rooftop commercial applications remain a niche segment constrained by structural load limits and shading complexity.
The Inflation Reduction Act's domestic content requirements and the Department of Energy's loan guarantee programs are reshaping tracker procurement standards toward US-manufactured steel and assembly. FERC interconnection queue reforms and NERC reliability standards influence tracker system design for grid-stability compliance in high-penetration renewable zones. Stakeholders must monitor evolving domestic content percentage thresholds and regional transmission organization interconnection timelines to align manufacturing capacity with project development cycles.
Market Dynamics
The Inflation Reduction Act's domestic content bonus credits are restructuring solar tracker procurement economics, forcing developers to requalify supply chains around US-sourced steel and assembly capacity or forfeit percentage-point adders on project returns.
Growth Catalysts
- IRA Domestic Content Adders:The Inflation Reduction Act's 10% investment tax credit bonus for US-manufactured components is redirecting capital toward domestic tracker production facilities.
- Utility-Scale Pipeline Expansion:Texas and Arizona interconnection queues show concentrated gigawatt-scale project development favoring single-axis tracker economics over fixed-tilt alternatives.
- Machine-Learning Backtracking:Smart tracker algorithms that optimize row-to-row shading in diffuse light conditions are improving capacity factors in high-penetration renewable zones.
Market Restraints
- Steel Price Volatility:Galvanized steel coil represents 60-70% of tracker bill-of-materials, exposing margins to commodity swings and tariff uncertainty.
- Domestic Manufacturing Bottlenecks:US steel rolling and coating capacity constraints limit tracker supply expansion speed despite demand signals.
- Interconnection Queue Delays:FERC reform implementation lags are stretching project commissioning timelines and compressing equipment delivery windows.
Strategic Opportunities
- Agrivoltaics Integration:Elevated tracker configurations enabling dual-use agriculture are opening project development on marginal farmland in Midwest states.
- Bifacial Module Pairing:Tracker architectures optimized for rear-side gain capture are extracting incremental yield from next-generation photovoltaic panels.
- Department of Energy Loan Guarantees:DOE Title 17 financing is de-risking capital investment in greenfield tracker manufacturing plants.
Industry Challenges
- Wind-Load Engineering Talent:Specialized structural analysis capability for extreme weather zones remains concentrated among a limited engineering pool.
- NERC Compliance Complexity:Grid-stability standards for high-penetration renewable zones are adding certification layers to tracker control system design.
- Supply Chain Reconfiguration:Shifting from Asian to US steel sourcing requires requalification of welding and galvanization processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar Tracker Market |
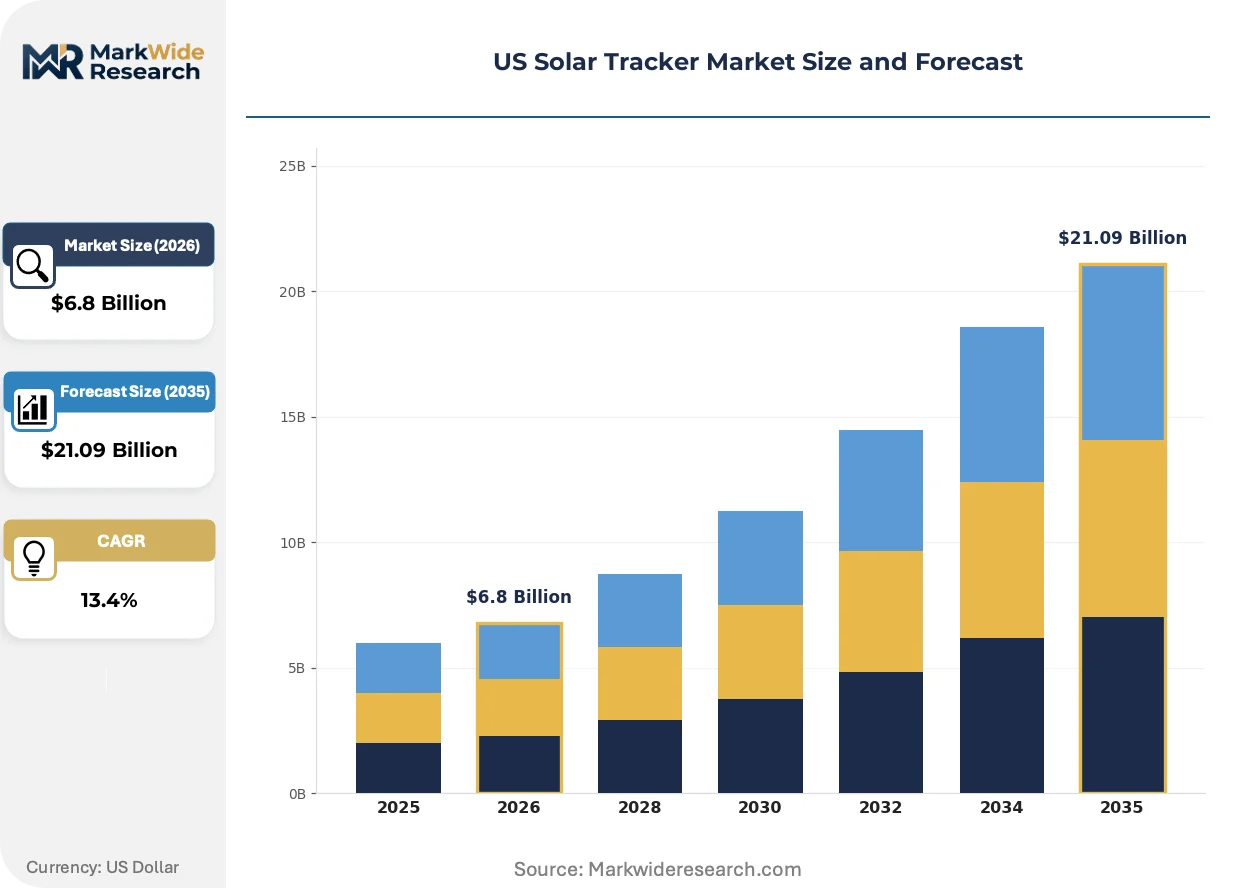
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis Tracker, Dual-Axis Tracker, Fixed Tilt, Smart Trackers End User: Utility Scale, Commercial, Residential, Industrial Application: Ground Mounted, Rooftop, BIPV, Floating Systems Installation Type: Onshore, Offshore, Ground Installation, Integrated Solutions |
| Companies Covered | Nextracker, Array Technologies, GameChange Solar, PV Hardware, Soltec, FTC Solar, Valmont Industries, TrinaTracker, Ideematec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar Tracker Market Trends and Innovations
Tracker technology is bifurcating between commodity single-axis systems and intelligent platforms that embed sensing, control, and grid-interactive capabilities. This evolution is compressing hardware margins while expanding software and service revenue pools.
Distributed control architectures with row-level motorization and independent tracking algorithms are fragmenting the traditional centralized-drive market. Mid-scale developers in the Southwest are adopting these systems for terrain-following flexibility. The structural consequence is margin compression for legacy centralized-drive suppliers and opening for modular electronics specialists.
The Inflation Reduction Act's domestic content thresholds are forcing requalification of steel supply chains toward US-melted and -rolled sources. Tracker manufacturers are securing captive supply agreements with domestic mills or integrating backward into steel processing. The segment most affected is utility-scale procurement, where developers now embed domestic content compliance into RFP scoring.
Independent power producers are consolidating procurement around fewer, larger tracker suppliers capable of multi-gigawatt execution. This buyer concentration is displacing regional equipment vendors and favoring vertically integrated manufacturers with captive steel supply. The shift is most visible in Texas, where project sponsors now require single-source accountability across engineering, supply, and installation.
US Solar Tracker Market Segmentation
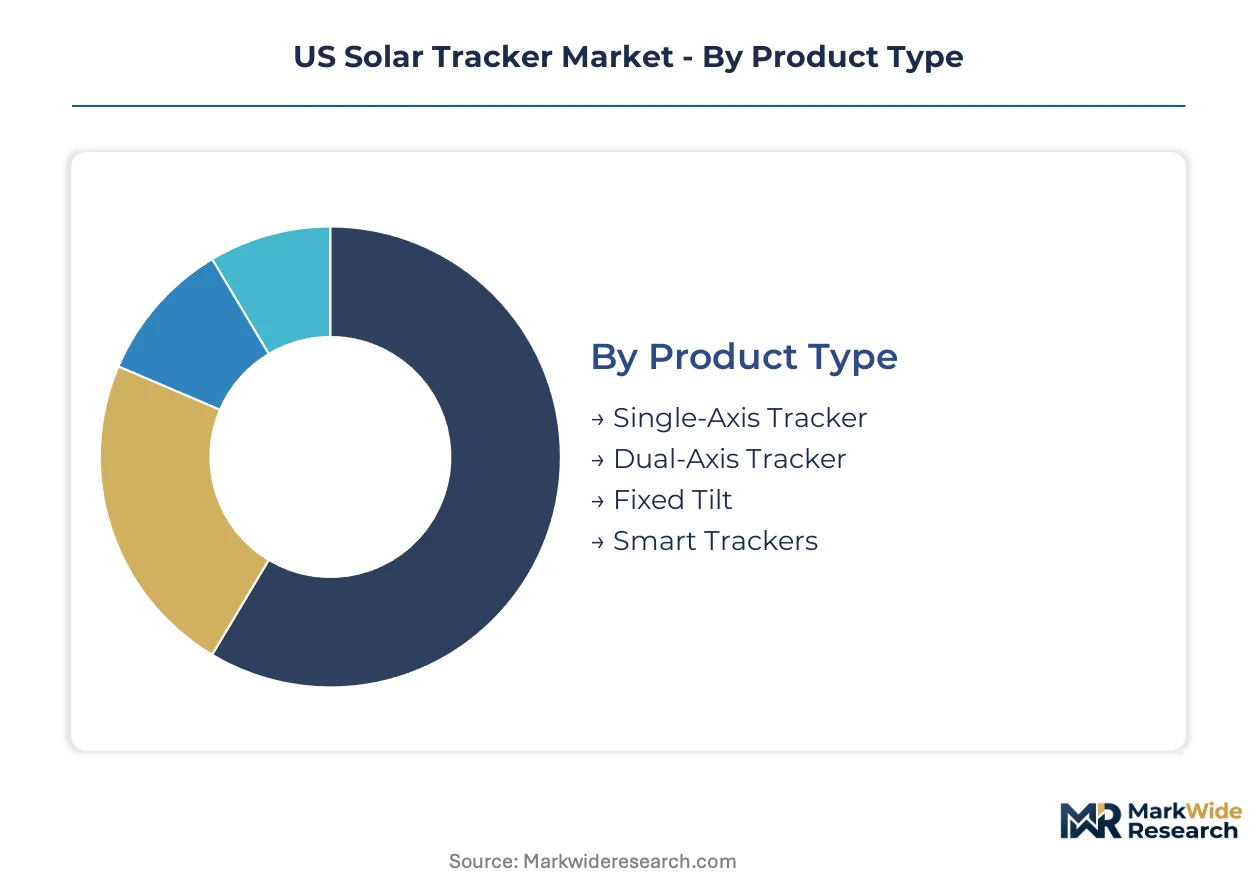
Segmentation in the US solar tracker market reveals where capital deployment concentrates and which technology configurations command premium economics. Developers align tracker selection with interconnection timelines, domestic content compliance, and terrain constraints across Southwest utility zones.
Product Type:
Margin pools concentrate in systems that embed control intelligence and software-driven optimization capabilities rather than commodity hardware alone.
- Single-Axis Tracker:Horizontal rotation mechanisms track the sun's east-west path, delivering 20-35% yield improvement over fixed-tilt configurations. Texas and Arizona utility pipelines favor this architecture for favorable LCOE economics on flat desert terrain. The segment anchors volume deployment but faces margin compression from steel commodity exposure.
- Smart Trackers:Machine-learning-driven backtracking algorithms optimize row-to-row shading in diffuse light and complex topography. Southwest developers adopt these systems for terrain-following flexibility and grid-stability compliance. Control software and predictive maintenance subscriptions generate recurring revenue streams distinct from hardware sales.
- Dual-Axis Tracker:Two-degree-of-freedom rotation captures maximum direct normal irradiance through azimuth and elevation adjustment.
- Fixed Tilt:Stationary racking systems without tracking capability serve cost-constrained installations where land availability and simplicity outweigh yield optimization.
The dominant share belongs to Single-Axis Tracker, while Smart Trackers are gaining share fastest.
End User:
Procurement scale and contract duration separate volume buyers from price-sensitive segments with fragmented decision-making.
- Utility Scale:Independent power producers and project developers deploy gigawatt-scale installations with 25-30 year power purchase agreements. IRA domestic content adders reshape procurement scoring toward US-manufactured steel and assembly capacity. FERC interconnection queue positions determine equipment delivery windows and supplier selection.
- Commercial:C&I buyers with 500kW-5MW rooftop and carport installations face structural load limits and shading complexity that constrain tracker adoption.
- Industrial:On-site generation for manufacturing facilities and data centers prioritizes land-use efficiency over tracking economics.
- Residential:Single-family rooftop applications rarely justify tracker mechanical complexity given space constraints and permitting friction.
Utility Scale commands the installed base, with Commercial expanding most quickly as agrivoltaics configurations open marginal farmland.
Application:
Ground conditions and mounting infrastructure costs determine where tracking mechanics deliver viable returns.
- Ground Mounted:Open-field installations on graded terrain support single-axis and dual-axis tracker deployment with standardized foundation engineering. Texas, Arizona, and Nevada desert parcels enable gigawatt-scale project development with minimal shading interference.
- Rooftop:Structural load limits, wind exposure, and parapet shading constrain tracker mechanics to specialized commercial configurations with distributed drive architectures.
- BIPV:Building-integrated photovoltaic systems prioritize architectural aesthetics and envelope performance over solar tracking functionality.
- Floating Systems:Reservoir and canal-mounted installations face corrosion and mooring complexity that limits tracker mechanical adoption.
Ground Mounted holds the dominant position, though BIPV is climbing the fastest as building codes integrate solar mandates.
Installation Type:
Project delivery models separate self-perform construction from integrated engineering-procurement-construction contracts with performance guarantees.
- Ground Installation:Conventional pile-driven or ballasted foundations for open-field utility and commercial deployments with standardized civil engineering.
- Integrated Solutions:Single-source accountability spanning tracker supply, installation, and commissioning with multi-gigawatt execution capability.
- Onshore:Terrestrial project development excluding coastal or marine environments with standard wind-load engineering.
- Offshore:Coastal and marine-adjacent installations requiring corrosion-resistant materials and enhanced structural certification.
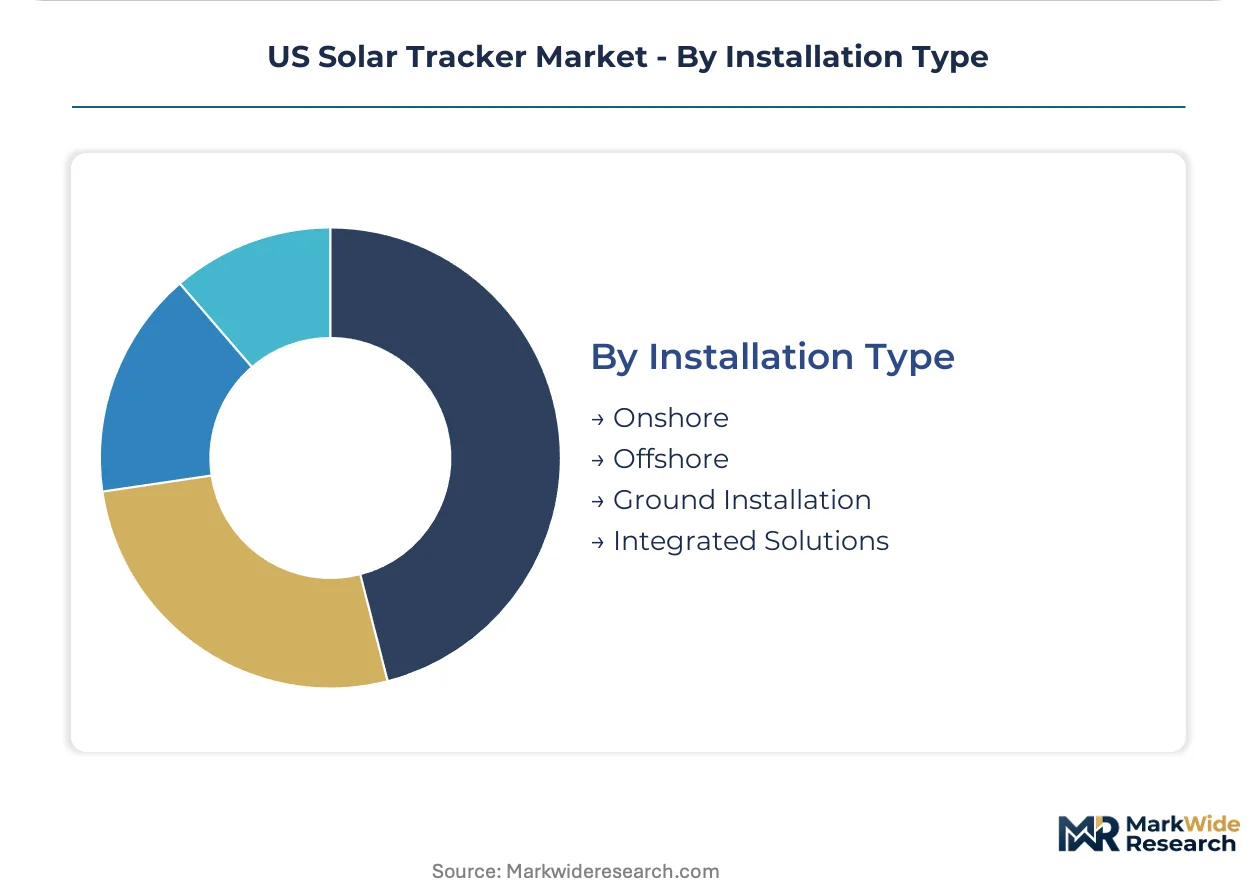
Ground Installation represents the largest deployment mode, while Integrated Solutions are expanding most quickly as buyer consolidation favors turnkey accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic steel rolling capacity clusters along the Gulf Coast and Great Lakes corridors, concentrating tracker manufacturing investment near these metallurgical hubs. FERC interconnection queue positions and IRA domestic content thresholds are redrawing procurement geography across utility-scale development zones.
Southwest
Texas and Arizona host the densest interconnection queues for gigawatt-scale tracker deployment. The Inflation Reduction Act's domestic content bonus credits are redirecting developer procurement toward US-assembled systems. Nextracker operates manufacturing facilities in Texas and Arizona to serve regional utility pipelines with compliant steel supply.
California
Utility-scale development in the Central Valley and Mojave Desert favors single-axis trackers for high irradiance capture. The California Energy Commission's permitting reforms are accelerating project timelines for agrivoltaics configurations. Array Technologies maintains engineering presence in the state for wind-load optimization on complex terrain.
Midwest
Ohio and Illinois are emerging as tracker manufacturing nodes serving regional renewable energy zones. The Department of Energy's loan guarantee programs are de-risking greenfield steel processing investments. GameChange Solar expanded Ohio production capacity to capture Midwest utility procurement with domestic content compliance.
Southeast
Florida and Georgia utility pipelines are adopting elevated tracker configurations for dual-use agriculture on marginal farmland. FERC interconnection reforms are compressing equipment delivery windows for coastal wind-load zones. Regional developers are qualifying tracker suppliers with hurricane-resistant engineering certification.
US Solar Tracker Market Competitive Landscape
Concentration sits with vertically integrated manufacturers controlling domestic steel supply chains. The vendor base separates into three tiers: multi-gigawatt execution specialists with captive metallurgical capacity, modular electronics providers with distributed drive architectures, and regional fabricators serving niche terrain applications. Strategic moves center on backward integration into steel processing and securing DOE loan guarantees for manufacturing expansion.
Among US-based system integrators, Nextracker, Array Technologies, and GameChange Solar exemplify the dominant competitive archetypes. Nextracker represents the vertically integrated model with upstream steel supply control. Array Technologies occupies the wind-load engineering specialization position for extreme weather zones. GameChange Solar anchors the manufacturing scale tier with expanded domestic production footprint. These three companies capture the majority of utility-scale procurement volume where IRA domestic content compliance determines RFP scoring.
| Leading Market Players |
|---|
| Nextracker |
| Array Technologies |
| GameChange Solar |
| PV Hardware |
| Soltec |
| FTC Solar |
| Valmont Industries |
| TrinaTracker |
| Ideematec |
| Others |
Pricing and Supply Chain Analysis
The Inflation Reduction Act's domestic content thresholds gate both tracker qualification and price differentiation simultaneously. Developers forfeit percentage-point adders on project returns unless suppliers meet US-melted and US-rolled steel requirements, forcing procurement scoring to weight domestic provenance heavily.
Pricing Analysis
The Inflation Reduction Act dictates the pricing tier structure across compliant and non-compliant supply tiers. Three-tier pricing separates premium domestic-content systems from standard import-blended configurations and economy fixed-tilt alternatives. Price differentiation rests on steel origin certification and wind-load engineering tier. Cost compression in the economy tier is intensifying because developers optimize for LCOE on flat desert terrain. Utility-scale independent power producers show least price sensitivity given long-term PPA economics, while commercial rooftop buyers face acute budget constraints.
Supply Chain Analysis
Port congestion on the Houston-Galveston trade lane shapes inbound steel coil availability for tracker manufacturers. Supply concentrates in domestic mills along the Gulf Coast and Great Lakes corridors, with secondary sourcing from Mexican and Canadian rolling facilities. Raw material dependencies center on galvanized steel coil, aluminum extrusions, and precision drive motors. Single-source vulnerability persists in domestic zinc coating capacity. Distribution runs through direct mill relationships to captive fabrication facilities, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
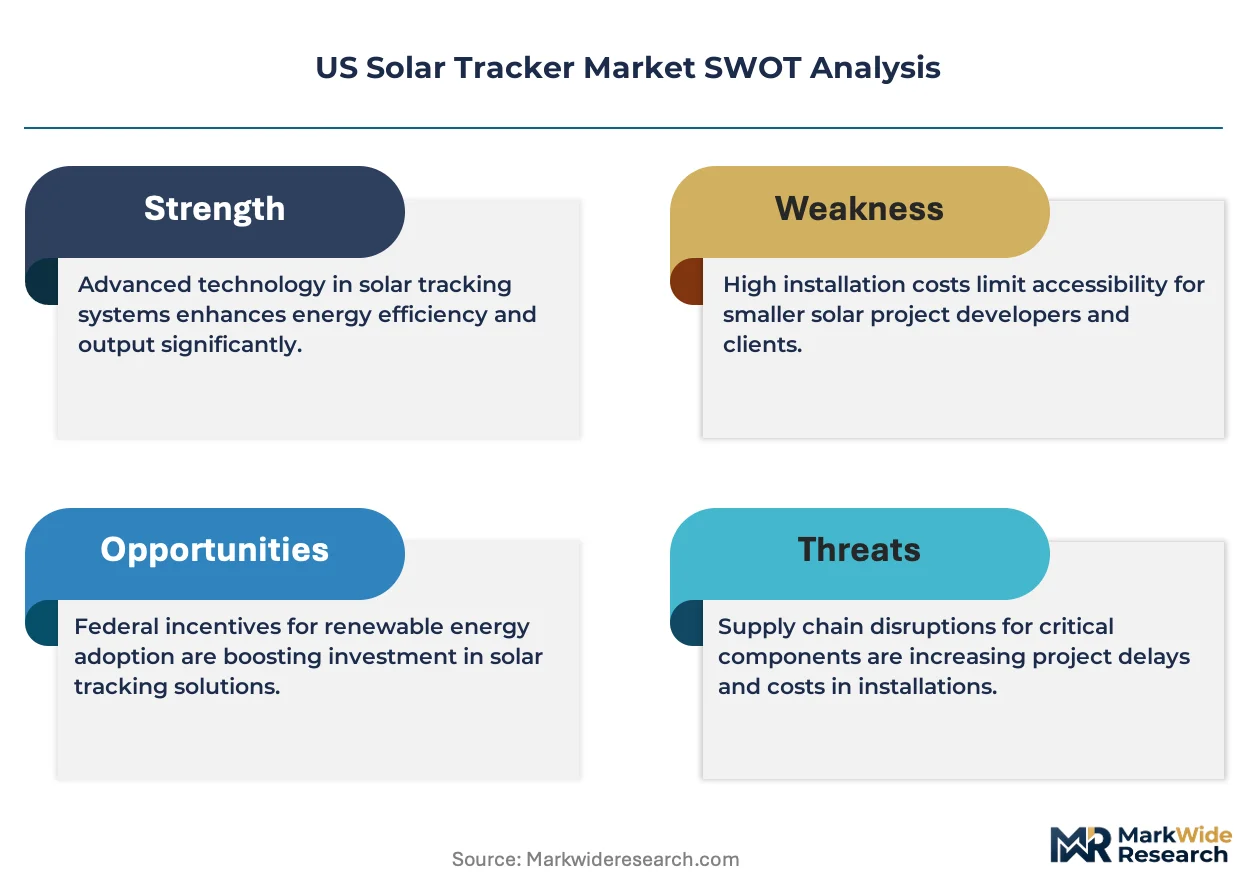
Fixed-tilt racking systems pose a substitution threat that tracker incumbents must navigate as developers weigh yield premiums against capital simplicity on marginal projects.
For Market Incumbents: Fortify domestic steel supply through captive mill agreements or backward integration into rolling capacity. Array Technologies anchors wind-load engineering specialization as a defensive moat against commodity competitors. Nextracker's vertical integration model demonstrates how upstream control over metallurgical inputs secures IRA bonus credit access. For New Entrants and Emerging Players: UL 3703 certification fast-track enables entry into the commercial agrivoltaics segment where elevated tracker configurations face lighter competitive density. Midwest utility pipelines offer the most penetrable geography given Ohio manufacturing expansion and regional renewable energy zone development. Target integrated EPC relationships rather than equipment-only supply to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: FERC interconnection queue reforms reshape the acquisition landscape toward suppliers with multi-gigawatt execution capability and domestic content compliance infrastructure. Long-term viability favors vertically integrated manufacturers with captive steel processing over modular electronics specialists facing margin compression. Monitor NERC reliability standard revisions as the signal for grid-stability certification requirements that would favor control-system-embedded tracker platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Steel Supply Integration | Captive mill agreements secure IRA domestic content bonus credit eligibility for utility-scale developers. |
| Smart Tracker Control Platform Development | Machine-learning backtracking algorithms differentiate offerings in high-penetration renewable zones. |
| Agrivoltaics Configuration Engineering | Elevated tracker architectures open marginal farmland in Midwest and Southeast state pipelines. |
| Wind-Load Certification Expansion | Extreme weather engineering capabilities qualify suppliers for coastal and high-altitude desert installations. |
| Integrated EPC Service Capability | Single-source accountability spans tracker supply through commissioning for buyer consolidation trends. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA generation databases, FERC interconnection filings, and steel industry trade publications. Primary interviews captured perspectives from utility planning officers, independent power producer project developers, EPC contractors, tracker manufacturing executives, and domestic steel mill procurement leads. Secondary validation drew from Department of Energy loan guarantee announcements, NERC reliability standards documentation, and state renewable portfolio credit tracking systems. Bottom-up project pipeline aggregation triangulates against top-down market sizing from equipment shipment disclosures.
Segmentation dimensions modeled include product type architecture, end-user procurement scale, application mounting infrastructure, and installation delivery model across the projection horizon. CAGRs derive from regression analysis of historical deployment velocity against interconnection queue depth and domestic manufacturing capacity expansion. Forecast inputs incorporate IRA domestic content threshold evolution and regional transmission organization interconnection timeline assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained IRA incentive structures and FERC reform implementation; material deviation would warrant model refresh. Specific risk factors include steel tariff volatility, NERC compliance timeline acceleration, and substitute fixed-tilt technology cost breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Vietnam Solar Energy Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market