
 Europe Solar Photovoltaic (PV) Market | 2026-2036
Europe Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Photovoltaic (PV) Market Foresight
Modular system bundling with energy storage and smart inverters is realigning procurement patterns for commercial buyers. Iberdrola, S.A. leverages its utility-scale development pipeline to anchor long-term power purchase agreements across Southern Europe. JinkoSolar Holding Co., Ltd. competes on manufacturing scale, sustaining cost leadership in monocrystalline module supply. TotalEnergies positions its distributed generation unit to capture rooftop installations through integrated financing structures.
Europe Solar Photovoltaic (PV) systems convert sunlight into direct-current electricity using semiconductor junctions, typically silicon-based cells with power conversion efficiencies ranging from 18% to 23% for commercial modules, then feeding alternating current to buildings or grids through inverters. Monocrystalline modules dominate installed capacity due to superior efficiency density, while bifacial designs claim the fastest expansion as agrivoltaic and floating projects exploit rear-side gain. Utility-scale ground-mounted installations concentrate the largest revenue pools, though residential rooftop systems generate higher margin per watt because of soft-cost premiums and self-consumption incentives.
The EU Green Deal and REPowerEU framework mandate accelerated renewable deployment, while CE marking and the EU AI Act for smart grid integration shape product compliance pathways. Germany's KBA coordinates standards for building-integrated systems, and France's ANSM oversees occupational safety in installation protocols. Stakeholders must track evolving F-Gas Regulation limits on heat pumps paired with solar thermal hybrids, and monitor grid code harmonization across ENTSO-E member states to anticipate interconnection queue risks.
Market Dynamics
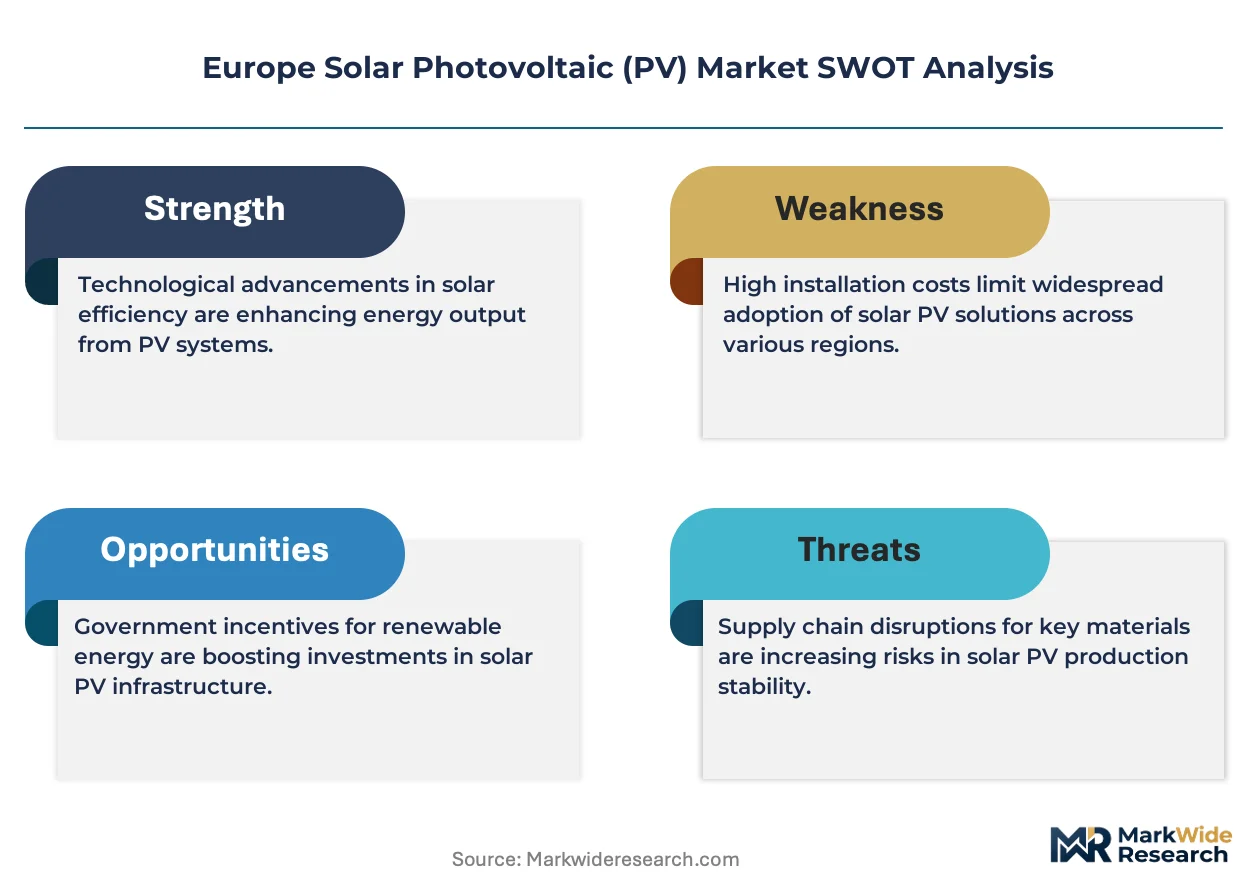
The EU Green Deal and REPowerEU framework are compressing project development timelines while forcing grid code harmonization across ENTSO-E member states, fundamentally restructuring how developers secure interconnection queues and offtake contracts.
Growth Catalysts
- Agrivoltaic deployment:Dual-use land frameworks in France and Italy unlock agricultural land for bifacial installations without sacrificing crop yields.
- Building-integrated mandates:Germany's KBA standards for rooftop-integrated systems accelerate commercial and industrial retrofit cycles.
- REPowerEU acceleration:The framework's streamlined permitting targets halve approval timelines for utility-scale ground-mounted projects.
Market Restraints
- Polysilicon supply concentration:European module assemblers remain dependent on Xinjiang-origin feedstock despite due diligence regulations.
- F-Gas Regulation limits:Restrictions on heat pump-solar thermal hybrids constrain residential system bundling options.
- Grid saturation:Distribution network congestion in southern Spain and Italy blocks project energization regardless of generation capacity.
Strategic Opportunities
- Floating PV expansion:Reservoir and quarry installations in Portugal and Greece exploit underutilized water surfaces with minimal land conflict.
- Smart inverter convergence:Module-level power electronics paired with grid-forming inverters enable commercial aggregators to stack revenue streams.
- Corporate PPA origination:Spain's merchant price exposure attracts energy-intensive manufacturers seeking 10-15 year baseload contracts.
Industry Challenges
- Electrical engineering talent scarcity:Grid integration specialists with ENTSO-E code expertise command premium wages across Germany and the Netherlands.
- CE marking complexity:Module manufacturers face divergent national interpretations of the EU AI Act for smart grid interface compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Photovoltaic (PV) Market |
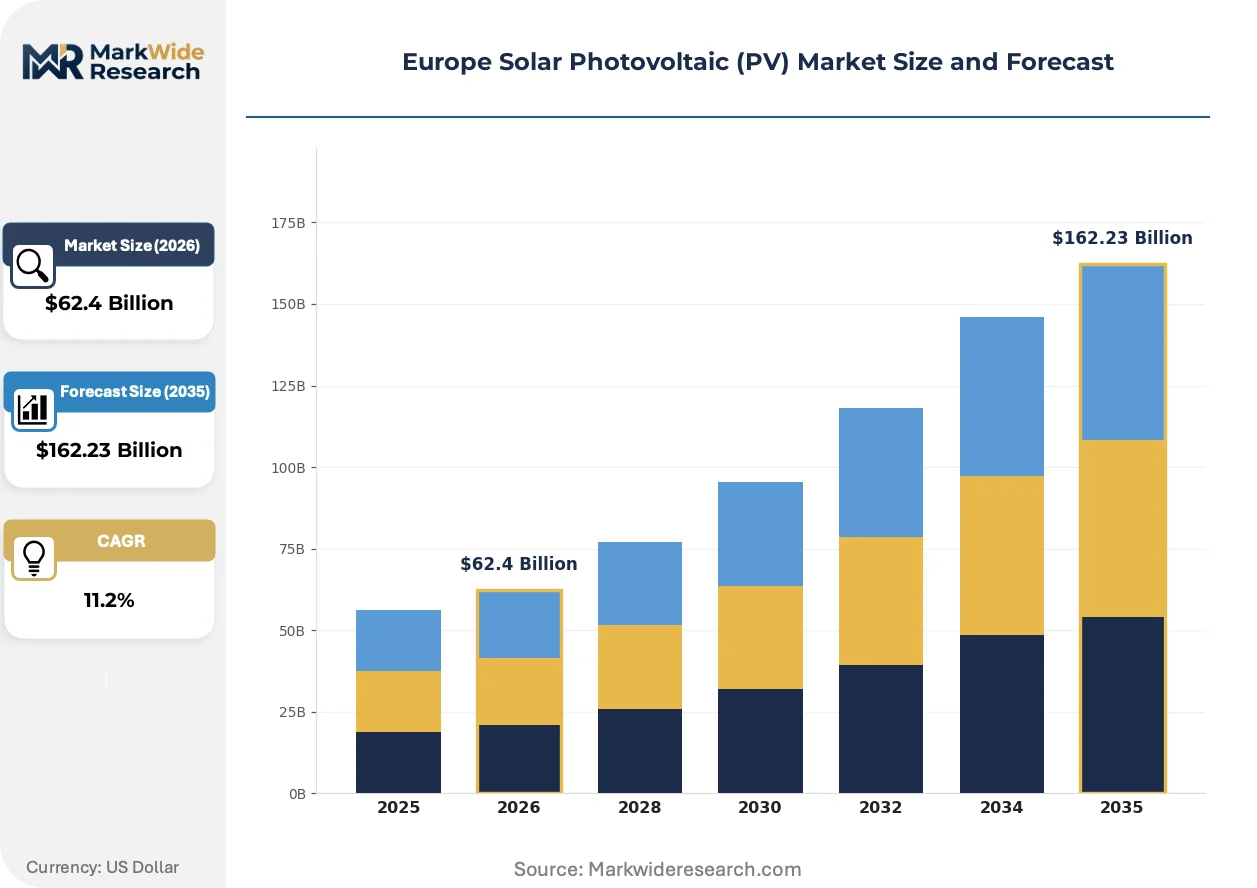
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $162.23 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin Film, Bifacial Technology: Grid-Tied, Off-Grid, Hybrid, Concentrated Solar Power End User: Residential, Commercial, Industrial, Utility Installation Type: Rooftop, Ground-Mounted, Building Integrated, Floating |
| Companies Covered | Lightsource BP Renewable Energy Investments Limited, Hanwha Q CELLS Technology Co., Ltd, SunPower Corporation, Iberdrola, S.A, JinkoSolar Holding Co., Ltd, First Solar, Inc., E.ON SE, TotalEnergies, ENGIE Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Photovoltaic (PV) Market Shifts & Advancements
Module-level optimization and grid-forming capabilities are compressing the technical boundary between generation asset and network infrastructure, forcing inverter manufacturers and project developers to recalibrate their competitive positioning.
Bifacial PERC and TOPCon cell architectures are absorbing rear-side albedo gain to push commercial module outputs beyond 600W in standard test conditions. Iberian agrivoltaic developers are adopting these formats fastest, exploiting Spain's high irradiance and France's dual-use tariff premiums. The technology is absorbing project IRR compression that would otherwise erode developer margins under rising interconnection costs.
The EU AI Act's grid integration provisions are mandating cybersecurity certification for smart inverters above 50kW. Module suppliers must now embed secure firmware update protocols and encrypted communication stacks. Southern European markets face the steepest compliance ramps as their distributed generation penetration exceeds legacy SCADA upgrade cycles.
Aggregated procurement platforms are consolidating commercial and industrial buyer demand into volume tenders that bypass traditional EPC markups. German Mittelstand manufacturers are pooling rooftop requirements through sector associations, securing direct module pricing previously reserved for utility-scale offtakers. This behavior concentrates most visibly in Baden-Württemberg's automotive supply chain, where energy cost hedging now drives 7-10 year self-consumption contracts.
Europe Solar Photovoltaic (PV) Market Segmentation
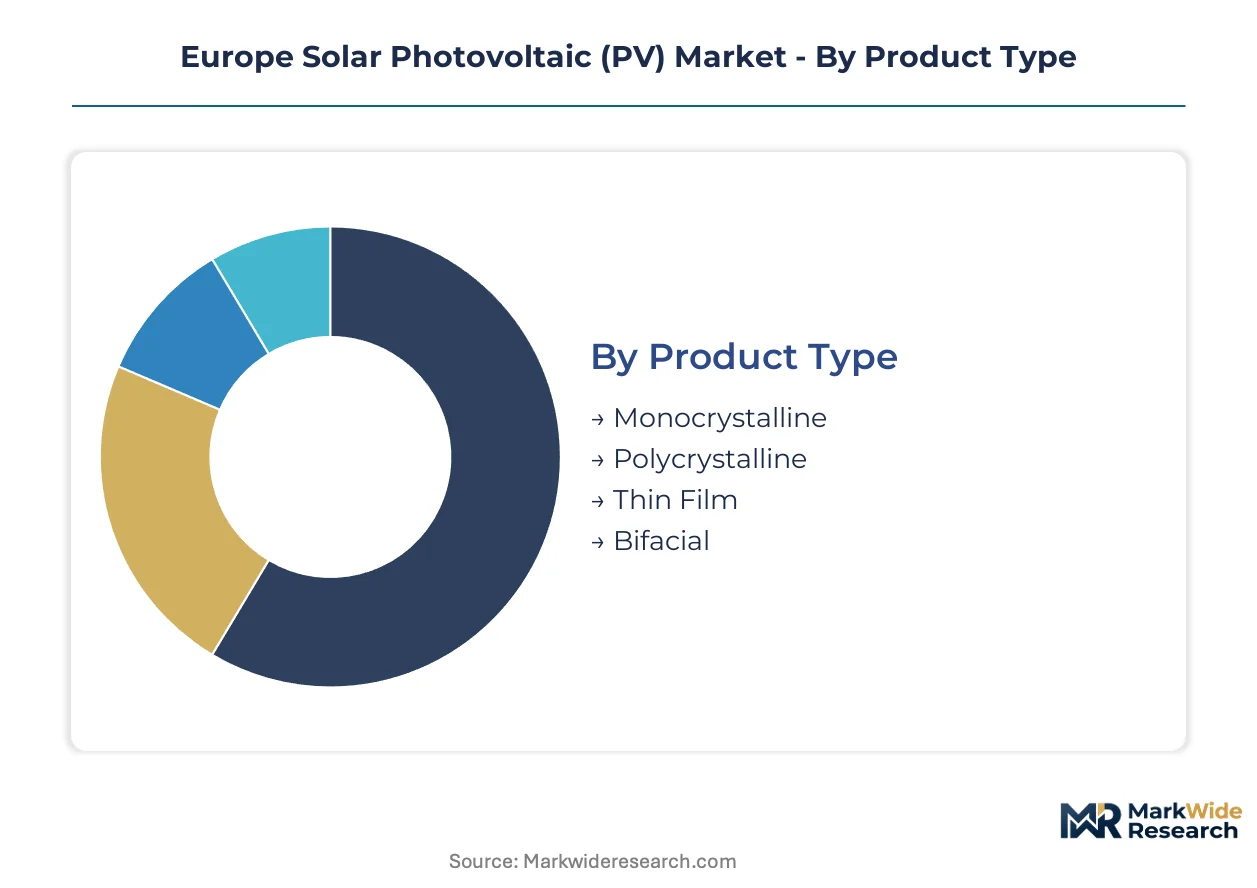
Technology choices in the Europe Solar Photovoltaic (PV) Market reflect divergent cost-efficiency tradeoffs across installation scales and regulatory environments. Procurement patterns vary sharply between subsidy-dependent residential buyers and merchant-exposed utility developers.
Product Type:
Buyers differentiate primarily by module efficiency density and land availability constraints.
- Monocrystalline:Silicon ingots from single-crystal boules deliver conversion efficiencies of 20-23% in commercial modules. German and Spanish utility-scale developers specify these formats to maximize yield per hectare where land costs pressure project IRR.
- Bifacial:Dual-sided cell architectures capture rear-side albedo gain, pushing effective outputs beyond 600W in high-reflectivity environments. Italian agrivoltaic projects in Puglia and French dual-use installations in Provence absorb these modules fastest.
- Polycrystalline:Multi-crystal silicon structures trade efficiency for lower manufacturing energy intensity, finding residual demand in price-sensitive Eastern European residential retrofits.
- Thin Film:Cadmium-telluride and CIGS chemistries enable flexible substrates and low-light performance, occupying niche building-integrated applications in German KBA-compliant facades.
Volume sits with Monocrystalline; growth tilts toward Bifacial.
Technology:
System architecture determines grid interconnection complexity and revenue stacking potential.
- Grid-Tied:Direct AC coupling to distribution networks dominates installed base, with German Mittelstand manufacturers aggregating rooftop capacity into virtual power plants under ENTSO-E harmonized codes.
- Hybrid:DC-coupled battery integration enables self-consumption optimization and backup power, expanding fastest in Italian commercial installations facing grid saturation delays.
- Off-Grid:Stand-alone systems with dedicated storage serve Greek island municipalities and remote Alpine lodges beyond distribution network reach.
- Concentrated Solar Power:Parabolic trough and tower configurations with thermal storage occupy Spanish Mancha and Andalusian markets, though PV cost compression constrains new deployment.
Grid-Tied absorbs current procurement; Hybrid claims the steepest expansion trajectory.
End User:
Customer scale dictates financing structure and offtake contract duration.
- Utility:Ground-mounted projects above 10MW secure long-term power purchase agreements through competitive auctions in Spain and merchant exposure in wholesale markets. Iberdrola's Southern European pipeline anchors this segment.
- Residential:Sub-10kW rooftop systems generate premium margins through soft-cost markups and net metering incentives, concentrating in German Baden-Württemberg and Italian Lombardy.
- Commercial:Mid-scale installations on logistics warehouses and manufacturing plants exploit self-consumption tariffs, with French C&I buyers pooling demand through sector associations.
- Industrial:Energy-intensive manufacturers in Spain's Basque Country and Germany's Ruhr Valley contract corporate PPAs to hedge electricity price volatility.
Utility commands capital deployment; Residential delivers margin per watt.
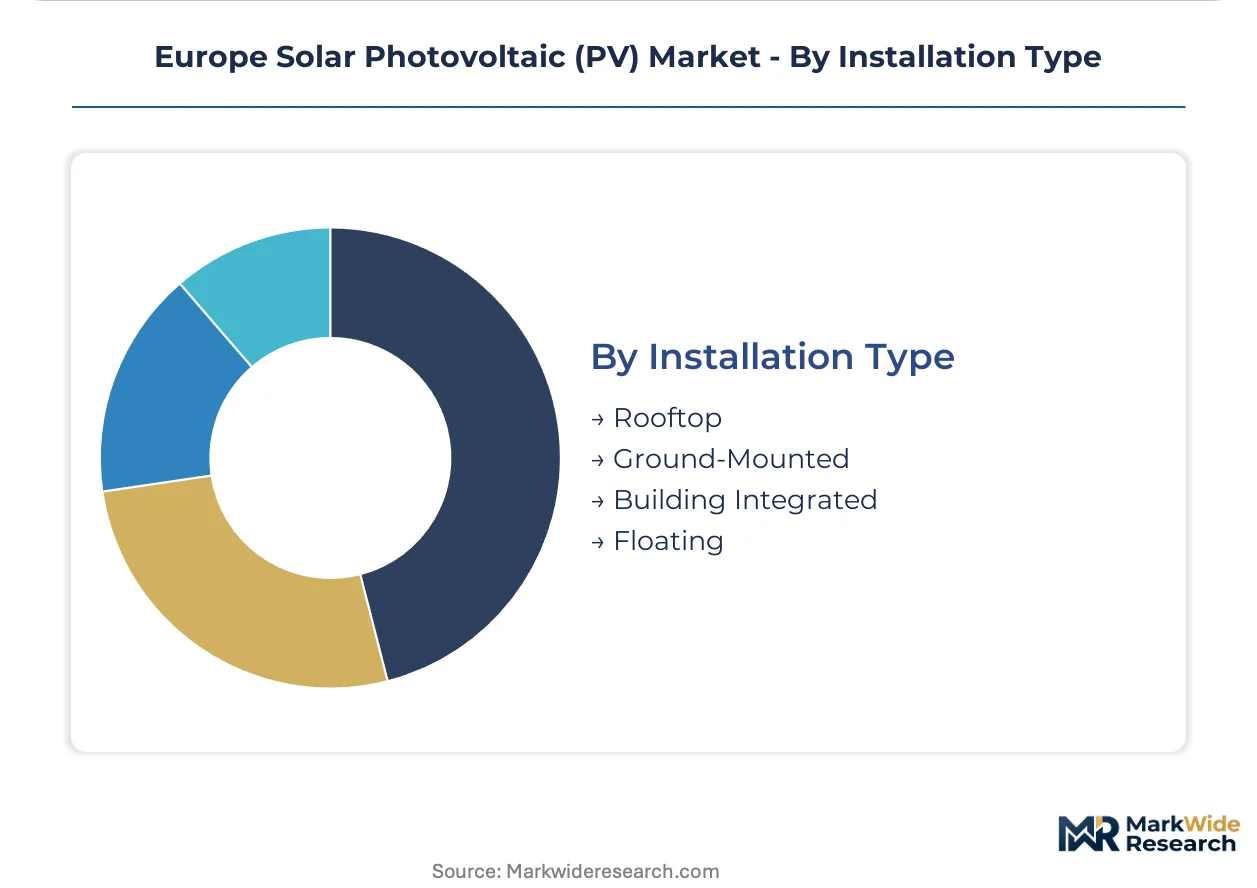
Installation Type:
Site constraints and land-use regulations shape developer site selection.
- Ground-Mounted:Utility-scale arrays on agricultural and brownfield sites concentrate revenue pools, though REPowerEU permitting acceleration has compressed development timelines only in Germany and Spain.
- Rooftop:Commercial and industrial surface exploitation dominates deployment volume, with Italian Superbonus 110% incentives driving retrofit cycles through 2026.
- Floating:Reservoir and quarry installations in Portugal's Alqueva and Greek lignite pit lakes exploit minimal land conflict and evaporative cooling gains.
- Building Integrated:Facade and canopy systems meeting German KBA structural standards capture premium tariffs in urban infill projects.
Ground-Mounted holds installed capacity; Floating gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly capacity concentrates in Southeast Asia while European demand absorbs deployment across Germany, Spain, and Italy. Grid saturation in southern markets and permitting acceleration in northern jurisdictions are reshaping developer site selection.
Germany
Industrial electricity tariffs and Mittelstand energy hedging sustain rooftop demand across Baden-Württemberg and North Rhine-Westphalia. KBA building-integrated standards accelerate commercial retrofit cycles. The Ruhr Valley industrial corridor anchors corporate PPA origination for automotive supply chain decarbonization.
Spain
Merchant price exposure and high irradiance attract utility-scale investment across Castilla-La Mancha and Extremadura. REPowerEU permitting targets compress approval timelines for ground-mounted arrays. The Basque Country industrial cluster contracts long-term baseload agreements to hedge electricity volatility.
Italy
Grid saturation delays in southern regions push developers toward agrivoltaic dual-use frameworks in Puglia and Sicily. Superbonus 110% incentives drive residential retrofit volume through Lombardy and Veneto. ANSM occupational safety protocols shape installation labor deployment.
France
Dual-use tariff premiums unlock agricultural land for bifacial installations across Provence-Alpes-Côte d'Azur. CE marking and EU AI Act cybersecurity mandates complicate smart inverter deployment. The Occitanie region concentrates floating PV pilot projects on reservoir surfaces.
Netherlands
Distribution network congestion and land scarcity accelerate floating PV adoption on IJsselmeer and sand extraction lakes. ENTSO-E grid code harmonization enables virtual power plant aggregation. The Randstad urban corridor dominates building-integrated facade deployments.
Europe Solar Photovoltaic (PV) Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with utility-scale development pipelines. Tier-one module suppliers and European utility incumbents divide procurement influence across distinct customer segments. Strategic archetypes include pipeline aggregators anchoring long-term offtake, manufacturing-scale cost leaders, and distributed generation financiers. Capacity expansion and corporate PPA origination represent the dominant competitive moves.
Among utility-scale developers, Iberdrola, S.A. occupies a position exemplifying pipeline-anchored PPA strategies across Southern Europe. JinkoSolar Holding Co., Ltd. represents manufacturing-scale archetypes competing on monocrystalline module supply. TotalEnergies sits within integrated energy major positioning, capturing distributed generation through financing structures.
| Leading Market Players |
|---|
| Lightsource BP Renewable Energy Investments Limited |
| Hanwha Q CELLS Technology Co., Ltd |
| SunPower Corporation |
| Iberdrola, S.A |
| JinkoSolar Holding Co., Ltd |
| First Solar, Inc. |
| E.ON SE |
| TotalEnergies |
| ENGIE Group |
| Others |
Supply & Pricing Matrix
Polysilicon ingot costs originating from Xinjiang feedstock cascade through module assembly tiers, compressing margins for European distributors while bifacial premium formats sustain price separation from standard monocrystalline offerings.
Pricing Analysis
Cost-down pressure on residential rooftop systems accelerates because Italian Superbonus incentive phase-outs squeeze installer markups. Three-tier pricing structure across premium, standard, and economy levels stratifies by module efficiency grade and CE marking tier. Price differentiation hinges on volume scale for utility-scale offtakers versus soft-cost premiums for distributed commercial buyers. Commercial and industrial aggregators exhibit highest price sensitivity; utility developers with corporate PPA cover display lowest.
Supply Chain Analysis
Dual-sourcing mandates from European EPC contractors require qualification of Southeast Asian and domestic module suppliers to mitigate Xinjiang-origin concentration risks. Polysilicon feedstock draws from China, Malaysia, and Germany; glass and aluminum framing rest on Chinese and Turkish manufacturing. Single-source vulnerability persists for high-purity silicon metal. Distribution runs through Rotterdam and Hamburg port hubs into regional logistics networks serving German and Spanish project clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysilicon purification capacity constraints in non-Chinese jurisdictions prop module pricing premiums, creating supply-constrained dynamics through the analysis window.
For Market Incumbents: Cement pipeline-anchored PPA positions across Southern European merchant markets to lock in offtake visibility. Secure backward integration into energy storage manufacturing to capture hybrid system bundling premiums. Defend against emerging Chinese module suppliers by accelerating CE marking and EU AI Act cybersecurity certification for smart inverter portfolios.
For New Entrants and Emerging Players: Enter via agrivoltaic dual-use frameworks in France and Italy where land-access barriers filter incumbent competition. Target floating PV installations in Portuguese reservoirs and Greek lignite pit lakes as penetrable whitespace. Pursue direct procurement platform aggregation for German Mittelstand rooftop demand as the primary go-to-market angle.
For Investors and Strategic Acquirers: Grid saturation resolution in southern Spain and Italy is the leading indicator that project energization timelines will compress and developer IRRs will expand. Long-term viability centers on utility-scale pipeline aggregators with interconnection queue positions and corporate PPA origination capabilities. Monitor ENTSO-E grid code harmonization implementation as the signal for virtual power plant aggregation scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Corporate PPA Origination | Basque Country manufacturers anchor long-term baseload contracts with Iberian developers. |
| Agrivoltaic Project Development | Provence dual-use tariffs unlock agricultural land without sacrificing crop yields. |
| Smart Inverter Certification | EU AI Act cybersecurity mandates create compliance moats above 50kW threshold. |
| Floating PV Deployment | Alqueva reservoir installations exploit minimal land conflict and evaporative cooling. |
| Virtual Power Plant Aggregation | ENTSO-E harmonized codes enable German Mittelstand rooftop pooling into grid services. |
Research Methodology
Document review covered IEA renewable deployment databases, ENTSO-E grid development plans, and EU regulatory filings, complemented by interviews with utility-scale project developers, EPC contractors, grid operators, and module procurement leads. Secondary validation drew from REPowerEU implementation tracking, national permitting authority disclosures, and corporate PPA registries. Bottom-up capacity installation modeling and top-down policy target reconciliation provided cross-verification.
Historical deployment trajectories were cross-referenced against panel input from industry stakeholders to construct the analytical framework. Segmentation dimensions spanned module technology type, system architecture, end-user scale, and installation format across the projection horizon. CAGRs were derived from capacity deployment curves and revenue-per-watt compression trends. Forecast inputs incorporated interconnection queue depths and permitting timeline assumptions by member state.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REPowerEU permitting acceleration delays or F-Gas Regulation enforcement shifts. Deviation in polysilicon supply chain restructuring away from Xinjiang-origin feedstock would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Distributed Solar Power Generation System Market