
 Indonesia Solar Energy Market | 2026-2036
Indonesia Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Solar Energy Market Outlook
Skilled EPC labor availability is rotating from a bottleneck into a growth enabler as vocational institutes in Surabaya and Bandung expand solar technician certification. Canadian Solar Inc. leverages its module supply agreements to anchor utility-scale projects across the archipelago. Trina Solar Co. Ltd. competes through bifacial panel specialization suited to Indonesia's high humidity and diffuse irradiance conditions. ACWA Power Indonesia dominates the independent power producer segment through long-term offtake contracts with PLN.
Indonesia solar energy encompasses photovoltaic systems that convert solar irradiance into direct current electricity through semiconductor junctions, typically operating at 15-22% conversion efficiency for crystalline silicon modules deployed in tropical climates. These installations primarily serve grid-connected generation and distributed commercial-industrial supply, reducing diesel dependency across the 17,000-island nation. Crystalline silicon technology leads installed capacity due to proven bankability and local supply chain familiarity, while bifacial modules represent the fastest-growing technology segment as developers exploit reflected irradiance from water bodies and light-colored ground surfaces. Rooftop installation dominates the commercial end-user category where C&I offtakers seek tariff arbitrage against rising PLN electricity rates.
PLN's RUPTL procurement framework, MEMR ministerial regulations on renewable energy pricing, and BSN SNI standards for module safety and grid interconnection collectively shape project economics and equipment eligibility. These regulations enforce local content requirements that steer developer procurement toward domestically assembled components, directly influencing supply chain configuration and vendor selection criteria. Stakeholders must monitor RUPTL auction schedules and domestic content threshold adjustments to align procurement timelines with regulatory compliance windows.
Market Dynamics
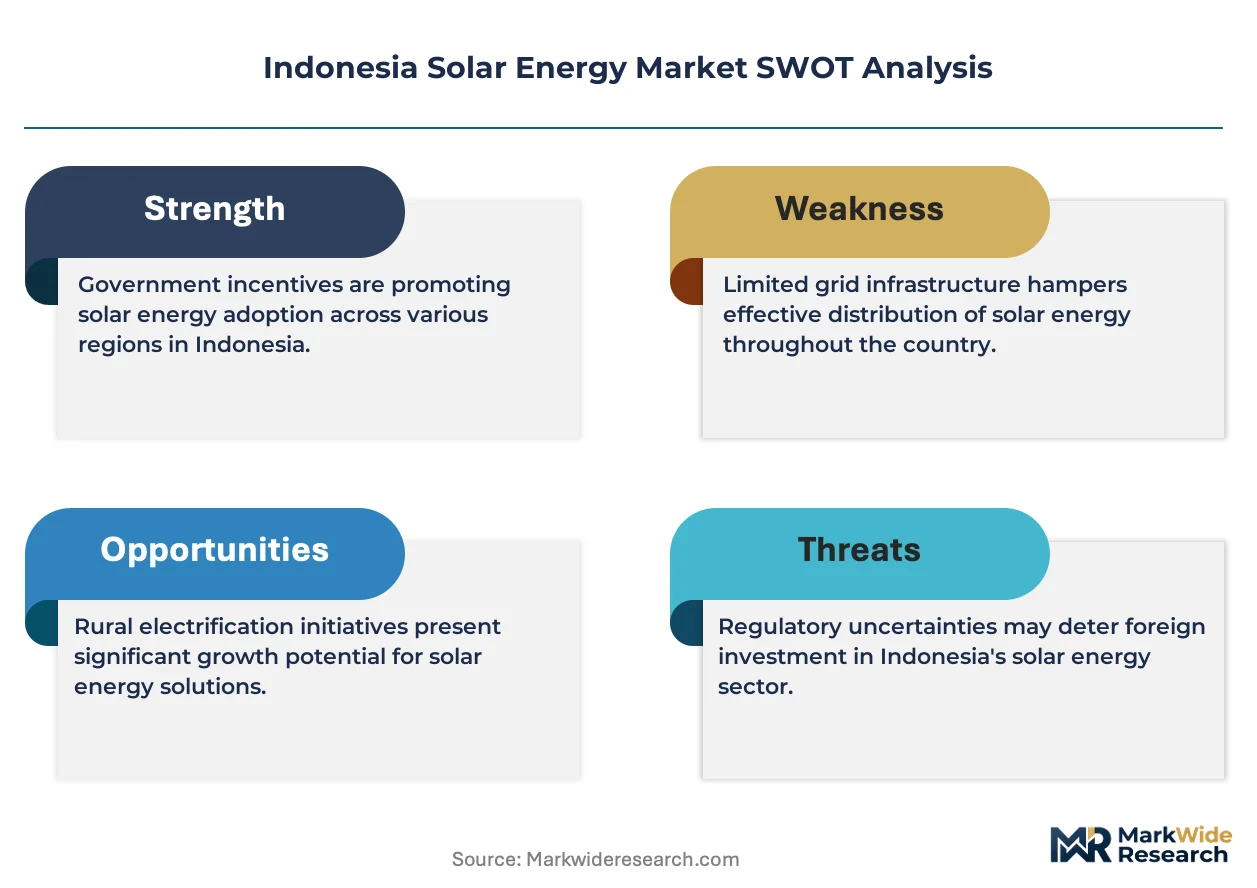
PLN's RUPTL procurement framework is compressing project development timelines while bifacial module technology unlocks higher yields across Indonesia's humid archipelago conditions, creating a dual-force restructuring of developer economics.
Growth Catalysts
- RUPTL Auction Schedules:PLN's five-year electricity procurement roadmap mandates renewable capacity additions, creating predictable offtake pipelines for independent power producers and utility-scale developers.
- Java-Bali Grid Interconnection:Concentrated transmission infrastructure and land availability in this corridor concentrates developer activity where PLN can absorb large-scale solar injection.
- Bifacial Module Performance:Reflected irradiance capture from water bodies and light-colored surfaces boosts effective capacity factors, improving project returns without expanding physical footprint.
Market Restraints
- Polysilicon Price Volatility:Crystalline silicon module costs remain exposed to upstream polysilicon supply concentration in China, compressing developer margins during input price spikes.
- Domestic Content Thresholds:MEMR regulations enforce local assembly requirements that outpace Indonesia's current manufacturing base, creating procurement bottlenecks for compliant equipment.
- Diesel Subsidy Persistence:Off-grid generation in outer islands retains artificial cost advantages from subsidized fossil fuel pricing, delaying solar substitution in remote demand pockets.
Strategic Opportunities
- Sumatra and Sulawesi Penetration:These islands hold substantial unmet electricity demand with weaker grid infrastructure, creating first-mover advantages for hybrid solar-storage configurations.
- Corporate PPA Structures:Direct power purchase agreements with C&I offtakers bypass PLN tariff constraints, opening bilateral contracting models for commercial rooftop and floating solar.
- Floating PV Technology Convergence:Integration of bifacial modules with floating platforms exploits Indonesia's reservoir and coastal geography while reducing land-use conflicts.
Industry Challenges
- Certification Timeline Compression:BSN SNI standards for module safety and grid interconnection require extended testing protocols that misalign with RUPTL auction deadlines.
- EPC Labor Scaling:Vocational certification expansion in Surabaya and Bandung must accelerate to match construction velocity demanded by concurrent utility-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Solar Energy Market |
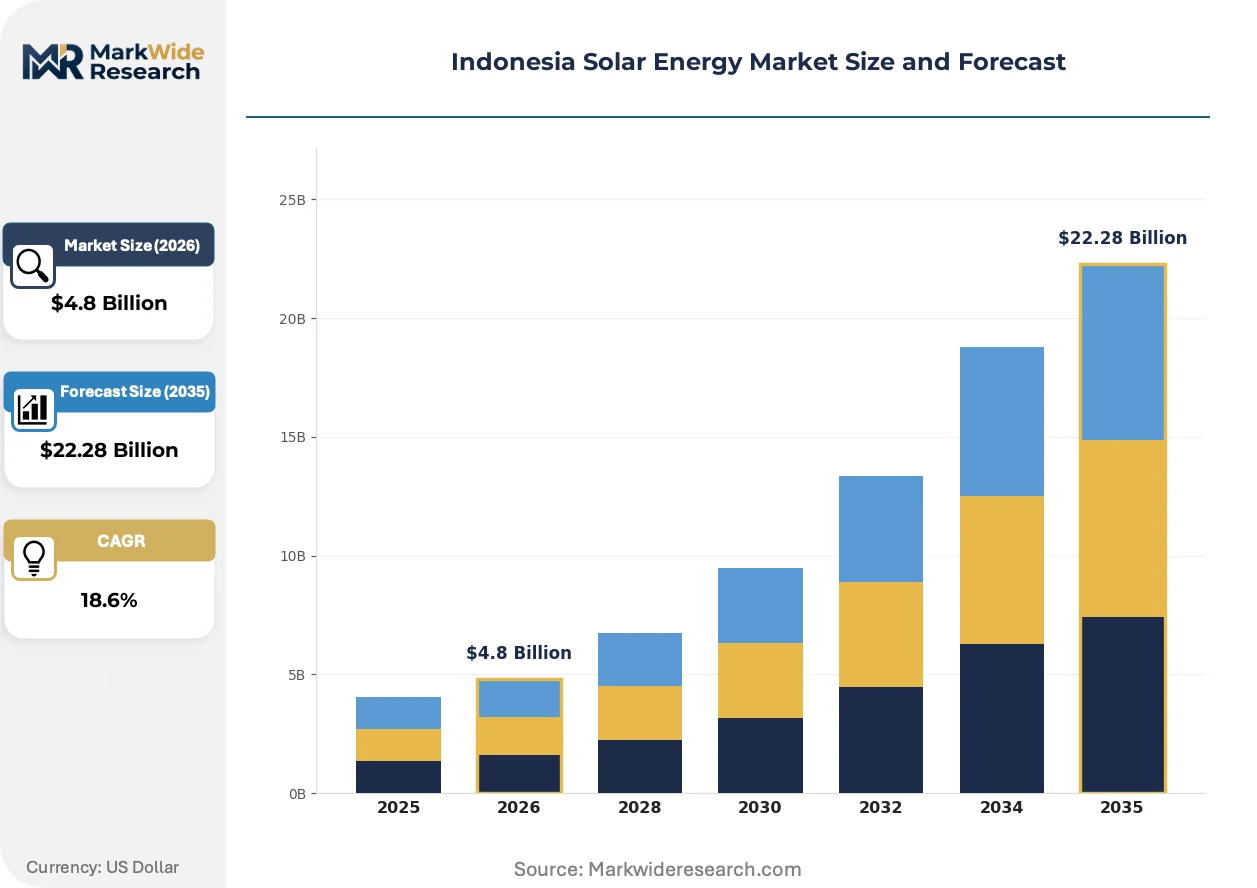
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Batteries, Mounting Structures Technology: Thin-Film, Crystalline Silicon, Bifacial, Concentrated Solar Power End User: Residential, Commercial, Industrial, Utility Installation: Rooftop, Ground-Mounted, Off-Grid, Hybrid Systems |
| Companies Covered | PT Sumber Energi Sukses Makmur, PT Solardex Energy Indonesia, Canadian Solar Inc., PT Surya Utama Nuansa, PT Sumber Energi Surya Nusantara, Trina Solar Co. Ltd., ACWA Power Indonesia, PT Xurya Daya Indonesia, SUN Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Solar Energy Market Strategic Shifts
Bifacial module architecture is restructuring technology preferences across Indonesia's solar pipeline, while regulatory enforcement of domestic content rules and evolving procurement modalities are compressing traditional development playbooks.
Monofacial crystalline silicon modules dominated Indonesia's early installations due to supply chain familiarity and bankability. Utility-scale developers and IPPs now specify bifacial glass-glass constructions for new RUPTL projects, exploiting reflected irradiance from reservoirs and agricultural surfaces. This technology is supplanting monofacial specifications in PLN auction requirements, forcing procurement teams to requalify supplier bases and EPC contractors to adapt mounting system designs.
MEMR ministerial regulations on renewable energy pricing now embed escalating domestic content thresholds that ratchet higher through the forecast window. These rules disqualify fully imported module assemblies, steering developer procurement toward domestically assembled components. IPPs and EPCs are responding by pre-qualifying local assembly partners and adjusting project cost structures to absorb compliance premiums.
Direct corporate power purchase agreements are fragmenting the traditional PLN-centric offtake model. C&I buyers in manufacturing and data center verticals now seek bilateral contracts that bypass regulated tariff structures, particularly in Batam and Jakarta industrial zones. This modality is most visible among multinational subsidiaries with renewable energy procurement mandates from parent entities.
Indonesia Solar Energy Market Segmentation
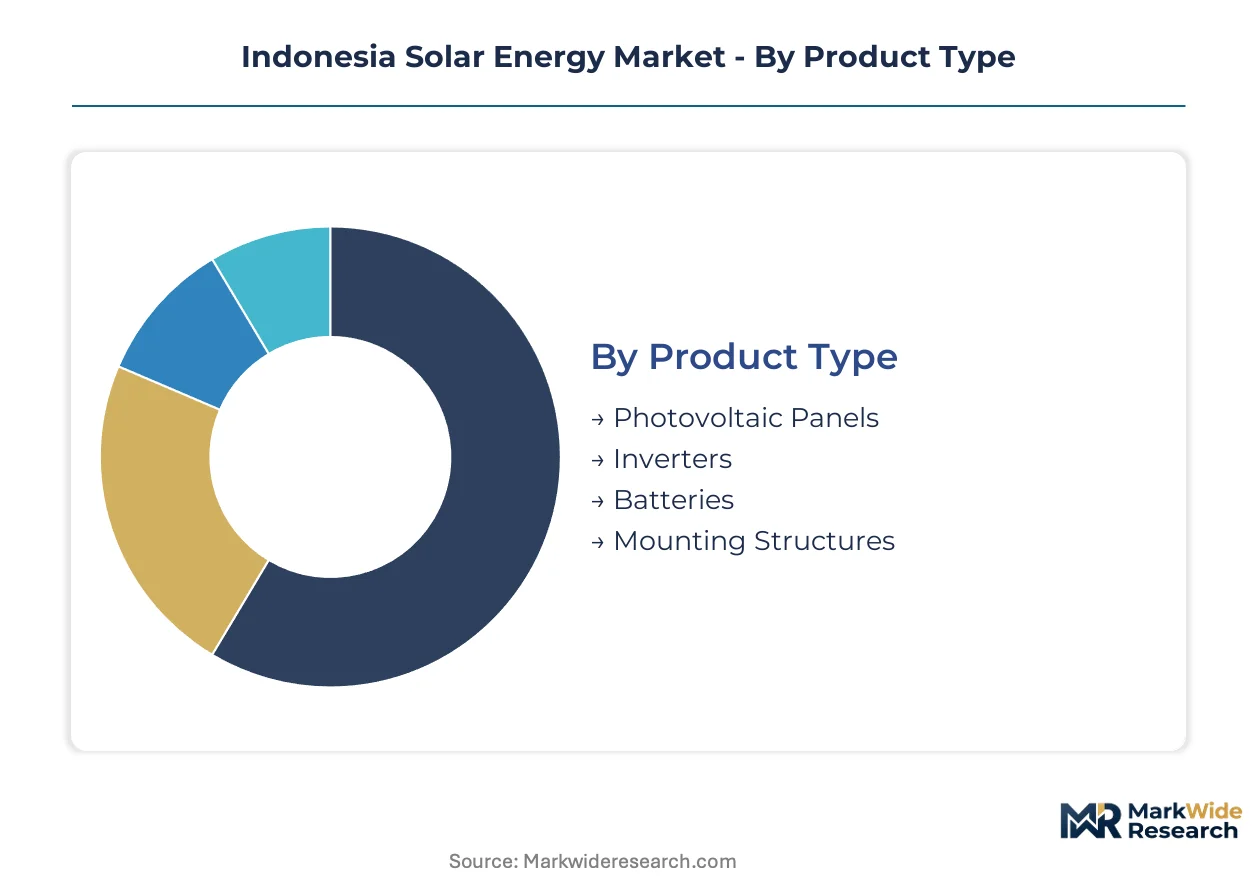
Segmentation reveals how PLN's procurement priorities and Indonesia's archipelago geography distribute revenue across equipment categories and installation modalities. Developers configure project economics differently across these dimensions to align with MEMR regulations and RUPTL auction requirements.
Product Type:
Margin pools concentrate in power electronics and storage systems where import dependency and technical complexity sustain pricing premiums above commodity panel assemblies.
- Photovoltaic Panels:Crystalline silicon modules dominate procurement volumes, with bifacial glass-glass constructions commanding preference in RUPTL auctions due to reflected irradiance capture from reservoirs and agricultural surfaces. Java-Bali utility-scale projects absorb the largest share of panel shipments where PLN interconnection capacity permits multi-hundred-megawatt injections.
- Inverters:String and central inverter architectures convert DC generation to grid-compliant AC output, with utility-scale developers specifying 1500V systems to reduce BOS costs. MEMR local content thresholds push procurement toward domestically assembled units, compressing margins for fully imported equipment.
- Batteries:Lithium-ion storage systems enable solar-plus-storage configurations in Sumatra and Sulawesi where grid stability constraints limit direct solar penetration.
- Mounting Structures:Fixed-tilt and tracking systems anchor modules to ground or rooftop substrates, with floating platform variants gaining traction for reservoir installations.
The dominant share belongs to Photovoltaic Panels, while Batteries is closing the gap fastest as hybrid solar-storage configurations proliferate in outer islands.
Technology:
Technology selection determines capacity factors and project returns across Indonesia's humid tropical conditions with high diffuse irradiance and frequent cloud cover.
- Crystalline Silicon:Monocrystalline and polycrystalline cell architectures deliver 18-22% conversion efficiency in standard test conditions, with proven bankability attracting project finance from domestic and regional lenders. This technology anchors PLN's RUPTL procurement specifications and dominates installed capacity across Java-Bali corridors.
- Bifacial:Dual-sided module construction captures reflected irradiance from water bodies and light-colored ground surfaces, boosting effective yields. Floating PV developers in West Java reservoirs and Batam coastal zones specify bifacial glass-glass constructions to maximize energy density per hectare.
- Thin-Film:Cadmium telluride and copper indium gallium selenide technologies offer superior temperature coefficients for tropical deployment, though limited local supply chain familiarity constrains adoption.
- Concentrated Solar Power:Parabolic trough and tower configurations with thermal storage suit dispatchable generation requirements, but high capital intensity and water consumption limits deployment to demonstration projects.
Crystalline Silicon retains the largest installed base, though Bifacial is expanding most quickly as developers requalify supplier bases for new RUPTL tenders.
End User:
Customer type shapes offtake structure, with utility-scale and corporate direct contracts offering distinct margin profiles compared to fragmented residential sales.
- Utility:PLN and independent power producers procure multi-megawatt installations under RUPTL auction frameworks, with long-term power purchase agreements providing revenue certainty. These projects concentrate in Java-Bali where transmission infrastructure absorbs large-scale injection.
- Industrial:Manufacturing facilities and data centers in Batam and Jakarta industrial zones seek bilateral corporate PPAs to bypass regulated tariffs and meet renewable energy procurement mandates from parent entities.
- Commercial:Office buildings, retail centers, and hospitality operators deploy rooftop systems for tariff arbitrage against rising PLN electricity rates.
- Residential:Single-family and multi-unit dwellings adopt small-scale rooftop installations, constrained by limited net metering incentives and financing availability.
Utility commands the greatest procurement volume, while Industrial is gaining share fastest as direct corporate contracting fragments the traditional PLN-centric offtake model.
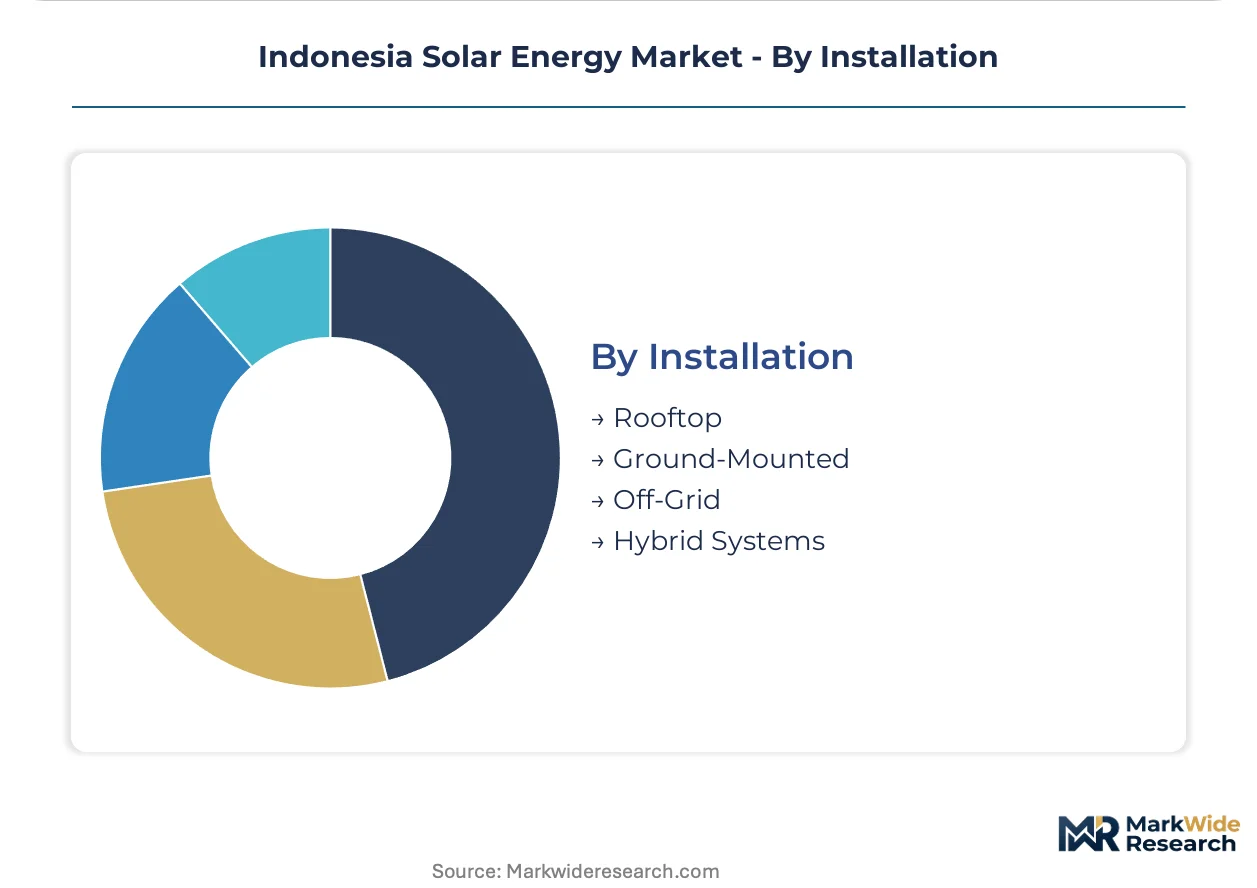
Installation:
Installation modality determines land-use conflicts, grid interconnection requirements, and project development timelines across Indonesia's fragmented geography.
- Rooftop:Building-integrated and building-applied systems dominate commercial-industrial deployment in urban centers where land scarcity precludes ground-mounted alternatives. Jakarta and Surabaya manufacturing zones show highest concentration of C&I rooftop adoption.
- Ground-Mounted:Utility-scale fixed-tilt and tracking installations occupy agricultural and degraded land in East Java and West Java, where PLN transmission capacity supports large-scale solar injection.
- Floating PV:Reservoir and coastal platforms reduce land-use conflicts while exploiting bifacial module performance from water surface reflectance. Cirata Reservoir and Batam coastal projects demonstrate commercial viability.
- Off-Grid:Stand-alone systems serve outer islands where PLN grid extension remains uneconomic, competing against subsidized diesel generation.
- Hybrid Systems:Solar-plus-storage and solar-diesel configurations address grid stability constraints in Sumatra and Sulawesi, enabling higher renewable penetration in weak grid zones.
Ground-Mounted retains the dominant deployment share, though Floating PV is climbing the fastest as developers exploit Indonesia's reservoir geography and reduce land acquisition friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java-Bali commands premium project valuations while Sumatra and Sulawesi trade at discount rates reflecting grid infrastructure gaps. This pricing-power asymmetry concentrates developer capital in the western corridor while leaving eastern islands dependent on hybrid configurations.
Java-Bali
PLN's transmission backbone and land availability in East Java and West Java absorb multi-hundred-megawatt solar injections. MEMR ministerial regulations on renewable energy pricing enforce domestic content thresholds that steer procurement toward locally assembled modules. The Cirata Reservoir floating PV installation demonstrates commercial viability for bifacial glass-glass constructions exploiting water surface reflectance.
Sumatra
Unmet electricity demand in North Sumatra and Riau provinces creates first-mover openings for solar-plus-storage developers. PLN's RUPTL procurement framework extends auction eligibility to hybrid configurations addressing grid stability constraints. The Medan industrial corridor hosts early corporate PPA negotiations between manufacturing facilities and independent power producers.
Sulawesi
Weak grid infrastructure in South Sulawesi and Central Sulawesi limits direct solar penetration without co-located lithium-ion storage. MEMR regulations on renewable energy pricing provide tariff benchmarks for off-grid and hybrid system economics. The Makassar manufacturing zone attracts bilateral power purchase agreement discussions with C&I offtakers seeking tariff arbitrage.
Batam
Free trade zone status and data center concentration in this Riau Islands cluster drive demand for direct corporate contracting bypassing PLN tariffs. BSN SNI standards for module safety and grid interconnection apply with modified compliance timelines reflecting special economic zone administration. The Batam industrial park hosts multinational subsidiaries with renewable energy procurement mandates from parent entities.
Kalimantan
Degraded land availability and new capital city development in East Kalimantan create utility-scale project pipelines outside Java-Bali saturation. PLN's RUPTL procurement framework designates this corridor for priority renewable capacity additions through 2030. The Nusantara capital zone attracts floating PV feasibility studies exploiting reservoir geography while reducing land-use conflicts.
Indonesia Solar Energy Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Indonesia's solar value chain. Module suppliers with bifacial specialization command premium positioning in RUPTL auctions, while domestic assemblers capture compliance rents from escalating local content thresholds. The market structures around three strategic archetypes: international module manufacturers anchoring utility-scale supply, regional IPPs securing long-term PLN offtake, and domestic EPC contractors scaling vocational-certified labor pools. Dominant competitive moves center on pre-qualifying local assembly partnerships and accelerating SNI certification timelines to align with auction deadlines.
Within the international module supplier tier, Canadian Solar Inc. and Trina Solar Co. Ltd. occupy positions shaped by their respective supply agreement structures and technology specializations. Canadian Solar leverages module supply agreements to anchor utility-scale project participation, while Trina Solar competes through bifacial panel configurations suited to Indonesia's humid tropical conditions. ACWA Power Indonesia sits within the independent power producer archetype, securing long-term offtake contracts with PLN that provide revenue certainty across multi-year development horizons. These three entities exemplify how geographic origin and corporate structure map to distinct competitive positioning within MEMR's regulatory framework.
| Leading Market Players |
|---|
| PT Sumber Energi Sukses Makmur |
| PT Solardex Energy Indonesia |
| Canadian Solar Inc. |
| PT Surya Utama Nuansa |
| PT Sumber Energi Surya Nusantara |
| Trina Solar Co. Ltd. |
| ACWA Power Indonesia |
| PT Xurya Daya Indonesia |
| SUN Energy |
| Others |
Value Chain & Pricing Dynamics
BSN SNI certification requirements for module safety and grid interconnection gate both supplier qualification and price differentiation simultaneously, creating compliance premiums for certified equipment while compressing margins for non-compliant imports. Developers absorb these cost differentials through project economics adjustments or pass them to offtakers via tariff structures.
Pricing Analysis
Configured-to-order pricing for bifacial glass-glass modules commands substantial premiums over standard monofacial crystalline silicon units. Project-based contract structures dominate utility-scale procurement under RUPTL auctions, with price differentiation driven by certification tier and volume scale. Cost compression in standard-tier equipment is intensifying because polysilicon input volatility feeds through module assembly costs. Industrial C&I offtakers in Batam and Jakarta zones exhibit highest price sensitivity, while utility IPPs prioritize performance guarantees over unit economics.
Supply Chain Analysis
China and Vietnam anchor polysilicon refining and cell manufacturing, with Indonesia's domestic assembly capacity expanding to meet MEMR local content thresholds. Indonesia's solar pipeline draws from imported wafers, domestic module assembly, and regional inverter sourcing. Single-source vulnerability concentrates in upstream polysilicon where Chinese supply concentration creates exposure to trade policy shifts. Distribution runs through PLN procurement channels for utility-scale projects and direct EPC contracting for commercial rooftop installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward PLN and consolidated industrial offtakers as RUPTL auction aggregation and corporate PPA standardization reduce fragmentation among demand-side participants.
For Market Incumbents: Secure long-term polysilicon supply agreements to buffer margin compression from input price volatility. Anchor utility-scale market share by accelerating SNI certification timelines to align with compressed RUPTL auction deadlines. Vertical integration into domestic module assembly captures compliance rents from escalating MEMR local content thresholds. For New Entrants and Emerging Players: Differentiate on floating PV technology integration for reservoir and coastal deployments where land-use friction creates first-mover openings. Target Sumatra and Sulawesi hybrid solar-storage configurations where grid stability constraints limit incumbent penetration. Pursue direct corporate PPA origination with multinational manufacturing subsidiaries in Batam free trade zone. For Investors and Strategic Acquirers: MEMR domestic content threshold escalations through the forecast window reshape the acquisition landscape toward local assembly assets and certified EPC capabilities. Five-to-ten-year viability favors vertically integrated developers with captive supply chains and PLN offtake relationships. Monitor RUPTL auction schedule density as inflection indicator for construction velocity and equipment demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Module Assembly Partnership | MEMR local content compliance unlocks RUPTL auction eligibility for developers. |
| Floating PV Technology Licensing | Reservoir installations exploit bifacial performance while reducing land acquisition costs. |
| Corporate PPA Origination | Bilateral contracting with C&I offtakers bypasses PLN tariff constraints in industrial zones. |
| Solar-Plus-Storage Integration | Hybrid configurations address grid stability limits in Sumatra and Sulawesi corridors. |
| Vocational Certification Program | Surabaya and Bandung technician pipelines match EPC labor demands from concurrent deployments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from MEMR regulatory filings, PLN RUPTL procurement schedules, BSN SNI standards documentation, and project development databases. Bottom-up capacity aggregation and top-down demand forecasting were triangulated to reconcile supply-side construction pipelines with offtake absorption rates.
Across the projection horizon, the analytical framework modeled capacity additions by technology type, installation modality, and regional grid infrastructure tier. CAGRs were derived from regression analysis of historical auction awards and announced project pipelines, incorporating polysilicon price elasticity and domestic content compliance cost curves as industry-specific forecast inputs.
Material uncertainties — polysilicon supply disruptions, MEMR local content threshold adjustments, and PLN interconnection capacity allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and auction schedule adherence. Recalibration cycles align with material shifts in RUPTL procurement velocity and upstream input cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Smart Solar Solutions Market