
 Photovoltaic Mounting System Market | 2026-2036
Photovoltaic Mounting System Market Size, Share, and Industry Trends Forecast 2026-2036
Photovoltaic Mounting System Market Analytics
The EU Green Deal is realigning cost-of-entry calculus for mounting system suppliers entering European utility tenders. Nextracker Inc. leverages its tracker software and steel supply chain to sustain pricing power across Americas utility-scale deployments. Array Technologies Inc. anchors its competitive stance through domestic manufacturing scale and project finance relationships. GameChange Solar differentiates via rapid-install racking designs that reduce labor hours on large ground-mount sites.
Photovoltaic mounting systems are structural assemblies that secure solar modules to rooftops, terrain, or floating platforms, typically fabricated from extruded aluminum sections, galvanized steel purlins, or reinforced polymer bases engineered for wind loads and seismic ratings. Their primary function is to maintain optimal tilt angles, drainage clearance, and mechanical integrity across decades of environmental exposure. Fixed tilt racking dominates utility-scale economics in high-irradiance flat terrain where simplicity minimizes operations expenditure. Solar tracker installations command premium pricing but capture incremental energy yield that justifies structural complexity in competitive power purchase agreement markets. Roof mount systems occupy denser margin pools across European and Japanese residential segments where permitting constraints and aesthetic requirements elevate aluminum and integrated BIPV solutions.
REACH compliance in Europe and GB standards enforcement in China are elevating material traceability and corrosion testing requirements for aluminum and steel components. The EU AI Act and emerging US FERC interconnection rules are reshaping how tracker control systems integrate with grid dispatch and cybersecurity protocols. Stakeholders must monitor whether national content requirements in India, Brazil, and Saudi Arabia fragment procurement strategies or incentivize localized extrusion and galvanizing capacity.
Market Dynamics
Steel and aluminum supply concentration across Chinese and Indian smelters is compressing margin buffers for mounting system fabricators while tracker software complexity is fragmenting vendor tiers between integrated controls providers and hardware-only suppliers.
Growth Catalysts
- Utility-scale solar parks:India's national solar mission mandates gigawatt-scale installations requiring specialized fixed-tilt and single-axis tracking infrastructure across Rajasthan and Gujarat states.
- EU Green Deal certification tightening:REACH compliance and CE marking for structural aluminum are accelerating replacement cycles among European commercial rooftop installers.
- Floating PV platforms:Reservoir-based solar installations across Japan and South Korea are creating demand for corrosion-resistant polymer and stainless-steel anchoring systems.
Market Restraints
- Galvanized steel price volatility:Hot-rolled coil input costs swing with Chinese export quotas and energy-intensive production curbs, destabilizing project quoting.
- Extrusion supply concentration:Premium aluminum profile capacity clusters in Zhejiang and Guangdong provinces, exposing procurement to regional logistics disruptions.
- Interconnection queue delays:US FERC Order 2023 implementation gaps extend project commissioning timelines, freezing capital deployment on tracker-equipped sites.
Strategic Opportunities
- Brazil distributed generation:Net metering expansion and import tariff phase-downs open residential and commercial rooftop segments for lightweight aluminum racking.
- Agrivoltaic convergence:Dual-use land frameworks in France and Germany permit elevated tracker structures that preserve agricultural output beneath panel arrays.
- Saudi Arabia localization:National content requirements under Vision 2030 incentivize domestic steel galvanizing and aluminum extrusion partnerships for gigaproject supply.
Industry Challenges
- Electromechanical technician scarcity:Solar tracker installation and commissioning requires skilled labor pools that remain thin across US Southwest and Australian remote sites.
- Multi-standard certification burden:IEC 62817 tracker durability testing, ASCE 7 wind load compliance, and country-specific seismic codes extend product validation cycles.
- Cybersecurity integration complexity:EU AI Act and emerging grid dispatch protocols demand encrypted control architectures that legacy tracker fleets cannot retrofit economically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photovoltaic Mounting System Market |
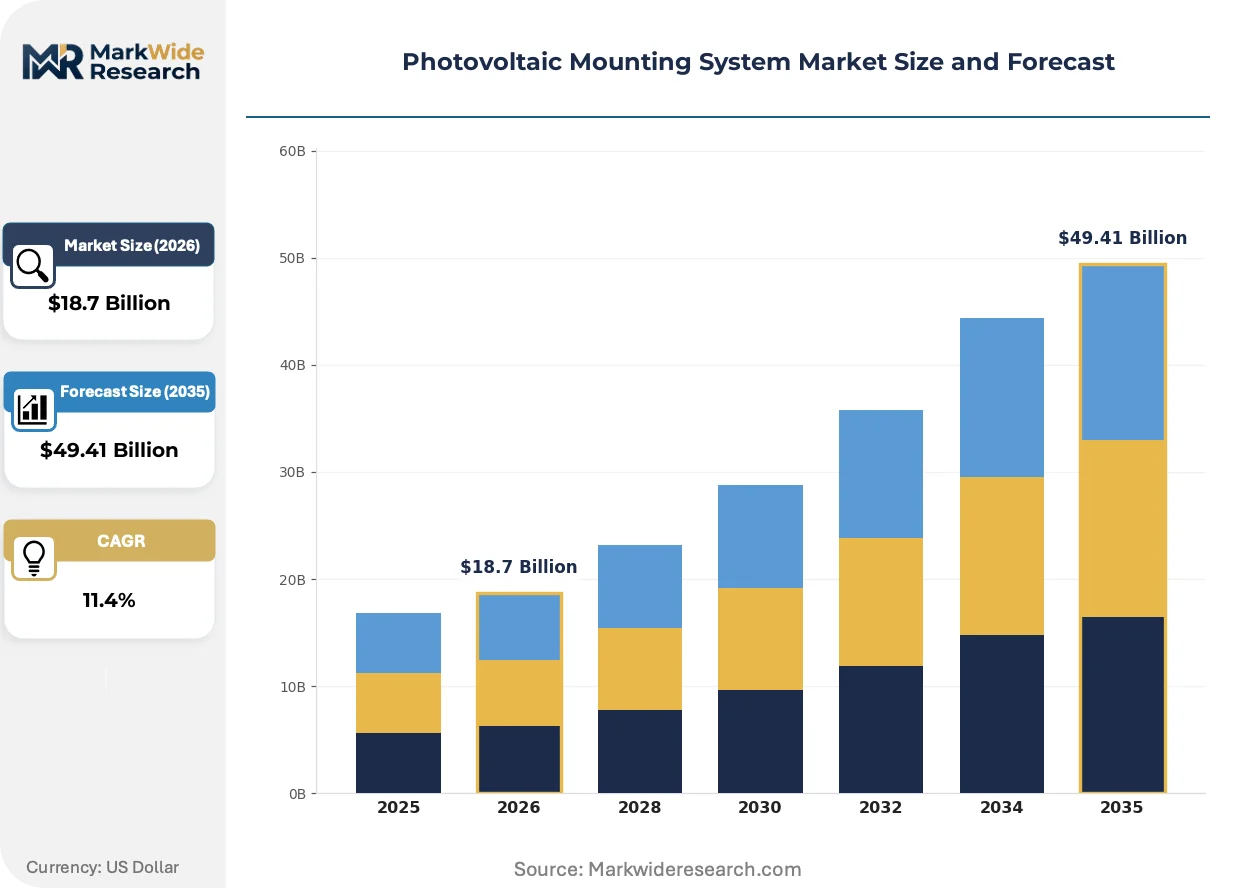
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Tilt, Adjustable Tilt, Solar Tracker, Roof Mount Installation Type: Ground-mounted, Roof-mounted, BIPV, Floating Material: Aluminum, Steel, Plastic, Concrete End User: Residential, Commercial, Industrial, Utility |
| Companies Covered | Nextracker Inc., Array Technologies Inc., GameChange Solar, Arctech Solar Holding Co., Ltd., Soltec Power Holdings, PVHardware, Unirac Inc., Schletter, K2 Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photovoltaic Mounting System Market Evolving Landscape
Tracker control architectures are converging with grid-edge intelligence while material science advances reduce structural mass without compromising wind ratings.
Machine-learning-driven tracker algorithms are unifying row-level optimization with substation dispatch signals. US utility-scale developers are deploying these systems across Texas and California ISO territories. This convergence is compressing vendor differentiation toward software performance rather than mechanical hardware specifications.
EU AI Act classification of autonomous tracker control systems as high-risk AI is mandating human-in-the-loop override capabilities and algorithmic transparency documentation. European mounting suppliers are re-engineering firmware architectures to satisfy conformity assessment requirements. The compliance burden falls heaviest on mid-scale tracker vendors lacking dedicated regulatory affairs functions.
Engineering-procurement-construction contractors are consolidating vendor relationships around full-package suppliers who deliver steel, aluminum, controls, and installation labor under single-contract structures. This consolidation displaces fragmented procurement of racking hardware from separate extruders and galvanizers. The shift is most visible across Indian and Brazilian utility-scale tenders where EPCs assume full performance risk.
Photovoltaic Mounting System Market Segmentation
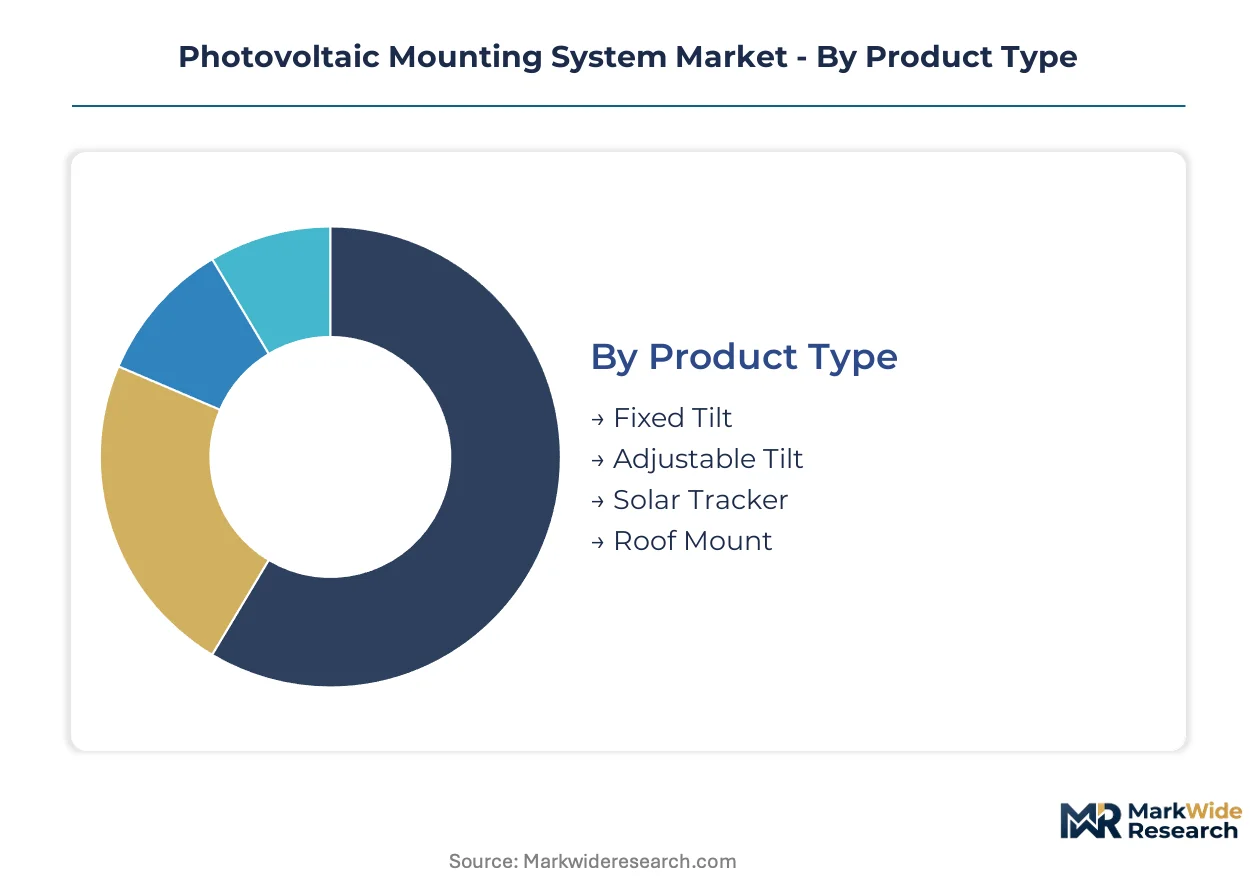
Mounting system procurement diverges sharply across installation environments, with material selection and structural configuration directly tied to project scale, terrain constraints, and regulatory load requirements. Understanding these segment boundaries clarifies where fabrication capacity concentrates and where margin pools shift.
Product Type:
Supply concentration for tracker control systems and precision steel fabrication shapes competitive tiers across product categories.
- Solar Tracker:Single-axis and dual-axis assemblies incorporate electromechanical drive systems, wind sensors, and row-level optimization software. Demand clusters in Texas and California ISO territories where energy yield premiums justify structural complexity and higher capital expenditure.
- Fixed Tilt:Stationary racking maintains constant azimuth and elevation angles through extruded aluminum rails or galvanized steel purlins. Rajasthan and Gujarat solar parks in India specify these systems for gigawatt-scale deployment where simplicity minimizes lifetime operations expenditure.
- Adjustable Tilt:Seasonally variable angle mechanisms suit high-latitude installations across Germany and Japan where solar elevation shifts significantly.
- Roof Mount:Ballasted or penetrating attachments secure modules to residential and commercial structures, with aluminum and composite solutions dominating European aesthetic-sensitive segments.
Fixed Tilt absorbs the bulk of installed capacity; Solar Tracker is expanding most quickly.
Installation Type:
Application environment dictates corrosion specifications, foundation engineering, and labor deployment models.
- Ground-mounted:Terrain-based installations deploy driven piles, concrete ballasts, or screw anchors across flat and graded sites. Utility-scale developers in Brazil and Saudi Arabia specify these systems for gigaproject execution under engineering-procurement-construction contracts.
- Floating:Reservoir and coastal platforms employ high-density polyethylene pontoons with stainless-steel mooring systems. Japan and South Korea mandate these configurations where land scarcity and agricultural protection priorities constrain ground-based development.
- Roof-mounted:Elevated attachments to commercial and industrial buildings concentrate in European net-zero retrofit programs and Brazilian distributed generation expansion.
- BIPV:Building-integrated photovoltaic systems embed cells within facade and skylight assemblies, with demand anchored in German and French commercial construction codes.
Ground-mounted retains dominant volume share; Floating gains share fastest.
Material:
Raw material sourcing geography and processing energy intensity determine landed cost structures and carbon footprint credentials.
- Steel:Hot-rolled coil and galvanized structural sections provide high load-bearing capacity for tracker torque tubes and fixed-tilt purlins. Chinese and Indian smelter concentration exposes procurement to export quota volatility and energy-intensive production curbs.
- Aluminum:Extruded 6000-series profiles deliver corrosion resistance and lightweight handling for rooftop and residential segments. Zhejiang and Guangdong province capacity clusters create regional logistics vulnerability for European and North American fabricators.
- Plastic:Glass-reinforced polymer and high-density polyethylene components serve floating platform buoyancy and residential ballast applications.
- Concrete:Precast ballast blocks and foundation piers anchor ground-mounted arrays in high-wind zones and seismic-rated jurisdictions.
Steel commands the greatest tonnage throughput; Aluminum climbs the fastest on weight-reduction and corrosion performance.
End User:
Customer scale determines procurement sophistication, performance risk allocation, and vendor relationship structures.
- Utility:Gigawatt-scale developers deploy single-axis trackers and fixed-tilt arrays under long-term power purchase agreements. Indian national solar mission tenders and Saudi Vision 2030 gigaprojects concentrate demand for integrated steel, controls, and installation packages.
- Residential:Distributed rooftop installations across Europe, Japan, and Brazil specify lightweight aluminum racking with rapid-permitting documentation. Net metering policy shifts and import tariff phase-downs are restructuring procurement economics.
- Commercial:Corporate offtake agreements and building retrofit programs in Germany and France drive demand for aesthetic-integrated and BIPV-compatible solutions.
- Industrial:On-site generation for manufacturing facilities combines ground-mounted and rooftop configurations with behind-the-meter storage integration.
Utility captures dominant project volume; Residential shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates utility-scale procurement through national solar mission tenders, while the United States and Saudi Arabia anchor gigaproject development through distinct regulatory and financing frameworks. China supplies the majority of upstream aluminum and steel inputs, creating geographic asymmetry between manufacturing and deployment.
India
Rajasthan and Gujarat states host gigawatt-scale solar parks requiring specialized fixed-tilt and single-axis tracking infrastructure under the national solar mission. The Ministry of New and Renewable Energy mandates domestic content requirements through the Approved List of Models and Manufacturers. Manufacturing clusters in Pune and Ahmedabad are expanding aluminum extrusion and galvanizing capacity to serve localized procurement.
United States
Texas and California ISO territories drive single-axis tracker deployment under competitive power purchase agreement structures. FERC Order 2023 implementation gaps extend interconnection queue timelines, freezing capital deployment on tracker-equipped sites. Phoenix and Dallas-Fort Worth metro areas concentrate EPC contractor relationships and project finance origination for utility-scale arrays.
Saudi Arabia
Vision 2030 gigaprojects in the Western Region and NEOM Northwest mandate steel galvanizing and aluminum extrusion partnerships under national content requirements. The Saudi Standards, Metrology and Quality Organization enforces structural certification for desert wind load conditions. Jubail Industrial City is attracting mounting system fabricators seeking captive supply integration with domestic smelters.
Germany
Commercial rooftop retrofits and agrivoltaic dual-use frameworks in Bavaria and Baden-Württemberg elevate demand for elevated tracker structures. The EU Green Deal's REACH compliance and CE marking requirements accelerate replacement cycles among installers. Industrial clusters in North Rhine-Westphalia specialize in precision steel fabrication for high-latitude adjustable tilt systems.
Japan
Reservoir-based floating PV platforms across Kansai and Kyushu regions create demand for corrosion-resistant polymer anchoring systems. METI procurement guidelines prioritize agricultural land protection, constraining ground-mounted development. Manufacturing concentration in Chubu around Nagoya serves domestic stainless-steel mooring component requirements.
Photovoltaic Mounting System Market Competitive Landscape
Chinese producers anchor the upstream materials tier; American and European specialists hold differentiated positions in tracker software and precision fabrication. The vendor base organizes around three strategic archetypes: integrated controls-and-hardware providers, steel-heavy structural fabricators, and rapid-install racking specialists. Dominant competitive moves include EPC contractor consolidation around full-package suppliers and backward integration into aluminum extrusion capacity.
Among American tracker specialists, Nextracker Inc. and Array Technologies Inc. exemplify the integrated controls archetype through software-hardware convergence. GameChange Solar occupies a position within the rapid-install racking tier. Chinese fabricators including Arctech Solar Holding Co., Ltd. and Zhengzhou-based specialists anchor the structural steel and precision torque tube segment. European precision engineers represented by K2 Systems GmbH and Schletter sit within the premium-tier aluminum extrusion and rooftop-optimized category.
| Leading Market Players |
|---|
| Nextracker Inc. |
| Array Technologies Inc. |
| GameChange Solar |
| Arctech Solar Holding Co., Ltd. |
| Soltec Power Holdings |
| PVHardware |
| Unirac Inc. |
| Schletter |
| K2 Systems GmbH |
| Others |
Value Network & Pricing Analysis
Electromechanical technician scarcity across the US Southwest and Australian remote sites widens pricing-tier spreads between integrated tracker packages and hardware-only racking. Labor-cost differentials between certified installation crews and general construction labor feed directly into premium positioning for full-service EPC contracts versus component-only procurement.
Pricing Analysis
Volume-mass fixed-tilt systems compete on commodity steel pricing while tracker margins concentrate in software-enabled yield optimization tiers. Price differentiation separates IEC 62817-certified tracker controls from basic fixed-tilt hardware across utility-scale tenders. Pricing pressure stems from Chinese hot-rolled coil export quota volatility destabilizing project quoting timelines. Residential rooftop buyers in Brazil and Europe show highest price sensitivity due to net metering policy uncertainty, while Saudi gigaproject developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
CE marking and REACH compliance for structural aluminum gate European market access, filtering out uncertified Chinese extruders. Geographic supply concentration centers on Chinese Zhejiang and Guangdong provinces for aluminum profiles, Indian Pune and Ahmedabad clusters for galvanizing capacity, and German North Rhine-Westphalia for precision steel fabrication. Raw material dependencies span hot-rolled coil, 6000-series aluminum billet, and high-density polyethylene resin. Single-source vulnerability in Zhejiang extrusion capacity exposes procurement to regional logistics disruptions. Distribution runs through EPC contractor consolidation toward full-package suppliers who bundle steel, controls, and installation labor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion capacity expansion lagging Indian utility-scale tender awards sustains pricing power for qualified mounting system suppliers. Domestic content requirements under the Approved List of Models and Manufacturers prop localized procurement premiums.
For Market Incumbents: To counter mid-scale tracker vendors lacking dedicated regulatory affairs functions, Nextracker Inc. and Array Technologies Inc. should deepen firmware architecture investments satisfying EU AI Act conformity assessments. Array Technologies Inc. can anchor competitive positioning through captive aluminum extrusion partnerships in Gujarat state. Certification investment in IEC 62817 durability testing creates channel control against hardware-only suppliers. For New Entrants and Emerging Players: Rapid-install racking designs that reduce labor hours on large ground-mount sites offer a technology-first wedge into Brazilian distributed generation expansion. White-space targets include agrivoltaic dual-use frameworks in France and Germany requiring elevated tracker structures, and floating PV polymer anchoring systems across Japanese reservoirs. A direct EPC contractor engagement model bypasses fragmented procurement channels. For Investors and Strategic Acquirers: The window for entry favors precision steel fabricators with existing FERC Order 2023 cybersecurity integration capabilities. Long-term viability over the next decade hinges on software-hardware convergence rather than commodity racking production. Acquisition targets should demonstrate algorithmic transparency documentation for EU AI Act compliance. The signal to watch is interconnection queue clearance velocity across Texas and California ISO territories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Pune and Ahmedabad capacity additions satisfy Indian ALMM domestic content mandates. |
| Cybersecurity-Enabled Tracker Control Architecture | EU AI Act high-risk AI classification demands encrypted firmware with human-in-the-loop override. |
| Floating PV Platform Specialization | Japanese METI agricultural land protection policies redirect procurement toward reservoir-based systems. |
| Agrivoltaic Structure Engineering | French and German dual-use land frameworks permit elevated trackers preserving agricultural output. |
| EPC Full-Package Consolidation | Indian and Brazilian utility tenders shift risk allocation toward single-contract performance guarantees. |
Research Methodology
Document review covered FERC interconnection filings, EIA project development databases, and EU Green Deal regulatory texts, complemented by interviews with utility-scale EPC contractors, tracker control system engineers, and aluminum extrusion procurement managers. Secondary validation drew from IEC 62817 certification records, Indian Ministry of New and Renewable Energy tender documents, and Saudi Standards, Metrology and Quality Organization structural guidelines. Bottom-up capacity modeling triangulated against top-down demand projections from national solar mission targets.
Historical installation data cross-referenced against expert panel input on steel price elasticity and tracker software adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (tracker, fixed-tilt, roof-mount), installation environment (ground, floating, BIPV), material grade (galvanized steel, extruded aluminum, polymer composite), and end-user scale (utility, residential, commercial, industrial). CAGRs derived from capacity expansion announcements correlated with interconnection queue clearance rates and national content requirement phase-in schedules.
Several conditions sit outside the modeled scope, including unannounced trade remedy actions on Chinese aluminum extrusions, abrupt FERC Order 2023 implementation timeline accelerations, and force majeure disruptions to Zhejiang province smelter operations. Forecasts reflect assumptions regarding continued REPowerEU and IRA policy continuity. A model refresh is warranted upon material change in utility-scale PPA pricing spreads between tracked and fixed-tilt configurations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Polycrystalline Solar Panel Market