
 Global Crystalline Solar Cells Market | 2026-2036
Global Crystalline Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crystalline Solar Cells Market Foresight
Utility-scale independent power producers is reorganizing procurement priorities toward higher-wattage bifacial modules. LONGi Green Energy Technology Co., Ltd. anchors its position through in-house silicon ingot production from polysilicon to wafer. JinkoSolar Holding Co., Ltd. extends manufacturing scale across Southeast Asian facilities to serve distributed markets. Trina Solar Co., Ltd. differentiates through Tracker-integrated module solutions that reduce balance-of-system costs for EPC contractors.
Crystalline solar cells are semiconductor devices fabricated from silicon wafers with p-n junction architectures, typically achieving conversion efficiencies between 20% and 24% for commercial monocrystalline variants through phosphorus diffusion and silicon nitride anti-reflective coating processes. Their primary purpose is direct photovoltaic conversion of sunlight into direct-current electricity for grid-connected and off-grid power systems. Monocrystalline products command premium positioning in residential rooftops where space constraints maximize value per watt, while bifacial technology under heterojunction architecture captures expanding share in utility-scale projects seeking enhanced energy yield from rear-side albedo reflection. Passivated Emitter Rear Cell technology remains the dominant manufacturing platform for cost-optimized utility deployment.
FDA oversees occupational safety in US solar manufacturing facilities through OSHA-aligned workplace standards, while ECHA's REACH framework governs chemical substance registration for silicon purification and cell metallization processes imported into Europe. China's MIIT enforces GB standards for module efficiency certification and carbon footprint disclosure under dual carbon implementation pathways. India's BIS mandates compulsory registration for crystalline silicon modules entering the national grid-connected market under CEA technical specifications. Stakeholders must monitor evolving carbon-border adjustment mechanisms that will reshape sourcing decisions between Southeast Asian assembly hubs and integrated domestic supply chains.
Market Dynamics
Utility-scale developers are consolidating procurement around high-wattage bifacial modules while China's dual carbon goals and the EU Green Deal impose stricter embodied-carbon standards on imported cells, forcing supply chain reconfiguration across Southeast Asian assembly hubs.
Growth Catalysts
- India's PLI scheme:Production-linked incentives attract module assembly investment and concentrate demand growth in domestic manufacturing capacity.
- Heterojunction architecture:Passivated contact designs push commercial efficiencies toward 26% while reducing temperature coefficients for utility deployment.
- EU Green Deal carbon-border adjustments:Embodied-carbon disclosure requirements accelerate sourcing shifts toward vertically integrated European supply chains.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon purification costs swing with energy input prices, compressing wafer margins unpredictably.
- Xinjiang supply concentration:Over 40% of global polysilicon originates from a single Chinese province, creating geopolitical and forced-labor compliance exposure.
- Silver paste metallization:Screen-printed contacts require precious metal inputs that face mining supply constraints and price escalation.
Strategic Opportunities
- Agrivoltaic dual-use installations:Bifacial modules mounted above crops unlock land-constrained European markets with elevated albedo yields.
- Tracker-integrated module systems:Pre-cabled DC optimization reduces EPC labor hours and accelerates utility-scale commissioning timelines.
- US Inflation Reduction Act domestic content bonuses:Adders for cells and wafers manufactured in North America reward backward integration investments.
Industry Challenges
- Cell metallization engineering talent:Screen-printing and plating process optimization requires specialized semiconductor fabrication expertise that remains scarce outside East Asian manufacturing clusters.
- CEA-BIS certification timelines:India's compulsory registration scheme for grid-connected modules imposes 12-16 week testing queues that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crystalline Solar Cells Market |
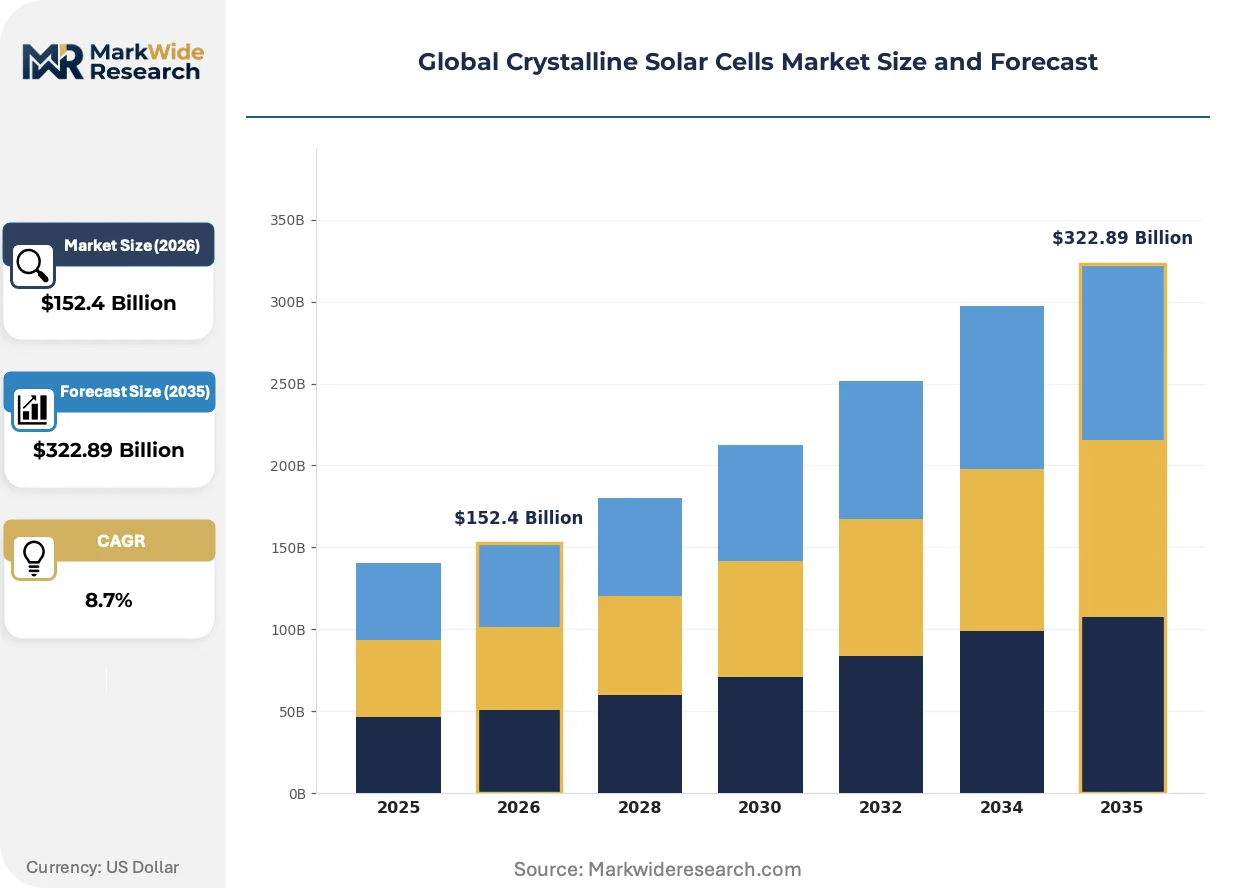
| Market Size in 2026 | $152.4 Billion |
| Market Size in 2035 | $322.89 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Passivated Emitter Rear Cell, Tandem Cell Technology: Heterojunction, Back Contact, Perovskite Tandem, Bifacial, PERC Application: Residential Rooftops, Commercial Buildings, Utility-Scale Projects, Off-Grid Systems, Space Missions End User: Energy Developers, EPC Contractors, Independent Power Producers, Telecommunications Providers, Agricultural Operators |
| Companies Covered | JinkoSolar Holding Co., Ltd., Trina Solar Co., Ltd., Canadian Solar Inc., LONGi Green Energy Technology Co., Ltd., JA Solar Technology Co., Ltd., First Solar, Hanwha Q CELLS, Risen Energy Co., Ltd., SunPower Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crystalline Solar Cells Market Shifts & Advancements
Silicon cell architectures are converging with tracker hardware and energy storage systems, blurring traditional boundaries between module supply and system integration while regulatory carbon accounting reshapes sourcing geography.
TOPCon tunnel oxide passivated contact technology is miniaturizing the efficiency gap between mass-produced PERC and laboratory heterojunction records. European utility developers now specify TOPCon in 80% of new tenders. This platform is miniaturizing the cost premium for high-efficiency architectures, compressing payback periods for premium module investments.
REACH chemical substance registration now governs silicon tetrachloride byproduct handling and silver paste solvent emissions across European cell imports. Manufacturers face expanded documentation burdens for metallization pastes. German and Dutch importers are accelerating qualification of water-based paste formulations to preempt authorization restrictions.
Long-term power purchase agreements now embed module performance guarantees that extend 25-30 years, shifting risk from project owners to cell suppliers. This contractual evolution forces manufacturers to tighten process control and warranty reserves. The phenomenon is most pronounced in Australian and Chilean markets where merchant price exposure drives conservative technology selection.
Global Crystalline Solar Cells Market Segmentation
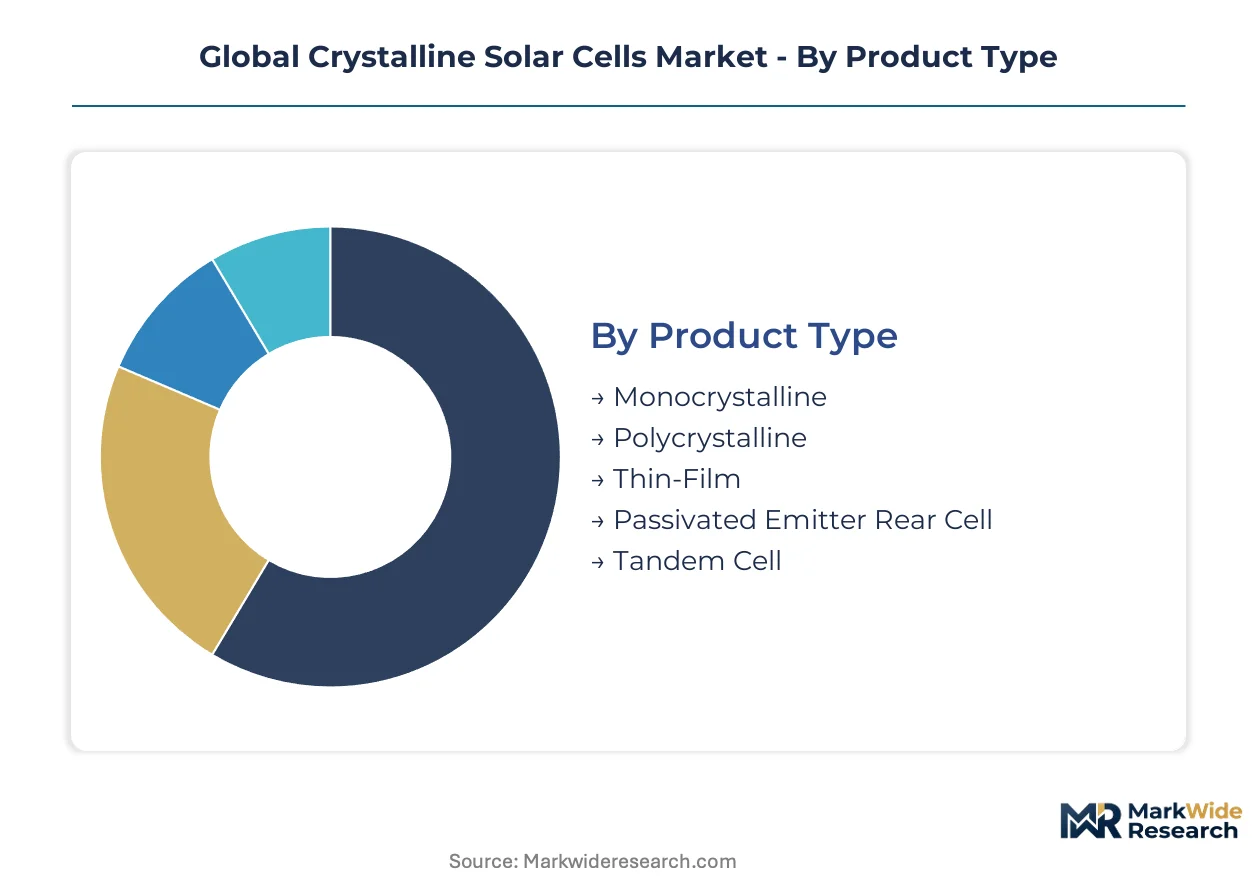
Crystalline solar cell procurement channels diverge sharply by segment. Residential buyers source through installer networks, while utility-scale developers contract directly with manufacturers for containerized volume. Technology selection determines margin structure and warranty risk allocation across these channels.
Product Type:
Channel flow varies by wafer architecture. Monocrystalline and PERC variants move through premium installer channels, while polycrystalline serves price-sensitive utility tenders. Tandem and thin-film technologies remain concentrated in specialized distributor networks.
- Monocrystalline:Silicon ingots grown from single-crystal boules yield uniform lattice structures with commercial efficiencies reaching 24%. Residential rooftops in Germany and Australia concentrate demand where space constraints maximize value per watt. Premium positioning sustains higher distributor margins.
- Passivated Emitter Rear Cell:Localized rear-surface passivation reduces recombination losses while preserving aluminum back-surface field compatibility. Utility-scale projects in India and Chile absorb volume through direct manufacturer contracts seeking bankable degradation warranties.
- Polycrystalline:Cast multicrystalline ingots serve emerging markets through price-optimized tenders.
- Thin-Film:Cadmium telluride and CIGS architectures occupy niche building-integrated applications.
- Tandem Cell:Perovskite-silicon stacks remain pre-commercial with limited pilot production.
By volume, PERC leads. By growth pace, monocrystalline with TOPCon upgrade pathways is climbing the fastest.
Technology:
Cost tier stratification separates mass-market from premium capture. Heterojunction and perovskite tandems command manufacturing premiums above 15%, while bifacial and PERC compete on levelized cost metrics.
- Heterojunction:Amorphous silicon layers deposited on crystalline substrates achieve sub-0.3% temperature coefficients. Japanese utility developers under METI procurement guidelines specify heterojunction for high-irradiance sites. Passivated contact designs reduce thermal degradation risk over 25-year warranties.
- Bifacial:Transparent rear-side encapsulation captures albedo reflection with 5-20% energy yield uplift. Agrivoltaic installations in France and the Netherlands drive demand where elevated mounting preserves agricultural output. Tracker compatibility multiplies rear-side exposure.
- PERC:Laser-grooved buried contacts dominate cost-optimized utility deployment.
- Back Contact:Interdigitated rear electrodes eliminate front-side shading losses for premium residential.
- Perovskite Tandem:Solution-processed top cells promise efficiency breakthroughs pending stability certification.
By manufacturing scale, PERC dominates. By efficiency trajectory, heterojunction is gaining share fastest.
Application:
Customer type determines procurement cadence and technical specifications. Residential and commercial segments prioritize aesthetics and rapid installation, while utility-scale and off-grid applications emphasize durability and remote monitoring.
- Utility-Scale Projects:Ground-mounted arrays above 50 MWac capacity require module-level power electronics and drone-accessible O&M protocols. Independent power producers in Saudi Arabia and Australia negotiate long-term offtake contracts with performance guarantees extending 30 years. Procurement teams specify bifacial TOPCon with single-axis tracking.
- Residential Rooftops:Distributed generation below 20 kW capacity favors all-black monocrystalline modules for visual integration. Installer networks in California and Italy bundle storage inverters with panel sales. Net metering policy stability shapes purchase timing.
- Commercial Buildings:Flat-roof ballasted systems serve manufacturing facilities and logistics warehouses.
- Off-Grid Systems:Remote telecommunications and rural electrification demand ruggedized frames and bypass diode redundancy.
- Space Missions:Radiation-hardened III-V multijunction cells serve satellite manufacturers through specialized aerospace suppliers.
By installed capacity, utility-scale leads. By project count, residential rooftops are expanding most quickly.
End User:
Margin capture concentrates with entities controlling development risk. Energy developers and independent power producers internalize module selection, while EPC contractors and agricultural operators delegate technical specification to engineering teams.
- Independent Power Producers:Balance-sheet-financed renewable portfolios negotiate frame contracts with tier-one manufacturers for multi-gigawatt procurement. European utilities under EU Green Deal compliance timelines source from vertically integrated suppliers with verified carbon disclosures. Long-term power purchase agreements transfer performance risk to cell vendors.
- EPC Contractors:Engineering-procurement-construction firms optimize balance-of-system costs through tracker-integrated module solutions. Labor productivity in US and Australian markets drives demand for pre-cabled DC string configurations. Procurement teams value installation speed over marginal efficiency gains.
- Energy Developers:Project origination specialists secure interconnection queue positions before module procurement.
- Telecommunications Providers:Tower operators in sub-Saharan Africa and Southeast Asia specify ruggedized off-grid packages.
- Agricultural Operators:European and Japanese farmers adopt agrivoltaic configurations for crop-shade revenue diversification.
By procurement volume, independent power producers lead. By contract growth, EPC contractors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's green hydrogen corridor anchors European solar module import flows, while China's Belt and Road grid interconnects redistribute manufacturing capacity across Southeast Asian assembly hubs.
China
Xinjiang polysilicon refineries and Jiangsu wafer fabs concentrate upstream supply. MIIT enforces GB standards for module efficiency certification and carbon footprint disclosure under dual carbon implementation pathways. Hefei and Xi'an industrial clusters host heterojunction pilot lines scaling toward mass production.
United States
ERCOT interconnection queues in Texas and CAISO grid expansion in California drive utility-scale procurement. The Inflation Reduction Act domestic content bonuses reward backward integration investments for cells and wafers manufactured in North America. Southeast manufacturing corridors in Georgia and South Carolina attract module assembly investment.
Germany
Agrivoltaic dual-use installations in Bavaria and Baden-Württemberg unlock land-constrained markets with elevated albedo yields. ECHA's REACH framework governs chemical substance registration for silicon purification and cell metallization processes. Saxony-Anhalt hosts emerging TOPCon research clusters bridging laboratory and fab-scale production.
India
Gujarat and Rajasthan solar parks absorb gigawatt-scale module deployment under PLI scheme incentives. BIS mandates compulsory registration for crystalline silicon modules entering the national grid-connected market under CEA technical specifications. Andhra Pradesh and Tamil Nadu assembly hubs face 12-16 week certification queues delaying market entry.
Japan
High-irradiance utility sites under METI procurement guidelines specify heterojunction architectures for reduced thermal degradation risk. JIS standards govern module performance certification for residential rooftop installations. Kyushu and Hokkaido prefectures concentrate bifacial tracker deployments seeking rear-side albedo capture.
Global Crystalline Solar Cells Market Competitive Landscape
Listed leaders compete with private specialists across capital access and manufacturing scale, producing a tiered structure where integrated polysilicon-to-module players hold cost advantages over pure-play assemblers. Three archetypes dominate: vertically integrated Chinese conglomerates controlling ingot supply, Southeast Asian contract manufacturers serving tariff-sensitive export markets, and regional specialists capturing domestic content bonuses. Competitive moves concentrate on backward integration into wafer and cell production and strategic partnerships with tracker and inverter suppliers.
Within the integrated conglomerate tier, LONGi Green Energy Technology Co., Ltd. and JinkoSolar Holding Co., Ltd. exemplify archetypes spanning polysilicon refinement through module assembly. Trina Solar Co., Ltd. occupies a position emphasizing system-level solutions. These three anchors represent distinct strategic postures: captive silicon supply, geographic diversification across Southeast Asian facilities, and hardware-integrated offerings reducing balance-of-system costs.
| Leading Market Players |
|---|
| JinkoSolar Holding Co., Ltd. |
| Trina Solar Co., Ltd. |
| Canadian Solar Inc. |
| LONGi Green Energy Technology Co., Ltd. |
| JA Solar Technology Co., Ltd. |
| First Solar |
| Hanwha Q CELLS |
| Risen Energy Co., Ltd. |
| SunPower Corporation |
| Others |
Supply & Pricing Matrix
Twelve-to-sixteen-week certification queues for BIS registration compress inventory turnover for India-bound shipments, concentrating pricing power with vertically integrated manufacturers holding captive wafer supply while forcing pure-play assemblers into spot-market polysilicon exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heterojunction modules with 25-year performance guarantees from PERC utility volumes and polycrystalline tenders. Price differentiation hinges on certification tier—BIS/CEA registration versus IEC baseline—and volume scale with multi-gigawatt frame contracts. Cost compression in standard-tier PERC is intensifying because Xinjiang polysilicon price volatility feeds through wafer spot markets. Utility-scale independent power producers exhibit lowest price sensitivity, while distributed residential installers face margin pressure from installer network commissions.
Supply Chain Analysis
Inventory cycles stretching 90-120 days from polysilicon ingot to module containerization expose manufacturers to energy input cost swings. Supply concentrates in China for polysilicon refinement and wafer slicing, Vietnam and Thailand for tariff-advantaged assembly, and India for PLI-subsidized domestic capacity. Raw material dependencies encompass metallurgical-grade silicon, silver paste for screen-printed contacts, and aluminum frames. Single-source vulnerability in Xinjiang polysilicon—over 40% of global supply—creates forced-labor compliance exposure under EU Green Deal carbon-border adjustments. Distribution runs through port-centric consolidation at Rotterdam for European offtake and Mundra for Indian utility parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crystalline solar cell market is exiting a polysilicon price supercycle into capacity-led margin compression, with cyclical recovery tied to heterojunction and TOPCon technology upgrade capex cycles.
For Market Incumbents: Consolidate backward into ingot production to escape Xinjiang supply concentration and capture IRA domestic content bonuses for North American wafer fabs. Lock multi-year polysilicon offtake with metallurgical-grade suppliers outside Xinjiang to preempt EU carbon-border adjustment exposure. Priority lever rests on heterojunction pilot line scale-up before TOPCon cost curves flatten efficiency premiums.
For New Entrants and Emerging Players: Differentiate on agrivoltaic module configurations with elevated bifacial gain certification for European land-constrained markets. Target India's PLI scheme assembly incentives before BIS registration queues lengthen further. Go-to-market angle emphasizes tracker-integrated pre-cabled DC strings reducing EPC labor hours for Australian and US utility contractors.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate energy divisions with stranded PERC capacity lacking TOPCon retooling capital. Long-term viability favors integrated polysilicon-to-module players with verified carbon disclosures under tightening EU Green Deal standards. Signal to watch is BIS certification timeline extension beyond 16 weeks, which would accelerate consolidation toward domestic Indian manufacturers with queue priority.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive Xinjiang-free supply secures EU carbon-border compliance and IRA bonus eligibility. |
| Heterojunction Capacity Buildout | Sub-0.3% temperature coefficients command premium positioning in Japanese METI utility tenders. |
| Tracker-Integrated Module Systems | Pre-cabled DC optimization reduces EPC labor costs for ERCOT and CAISO interconnection queues. |
| Agrivoltaic Certification Program | Elevated albedo yield validation unlocks Bavaria and Netherlands dual-use land constraints. |
| Long-Term Polysilicon Supply Agreement | Fixed-price metallurgical-grade contracts hedge against energy-input volatility in Jiangsu refining. |
Research Methodology
A standing panel of utility procurement directors, EPC project managers, polysilicon supply specialists, and BIS certification consultants provided ongoing calibration against market developments. Primary interviews with tier-one module manufacturers and independent power producers in India, Germany, and the United States were cross-validated against secondary sources including EIA generation data, IEA renewable investment trackers, MIIT GB standard disclosures, and SEC filings from listed solar manufacturers. Bottom-up project pipeline aggregation was triangulated with top-down capacity installation forecasts.
Consistency checks against IEA and BNEF external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation by wafer architecture, cell technology, application scale, and regional regulatory cluster. CAGRs were derived from installer survey data on technology substitution rates and utility tender award patterns. Forecast inputs incorporated polysilicon price elasticity, PLI scheme disbursement schedules, and carbon-border adjustment implementation timelines.
Decision-makers should treat outputs as directional under assumptions of stable IRA domestic content rules and EU Green Deal carbon-border phase-in; material deviation in either regulatory trajectory would warrant model refresh. Specific risk factors include forced-labor supply chain exclusions, BIS certification backlog extension, and heterojunction equipment delivery delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Austria Solar Energy Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
High-Efficiency Solar Modules Market