
 EV Charge Management Software Market | 2026-2036
EV Charge Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
EV Charge Management Software Market Insights
Commercial fleet operators are unwinding the historical dominance of residential users as the primary buyer archetype in EV charge management software procurement. ChargePoint leverages its installed base across North American highway corridors to sustain recurring software revenue streams. Siemens anchors European deployments through its industrial automation heritage and grid-integration capabilities. ABB competes on hardware-software bundling across high-power charging sites, extending its factory automation expertise into energy management.
EV charge management software orchestrates charging sessions, load balancing, and tariff optimization across distributed charging assets through real-time communication with grid operators and vehicle onboard systems. The platform integrates OCPP 2.0.1 protocol messaging, ISO 15118 plug-and-charge authentication, and dynamic power allocation algorithms to maximize asset utilization while minimizing demand charges. Cloud-based deployments lead in new installations due to lower capital requirements and faster feature iteration cycles, though hybrid architectures are gaining traction among fleet operators with strict data sovereignty requirements. Energy management functionality represents the fastest-expanding feature category as vehicle-to-grid bidirectional charging moves from pilot to commercial scale.
The US Federal Energy Regulatory Commission shapes wholesale market participation rules for aggregated EV loads, while the EU Green Deal and F-Gas Regulation accelerate infrastructure buildout mandates across member states. California's Air Resources Board zero-emission fleet rules and Germany's Bundesnetzagentur grid codes create divergent compliance templates that software vendors must navigate. Stakeholders should monitor how NEVI funding interoperability requirements and evolving ISO 15118-20 bidirectional standards reshape platform architecture roadmaps and partnership strategies.
Market Dynamics
Vehicle-to-grid bidirectional charging capabilities are compressing the boundary between EV fleet operations and distributed energy resource participation, forcing software vendors to rebuild their platforms around real-time grid market integration rather than session management alone.
Growth Catalysts
- California's Air Resources Board zero-emission fleet mandates:Commercial operators across logistics and transit sectors must electrify vehicle pools by specified deadlines, creating immediate procurement pull for charge orchestration platforms that can manage hundreds of simultaneous charging events.
- OCPP 2.0.1 protocol standardization:Interoperability requirements embedded in the US NEVI funding program and EU Alternative Fuels Infrastructure Regulation eliminate vendor lock-in risks, accelerating replacement cycles for legacy proprietary systems.
- Utility time-of-use rate structures:Demand charge volatility in Germany and California creates measurable ROI for dynamic load balancing algorithms that shift charging loads away from peak pricing windows.
Market Restraints
- Silicon carbide semiconductor supply concentration:Power electronics manufacturing for high-frequency charging hardware remains concentrated among Asian foundries, creating input cost volatility that propagates through to software-hardware bundled procurement.
- ISO 15118-20 certification timelines:Plug-and-charge authentication and bidirectional power flow standards remain in phased rollout, forcing vendors to maintain multiple protocol stacks and delaying unified platform architectures.
- Legacy fleet management system entrenchment:Existing telematics and route optimization investments by major logistics operators create integration friction that slows pure-play charge management software displacement.
Strategic Opportunities
- United Kingdom grid services market opening:National Grid ESO's flexibility procurement mechanisms now explicitly include aggregated EV loads, creating revenue stacking opportunities for software platforms that can bid into frequency response and capacity markets.
- Vehicle-to-home residential applications:Residential EV owners in markets with unreliable grid infrastructure represent an underpenetrated segment for bidirectional charging software that manages home energy arbitrage.
- EU Green Deal carbon accounting integration:Corporate sustainability reporting requirements create demand for charge management platforms that can attribute Scope 3 emissions reductions to specific charging events and renewable energy certificates.
Industry Challenges
- Cybersecurity certification complexity:IEC 62443 industrial security standards and EU NIS2 directive requirements impose multi-quarter compliance timelines that delay product launches and inflate development overhead.
- Embedded systems talent scarcity:The intersection of power electronics firmware, cloud-native platform development, and grid communication protocols requires skill sets concentrated among a small pool of specialists with automotive and utility sector experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Charge Management Software Market |
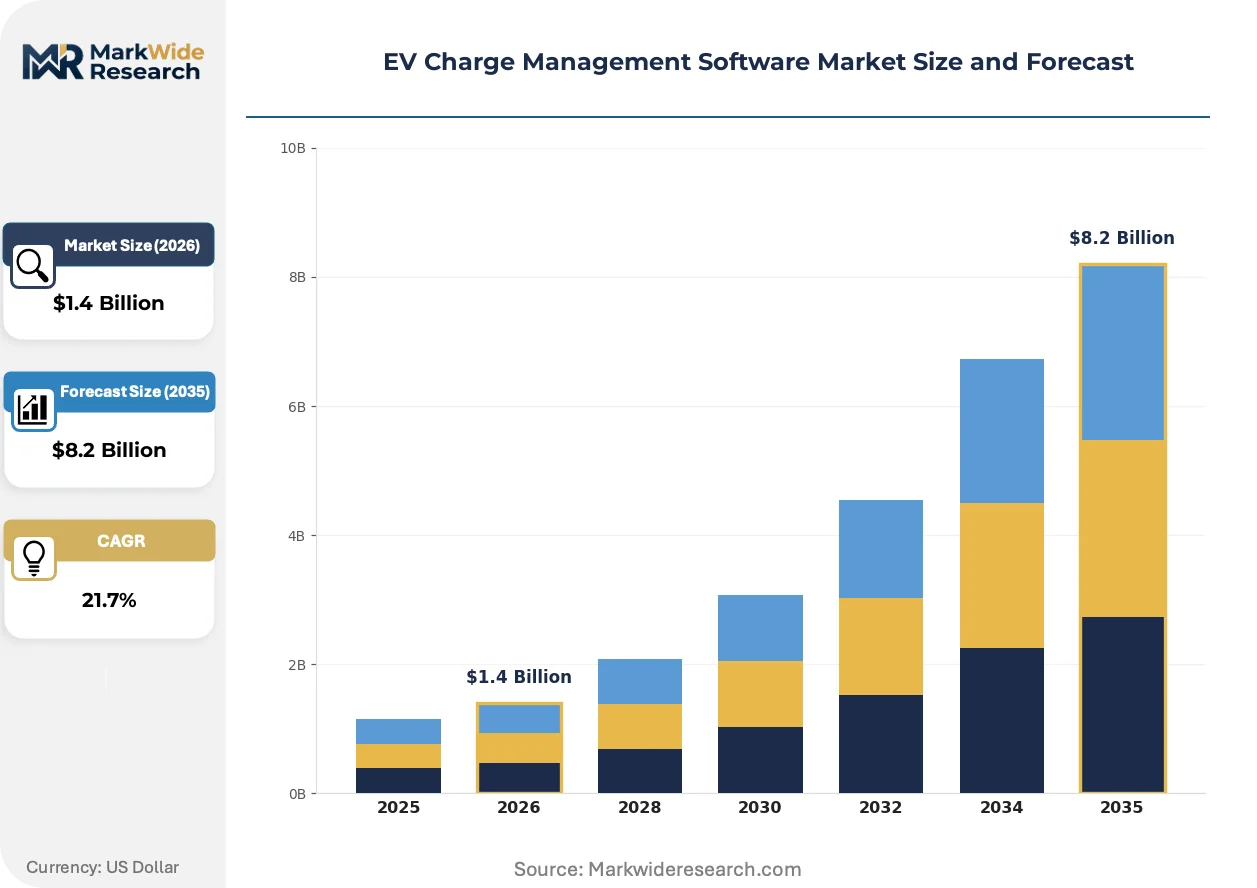
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $8.2 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile Solutions End User: Commercial Fleets, Residential Users, Charging Network Operators, Automotive Manufacturers Deployment Model: Public Charging Stations, Private Charging Infrastructure, Fleet Charging, Smart Home Integrations Feature: Real-Time Monitoring, Payment Processing, User Management, Energy Management |
| Companies Covered | Ampeco, Schneider Electric, ChargePoint, Siemens, ABB, Driivz, Shell, Monta, EVBox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Charge Management Software Market Trends and Innovations
Software-defined energy management is displacing hardware-centric power distribution in charging infrastructure, with algorithms rather than physical switchgear determining how electrons flow between vehicles, buildings, and grid assets.
Edge computing architectures are fragmenting the traditional cloud-centralized model for charge management platforms. Real-time load balancing algorithms now execute on local controllers to meet sub-second response requirements for grid frequency regulation services. Fleet operators with strict data sovereignty requirements in Germany and California are deploying hybrid architectures that keep sensitive vehicle telemetry on-premises while pushing anonymized grid interaction data to cloud analytics layers. This fragmentation is compressing margins for pure SaaS vendors unable to support distributed deployment models.
The EU F-Gas Regulation and its phasedown of fluorinated greenhouse gases used in charging station cooling systems is forcing hardware redesigns that propagate into software thermal management modules. Vendors must now model and predict thermal throttling events under high-power charging scenarios to maintain session throughput. European deployments face the most acute compliance pressure, with German TÜV certification bodies expanding audit scopes to include software-controlled thermal derating algorithms.
Outcome-based service contracts are displacing per-port licensing for enterprise fleet deployments. Logistics operators now negotiate agreements tied to vehicle uptime guarantees and energy cost savings rather than seat counts or charging station connections. This shift concentrates purchasing power among procurement teams with sophisticated energy market expertise, most visibly in California where commercial electricity rates create the strongest economic case for performance-based vendor relationships.
EV Charge Management Software Market Segmentation
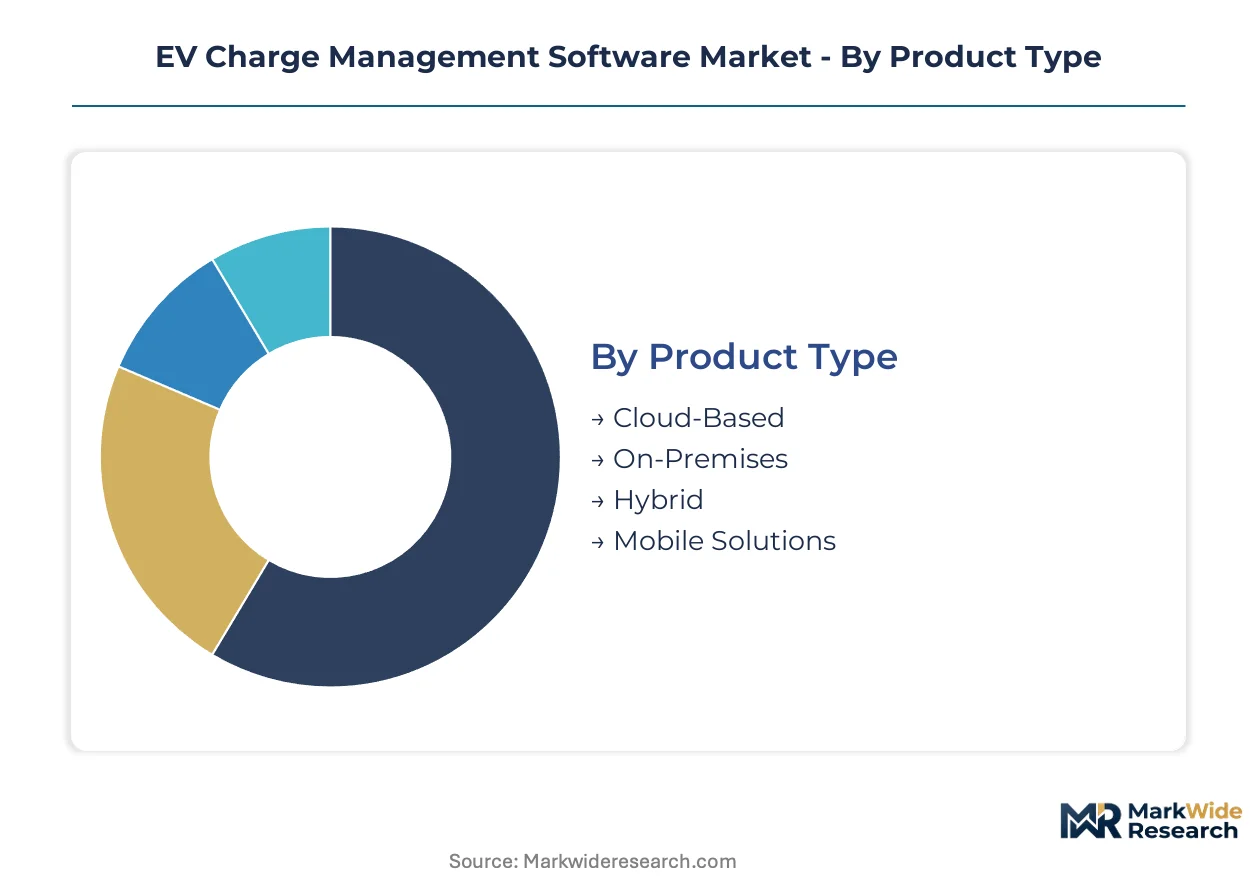
Segmentation in EV charge management software reveals how procurement criteria diverge across regulatory environments and operational scales. Deployment architecture choices increasingly hinge on data sovereignty mandates from Germany's BfDI and California's CCPA rather than purely technical specifications.
Product Type:
German BDSG and EU GDPR data localization requirements create divergent compliance burdens across deployment architectures, pushing fleet operators toward specific infrastructure models.
- Cloud-Based:Multi-tenant SaaS architectures enable rapid feature deployment and centralized analytics for distributed charging networks. Demand concentrates among mid-sized charging network operators in California seeking to minimize capital expenditure while meeting FERC cybersecurity guidelines for grid interconnection.
- On-Premises:Dedicated server installations within operator facilities maintain complete data custody and sub-millisecond response times for grid frequency regulation. German commercial fleet operators with BDSG-mandated data residency requirements represent the primary adoption cluster for this architecture.
- Hybrid:Split processing keeps sensitive vehicle telemetry local while pushing grid interaction data to cloud analytics layers.
- Mobile Solutions:Native applications for iOS and Android platforms provide driver-facing session control and payment interfaces.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
End User:
Procurement authority is shifting from residential consumers toward enterprise procurement teams with dedicated energy market expertise.
- Commercial Fleets:Logistics and transit operators managing hundreds of vehicles require orchestration platforms handling simultaneous charging events, route integration, and utility demand charge optimization. California CARB zero-emission mandates and Germany's Bundesnetzagentur grid codes create immediate procurement pull from parcel delivery and municipal bus operators.
- Residential Users:Individual EV owners primarily seek smartphone-based session initiation and home energy arbitrage capabilities. Demand clusters in markets with time-of-use rate structures from utilities like PG&E and Southern California Edison.
- Charging Network Operators:CPOs managing public infrastructure prioritize interoperability certifications and roaming settlement capabilities.
- Automotive Manufacturers:OEMs embed charge management into vehicle telematics platforms for seamless plug-and-charge authentication.
Procurement concentration favors Commercial Fleets; technology integration favors Automotive Manufacturers.
Deployment Model:
Site classification determines which regulatory frameworks apply and which revenue streams platforms can access.
- Public Charging Stations:Curb-side and highway corridor installations must comply with NEVI funding interoperability requirements and EU Alternative Fuels Infrastructure Regulation payment terminal mandates. These sites face the most acute cybersecurity certification pressure under IEC 62443 and emerging EU NIS2 directives.
- Private Charging Infrastructure:Workplace and destination charging operated by single entities avoids public access regulations while enabling closed-loop payment systems. Corporate campuses in California and industrial parks in Germany represent primary deployment sites.
- Fleet Charging:Dedicated depot infrastructure supports overnight charging for logistics and transit operators with predictable duty cycles.
- Smart Home Integrations:Bidirectional charging coordination with residential solar and battery storage systems.
Regulatory complexity favors Public Charging Stations; margin expansion favors Fleet Charging.
Feature:
Functionality prioritization reflects the market's transition from session management toward grid market participation.
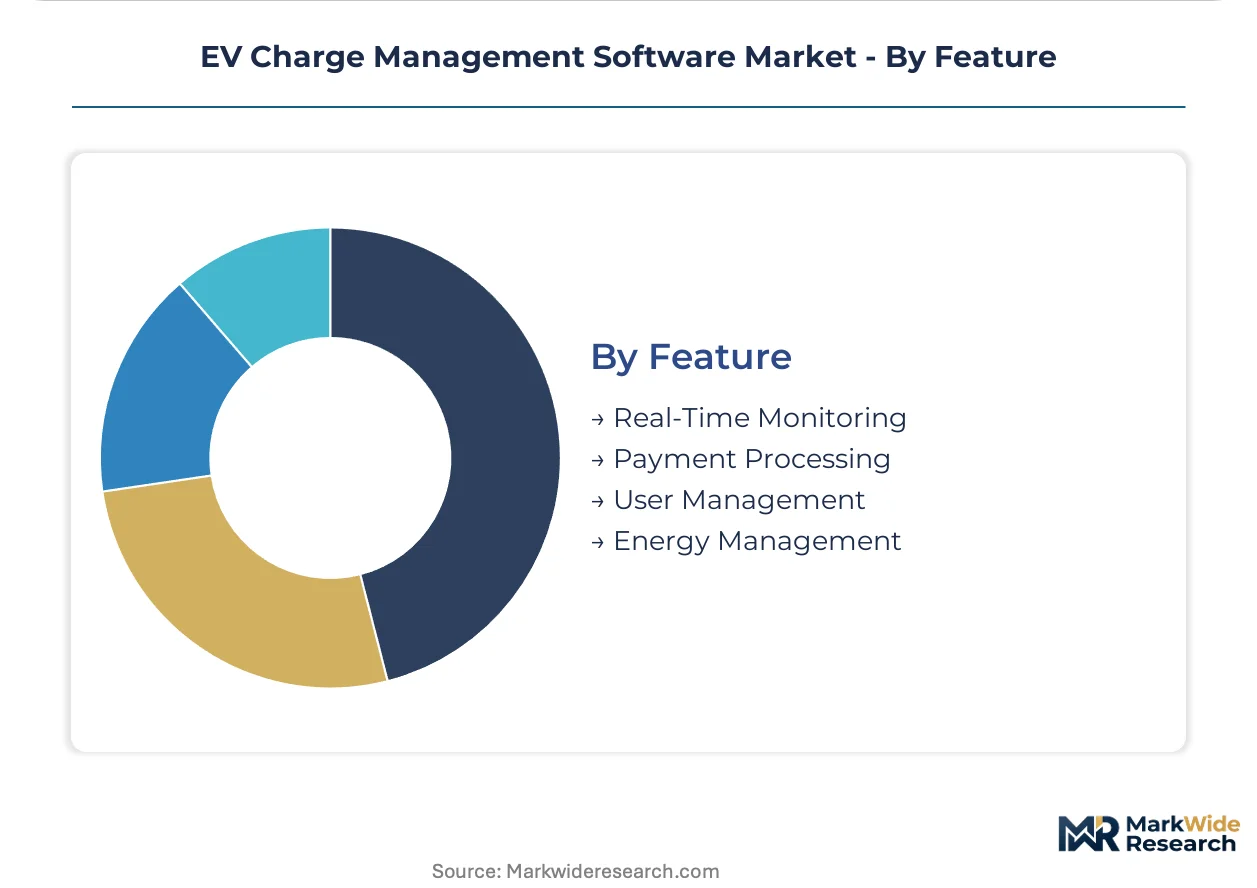
- Energy Management:Dynamic load balancing, vehicle-to-grid bidirectional control, and wholesale market bidding algorithms now represent the steepest expansion trajectory as aggregated EV loads gain FERC Order 2222 and UK National Grid ESO flexibility market eligibility. Platforms must model thermal derating under EU F-Gas Regulation cooling constraints.
- Real-Time Monitoring:Sub-second telemetry collection from charging hardware and vehicle onboard systems enables predictive maintenance and immediate fault detection. Essential for high-availability fleet operations.
- Payment Processing:Roaming settlement, subscription billing, and utility bill integration.
- User Management:Driver authentication, access control, and corporate account hierarchies.
Platform differentiation favors Energy Management; baseline functionality favors Real-Time Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German software vendors export charge management platforms to fleet operators across California and the United Kingdom, while US-based providers supply interoperability solutions to European charging network operators navigating divergent regulatory requirements.
United States
California's Air Resources Board zero-emission fleet mandates drive procurement from logistics operators managing depot charging for hundreds of electric trucks. The Federal Energy Regulatory Commission's Order 2222 enables aggregated EV loads to participate in wholesale electricity markets. Los Angeles and San Francisco anchor the densest concentration of commercial fleet electrification projects, with software vendors embedding NEVI funding compliance modules.
Germany
Bundesnetzagentur grid codes require bidirectional charging capabilities for new installations, accelerating platform rebuilds around vehicle-to-grid integration. The EU Green Deal and F-Gas Regulation impose thermal management constraints that propagate into software-controlled derating algorithms. Munich and Stuttgart host the primary engineering clusters where automotive OEMs collaborate with charge management providers on ISO 15118-20 certification.
United Kingdom
National Grid ESO flexibility procurement mechanisms now explicitly include aggregated EV loads, creating revenue stacking opportunities for software platforms. OZEV grant programs subsidize workplace and residential charging infrastructure with interoperability requirements. London and the Midlands concentrate fleet operator headquarters procuring outcome-based service contracts tied to vehicle uptime guarantees.
France
Decree No. 2021-771 mandates smart charging capabilities for all new and replacement charging points, accelerating cloud-based platform adoption. The country's national pharmaceutical regulator framework does not apply here; instead, CRE tariff structures incentivize load shifting away from peak demand periods. Paris and Lyon anchor charging network operator deployments prioritizing roaming settlement capabilities.
Netherlands
AFIR payment terminal mandates and interoperability requirements eliminate vendor lock-in risks for public charging infrastructure. The country's dense urban geography favors compact depot charging solutions for last-mile delivery electrification. Amsterdam and Rotterdam host pilot programs testing vehicle-to-grid bidirectional charging at scale.
EV Charge Management Software Market Competitive Landscape
Player mix skews toward industrial conglomerates with grid-automation heritage alongside pure-play software specialists. Market structure exhibits tiered consolidation with three to five dominant platforms capturing enterprise fleet deployments. Strategic archetypes include hardware-software bundlers, cloud-native SaaS providers, and energy utility affiliates. Competitive moves center on ISO 15118-20 certification races and strategic partnerships with silicon carbide semiconductor suppliers.
Among industrial conglomerates, Schneider Electric and Siemens exemplify the grid-integration archetype, anchoring European deployments through industrial automation expertise. ChargePoint occupies a position representing the installed-base leverage model, sustaining recurring software revenue through highway corridor dominance. ABB sits within the hardware-software bundling tier, extending factory automation capabilities into high-power charging site management.
| Leading Market Players |
|---|
| Ampeco |
| Schneider Electric |
| ChargePoint |
| Siemens |
| ABB |
| Driivz |
| Shell |
| Monta |
| EVBox |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide power module substitution for silicon-based IGBT assemblies redraws procurement geography toward Taiwanese and Chinese foundries while compressing hardware-software bundle margins for European and North American platform vendors. This materials transition simultaneously elevates input cost volatility and forces charge management software providers to absorb margin pressure or push pricing adjustments downstream to fleet operators.
Pricing Analysis
OCPP 2.0.1-certified platforms command substantial premiums over legacy proprietary systems and pre-standardization installations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15118-20 compliant energy management suites from basic session orchestration tools. Pricing pressure stems from silicon carbide semiconductor supply bottlenecks propagating through hardware-software bundles. Commercial fleet operators in California exhibit acute price sensitivity due to scale procurement, while German industrial operators prioritize certification compliance over unit economics.
Supply Chain Analysis
Strategic stockpiling of power electronics components dominates inventory strategy among charge management hardware vendors anticipating silicon carbide wafer allocation constraints. Manufacturing concentration centers on Taiwan, China, and South Korea for high-frequency semiconductors, with Germany and the United States anchoring final system integration. Critical dependencies include silicon carbide substrates, high-voltage capacitors, and liquid cooling systems. Single-source vulnerability in Asian foundry capacity represents the primary structural risk. Distribution runs through direct OEM partnerships and charging network operator procurement channels rather than traditional IT reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV charge management software sits in early-cycle expansion as vehicle-to-grid commercialization accelerates platform rebuilds around grid market participation rather than session management alone. California CARB mandates and Germany BNetzA bidirectional requirements create immediate procurement pull from logistics and transit operators.
For Market Incumbents: Shield installed-base revenue by accelerating ISO 15118-20 certification timelines ahead of competitor platform launches. Prioritize backward integration into edge computing hardware to capture margin pools fleeing pure SaaS vendors. Cloud-native specialists with limited hybrid deployment capabilities represent the most vulnerable incumbent archetype as German BDSG and California CCPA data sovereignty requirements harden.
For New Entrants and Emerging Players: Anchor in vehicle-to-home residential applications across markets with unreliable grid infrastructure, the most underpenetrated segment in current competitive coverage. Target United Kingdom flexibility market participation as National Grid ESO mechanisms now explicitly include aggregated EV loads. Pursue partnership-first go-to-market models with silicon carbide semiconductor suppliers to secure hardware allocation priority.
For Investors and Strategic Acquirers: FERC Order 2222 wholesale market participation rules reshape the acquisition landscape toward platforms with proven grid integration capabilities and utility-scale deployment track records. Long-term viability favors vendors bridging automotive telematics and utility control room systems. Target acquisition candidates include pure-play energy management specialists with ISO 15118-20 development progress and existing utility partnerships. The signal to monitor is silicon carbide supply contract announcements from platform vendors, indicating secured manufacturing capacity for hardware-software bundle expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15118-20 Certification Investment | Unlocks bidirectional charging revenue streams under Germany BNetzA mandates. |
| Silicon Carbide Supply Partnership | Secures semiconductor allocation priority for high-power charging hardware production. |
| Hybrid Cloud-Edge Architecture Deployment | Addresses German BDSG data residency requirements while maintaining cloud analytics. |
| UK Grid Services Market Entry | Captures frequency response and capacity market revenue through National Grid ESO mechanisms. |
| Outcome-Based Service Contract Transition | Aligns vendor economics with California fleet operator uptime guarantees and energy savings. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet electrification managers, charging network operator CTOs, utility demand response planners, and automotive OEM platform engineers. Secondary validation drew from FERC Order 2222 implementation filings, EU Alternative Fuels Infrastructure Regulation compliance databases, California CARB zero-emission fleet program documentation, and silicon carbide supply chain trade data. Bottom-up unit economics modeling triangulated against top-down market sizing across deployment architectures and end-user segments.
Across the analysis window, volume and value outputs reflect segmentation by deployment model, fleet scale tier, integration complexity level, and regional regulatory framework cluster. CAGRs were derived from adoption curve modeling calibrated to mandate-driven procurement timelines and infrastructure buildout schedules. Key forecast inputs include utility rate structure evolution and vehicle-to-grid hardware penetration assumptions.
Decision-makers should treat outputs as directional under continued electrification mandate enforcement and silicon carbide supply expansion assumptions; material deviation in either would warrant model refresh. Cybersecurity certification delays or wholesale market rule reversals represent specific risk factors that could compress adoption trajectories. Practitioners should keep alternative scenarios live as F-Gas Regulation thermal constraints and NEVI funding disbursement pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
Electric Car Charging Pile Market