
 Off-Grid Energy Storage Systems Market | 2026-2036
Off-Grid Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Grid Energy Storage Systems Market Intelligence
The premium cycle-life tier above 6,000 cycles at 80 percent depth of discharge is collapsing into the mid-market as lithium iron phosphate cell costs fall and manufacturing scales. Tesla leverages its Nevada-based cell production to anchor pricing power in residential Powerwall configurations across North America. BYD sustains backward integration into cathode powder and cell assembly, which secures margin control in commercial-scale container systems. CATL dominates cylindrical and prismatic form factors for telecom backup applications in emerging markets, where EnerSys competes through its established lead-acid service channel and recycling infrastructure.
Off-grid energy storage systems are electrochemical or mechanical assemblies that capture electrical energy from distributed generation sources and discharge it on demand, typically incorporating battery management systems with voltage regulation between 48V and 1,500V DC depending on scale. These systems buffer intermittency from solar PV or wind installations where no utility interconnection exists, delivering stable power to isolated loads. Lithium-ion configurations now lead product type segmentation due to energy density advantages in residential and commercial footprints, while flow batteries occupy the long-duration niche above six hours of discharge where aqueous chemistry reduces thermal runaway risk. Lead-acid technology persists in telecommunications backup where capital constraints dominate total cost of ownership calculations, particularly across remote locations in Southeast Asia and Latin America.
The U.S. EPA and FERC shape market access through stationary battery emissions guidelines and wholesale market participation rules for distributed storage assets, while the EU's Battery Regulation and CE marking framework enforce supply chain due diligence and safety testing protocols for systems entering member states. India's BIS certification and CEA technical standards for standalone power systems create compliance thresholds that filter out uncertified imports. Stakeholders must monitor how evolving carbon border adjustments and domestic content incentives across these jurisdictions reshape procurement decisions and supplier qualification requirements.
Market Dynamics
Lithium iron phosphate cell costs are collapsing the premium cycle-life tier above 6,000 cycles into mid-market pricing, compressing margins for incumbent suppliers while democratizing access to long-duration storage across rural electrification programs.
Growth Catalysts
- Rural Electrification Mandates:Sub-Saharan Africa's national grid extension programs are accelerating household procurement of lithium-ion battery systems as primary power sources.
- EU Battery Regulation:Mandatory carbon footprint disclosure and recycled content thresholds are creating compliance-driven replacement demand for certified energy storage products.
- State-Level Solar Mini-Grids:India's tender-based procurement for commercial and industrial standalone power systems is scaling containerized storage deployments.
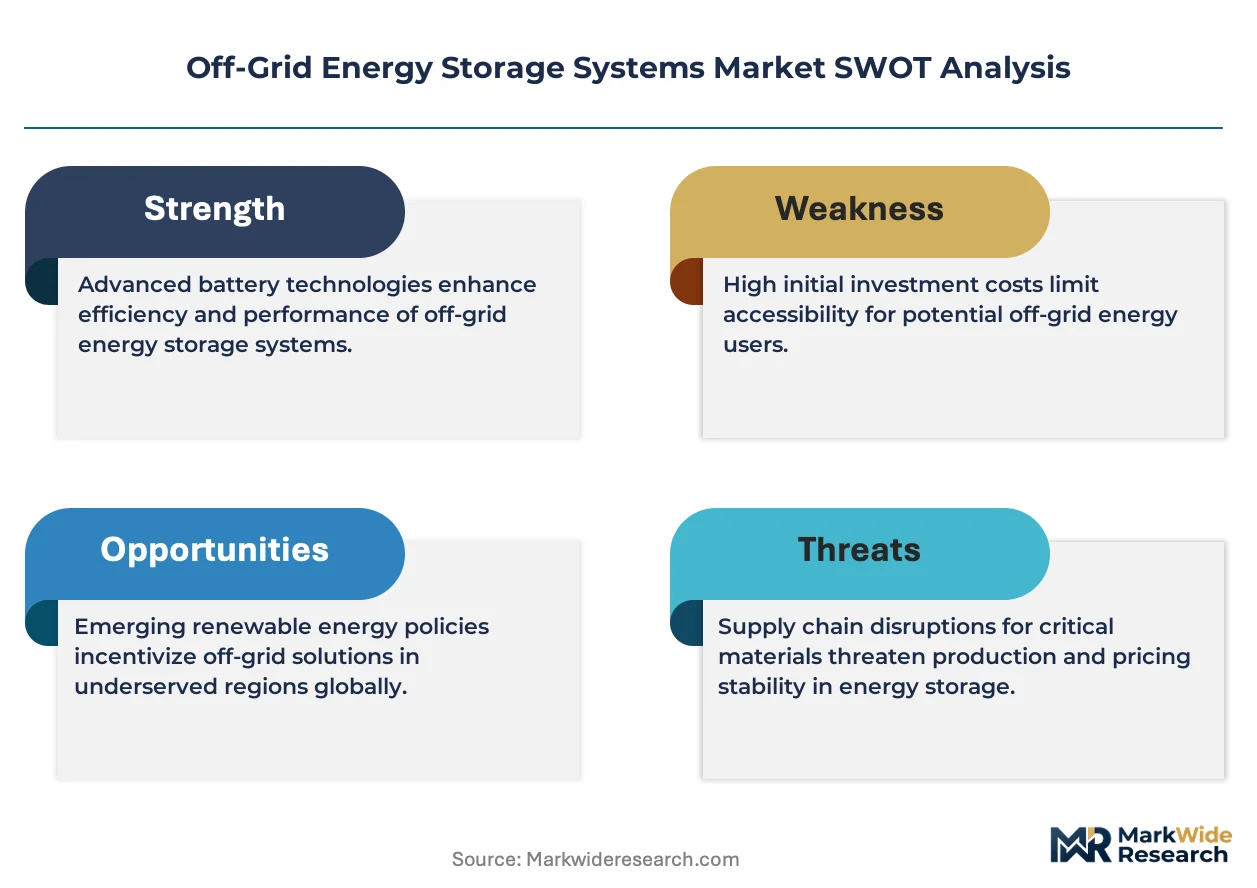
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings in cathode precursor chemicals destabilize cell cost forecasting for project developers.
- Supply Concentration Risk:Cathode powder and separator manufacturing clusters in East Asia create single-point vulnerability for non-integrated assemblers.
- Flow Battery Capex Premium:Aqueous vanadium systems face technical limitation in energy density below 20 Wh/L, restricting footprint-constrained applications.
Strategic Opportunities
- Telecom Backup Modernization:Southeast Asian and Latin American tower operators are retrofitting lead-acid installations with lithium-ion replacements.
- CEA Technical Standards:India's certification requirements for standalone power systems filter uncertified imports, creating protected market access for compliant suppliers.
- Solar-Diesel Hybrid Convergence:Integration of photovoltaic generation with battery buffering is displacing pure diesel mini-grids in remote mining and agricultural processing.
Industry Challenges
- Battery Management System Firmware:Shortage of embedded software engineers with electrochemical safety expertise delays product certification timelines.
- Multi-Jurisdiction Compliance:Divergent voltage regulation standards between 48V DC residential and 1,500V DC utility-scale systems fragment R&D resource allocation.
- Recycling Infrastructure Gap:End-of-life lithium-ion processing capacity lags deployment rates, creating liability exposure for original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Grid Energy Storage Systems Market |
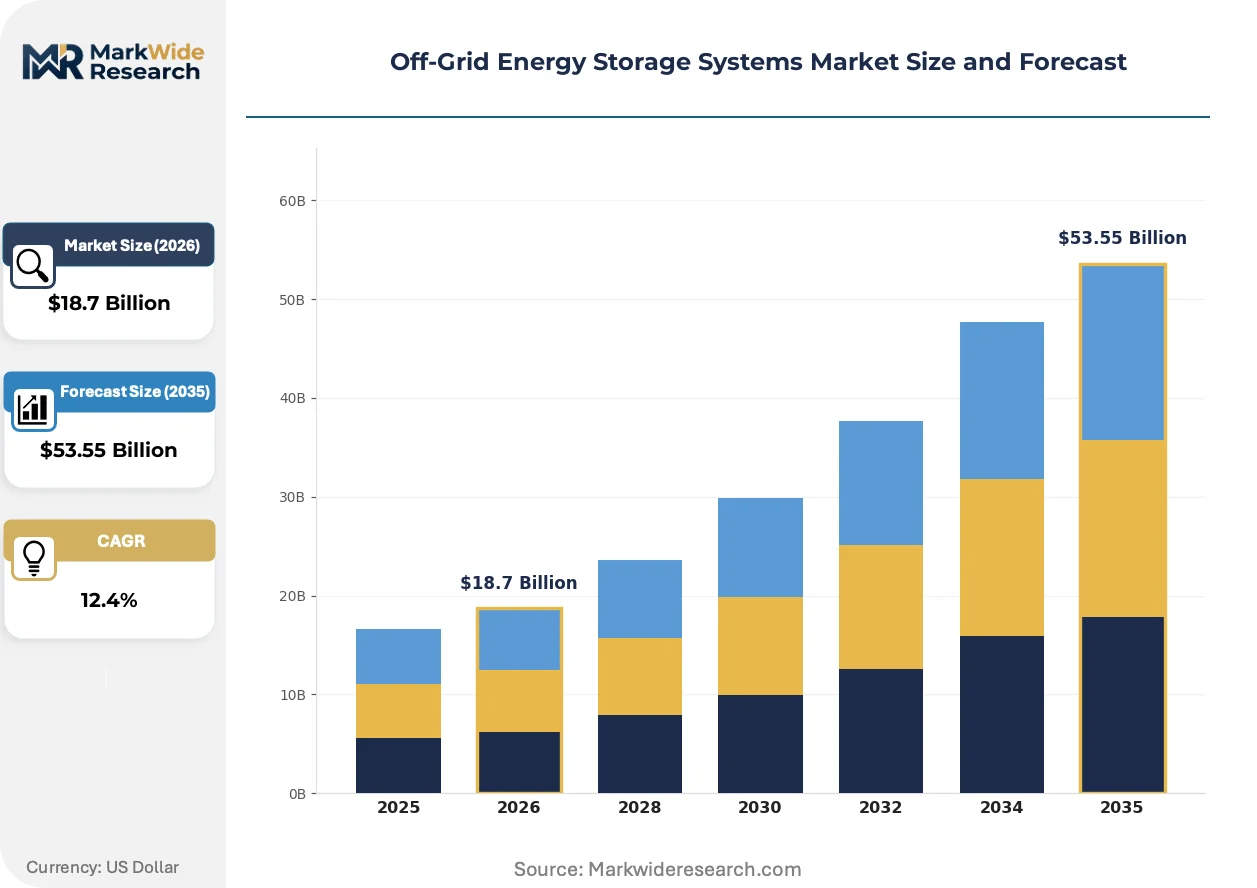
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow Batteries, Flywheel Application: Residential, Commercial, Remote Locations, Telecommunications End User: Households, Businesses, NGOs, Emergency Services Technology: Battery Storage, Supercapacitors, Pumped Hydro, Compressed Air |
| Companies Covered | Sonnen, BYD, EnerSys, Su-Kam Power Systems, CATL, Saft, Tesla, Okaya Power Group, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Grid Energy Storage Systems Market Strategic Shifts & Innovations
Cell chemistry evolution and regulatory disclosure mandates are restructuring competitive advantage around supply chain transparency and manufacturing scale rather than proprietary hardware differentiation.
Solid-state electrolyte research is advancing toward commercialization for high-voltage stationary applications. Grid-scale developers in Germany and Japan are piloting sulfide-based cells for six-to-eight hour discharge durations. This architecture is supplanting conventional liquid electrolyte designs in safety-critical installations where thermal runaway tolerance determines insurance premiums.
The EU's Battery Regulation enforcement through CE marking frameworks is mandating supply chain due diligence documentation. Industrial buyers now require carbon intensity certificates for cell production, forcing suppliers to reconfigure procurement from coal-heavy reduction facilities. Container system integrators serving member states are restructuring supplier qualification around recycled nickel and cobalt content thresholds.
Aggregators are bundling residential storage assets into virtual power plant configurations. Australian and Californian households with behind-the-meter batteries are selling frequency regulation services to wholesale markets through automated dispatch platforms. This procurement model shift is compressing payback periods and redirecting distributor focus from equipment margin to software-enabled revenue share arrangements.
Off-Grid Energy Storage Systems Market Segmentation
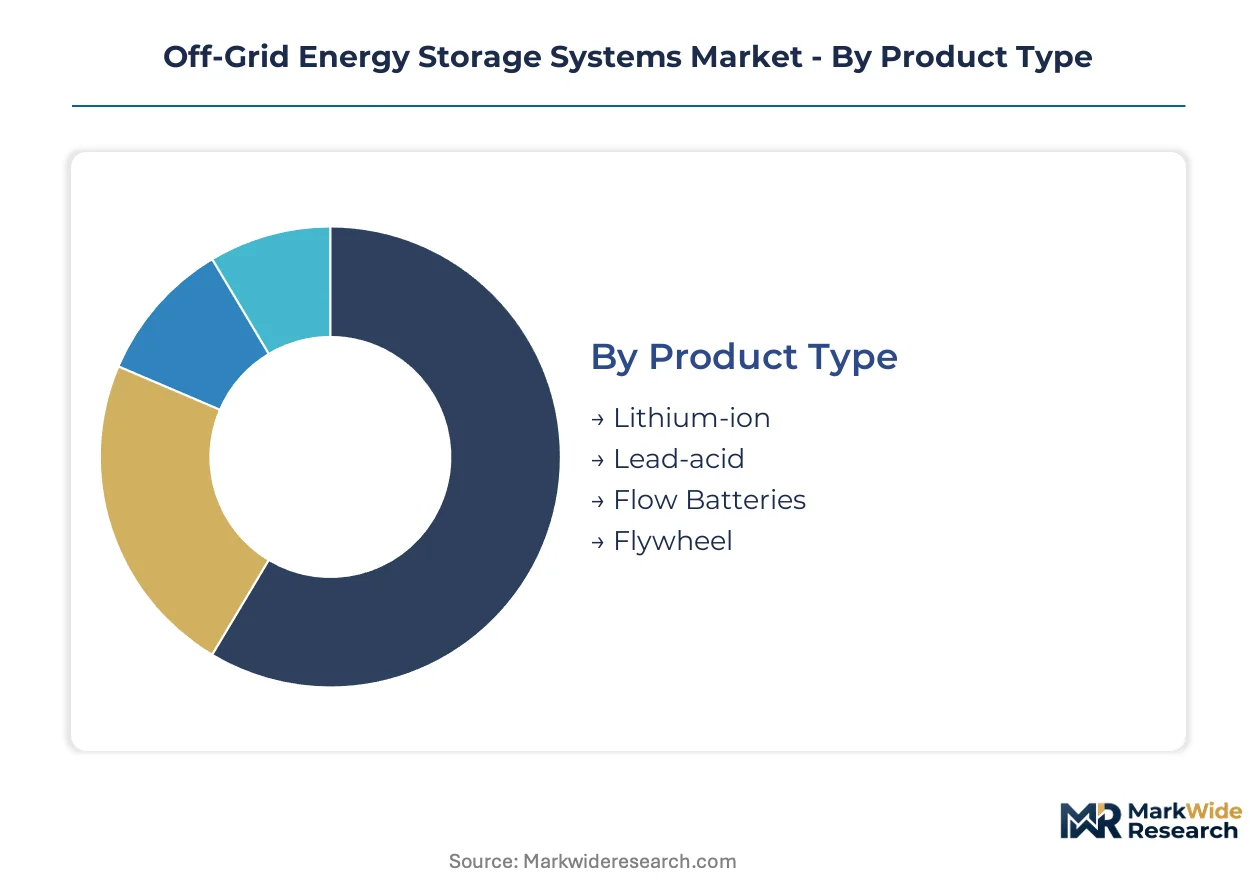
Segmentation in off-grid energy storage reveals how technology choices diverge between capital-constrained rural deployments and performance-critical industrial installations. Chemistry selection, voltage architecture, and cycle-life specifications map directly to financing availability and load profiles across unelectrified regions.
Product Type:
Lithium-ion and lead-acid systems serve predominantly domestic electrification programs across Sub-Saharan Africa and South Asia, while flow battery exports concentrate in European long-duration pilot projects and remote mining operations in Australia and Chile.
- Lithium-ion:These electrochemical systems utilize lithium iron phosphate or nickel-manganese-cobalt cathodes with energy densities between 150-250 Wh/kg. Demand concentrates in Indian state-level solar mini-grid tenders and Kenyan rural electrification programs where compact footprints justify premium pricing against diesel alternatives.
- Lead-acid:Flooded and valve-regulated lead-acid configurations persist where upfront capital constraints dominate lifecycle economics. Southeast Asian telecom tower operators in Indonesia and the Philippines continue retrofitting existing infrastructure with these systems due to established recycling networks and technician familiarity.
- Flow Batteries:Vanadium redox systems serve six-to-eight hour discharge applications in German grid-scale pilots and Japanese island microgrids where aqueous chemistry eliminates thermal runaway insurance penalties.
- Flywheel:Kinetic energy storage systems provide sub-second frequency regulation for remote industrial facilities in Western Australia and Canadian Arctic mining camps where extreme temperature cycling degrades electrochemical alternatives.
Lithium-ion holds the largest share; momentum sits with flow batteries as long-duration procurement shifts from pilot to commercial scale.
Application:
Residential and commercial deployments cluster around distributed solar generation in emerging economies, while telecommunications and remote location applications follow extractive industry capital expenditure cycles in frontier markets.
- Residential:Behind-the-meter battery systems paired with rooftop solar serve as primary power sources in Nigerian and Tanzanian households beyond grid extension timelines. PAYGO financing models from Nairobi-based distributors are accelerating adoption where traditional banking remains inaccessible.
- Commercial:Containerized storage integrated with C&I solar mini-grids powers agricultural processing facilities in Rajasthan and cold storage operations in Uttar Pradesh under India's tender-based procurement framework.
- Remote Locations:Standalone power systems for mining camps in Western Australia's Pilbara region and Chilean Atacama operations displace diesel generation through solar-battery hybrid architectures.
- Telecommunications:Tower backup power in Myanmar, Laos, and rural Brazil prioritizes lead-acid replacement cycles where site accessibility limits maintenance intervals and lithium-ion retrofit economics improve with falling cell costs.
Commercial applications hold the largest share; residential deployments are climbing the fastest as rural electrification mandates expand across Sub-Saharan Africa.
End User:
Household procurement dominates unit volumes through microfinance and government subsidy programs, while businesses and emergency services drive system sizing toward containerized configurations with higher voltage architectures.
- Households:Individual family units acquire 5-15 kWh wall-mounted systems through Kenya's Last Mile Connectivity Program and Nigeria's Rural Electrification Agency interventions, with lithium iron phosphate chemistry preferred for fire safety in dense settlements.
- Businesses:Commercial and industrial entities in India's MSME sector deploy 100-500 kWh containerized systems to buffer against diesel price volatility and grid unreliability in manufacturing clusters around Pune and Coimbatore.
- NGOs:Humanitarian organizations operating health clinics in South Sudan and refugee camps in Bangladesh prioritize modular lead-acid systems for field serviceability and local technician training capacity.
- Emergency Services:Disaster response agencies in Japan and California maintain mobile battery trailers for grid-islanded command centers and medical equipment support following seismic or wildfire events.
Households hold the largest share; business procurement is gaining share fastest as C&I solar mini-grid economics improve against diesel baseload.
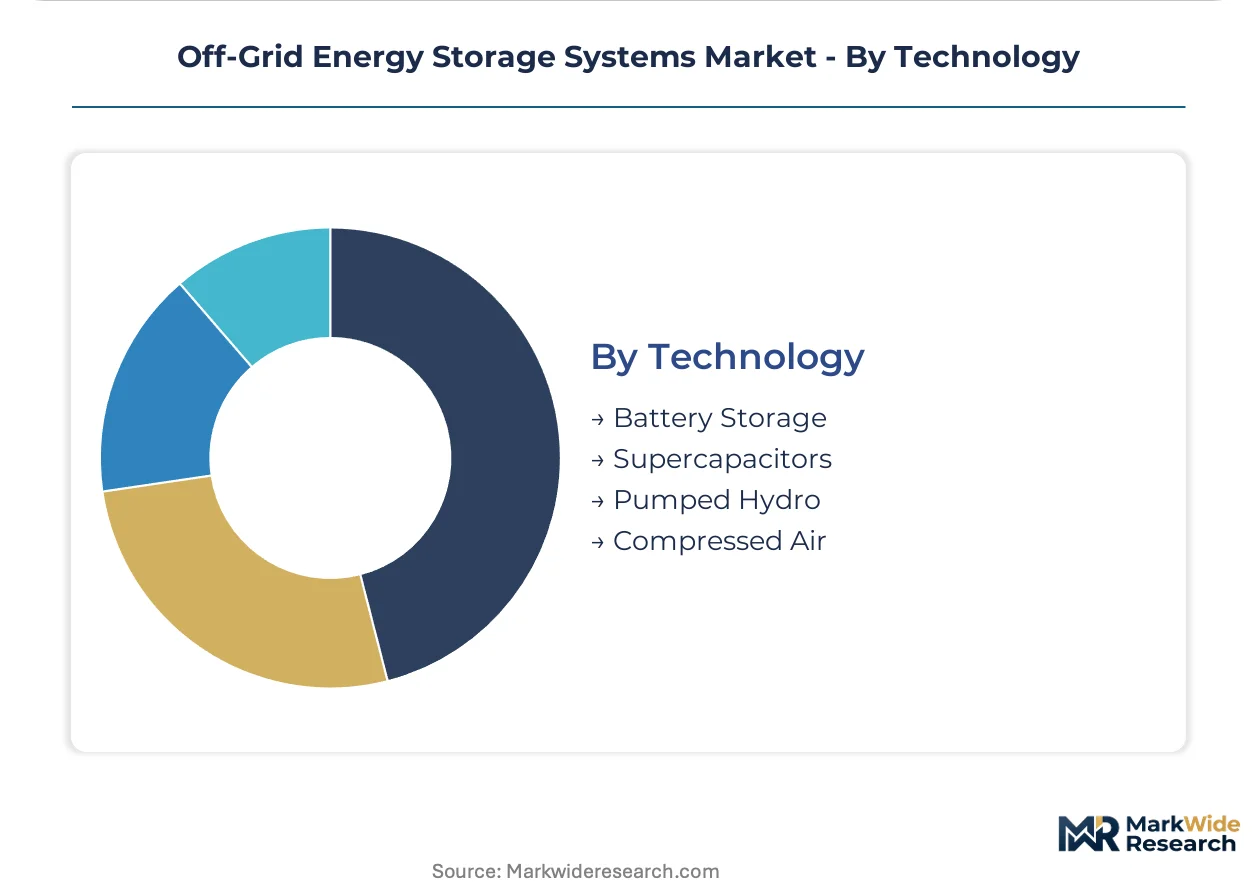
Technology:
Battery storage commands manufacturing scale and cost reduction trajectories, while mechanical and electrochemical alternatives occupy geographic niches where terrain or discharge duration requirements override capital cost sensitivity.
- Battery Storage:Electrochemical systems incorporating lithium-ion, lead-acid, or emerging sodium-ion chemistries represent the dominant technology pathway. Manufacturing concentration in China's Fujian and Jiangsu provinces is driving cell cost reductions that cascade through residential and commercial system pricing globally.
- Supercapacitors:Electric double-layer capacitors provide burst power for elevator regenerative braking and welding equipment in off-grid industrial facilities across South Africa's Eastern Cape where rapid charge-discharge cycles exceed battery cycle-life tolerance.
- Pumped Hydro:Gravity-based storage utilizing elevation differentials serves islanded grids in the Philippines and Scottish Highlands where favorable topography coincides with seasonal rainfall patterns and existing reservoir infrastructure.
- Compressed Air:Diabatic and adiabatic compressed air energy storage pilot projects in Germany's Lower Saxony and Utah's western desert exploit salt cavern geology for multi-day discharge duration beyond electrochemical cost competitiveness.
Battery storage holds the largest share; pumped hydro is expanding most quickly where favorable topography aligns with renewable resource development in Southeast Asian archipelago nations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing clusters in China's Fujian and Jiangsu provinces anchor supply-side capacity, while procurement demand fragments across electrification programs in India, Sub-Saharan Africa, and distributed solar markets in Australia and Germany.
India
State-level solar mini-grid tenders in Rajasthan and Uttar Pradesh are scaling commercial and industrial storage deployments. The Central Electricity Authority's technical standards for standalone power systems filter uncertified imports, creating protected market access. Manufacturing activity concentrates in Pune and Coimbatore where MSMEs deploy containerized systems against diesel price volatility.
Germany
Grid-scale developers pilot sulfide-based solid-state cells for six-to-eight hour discharge durations in safety-critical installations. The EU Battery Regulation enforces carbon footprint disclosure and recycled content thresholds through CE marking frameworks. Industrial buyers in Lower Saxony now require carbon intensity certificates for cell production, forcing supply chain reconfiguration.
United States
The EPA and FERC shape market access through stationary battery emissions guidelines and wholesale market participation rules. Nevada-based cell production anchors pricing power in residential configurations across North America. Virtual power plant aggregators in California bundle behind-the-meter assets into frequency regulation services.
Australia
Remote mining operations in Western Australia's Pilbara region displace diesel generation through solar-battery hybrid architectures. Kinetic energy storage systems provide sub-second frequency regulation for industrial facilities where extreme temperature cycling degrades electrochemical alternatives. Grid-scale procurement is shifting toward long-duration pilots in island microgrids.
Kenya
The Last Mile Connectivity Program accelerates household procurement of lithium-ion battery systems as primary power sources. Nairobi-based distributors deploy PAYGO financing models where traditional banking remains inaccessible. Rural electrification mandates are compressing payback periods for lithium iron phosphate chemistry in dense settlements.
Off-Grid Energy Storage Systems Market Key Industry Players
Concentration sits with diversified battery manufacturers and specialized system integrators. The vendor base spans three tiers: vertically integrated cell producers, container system assemblers, and regional distributors with financing partnerships. Two strategic archetypes dominate—backward-integrated chemistry specialists and software-enabled aggregators. Competitive moves center on supplier qualification restructuring and virtual power plant platform development.
Among Chinese manufacturers, BYD and CATL exemplify distinct archetypes. BYD occupies a position representing backward integration into cathode powder and cell assembly, securing margin control in commercial-scale configurations. CATL anchors the cylindrical and prismatic form factor supply for telecom backup applications. Tesla represents the software-enabled aggregator model, leveraging Nevada-based production to anchor pricing power across North American residential markets.
| Leading Market Players |
|---|
| Sonnen |
| BYD |
| EnerSys |
| Su-Kam Power Systems |
| CATL |
| Saft |
| Tesla |
| Okaya Power Group |
| LG Energy Solution |
| Others |
Cost & Logistics Intelligence
Lithium iron phosphate cathode chemistry displacing nickel-manganese-cobalt formulations simultaneously redraws procurement geography toward China's Fujian and Jiangsu manufacturing clusters and compresses cycle-life premiums into mid-market pricing tiers.
Pricing Analysis
The EU Battery Regulation dictates the pricing tier structure through mandatory carbon footprint disclosure and recycled content thresholds. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified systems with full supply chain documentation from uncertified imports. Price differentiation rests on certification grade and geographic delivery cost, with Indian state tender participants absorbing margin compression from BIS compliance investments. Rural electrification programs in Sub-Saharan Africa exhibit highest price sensitivity, while German grid-scale developers prioritize thermal runaway tolerance over unit economics.
Supply Chain Analysis
Inventory lead times for cathode powder and separator materials extend procurement cycles beyond six months for non-integrated assemblers. Manufacturing concentrates in China, South Korea, and Japan, with cell production drawing from Chilean lithium carbonate and Indonesian nickel laterite. Single-source vulnerability in East Asian separator fabrication creates tariff exposure for US-bound container systems. Distribution runs through regional system integrators with CEA certification in India and PAYGO financing partnerships in Kenya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with BIS and CEA certification timelines creating switching costs that lock out uncertified competitors.
For Market Incumbents: Compound certification advantages by accelerating CEA technical standards compliance ahead of India's expanding state tender pipeline. Deepen backward integration into cathode powder production to offset lithium carbonate volatility threatening margin stability in commercial container configurations. Lock in channel control through exclusive PAYGO financing partnerships with Nairobi-based distributors before emerging Chinese assemblers secure rural electrification mandates. For New Entrants and Emerging Players: After-sales firmware maintenance gaps in legacy lead-acid telecom installations across Myanmar and Laos present immediate service-layer entry points. Target Southeast Asian tower operator retrofit cycles with lithium-ion replacement economics bundled with technician retraining programs. Penetrate through software-enabled virtual power plant aggregation platforms where Australian and Californian residential assets remain underserved by incumbent hardware vendors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed container system integrators holding CEA certification but lacking cell-level backward integration. Five-to-ten year viability hinges on supplier qualification restructuring around EU Battery Regulation recycled content thresholds. Watch for carbon border adjustment mechanism enforcement as the inflection signal triggering distressed consolidation among import-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | Captures margin control for BYD and CATL against lithium carbonate spot volatility. |
| CEA Technical Standards Certification | Filters uncertified Chinese imports from Rajasthan solar mini-grid tenders. |
| Virtual Power Plant Platform Development | Enables Tesla's Nevada-based residential assets to sell FERC-regulated frequency services. |
| Recycled Content Supply Chain Restructuring | Aligns container integrators with EU Battery Regulation nickel and cobalt thresholds. |
| PAYGO Financing Channel Partnerships | Locks Nairobi distributors into Kenyan Last Mile Connectivity Program procurement flows. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and PAYGO financing distributors; and secondary validation against EIA data, IEA reports, FERC filings, and India's CEA tender databases. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic drivers across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by chemistry type, application scale, voltage architecture, and regulatory compliance tier. CAGRs derived from unit shipment trajectories and average selling price erosion curves, incorporating lithium iron phosphate cell cost reduction rates and rural electrification program budget allocations as energy-specific forecast inputs.
Underlying assumptions cover continued lithium carbonate supply expansion and stable Indian state tender issuance velocity, with deviation risk concentrated in EU Battery Regulation enforcement timing and carbon border adjustment mechanism scope expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Supercapacitor Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Power Bank Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
South America Energy Storage Market