
 Supercapacitor Market | 2026-2036
Supercapacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Supercapacitor Market Analysis
A shortage of electrochemists with graphene-carbon hybrid expertise is redrawing competitive boundaries in the supercapacitor sector. Skeleton Technologies leverages its Estonian-German engineering base to dominate high-power density modules for heavy transport. Panasonic Holdings Corp. sustains manufacturing scale across Japanese plants, anchoring consumer electronics supply chains. LS Mtron competes through vertical integration into activated carbon precursors, controlling raw material quality for Korean automotive clients.
Supercapacitors store energy via electrostatic charge separation at electrode-electrolyte interfaces, achieving power densities exceeding 10 kW/kg with cycle lives surpassing one million charge-discharge events. Electrochemical double-layer variants lead commercial shipments due to mature carbon electrode manufacturing, while hybrid architectures are capturing R&D investment for their superior energy density bridging batteries and conventional capacitors. Automotive end users concentrate procurement around regenerative braking and start-stop systems, whereas renewable energy applications in grid stabilization are expanding fastest despite smaller current volumes.
The EU Green Deal and F-Gas Regulation are mandating fluorinated electrolyte phase-outs, forcing reformulation toward ionic liquid and aqueous alternatives. China's MIIT enforces GB standards for energy storage device safety, restricting market access for uncertified imports. The US EPA and NHTSA coordinate on heavy-duty vehicle electrification rules that validate supercapacitor-assisted hybrid powertrains. Stakeholders must monitor electrolyte chemistry transitions and certification harmonization across jurisdictions to secure supply contracts in transportation and grid storage.
Market Dynamics
Electrolyte chemistry transitions are forcing manufacturers to rebuild supply chains around fluorinated-compound alternatives while maintaining performance benchmarks for automotive and grid clients.
Growth Catalysts
- EU F-Gas Regulation phase-outs:Mandates eliminating fluorinated electrolytes are accelerating ionic liquid and aqueous formulation R&D, creating first-mover advantages for compliant suppliers.
- Heavy transport electrification:NHTSA-coordinated rules validating supercapacitor-assisted hybrid powertrains are expanding addressable demand in US trucking and bus fleets.
- Graphene-carbon hybrid electrode advances:Breakthroughs in Estonia-Germany engineering corridors are extending energy density into battery-competitive ranges for regenerative braking systems.
Market Restraints
- Activated carbon precursor concentration:Korean and Japanese suppliers dominate high-purity coconut shell and pitch sources, exposing buyers to single-source risk during climate-driven harvest disruptions.
- Electrochemist talent scarcity:The specialized workforce capable of optimizing electrode-electrolyte interfaces remains concentrated in fewer than twelve university-industry clusters worldwide.
- Lithium-ion cost compression:Battery pack economics below $100/kWh in Chinese manufacturing are narrowing the total-cost-of-ownership window for supercapacitor-only solutions.
Strategic Opportunities
- Grid stabilization services:Frequency regulation contracts with independent system operators in Texas and California are creating recurring revenue streams for modular supercapacitor farms.
- India PLI scheme eligibility:Domestic cell manufacturing incentives are opening local assembly opportunities for imported electrode-electrolyte stacks.
- Aqueous electrolyte convergence:Water-based systems paired with solid-state separators are unlocking intrinsically safer designs for urban air mobility and subsea applications.
Industry Challenges
- GB standard certification timelines:China's MIIT safety testing protocols for energy storage devices extend market entry by 14-18 months for uncertified imports.
- Legacy powertrain integration:Retrofitting supercapacitor modules into existing 48V mild-hybrid architectures requires custom DC-DC converter engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supercapacitor Market |
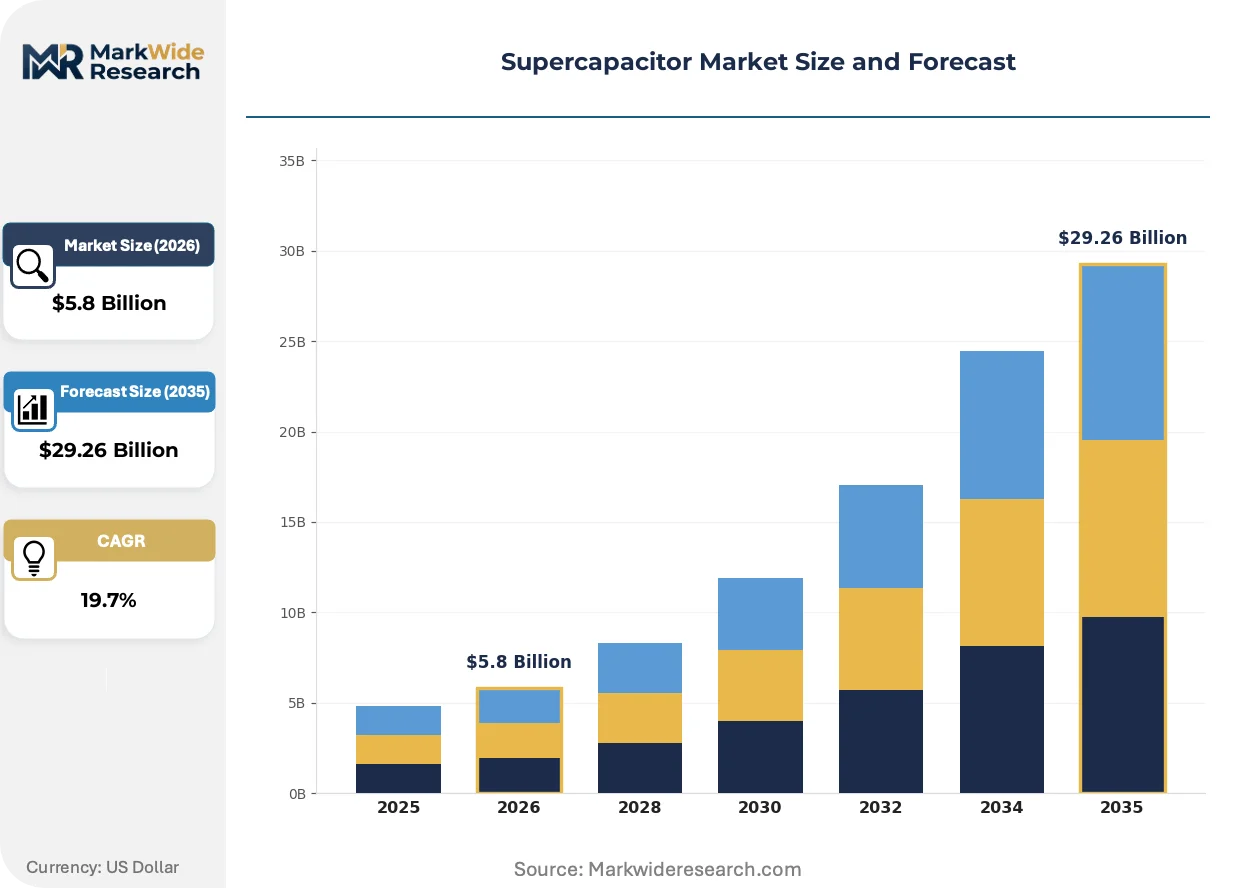
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $29.26 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Hybrid, Pseudocapacitor, Double-Layer End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Technology: Electrolyte, Carbon-Based, Metal Oxide, Conductive Polymer Application: Energy Storage, Power Backup, Regenerative Braking, Load Leveling |
| Companies Covered | Eaton Corporation, Panasonic Holdings Corp., Maxwell Technologies, Kyocera Corporation, LS Mtron, Skeleton Technologies, CAP-XX, Ioxus, Nippon Chemi-Con Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supercapacitor Market Emerging Trajectories
Electrode material science and regulatory chemistry mandates are converging to reshape competitive positioning around energy density and environmental compliance rather than pure power metrics.
Hybrid supercapacitor architectures combining battery-type electrodes with double-layer capacitors are fragmenting the traditional performance trade-off between power density and cycle life. German automotive suppliers are piloting these systems for start-stop applications demanding both cold-crank reliability and extended discharge duration. The technology is fragmenting procurement patterns as buyers abandon single-technology sourcing in favor of hybrid stacks.
REACH and RoHS amendments targeting persistent organic pollutants in electrolyte formulations are compelling solvent suppliers to validate biodegradable alternatives. Industrial consequence includes reformulation costs exceeding $2 million per certified chemistry line. Korean battery component manufacturers are responding fastest, integrating aqueous electrolyte production into existing activated carbon precursor facilities.
Buyer concentration around East Asian manufacturing clusters is compressing supplier qualification cycles from 24 months to 14 months. Tier-1 automotive procurement teams in Seoul and Ulsan are consolidating vendor panels to three approved sources per component category. This pattern is most visible in South Korea's heavy equipment sector, where Hyundai and Doosan are synchronizing supercapacitor specifications across excavator and forklift product lines.
Supercapacitor Market Segmentation
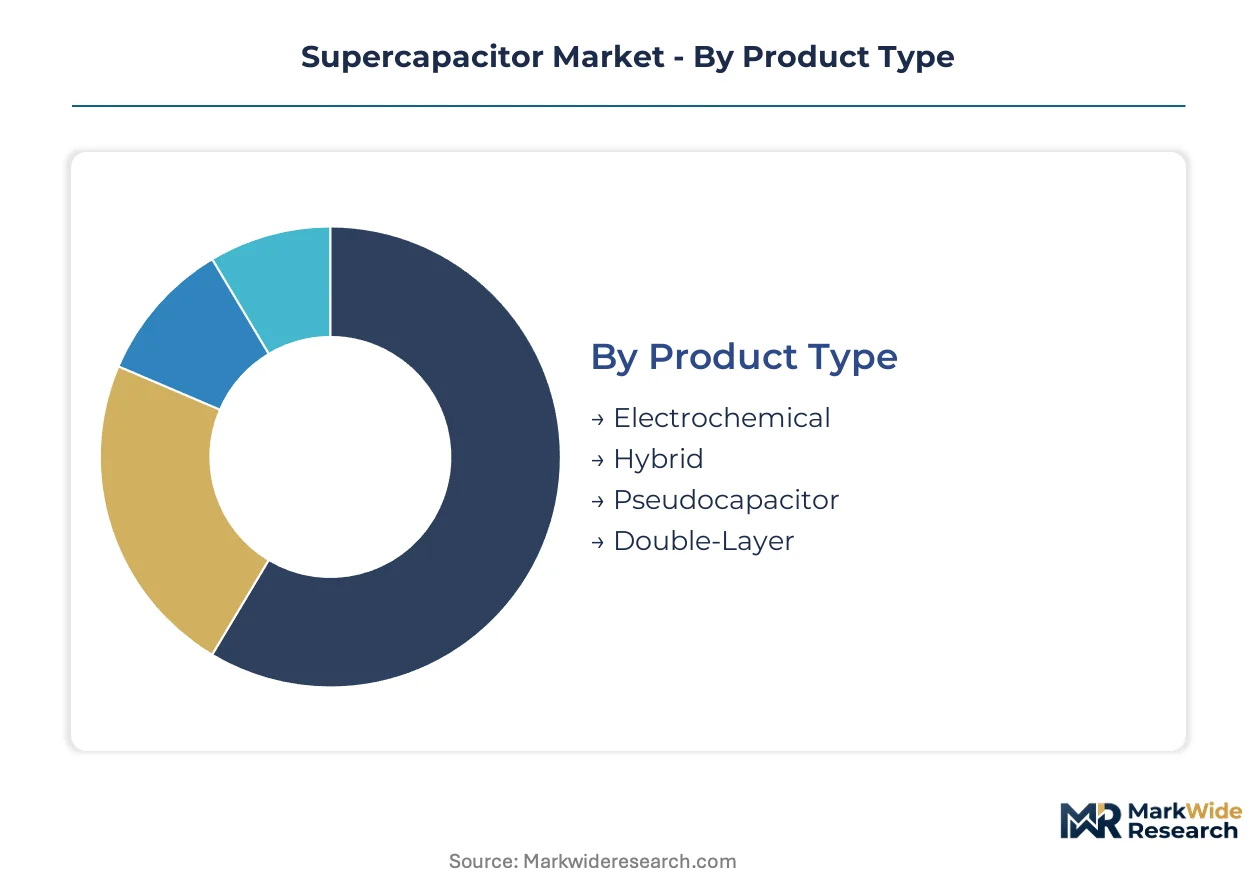
Supercapacitor procurement patterns fragment sharply across electrode chemistry and end-use specifications, with automotive qualification cycles and grid-storage duty cycles imposing incompatible performance benchmarks on suppliers.
Product Type:
Double-layer variants face the most acute substitution pressure from hybrid architectures as buyers demand battery-competitive energy density without sacrificing cycle life.
- Electrochemical:Conventional double-layer construction using activated carbon electrodes dominates heavy transport start-stop systems. German and Korean automotive OEMs specify these modules for 48V mild-hybrid buses where one million-plus cycle tolerance outweighs energy density limitations.
- Hybrid:Battery-type electrodes paired with capacitive layers are capturing regenerative braking contracts previously lost to lithium-ion. Skeleton Technologies and LS Mtron are scaling production for electric excavators and port cranes requiring both power bursts and sustained discharge.
- Pseudocapacitor:Faradaic charge transfer mechanisms using metal oxide electrodes serve niche military and aerospace applications demanding extreme temperature tolerance.
- Double-Layer:Mature carbon-electrode manufacturing anchors consumer electronics supply chains, with Panasonic sustaining volume production for camera flash and backup power modules.
Double-layer construction anchors the volume base while hybrid architectures gain share at the steepest rate.
End User:
Cost tier stratification separates qualification-intensive automotive procurement from price-sensitive consumer electronics sourcing.
- Automotive:OEMs in Germany, China, and South Korea specify modules for regenerative braking and cold-crank assist, with NHTSA and EU Green Deal rules validating supercapacitor-assisted hybrid powertrains. Skeleton Technologies dominates heavy truck applications through its Estonian-German engineering base.
- Consumer Electronics:Backup power for solid-state drives and camera flashes sustains Japanese manufacturing scale, though lithium-ion cost compression below $100/kWh in Chinese plants is narrowing the addressable window.
- Industrial:Forklift and crane manufacturers in Seoul and Ulsan clusters are synchronizing specifications across product lines, compressing supplier qualification cycles from 24 months to 14 months.
- Renewable Energy:Grid stabilization contracts with ERCOT and CAISO in Texas and California are creating recurring revenue streams for modular supercapacitor farms, though current volumes trail automotive procurement.
Automotive end users concentrate the largest contract values while renewable energy applications expand most quickly through frequency regulation services.
Technology:
Supply concentration around East Asian activated carbon precursor facilities is forcing electrode chemistry choices before electrolyte formulation decisions.
- Electrolyte:EU F-Gas Regulation phase-outs are mandating fluorinated compound elimination, accelerating ionic liquid and aqueous formulation R&D with reformulation costs exceeding $2 million per certified chemistry line.
- Carbon-Based:Korean and Japanese suppliers dominate high-purity coconut shell and pitch sources, exposing buyers to single-source risk during climate-driven harvest disruptions.
- Metal Oxide:Ruthenium and manganese dioxide electrodes serve pseudocapacitive applications where faradaic reactions extend energy density at the cost of cycle life degradation.
- Conductive Polymer:Polyaniline and polythiophene variants remain experimental, with limited commercial traction outside academic-industry partnerships.
Carbon-based electrodes anchor manufacturing scale while electrolyte chemistry transitions absorb the steepest R&D investment.
Application:
Maturity gradients separate established power backup deployments from emerging load leveling contracts in grid modernization programs.
- Energy Storage:Grid-scale installations paired with solar and wind farms require 15-20 year operational lifespans, favoring supercapacitor modules over battery alternatives in high-cycle-duty environments.
- Power Backup:Uninterruptible power supplies for data centers and telecommunications sustain steady demand for double-layer modules with rapid response times under 100 milliseconds.
- Regenerative Braking:Kinetic energy recovery in electric buses and rail systems captures the steepest procurement growth, with China's MIIT GB standards and EU electrification mandates tightening efficiency requirements.
- Load Leveling:Peak shaving and frequency regulation services with independent system operators are fragmenting traditional utility procurement patterns toward modular, distributed supercapacitor farms.
Power backup anchors installed base stability while regenerative braking commands the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China deploy supercapacitors primarily for heavy transport electrification, while South Korea concentrates procurement around industrial machinery clusters. Japan sustains consumer electronics demand. The United States is expanding grid stabilization contracts.
Germany
Automotive OEMs in Stuttgart and Munich specify supercapacitor modules for 48V mild-hybrid buses and heavy trucks. The EU Green Deal and F-Gas Regulation mandate fluorinated electrolyte phase-outs, accelerating ionic liquid formulation R&D. The Estonian-German engineering corridor around Dresden anchors Skeleton Technologies' high-power density production for regenerative braking systems.
China
Domestic manufacturers scale procurement for electric bus kinetic energy recovery and port crane electrification. MIIT enforces GB standards for energy storage device safety, restricting market access for uncertified imports. Manufacturing clusters around Shanghai and Shenzhen integrate supercapacitor-assisted hybrid powertrains under the country's dual carbon goals.
South Korea
Hyundai and Doosan synchronize supercapacitor specifications across excavator and forklift product lines in Seoul and Ulsan. The national industrial policy supports battery component hub development through targeted infrastructure investment. LS Mtron controls activated carbon precursor quality from domestic facilities, compressing supplier qualification cycles to fourteen months.
Japan
Panasonic Holdings Corp. sustains volume production for camera flash modules and solid-state drive backup power. METI coordinates standards alignment with IEC frameworks for energy storage device interoperability. Manufacturing scale concentrates in Osaka and Kyoto prefectures, anchoring consumer electronics supply chains against lithium-ion cost compression.
United States
Independent system operators in Texas and California award frequency regulation contracts to modular supercapacitor farms. NHTSA coordinates with EPA on heavy-duty vehicle electrification rules validating hybrid powertrain configurations. The ERCOT and CAISO grid markets create recurring revenue streams for energy storage developers despite smaller current volumes than automotive procurement.
Supercapacitor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with Korean and Japanese manufacturers controlling activated carbon precursor supply while European engineering houses dominate high-power density module design. The market structure reflects backward integration into raw material refining alongside forward integration into automotive qualification programs. Two archetypes prevail: vertically integrated material suppliers and design-focused system integrators. Capacity expansion and electrolyte chemistry reformulation represent the dominant competitive moves as F-Gas Regulation deadlines approach.
Among the integrated material tier, LS Mtron exemplifies captive supply chain control through in-house activated carbon production. Skeleton Technologies occupies a position within the European engineering specialist archetype, leveraging cross-border technical collaboration. Panasonic Holdings Corp. anchors the consumer electronics scale tier, representing sustained manufacturing volume in mature application segments. These three companies illustrate the geographic and strategic fragmentation shaping procurement decisions across automotive and industrial end uses.
| Leading Market Players |
|---|
| Eaton Corporation |
| Panasonic Holdings Corp. |
| Maxwell Technologies |
| Kyocera Corporation |
| LS Mtron |
| Skeleton Technologies |
| CAP-XX |
| Ioxus |
| Nippon Chemi-Con Corporation |
| Others |
Supply Flow & Price Mechanics
Fourteen-month supplier qualification cycles in Seoul and Ulsan clusters concentrate pricing power among Korean and Japanese activated carbon precursor producers, compressing margins for electrode manufacturers while amplifying cost pass-through leverage for backward-integrated incumbents.
Pricing Analysis
Long-term offtake contracts dominate automotive procurement, with German and Korean OEMs locking in eighteen-to-twenty-four month supply agreements for regenerative braking modules. Price differentiation hinges on GB standard certification tier and volume scale, with uncertified imports facing fourteen-month entry delays that erode project economics. Cost compression in Chinese lithium-ion manufacturing below the hundred-dollar-per-kilowatt-hour threshold is intensifying substitution pressure on double-layer supercapacitor-only solutions. Consumer electronics buyers exhibit the highest price sensitivity, whereas grid stabilization operators prioritize cycle-life reliability over unit cost.
Supply Chain Analysis
Indonesia and the Philippines anchor high-purity coconut shell activated carbon production, while South Korea and Japan control pitch-based synthetic precursor refining. Electrode manufacturing draws from these feedstocks alongside ionic liquid electrolyte formulations mandated by EU F-Gas Regulation phase-outs. Single-source vulnerability concentrates in climate-exposed tropical harvest regions where typhoon disruption risks cascade through carbon precursor availability. Distribution runs through Tier 1 automotive vendor panels consolidated to three approved sources per component category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercapacitor adoption sits in early-cycle expansion as heavy transport electrification rules validate hybrid powertrain configurations, creating installed-base foundations before grid-scale frequency regulation contracts mature into volume procurement.
For Market Incumbents: Shield module margins by deepening backward integration into activated carbon precursor production, mirroring LS Mtron's captive supply model, while accelerating aqueous electrolyte certification ahead of EU F-Gas deadlines to capture first-mover pricing premiums. For New Entrants and Emerging Players: Differentiate on aqueous electrolyte safety profiles for urban air mobility and subsea applications where lithium-ion thermal runaway risks exclude battery alternatives, targeting India's PLI scheme eligibility for domestic cell assembly partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry consolidation play because electrode-electrolyte interface optimization requires scarce electrochemist talent concentrated in fewer than twelve university-industry clusters worldwide; watch for MIIT GB standard harmonization with IEC frameworks as the signal that Chinese market access barriers are lowering for certified imports.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Electrolyte Certification | EU F-Gas Regulation compliance unlocks automotive supply contracts ahead of fluorinated compound phase-outs. |
| Activated Carbon Precursor Integration | Captive coconut shell and pitch refining insulates margin structures from climate-driven harvest volatility. |
| Grid Stabilization Farm Deployment | ERCOT and CAISO frequency regulation contracts create recurring revenue streams independent of automotive cycles. |
| Hybrid Architecture Scale-Up | Battery-type electrode pairing extends energy density into regenerative braking applications previously lost to lithium-ion. |
| India PLI Scheme Localization | Domestic cell manufacturing incentives open assembly opportunities for imported electrode-electrolyte stacks. |
Methodological Framework
A standing panel of supercapacitor module procurement managers, activated carbon precursor plant engineers, automotive Tier 1 supplier quality directors, and grid storage project developers provided ongoing calibration across the research window. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from customs trade databases, MIIT GB standard filings, EU F-Gas Regulation implementation notices, and SEC 10-K disclosures from listed energy storage manufacturers. Bottom-up electrode and electrolyte volume estimates triangulated against top-down automotive and grid installation forecasts.
Consistency checks validated volume and value outputs against IEA energy storage deployment trackers and regional vehicle electrification production databases across the modeling period. Segmentation modeling incorporated electrode chemistry type, end-use application duty cycle, certification tier, and regional regulatory framework. CAGRs derived from logistic adoption curves fitted to historical procurement patterns and projected electrification mandate compliance timelines, with electrolyte chemistry transition assumptions and automotive qualification cycle compression as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, Chinese dual carbon goal continuity, or lithium-ion cost compression stabilization would require recalibration. Forecasts reflect assumptions regarding F-Gas Regulation phase-out adherence, MIIT certification timeline consistency, and electrochemist talent pool expansion. Recalibration cycles align with material shifts in heavy transport electrification rulemakings and grid operator procurement policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Power Bank Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Marine Energy Storage System Market
Energy Storage
Energy Storage Software Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market