
 North America NMC Battery Energy Storage System (BESS) Market | 2026-2036
North America NMC Battery Energy Storage System (BESS) Market Size, Share, and Industry Trends Forecast 2026-2036
North America NMC Battery Energy Storage System (BESS) Market Insights
Multi-source cathode procurement is realigning supply chain resilience across the North America NMC BESS value chain. Tesla Inc. leverages its Nevada cell-to-pack manufacturing to control upstream nickel-manganese-cobalt throughput. LG Energy Solution Ltd. anchors its Michigan operations with dedicated NMC pouch cell lines for utility-scale integrators. Fluence Energy Inc. competes through software-defined energy storage platforms that optimize NMC cycle life across variable dispatch profiles.
A nickel-manganese-cobalt battery energy storage system combines lithium-ion cells with layered oxide cathodes in ratios typically emphasizing nickel content for energy density; these systems buffer electricity across temporal mismatches between renewable generation and grid load. Utility-scale systems dominate installed capacity, while commercial systems capture expanding margin pools behind-the-meter for C&I peak shaving. Frequency regulation applications lead in revenue stack complexity, though load shifting is accelerating fastest as time-of-use rate structures proliferate across deregulated North American markets.
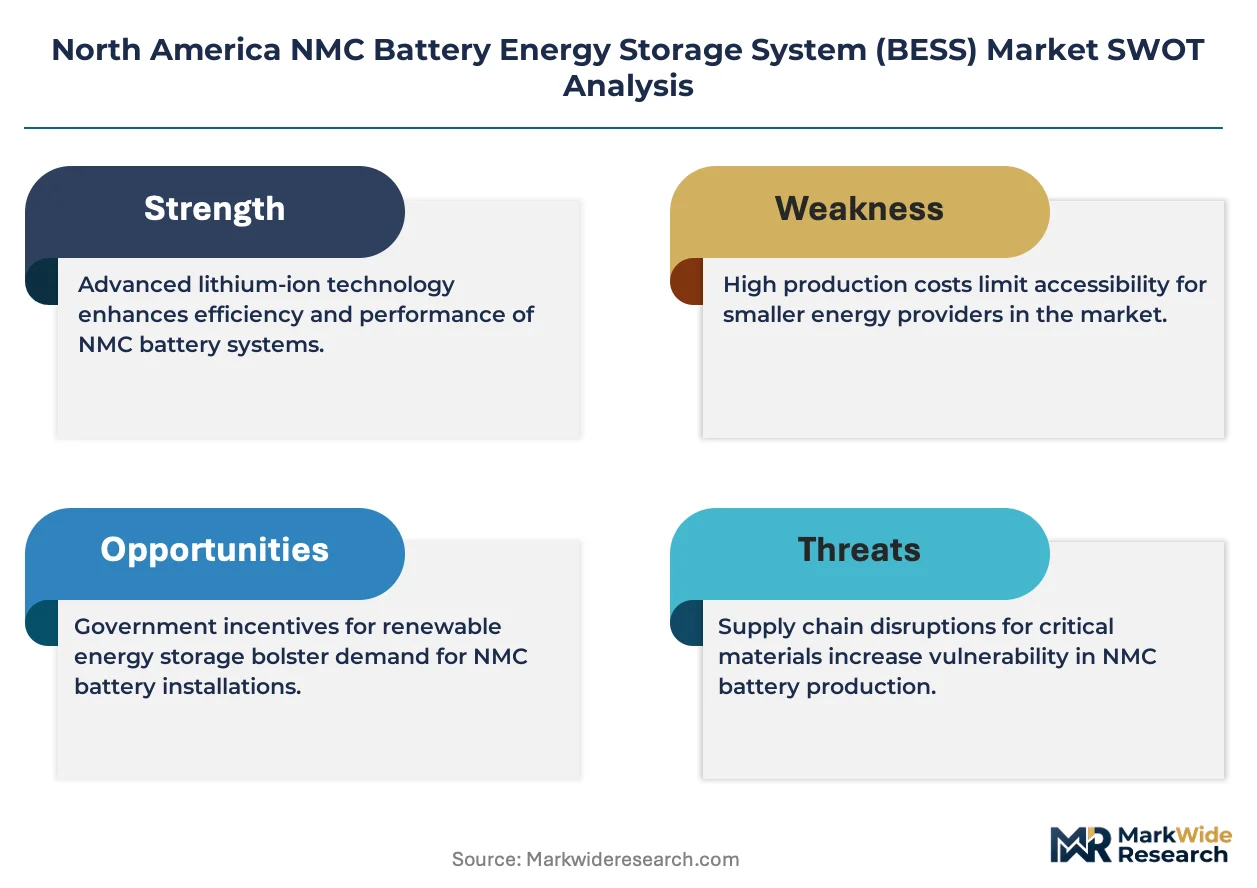
FERC Order 2222 enables distributed NMC BESS aggregation into wholesale markets, while NERC CIP standards govern cybersecurity for grid-connected installations. The IRA's standalone storage ITC and domestic content bonus credits reshape developer capital stacks, forcing equipment sourcing decisions toward qualifying cell and module assembly. Stakeholders must monitor interconnection queue reform timelines and state-level storage mandates to calibrate deployment pipelines against evolving dispatch revenue certainty.
Market Dynamics
The Inflation Reduction Act's standalone storage investment tax credit has fundamentally altered developer capital allocation, compressing payback periods and redirecting procurement toward domestic cell assembly.
Growth Catalysts
- ITC Bonus Credits:The IRA's domestic content bonus accelerates module sourcing from Michigan and Nevada cell plants, tightening supply chain loops within US borders.
- ERCOT Interconnection Reform:Texas grid operators are fast-tracking utility-scale queue positions for NMC BESS projects that provide ancillary services during peak demand events.
- CAISO Resource Adequacy Mandates:California's procurement requirements for clean firm capacity are pulling four-hour duration systems into long-term contracting structures.
Market Restraints
- Cobalt Price Volatility:DRC supply concentration and LME pricing swings compress developer margins on fixed-price EPC contracts.
- Interconnection Delays:CAISO and ERCOT queue backlogs extend project commissioning timelines by 18-36 months regardless of equipment readiness.
- LFP Substitution:Iron-phosphate chemistry is capturing shorter-duration segments where energy density premiums do not justify NMC cost structures.
Strategic Opportunities
- Mexico Manufacturing:Nearshoring cell and module assembly to Baja California and Nuevo León captures USMCA content rules for bonus credit eligibility.
- Hybrid Solar-Storage:Co-located DC-coupled configurations at Texas utility sites reduce balance-of-system costs and shared interconnection expenses.
- FERC Order 2222 Aggregation:Distributed BESS pooling into wholesale markets opens behind-the-meter revenue stacking for commercial C&I installations.
Industry Challenges
- NERC CIP Compliance:Grid-connected assets face escalating cybersecurity audit costs and documentation burdens for medium-impact bulk electric system facilities.
- Thermal Runaway Mitigation:NFPA 855 fire codes mandate gas detection and suppression systems that add capex and footprint constraints to dense containerized deployments.
- Recycling Infrastructure:End-of-life cathode recovery lacks scaled North American capacity, creating liability exposure for developers under extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America NMC Battery Energy Storage System (BESS) Market |
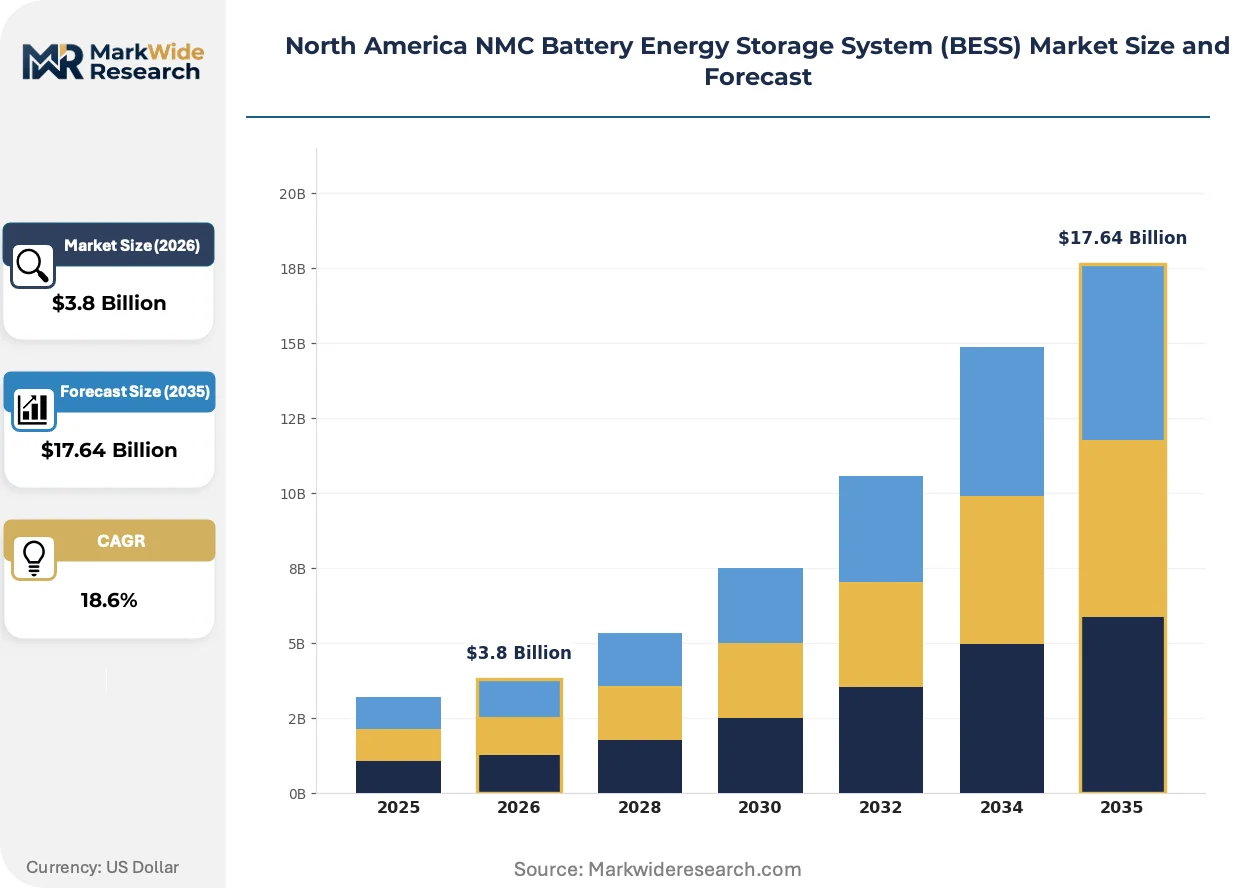
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Systems, Commercial Systems, Industrial Systems, Utility-scale Systems Application: Peak Shaving, Load Shifting, Frequency Regulation, Backup Power Installation: On-grid, Off-grid, Hybrid, Containerized End User: Residential Clients, Commercial Enterprises, Industrial Manufacturers, Power Utilities |
| Companies Covered | Tesla Inc., Fluence Energy Inc., LG Energy Solution Ltd., Hitachi Energy Ltd., Sungrow Power Supply Co., Ltd., Samsung SDI Co., Ltd., Panasonic Holdings Corp, AES Corp, Contemporary Amperex Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America NMC Battery Energy Storage System (BESS) Market Trends and Innovations
Technology convergence and procurement model evolution are compressing traditional equipment supply hierarchies while software-defined architectures capture margin from hardware commoditization.
High-nickel NMC 811 cathode formulations are expanding into utility-scale BESS configurations previously dominated by NMC 622 blends. Developers in ERCOT territories are specifying these chemistries for four-hour duration systems where energy density reduces land and civil works costs. The shift is expanding into project finance structures that previously discounted unproven cycle life performance.
FERC Order 841 implementation across US ISO territories is mandating storage participation in wholesale energy, capacity, and ancillary service markets. Grid operators must revise tariff structures to accommodate battery dispatch characteristics, forcing software upgrades and metering investments. Texas and California installations face the steepest compliance curves due to market complexity and existing legacy settlement systems.
Power purchase agreement structures are unbundling hardware ownership from operational performance guarantees. Independent power producers now contract energy throughput commitments rather than equipment capex, transferring degradation risk to integrators. This model concentrates in ERCOT and PJM territories where merchant revenue exposure justifies operational flexibility premiums over asset ownership.
North America NMC Battery Energy Storage System (BESS) Market Segmentation
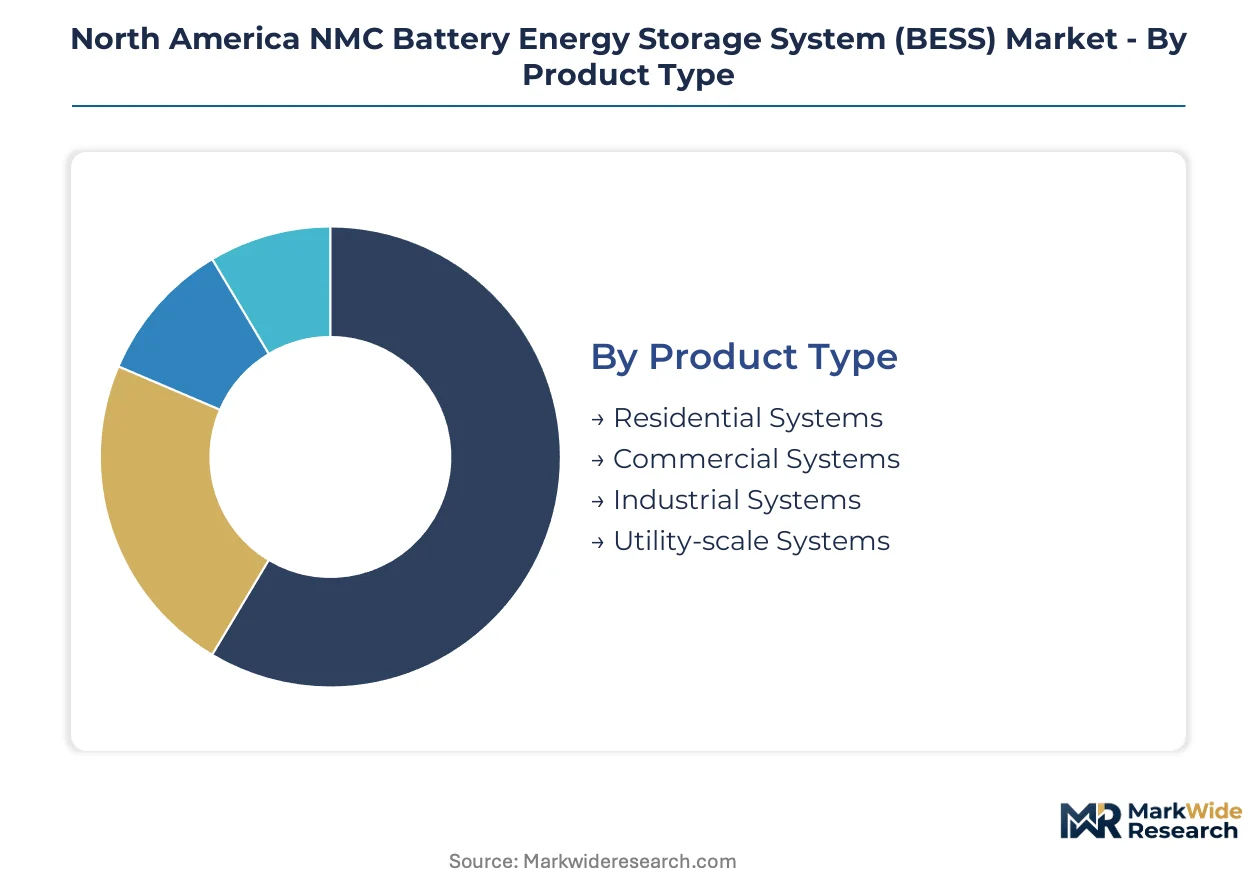
NMC BESS deployment patterns diverge sharply across power ratings and grid connection types. Segmentation reveals how cathode chemistry economics align with duration requirements and revenue stacking strategies across Texas and California territories.
Product Type:
Utility-scale systems command volume leadership while commercial installations capture premium margin pools through behind-the-meter flexibility services.
- Utility-scale Systems:Containerized megawatt-hour configurations dominate ERCOT and CAISO interconnection queues. Texas developers specify four-hour duration NMC 811 racks for ancillary service revenue streams. California procurement mandates under Resource Adequacy rules pull these systems into ten-plus year contracting structures.
- Commercial Systems:C&I peak shaving applications concentrate in deregulated markets with volatile demand charges. Installations behind retail meters in PJM and ERCOT territories stack time-of-use arbitrage with demand response payments. The IRA's standalone storage ITC compresses payback periods for 500kWh-2MWh deployments.
- Industrial Systems:Manufacturing facilities with high power quality requirements deploy NMC buffers for voltage support and outage ride-through.
- Residential Systems:Single-family installations with solar coupling remain a niche segment given NMC cost premiums against LFP alternatives.
Mature deployment sits with utility-scale systems. Newer deployment is concentrated in commercial systems.
Application:
Revenue complexity separates high-margin dispatch strategies from commodity energy arbitrage plays.
- Frequency Regulation:Fast-responding NMC assets capture ancillary service premiums in ISO markets with mileage-based compensation. PJM's RegD signal and ERCOT's ECRS product reward sub-second ramp rates that favor high-power battery configurations. These applications stress cycle life most aggressively.
- Load Shifting:Time-of-use rate arbitrage is expanding most quickly across territories with steep evening peak pricing. California's duck curve dynamics and Texas's real-time price volatility create favorable spread economics for four-hour duration systems. Developer offtake agreements increasingly structure around energy throughput rather than capacity payments.
- Peak Shaving:Demand charge management for C&I customers reduces utility bills through targeted discharge during ratchet-setting intervals.
- Backup Power:Outage protection applications prioritize reliability over cycling economics in hurricane-exposed Gulf Coast and wildfire-prone California territories.
Frequency regulation anchors established revenue stacks. Load shifting is climbing the fastest as rate structures evolve.
Installation:
Grid connection architecture determines balance-of-system costs and regulatory compliance burdens.
- On-grid:Direct interconnection to distribution or transmission networks subjects assets to NERC CIP cybersecurity standards and FERC Order 841 market participation rules. ERCOT and CAISO queue positions command development premiums given interconnection scarcity. These installations face the steepest compliance curves for bulk electric system classification.
- Containerized:Factory-integrated skid and enclosure designs compress field installation timelines for utility-scale developers. Pre-commissioned systems from Nevada and Michigan assembly plants reduce on-site labor and permit risk. The format dominates Texas utility procurement for rapid deployment against interconnection deadlines.
- Hybrid:DC-coupled solar-plus-storage configurations share inverters and interconnection infrastructure to reduce capex.
- Off-grid:Islanded microgrids serve remote industrial loads and critical facilities outside distribution network reach.
On-grid deployment holds mature market share. Containerized formats are gaining share fastest through procurement standardization.
End User:
Customer sophistication determines contracting structures and operational control preferences.
- Power Utilities:Investor-owned and municipal utilities in California and Texas procure NMC BESS through competitive solicitation for Resource Adequacy and transmission deferral. Long-term ownership models prevail, though some Texas utilities experiment with tolling agreements that transfer merchant risk to independent power producers.
- Commercial Enterprises:Retail, data center, and logistics operators deploy behind-the-meter systems to manage demand charges and sustain operations during grid disturbances. Third-party ownership through power purchase agreements dominates given balance sheet constraints and operational risk aversion.
- Industrial Manufacturers:Process industries with continuous loads value power quality and backup duration over cycling economics.
- Residential Clients:Early adopters with solar-plus-storage preferences drive limited volume in premium housing markets.
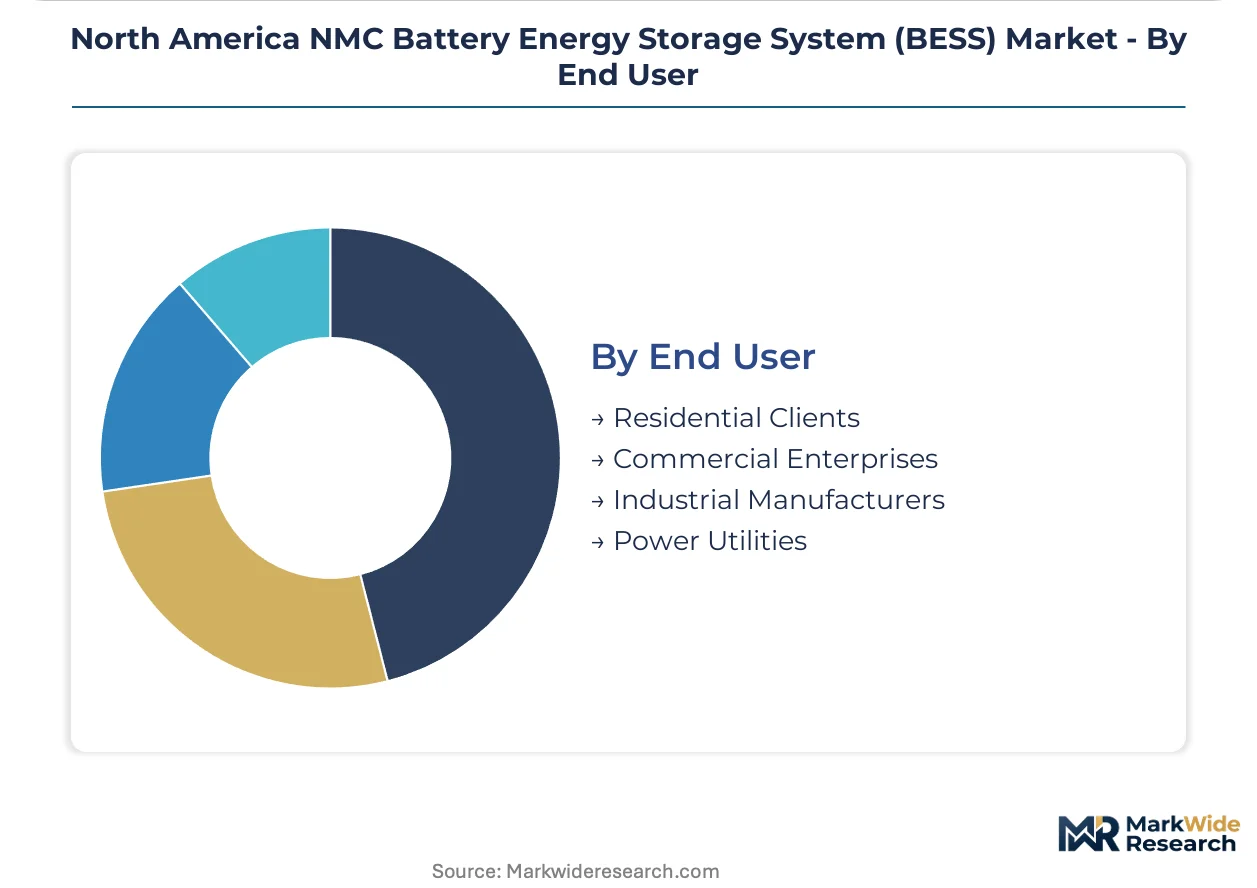
Power utilities anchor mature procurement pipelines. Commercial enterprises show the steepest expansion trajectory through third-party financing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nevada's lithium-rich Clayton Valley and Michigan's nickel processing corridors anchor cathode material flows for North American NMC BESS manufacturing. These mineral localities feed cell assembly plants that supply utility-scale projects across Texas and California interconnection queues.
United States
Texas ERCOT territory leads utility-scale procurement with four-hour duration systems specified for ancillary service revenue. The IRA's standalone storage ITC compresses developer payback periods and redirects module sourcing toward domestic assembly. Nevada's Tesla Gigafactory and Michigan's LG Energy Solution lines anchor cell-to-pack manufacturing for these deployments.
Canada
Ontario's manufacturing base and Quebec's critical mineral refining capacity support NMC cathode precursor production for cross-border supply chains. The country's national energy regulator and provincial utilities are piloting grid-scale storage pilots under clean electricity regulations. Vancouver and Toronto clusters concentrate project development expertise for North American offtake.
Mexico
Nuevo León and Baja California are attracting nearshored cell and module assembly to capture USMCA content rules for IRA bonus credit eligibility. Mexico's federal energy commission oversees interconnection standards for cross-border electricity trade. Monterrey industrial parks host preliminary manufacturing investments targeting Texas utility procurement timelines.
California
CAISO Resource Adequacy mandates pull four-hour duration NMC systems into ten-plus year contracting structures. The state's public utilities commission enforces storage procurement targets that accelerate queue positions for clean firm capacity. Los Angeles Basin and Central Valley project sites concentrate deployment for transmission deferral and renewable integration.
North America NMC Battery Energy Storage System (BESS) Market Competitive Landscape
Capacity expansion dominates the current landscape as integrators and cell manufacturers race to capture IRA-linked procurement windows. The vendor base stratifies across three tiers: captive cell producers with in-house pack integration, independent system integrators with software-defined architectures, and Asian cell suppliers penetrating through module partnerships. Strategic archetypes include vertically integrated energy companies, pure-play storage developers, and diversified electronics conglomerates. M&A activity and domestic manufacturing investments represent the two dominant competitive vectors reshaping supply chain positioning.
Within the captive manufacturing tier, Tesla Inc. and LG Energy Solution Ltd. exemplify upstream control strategies through Nevada and Michigan cell-to-pack facilities. Fluence Energy Inc. occupies a position among independent integrators competing through software optimization platforms. These three entities anchor distinct competitive vectors: in-house cathode throughput, dedicated pouch cell lines for utility-scale customers, and algorithmic dispatch management across variable grid profiles.
| Leading Market Players |
|---|
| Tesla Inc. |
| Fluence Energy Inc. |
| LG Energy Solution Ltd. |
| Hitachi Energy Ltd. |
| Sungrow Power Supply Co., Ltd. |
| Samsung SDI Co., Ltd. |
| Panasonic Holdings Corp |
| AES Corp |
| Contemporary Amperex Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up EPC contractors in ERCOT and CAISO territories are consolidating procurement volumes to extract module pricing concessions from Nevada and Michigan cell plants, tightening capital discipline across developer capital stacks while compressing integrator margins on fixed-price contracts.
Pricing Analysis
Warranty and performance guarantee bundling separates turnkey EPC quotes from unbundled equipment-only procurement, with ten-year throughput commitments commanding premiums over standard five-year defect coverage. Price differentiation hinges on cycle life certification tier and domestic content bonus eligibility under IRA rules. Cost compression in commercial behind-the-meter segments is intensifying because LFP alternatives are capturing shorter-duration applications. C&I customers with third-party PPA structures show highest price sensitivity; utility offtakers with Resource Adequacy mandates show least.
Supply Chain Analysis
Workforce availability constraints in Nevada's Lyon County and Michigan's Holland corridor are capping cell assembly throughput expansion despite capital deployment readiness. Geographic supply concentration centers on the United States, South Korea, and China for cathode precursor and separator inputs. The value chain draws from DRC cobalt, Chilean lithium, and Indonesian nickel for critical mineral feeds. Single-source vulnerability in cathode precursor refining creates concentration risk. Distribution runs through utility-scale integrators with direct OEM relationships rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a chemistry-transition phase as high-nickel NMC 811 formulations displace NMC 622 blends in four-hour duration utility configurations, forcing project finance structures to recalibrate degradation risk assumptions.
For Market Incumbents: Cement control over interconnection queue positions in ERCOT and CAISO territories through early deposit structures and land options. Deepen captive cell supply from Nevada and Michigan facilities to defend against Korean and Chinese module imports capturing IRA bonus credit eligibility. The LFP substitution threat in shorter-duration segments demands accelerated NMC 811 cycle life validation.
For New Entrants and Emerging Players: The premium-to-economy price gap in commercial C&I behind-the-meter systems offers white-space entry below utility-scale procurement thresholds. Target PJM and ERCOT demand charge management applications with 500kWh-2MWh containerized formats. Pursue software-defined dispatch optimization as the primary go-to-market angle to differentiate from hardware-commoditized incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor independent power producers with contracted Resource Adequacy offtake in California and merchant exposure in Texas. Long-term viability over a five-to-ten-year window rests on operational performance guarantee track records rather than equipment ownership. Watch FERC Order 2222 aggregation implementation timelines as the signal for distributed revenue stack inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Bonus Capture | Module sourcing from Nevada and Michigan cell plants secures IRA credit eligibility for utility developers. |
| Software-Defined Dispatch Platform | Algorithmic optimization of NMC cycle life across ERCOT real-time price volatility captures merchant premiums. |
| Hybrid Solar-Storage Configuration | DC-coupled Texas utility sites reduce balance-of-system costs through shared inverter and interconnection infrastructure. |
| NERC CIP Compliance Investment | Cybersecurity documentation and audit readiness protect grid-connected assets from bulk electric system classification delays. |
| Recycling Infrastructure Partnership | Cathode recovery capabilities address extended producer responsibility exposure under emerging state frameworks. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings on procurement timeline compression. Primary interviews with FERC and NERC compliance specialists combined with secondary validation through EIA deployment databases, FERC interconnection queue filings, and IRA implementation guidance from the Department of Treasury anchor the analysis. Bottom-up project pipeline aggregation and top-down policy impact modeling triangulate volume estimates.
Rate-of-change decomposition across the analysis window separates chemistry transition effects from interconnection reform impacts and ITC policy phase-in dynamics. Segmentation dimensions modeled include product type, application, installation architecture, and end-user sophistication across ERCOT, CAISO, and PJM regulatory frameworks. CAGRs derive from fitted growth curves applied to disclosed utility procurement targets and commercial PPA origination volumes.
Inputs from interconnection queue databases and state storage mandate filings were available through the study window; gaps in merchant revenue realization data introduce uncertainty bands around project finance closure assumptions. Forecasts reflect documented assumptions on IRA credit permanence and cobalt price regime stability. Material deviation in FERC Order 2222 implementation timelines or NERC CIP enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
High Capacity Power Banks Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Energy Storage Software Market
Energy Storage
Power Bank Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Supercapacitor Market
Energy Storage
Marine Energy Storage System Market