

Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market Insights
Buyer concentration across utility operators and grid service providers is broadening as independent power producers and microgrid developers enter procurement channels for BESS test platforms. UL Solutions leverages its North American certification network to anchor large-scale stationary test rig deployments. TÜV Rheinland competes across European markets with specialized power hardware-in-the-loop capabilities. Siemens sustains technology leadership through integrated grid simulation software bundled with hardware platforms.
Megawatt-scale battery energy storage system test platforms are integrated electromechanical systems designed to replicate grid conditions, apply controlled charge-discharge profiles, and inject faults across voltage ranges exceeding 1,000 V DC at power levels from hundreds of kilowatts to multiple megawatts; their primary purpose is to validate safety, performance, and interoperability before commercial deployment. Stationary test rigs dominate capital expenditure flows due to permanent installation at manufacturer facilities and third-party laboratories. Module-level platforms represent the fastest-growing product category as cell-to-pack architectures require discrete validation before full-system assembly. Grid simulation technology commands premium pricing among technology segments because it reproduces transient grid events that physical test beds cannot replicate economically.
The US Federal Energy Regulatory Commission and the Institute of Electrical and Electronics Engineers shape domestic demand through Order 841 and IEEE 1547-2018, which mandate verified frequency response and voltage ride-through capabilities for interconnected storage assets. Europe's Ecodesign and Energy Labelling frameworks, administered by the European Commission, progressively extend efficiency and disclosure requirements to grid-scale battery systems. Stakeholders must monitor whether emerging carbon border adjustments and domestic content incentives in multiple jurisdictions redirect test platform procurement toward regionally certified laboratories rather than centralized global facilities.
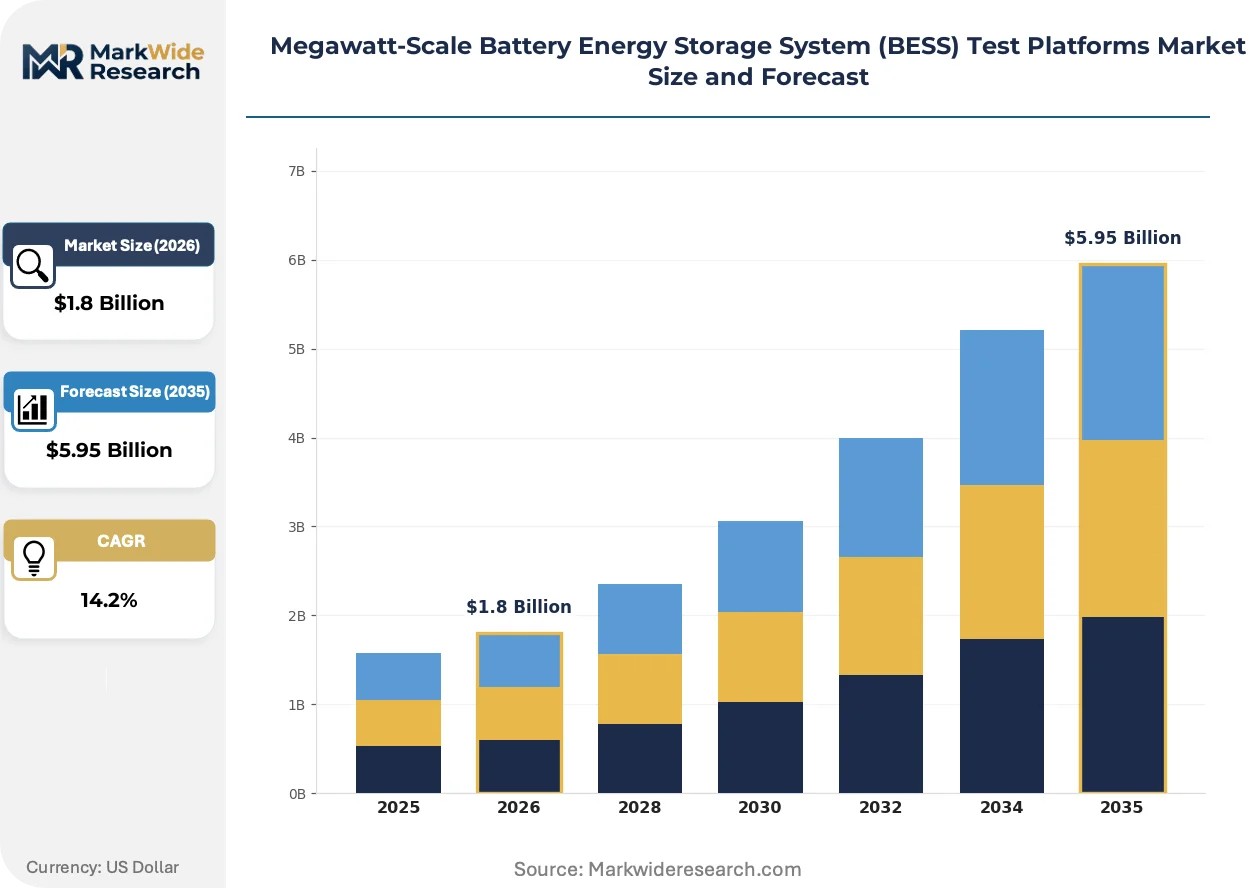
Market Dynamics
Cell-to-pack architectures are compressing validation timelines as battery manufacturers demand discrete module testing before full-system assembly, forcing test platform vendors to reconfigure hardware-in-the-loop capabilities for intermediate power tiers.
Growth Catalysts
- IEEE 1547-2018:US grid interconnection standards now mandate verified frequency response and voltage ride-through capabilities for storage assets, compelling developers to procure certified test platforms before commercial deployment.
- Solar-plus-storage developers:Renewable integration projects require pre-certification of megawatt-scale assets, creating sustained pull for stationary test rigs capable of simulating variable renewable output profiles.
- Silicon carbide power electronics:Adoption of wide-bandgap semiconductors in inverter test beds enables higher switching frequencies and more accurate fault replication, improving validation fidelity for grid-forming battery systems.
Market Restraints
- Lithium price volatility:Cell cost fluctuations compress capital budgets at battery manufacturers, delaying discretionary test platform investments despite regulatory deadlines.
- Specialized power electronics suppliers:Concentration among European and Japanese vendors for high-voltage DC testing components creates procurement bottlenecks and extended lead times for platform integrators.
- IEC 62933 interoperability gaps:Incomplete harmonization between regional grid codes forces test laboratories to maintain redundant equipment configurations, inflating fixed costs.
Strategic Opportunities
- India:Central Electricity Authority mandates for grid-scale storage testing are emerging alongside domestic manufacturing incentives, opening procurement channels for module-level platform vendors.
- Marine and offshore applications:Containerized battery systems for port electrification and vessel shore power require salt-corrosion and vibration testing protocols not yet standardized in terrestrial platforms.
- Power-to-X convergence:Integration of electrolyzer load banks with battery test systems enables unified validation for hybrid storage-hydrogen assets, capturing value from overlapping infrastructure investments.
Industry Challenges
- Grid simulation software expertise:Shortage of engineers proficient in real-time digital simulator programming limits laboratory throughput despite available hardware capacity.
- UL 9540A fire safety certification:Extended thermal runaway propagation testing timelines delay platform availability for new cell chemistries, compressing revenue recognition windows.
- Legacy SCADA integration:Utility-owned test facilities require custom protocol bridges to connect modern battery management systems with existing supervisory infrastructure, inflating deployment costs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market Trends and Innovations
Validation workflows are fragmenting across distributed test nodes as manufacturers push quality assurance closer to cell production facilities, compressing the traditional centralized laboratory model.
Power hardware-in-the-loop (PHIL) interfaces are expanding into module-level validation workflows, enabling real-time interaction between physical battery stacks and simulated grid disturbances. Tier-1 cell manufacturers in Germany and China are deploying these interfaces at pilot production lines to catch thermal management anomalies before pack assembly. The technology is expanding into cost-sensitive segments by displacing full-scale physical test beds for intermediate validation stages.
The EU Ecodesign framework is extending efficiency disclosure requirements to grid-scale battery systems, mandating standardized round-trip efficiency testing protocols that laboratories must embed in certification workflows. Battery OEMs must now submit third-party-verified degradation curves under specified temperature and duty cycles, increasing test platform utilization rates. European test houses are responding by expanding climate chamber capacity to cover the full -20°C to 50°C operating envelope.
Buyer preference is hardening around bundled software-hardware packages that include automated report generation for multiple jurisdiction certifications. Independent power producers in Texas and California are selecting vendors offering single-test multi-code compliance rather than sequential regional validations. This preference is most visible among solar-plus-storage developers facing overlapping FERC Order 841 and state-level interconnection queues.
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market Segmentation
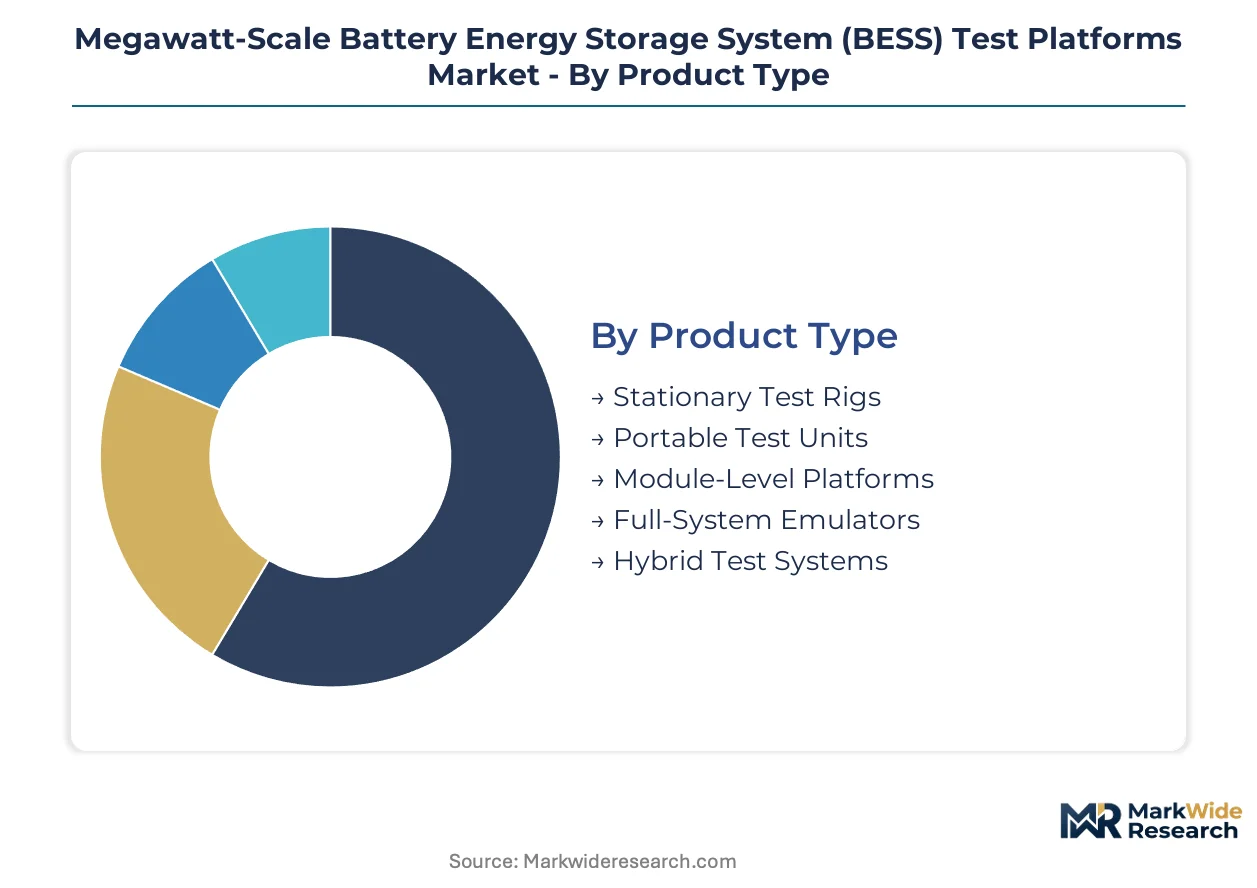
Segmentation in the BESS test platforms market reflects divergent capital deployment strategies across the battery supply chain. Test platform procurement varies sharply between permanent manufacturing infrastructure and flexible third-party laboratory services.
Product Type:
Customization intensity spans from permanently installed factory fixtures to mobile validation units deployed across distributed sites.
- Stationary Test Rigs:Permanent installations at manufacturer facilities and third-party laboratories dominate capital expenditure flows. Utility operators across the United States and Germany anchor demand for these systems as IEEE 1547 and IEC 62933 standards tighten pre-certification requirements.
- Module-Level Platforms:Intermediate-power systems validate cell-to-pack architectures before full-system assembly. Battery manufacturers in China compress validation timelines by deploying these platforms at pilot production lines.
- Portable Test Units:Mobile systems enable field validation at renewable project sites.
- Full-System Emulators:Complete battery stack replication for final commissioning protocols.
- Hybrid Test Systems:Combined physical and simulated testing environments.
Leading the category by volume: Stationary Test Rigs. Growing fastest: Module-Level Platforms.
Technology:
Technology selection tracks the fidelity-cost tradeoff between physical stress testing and software-based grid replication.
- Grid Simulation:Real-time digital simulators reproduce transient grid events that physical test beds cannot replicate economically. Premium pricing reflects software complexity and multi-jurisdiction certification bundling demanded by solar-plus-storage developers in Texas and California.
- Power Hardware-in-the-Loop:PHIL interfaces enable real-time interaction between physical battery stacks and simulated disturbances. Tier-1 cell manufacturers in Germany deploy these at production lines to catch thermal anomalies early.
- Thermal Analysis:Climate chamber validation across operating temperature envelopes.
- Fault Injection:Controlled grid disturbance replication for safety certification.
- Cycle Life Testing:Long-duration degradation assessment under specified duty cycles.
Dominating revenue contribution: Grid Simulation. Expanding most quickly: Power Hardware-in-the-Loop.
Application:
Application demand clusters around grid interconnection mandates and renewable project development cycles.
- Renewable Integration:Solar-plus-storage and wind farm developers require pre-certification of megawatt-scale assets before grid connection. FERC Order 841 in the United States mandates verified frequency response capabilities.
- Microgrid Validation:Islanding and resynchronization testing for distributed energy resources. Remote industrial facilities and military installations drive procurement in Germany and Australia.
- Load Management:Demand response capability verification.
- Peak Shaving:Utility-scale arbitrage performance testing.
- Backup Power Assessment:Critical facility resilience validation.
- Electric Grid Support:Ancillary services capability certification.
Commanding the largest share: Renewable Integration. Gaining share fastest: Microgrid Validation.
End User:
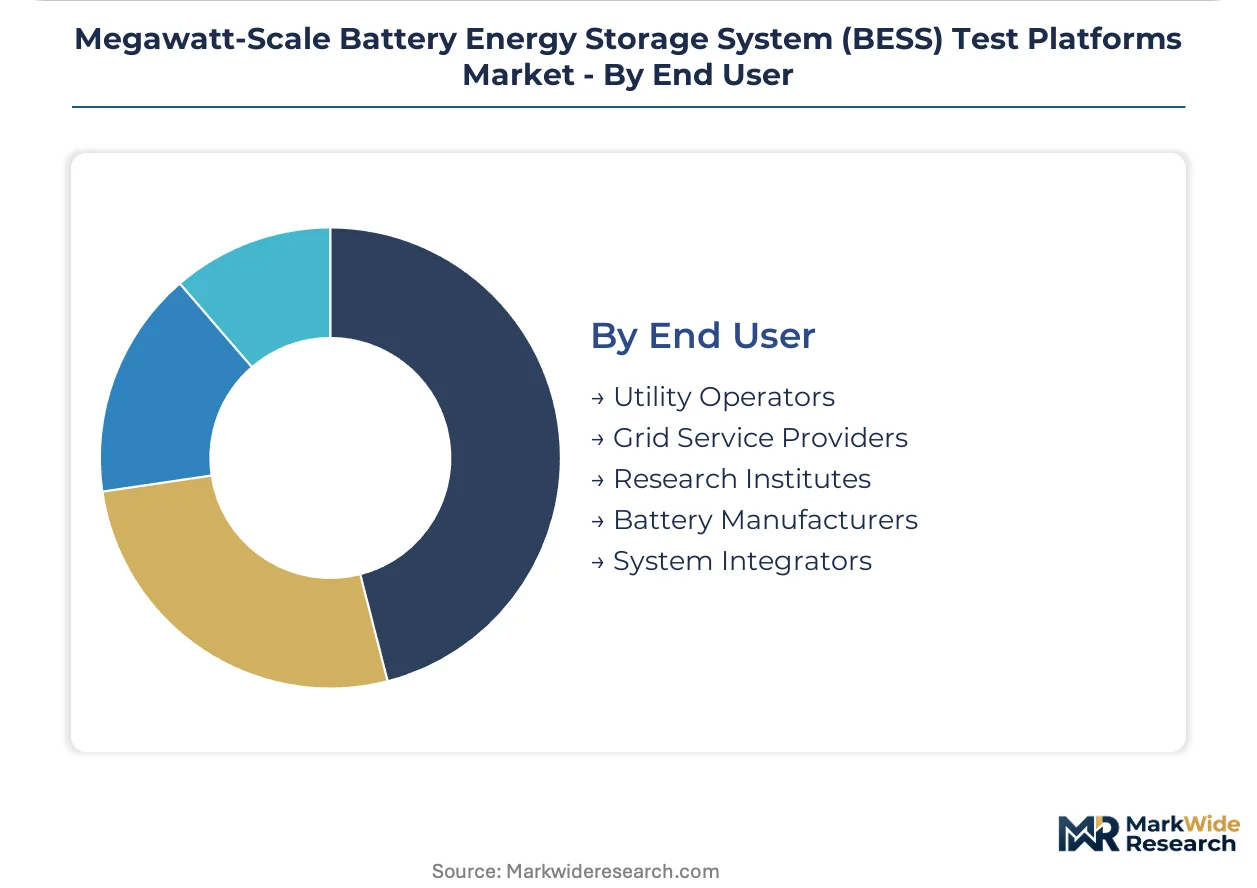
End user composition is broadening as independent power producers and microgrid developers enter procurement channels alongside traditional utilities.
- Utility Operators:Grid-connected storage asset owners mandate certified test platforms for interconnection compliance. Investor-owned utilities across the United States anchor volume through FERC-jurisdictional procurement.
- Battery Manufacturers:Cell and pack producers require in-house validation capabilities to compress development cycles. Chinese and South Korean producers drive module-level platform demand.
- Grid Service Providers:Independent laboratories offering third-party certification services.
- Research Institutes:Academic and government laboratories advancing test protocols.
- System Integrators:Turnkey project developers bundling testing services.
Representing the largest procurement base: Utility Operators. Expanding most rapidly: Battery Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility operators in the United States, Germany, and China concentrate procurement for megawatt-scale BESS test platforms, with regulatory tightening across IEEE 1547 and IEC 62933 standards reshaping laboratory infrastructure investments in each jurisdiction.
United States
FERC Order 841 and state-level interconnection mandates drive utility procurement of stationary test rigs. IEEE 1547-2018 compliance requirements for frequency response and voltage ride-through capabilities compel solar-plus-storage developers in Texas and California to secure pre-certification. The Pacific Northwest and Southwest regions host expanding third-party laboratory capacity.
Germany
Tier-1 cell manufacturers deploy power hardware-in-the-loop interfaces at pilot production lines to compress validation timelines. The EU Ecodesign framework mandates standardized round-trip efficiency testing, forcing laboratories to expand climate chamber coverage across the full operating envelope. Industrial clusters in Bavaria and North Rhine-Westphalia anchor test platform deployment.
China
Battery OEMs drive module-level platform demand as cell-to-pack architectures proliferate. Domestic manufacturing incentives and grid-scale storage procurement targets create pull for intermediate-power validation systems. Yangtze River Delta and Pearl River Delta production hubs integrate testing capabilities closer to cell fabrication facilities.
India
Central Electricity Authority mandates for grid-scale storage testing are emerging alongside production-linked incentive schemes for domestic battery manufacturing. Module-level platform vendors target procurement channels opened by these regulatory developments. Gujarat and Tamil Nadu industrial corridors concentrate early laboratory infrastructure deployment.
Japan
METI efficiency standards and grid interconnection codes shape demand for high-fidelity grid simulation technology. Silicon carbide power electronics adoption in inverter test beds aligns with domestic semiconductor manufacturing strengths. Kanto and Kansai regions host specialized power electronics suppliers serving platform integrators.
Megawatt-Scale Battery Energy Storage System (BESS) Test Platforms Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent validation services and software bundling. The vendor base stratifies across certification networks, power electronics integration specialists, and grid simulation software providers. Three archetypes dominate: third-party testing houses with multi-jurisdiction accreditation, industrial conglomerates offering integrated hardware-software platforms, and specialized power electronics component suppliers. Competitive moves center on strategic partnerships for multi-code certification bundling and geographic expansion into emerging procurement markets.
Among North American certification specialists, UL Solutions anchors the third-party laboratory archetype through its accredited network. TÜV Rheinland and TÜV SÜD occupy positions within the European testing house tier, leveraging specialized power hardware-in-the-loop capabilities. Siemens represents the integrated industrial conglomerate archetype, bundling grid simulation software with hardware platforms. These three exemplify divergent strategic postures: accreditation breadth, regional regulatory depth, and technology integration respectively.
| Leading Market Players |
|---|
| UL Solutions |
| Intertek |
| TÜV Rheinland |
| TÜV SÜD |
| CSA Group |
| DNV |
| Bureau Veritas |
| Siemens |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up testing specialists anchor supply capacity across North America and Europe, concentrating ownership of accredited laboratory networks while exerting pricing discipline through bundled certification packages that tie hardware procurement to multi-jurisdiction software licenses.
Pricing Analysis
High-volume stationary test rig deployments run on thin margins while grid simulation software and PHIL interfaces capture premium returns. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified multi-code bundles from single-jurisdiction hardware-only configurations. Cost compression in module-level platforms is intensifying because Chinese battery OEMs are internalizing validation capabilities. Independent power producers in Texas exhibit the sharpest price sensitivity, whereas German tier-1 cell manufacturers prioritize certification breadth over unit economics.
Supply Chain Analysis
Silicon carbide power electronics supply rests on Japanese and German specialty semiconductor producers, with high-voltage DC testing components drawing from concentrated European and Japanese vendor bases. Specialized IGBT modules, real-time digital simulator hardware, and climate chamber systems feed from these geographies. Single-source vulnerability in wide-bandgap semiconductor supply creates procurement bottlenecks for platform integrators facing IEEE 1547 compliance deadlines. Distribution runs through direct OEM sales for large stationary rigs and third-party laboratory service contracts for validation outsourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power hardware-in-the-loop engineering talent scarcity props pricing for integrated software-hardware bundles, constraining laboratory throughput despite available physical capacity.
For Market Incumbents: Acquire specialized PHIL engineering teams and real-time simulator programming capabilities to offset talent scarcity compressing project margins. Battery manufacturers in China are internalizing module-level validation, threatening third-party laboratory revenue streams. Backward integration into silicon carbide power electronics sourcing reduces exposure to Japanese supplier concentration. For New Entrants and Emerging Players: Microgrid developers in Australia and remote industrial facilities represent an underserved buyer archetype seeking containerized validation units for islanding certification. Marine and offshore battery applications for port electrification lack standardized salt-corrosion testing protocols. A field-deployable test unit rental model bypasses capital-intensive permanent laboratory infrastructure. For Investors and Strategic Acquirers: Central Electricity Authority mandate issuance in India is the leading indicator that module-level platform demand will accelerate beyond current supply capacity. Five-to-ten-year viability hinges on software-hardware bundling capture rather than commodity hardware margins. Acquisition targets with accredited multi-jurisdiction certification networks command defensive positioning. Watch FERC Order 841 enforcement intensity as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Bundling | Single-test compliance for IEEE 1547 and IEC 62933 reduces solar-plus-storage developer timeline risk. |
| Power Hardware-in-the-Loop Capacity Expansion | Real-time grid disturbance replication addresses tier-1 cell manufacturer validation compression needs. |
| Silicon Carbide Electronics Integration | Higher switching frequencies enable accurate fault replication for grid-forming battery systems. |
| Climate Chamber Infrastructure Scaling | EU Ecodesign round-trip efficiency mandates require expanded -20°C to 50°C testing coverage. |
| Marine Testing Protocol Development | Salt-corrosion and vibration standards for port electrification capture offshore battery demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving utility planning officers, battery OEM procurement leads, third-party laboratory technical directors, and grid simulation software engineers. FERC Order 841 implementation records, IEEE standards documentation, EU Ecodesign framework disclosures, and Central Electricity Authority notifications supplied regulatory trajectory inputs. Bottom-up test platform deployment tallies reconciled against top-down battery manufacturing capacity expansion estimates.
Data-stream reconciliation across shipment records, laboratory accreditation databases, and OEM capital expenditure disclosures shaped the analytical framework. Segmentation dimensions spanned product type permanence, technology fidelity-cost tier, application regulatory driver, and end-user procurement centralization. CAGRs derived from installed base growth curves and replacement cycle assumptions, with silicon carbide adoption rates and cell-to-pack architecture penetration serving as BESS-specific forecast modifiers.
Revisions become necessary when IEEE 1547-2018 enforcement intensity shifts, lithium price volatility alters battery manufacturer capital allocation, or carbon border adjustments redirect test platform procurement toward regionally certified laboratories. Forecasts reflect assumptions about standard harmonization progress and supply chain concentration persistence. A small set of named triggers—regulatory deadline acceleration, wide-bandgap semiconductor supply disruption, and domestic content incentive expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.