
 ASEAN Energy Storage Devices Market | 2026-2036
ASEAN Energy Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Energy Storage Devices Market Outlook
Lithium iron phosphate is shifting cost structures across utility-scale battery systems, undercutting nickel-manganese-cobalt formulations on cycle life economics. Contemporary Amperex Technology Co. Limited anchors cell supply through its Indonesia manufacturing complex. BYD Co. Ltd leverages integrated battery-to-inverter platforms to dominate commercial and industrial segments. LG Chem Ltd sustains premium positioning through high-nickel cathode R&D pipelines.
Energy storage devices are electrochemical or mechanical systems that capture electrical energy for deferred discharge, with lithium-ion cells achieving energy densities above 250 Wh/kg and cycle lives exceeding 6,000 charge events at 80% depth of discharge. These systems buffer intermittency from solar and wind installations while providing frequency regulation and voltage support to grid operators. Battery Systems command the dominant revenue share given lithium-ion's scalability and declining pack-level costs, while Supercapacitors occupy niche applications requiring rapid charge acceptance and millions of shallow cycles. Compressed Air Energy Storage remains nascent in ASEAN but attracts pilot funding for bulk seasonal storage where geological formations permit underground cavern deployment.
Indonesia's Ministry of Energy and Mineral Resources enforces local content requirements under domestic manufacturing regulations, compelling foreign cell producers to establish joint ventures with Indonesian partners. Thailand's ERC and the Philippines' DOE both mandate grid code compliance for battery energy storage systems interconnecting at distribution voltage levels, shaping product certification pathways. Vietnam's EVN technical standards for frequency response further segment supplier eligibility by response time thresholds. Stakeholders must track how rapidly each national regulator harmonizes safety standards with IEC 62933 or pursues divergent local protocols that fragment procurement specifications.
Market Dynamics
Lithium iron phosphate chemistry is compressing nickel-manganese-cobalt economics across ASEAN utility-scale procurements, while Indonesia's local content mandates force foreign cell manufacturers into joint venture structures that reshape competitive entry costs.
Growth Catalysts
- Thailand's renewable energy targets:The ERC mandates 30% renewable generation by 2037, compelling utility procurement of grid-scale battery systems for frequency regulation and solar firming.
- Frequency response standards:Vietnam's EVN technical specifications create tiered supplier eligibility by response time thresholds, accelerating demand for advanced battery management systems.
- Grid modernization programs:Indonesia's PLN distribution network upgrades concentrate battery procurement for voltage support and peak shaving across Java-Bali interconnections.
Market Restraints
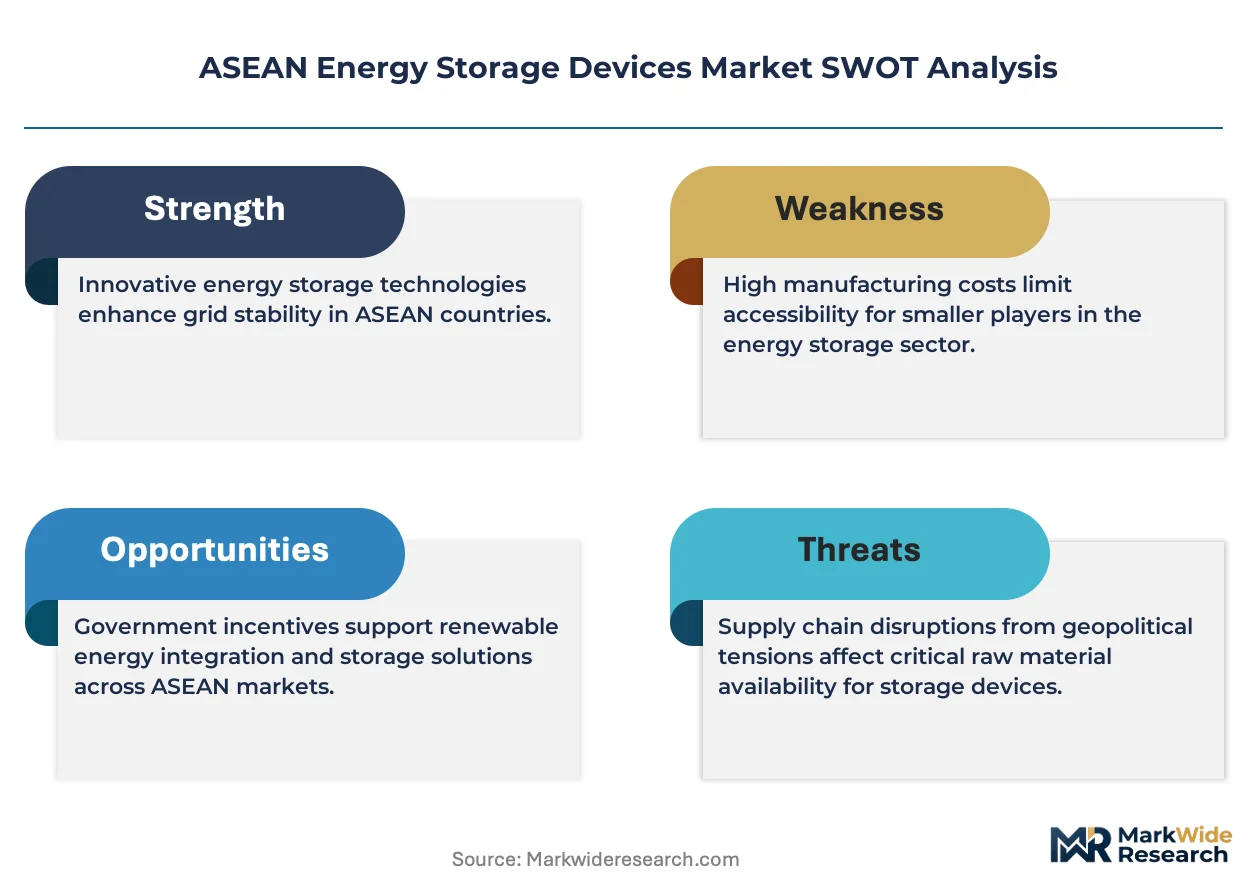
- Lithium carbonate price volatility:Raw material cost swings above 40% annually compress pack-level margins and deter long-term procurement contracts.
- Cell supply concentration:Manufacturing capacity clusters in China and Korea expose ASEAN buyers to shipping disruptions and currency mismatch risks.
- Local content enforcement:Indonesia's Ministry of Energy and Mineral Resources regulations mandate 40% domestic value-add, extending project timelines for foreign suppliers.
Strategic Opportunities
- Commercial and industrial behind-the-meter:Thailand's manufacturing estates and Philippines' export processing zones present underpenetrated demand for peak demand charge management.
- Compressed air seasonal storage:Geological salt domes in Vietnam and Thailand enable pilot funding for bulk multi-day discharge applications beyond lithium-ion economics.
- Supercapacitor fast-cycling niches:Port electrification and regenerative braking systems in Singapore and Malaysia create demand for million-cycle shallow discharge devices.
Industry Challenges
- Battery management system firmware integration:Utility-scale projects require 18-24 month certification cycles to harmonize proprietary control architectures with national grid codes.
- Thermal runaway containment engineering:ASEAN fire safety regulators lack unified testing protocols, forcing redundant validation against IEC 62933-5-2 and divergent local standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Energy Storage Devices Market |
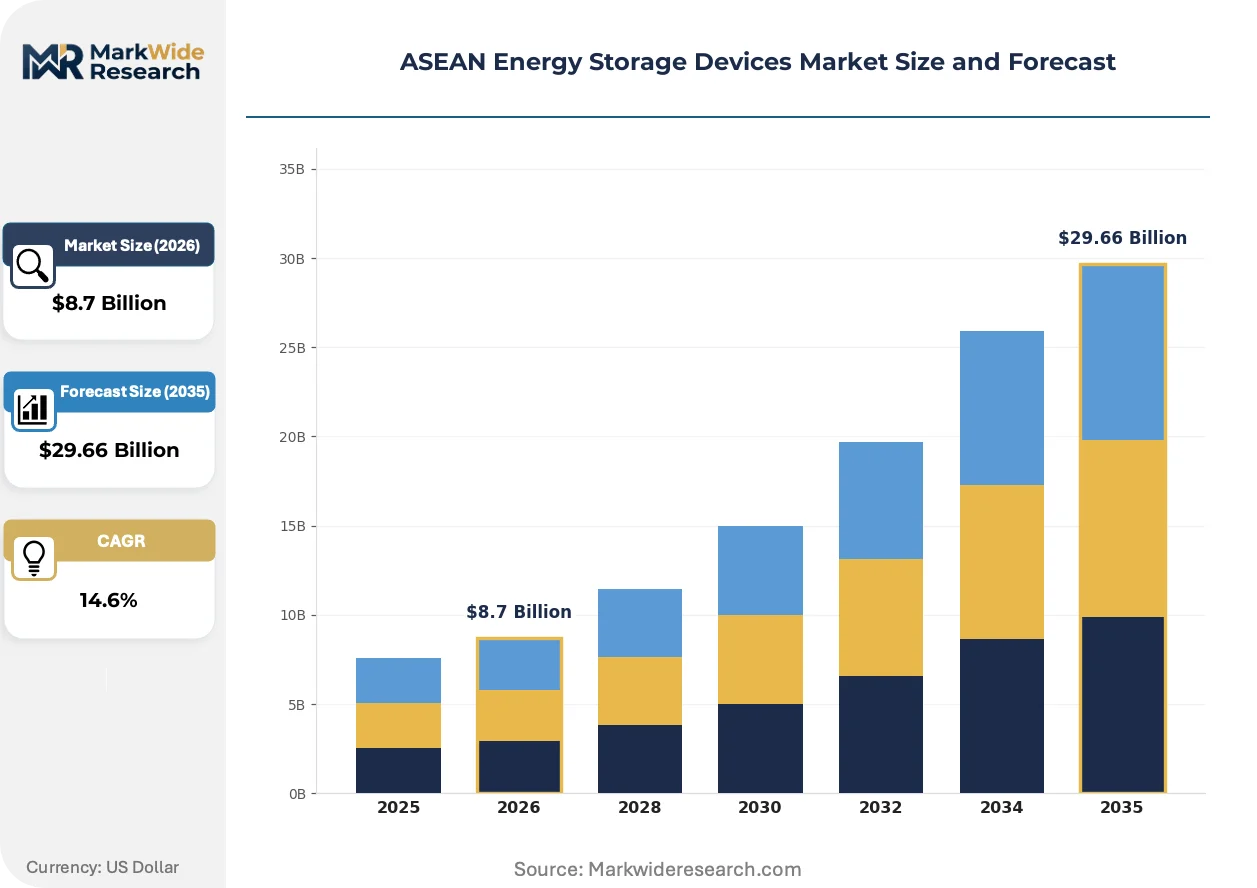
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Systems, Flywheel Energy Storage, Supercapacitors, Compressed Air Energy Storage Technology: Lithium-Ion, Nickel-Cadmium, Vanadium Redox, Lead-Acid End User: Utilities, Renewable Energy Providers, Commercial Facilities, Residential Users Application: Grid Stabilization, Peak Shaving, Load Shifting, Backup Power |
| Companies Covered | GS Yuasa Corporation, Wartsila Oyj Abp, BYD Co. Ltd, SEC Battery Company, NGK Insulators Ltd, Contemporary Amperex Technology Co. Limited, LG Chem Ltd, NEC Corporation, General Electric, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Energy Storage Devices Market Strategic Shifts
Electrochemical storage architectures are bifurcating between high-density mobility cells and long-duration stationary chemistries, with ASEAN procurement patterns tracking this divergence through differentiated tender specifications.
Solid-state battery prototyping is electrifying research pipelines across Singapore's A*STAR institutes and Thailand's NSTDA facilities, with sulfide electrolyte formulations targeting 400 Wh/kg densities for future electric bus deployments. State-owned transport operators in Bangkok and Jakarta are piloting module-scale validation programs. The technology is electrifying supplier R&D roadmaps and compressing conventional lithium-polymer development timelines.
Indonesia's domestic manufacturing regulations now compel joint venture structures for all cell production facilities above 5 GWh annual capacity, with Ministry of Energy and Mineral Resources officials enforcing equity participation thresholds. Foreign cathode active material suppliers must localize precursor chemical processing to maintain procurement eligibility. Industrial park developers in Batang and Karawang are responding with integrated chemical-to-cell infrastructure zones.
Utility procurement committees are consolidating battery energy storage system awards under engineering-procurement-construction contracts that bundle 15-year service agreements, displacing component-only transactions. State utilities in Thailand and Vietnam now mandate guaranteed performance degradation curves and availability warranties. This bundling concentrates supplier selection among integrated platform providers with captive service networks.
ASEAN Energy Storage Devices Market Segmentation
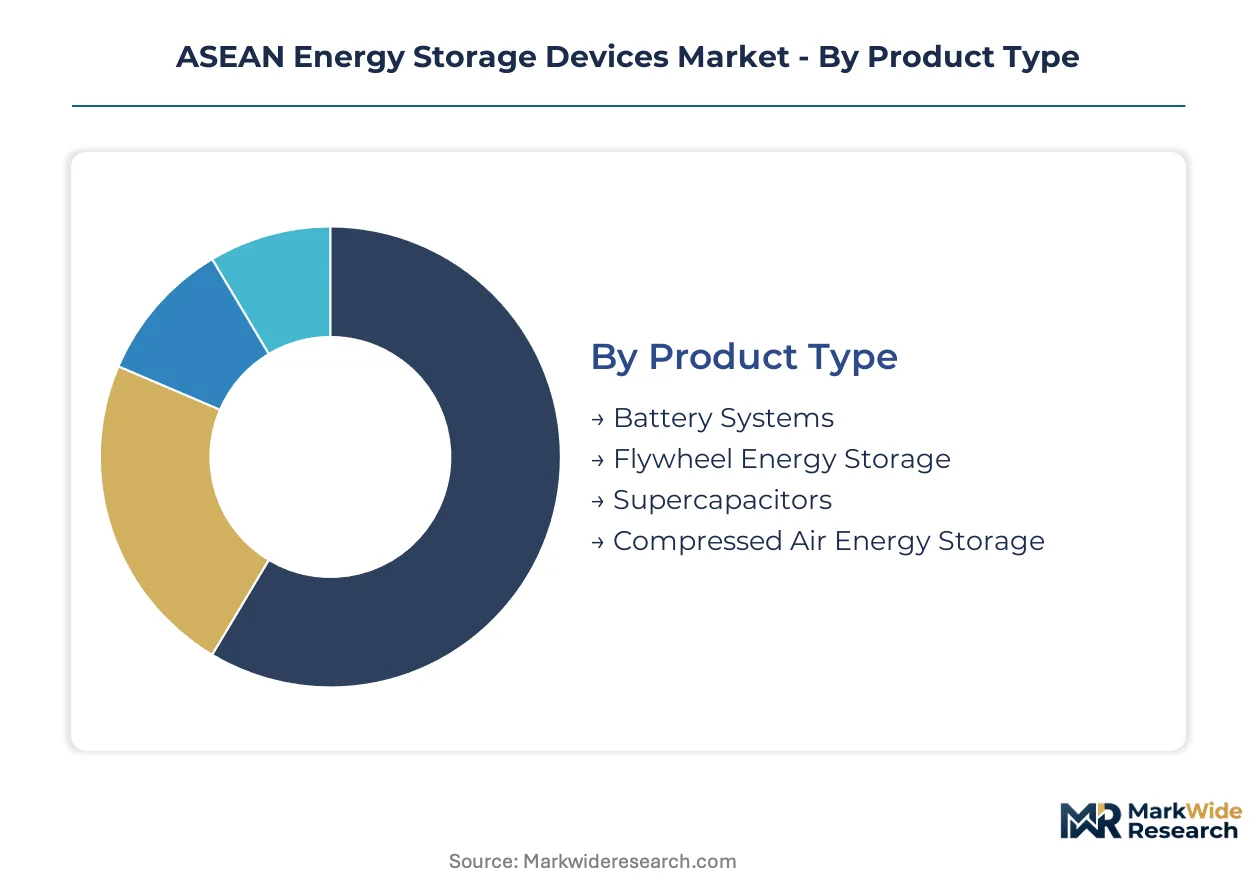
Procurement specifications across ASEAN diverge sharply between integrated utility-scale platforms and distributed behind-the-meter installations. Understanding where each segment sits on this integration spectrum clarifies supplier positioning and margin architecture.
Product Type:
Standalone battery systems dominate utility tenders, while embedded supercapacitor modules penetrate transportation electrification.
- Battery Systems:Lithium-ion packs configured in containerized megawatt-hour blocks deliver frequency regulation and solar firming for Thailand's ERC-mandated renewable targets. Indonesia's PLN procurement concentrates demand in Java-Bali grid interconnections where voltage support requirements are most acute.
- Supercapacitors:Electrochemical double-layer capacitors achieve million-cycle durability with rapid charge acceptance. Singapore's port electrification programs and Malaysia's regenerative braking deployments absorb production volumes for shallow-discharge cycling applications.
- Flywheel Energy Storage:Kinetic energy storage systems provide short-duration frequency response with minimal degradation over decades of operation.
- Compressed Air Energy Storage:Bulk seasonal storage technology leverages Vietnam's salt dome geology for multi-day discharge applications beyond lithium-ion economics.
Battery Systems lead volumes today; Compressed Air Energy Storage is gaining share fastest.
Technology:
Cost tiers separate premium high-nickel formulations from standardized iron phosphate cells reshaping utility procurement.
- Lithium-Ion:Energy densities above 250 Wh/kg and cycle lives exceeding 6,000 events at 80% depth of discharge anchor grid-scale deployments. Indonesia's local content mandates compel joint venture manufacturing structures that extend project timelines for foreign cathode suppliers.
- Lead-Acid:Mature electrochemistry retains installed base in residential backup applications across the Philippines' island grids where capital constraints predominate over lifecycle economics.
- Nickel-Cadmium:Robust temperature tolerance sustains niche demand in industrial environments with extreme thermal cycling requirements.
- Vanadium Redox:Aqueous flow batteries enable independent scaling of power and energy capacity for long-duration storage pilots in Thailand's manufacturing estates.
Lithium-Ion commands installed capacity; Vanadium Redox is expanding most quickly.
End User:
Customer type determines contract structure, with utilities consolidating under 15-year service agreements and commercial buyers accepting shorter warranty terms.
- Utilities:State-owned operators in Thailand and Vietnam mandate guaranteed performance degradation curves and availability warranties under engineering-procurement-construction contracts. These bundled awards concentrate supplier selection among integrated platform providers.
- Commercial Facilities:Thailand's manufacturing estates and Philippines' export processing zones present underpenetrated demand for peak demand charge management through behind-the-meter battery installations.
- Renewable Energy Providers:Solar and wind developers procure co-located storage to meet firming requirements under ERC and DOE interconnection standards.
- Residential Users:Distributed battery adoption clusters in the Philippines' island provinces where grid reliability failures drive backup power investment.
Utilities anchor procurement volumes today; Commercial Facilities are climbing the fastest.
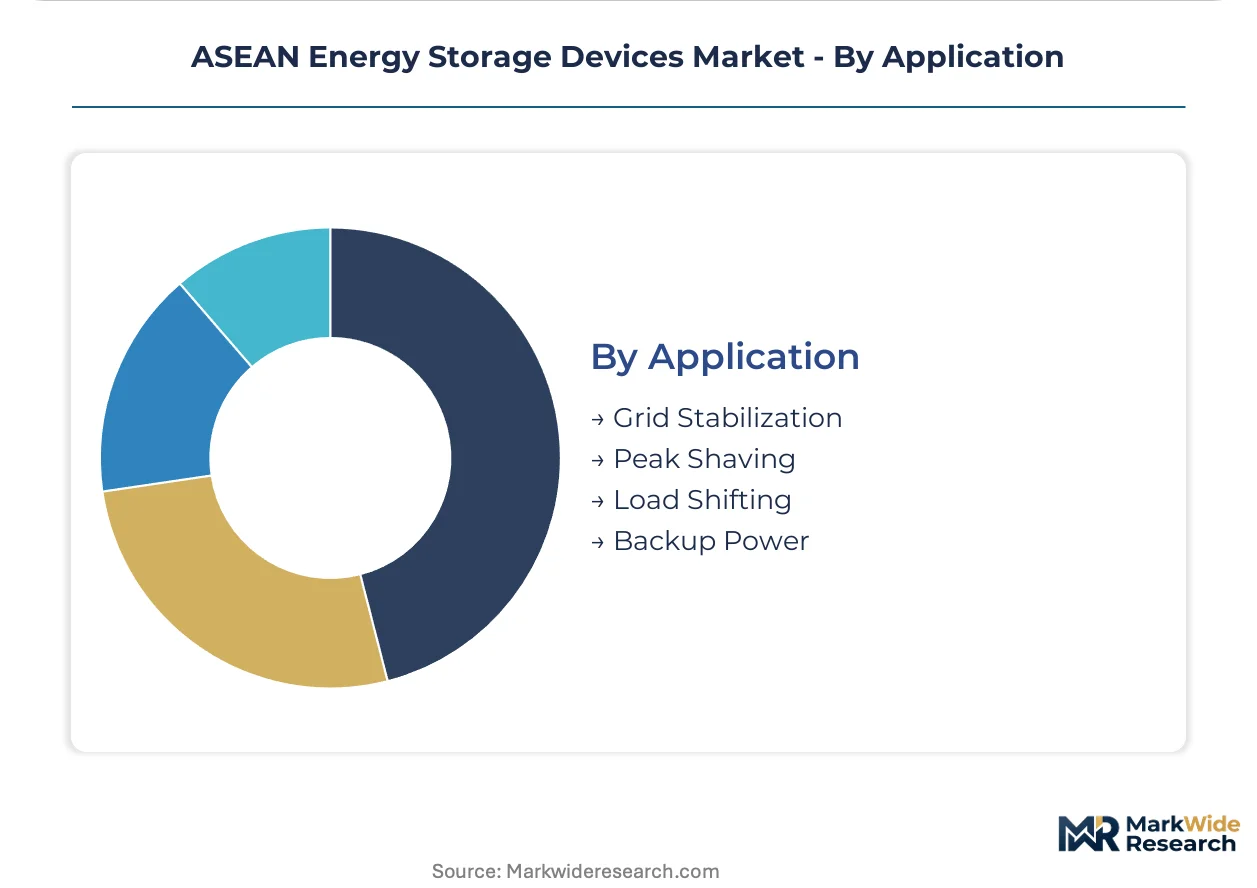
Application:
Maturity gradients separate established frequency regulation services from emerging load-shifting revenue streams.
- Grid Stabilization:Frequency regulation and voltage support services command premium pricing under Vietnam's EVN technical standards that segment supplier eligibility by response time thresholds. Battery management system firmware integration requires 18-24 month certification cycles.
- Peak Shaving:Demand charge reduction drives commercial adoption in Thailand's industrial tariff structures where time-of-use rates create arbitrage opportunities for behind-the-meter storage.
- Load Shifting:Energy arbitrage between high and low price periods remains constrained by ASEAN wholesale market design limitations in most jurisdictions.
- Backup Power:Uninterruptible supply applications dominate residential procurement in the Philippines and Indonesia where distribution network reliability varies by region.
Grid Stabilization leads revenue today; Peak Shaving is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Java-Bali grid corridor concentrates Indonesia's battery procurement activity, while Thailand's Eastern Economic Corridor and Vietnam's northern industrial provinces anchor manufacturing-linked storage demand across mainland Southeast Asia.
Indonesia
State utility PLN drives procurement for voltage support across Java-Bali interconnections where renewable penetration strains distribution networks. The Ministry of Energy and Mineral Resources enforces 40% local content thresholds through joint venture mandates for cell production above 5 GWh capacity. Industrial park developers in Batang and Karawang are constructing integrated chemical-to-cell infrastructure zones to satisfy these requirements.
Thailand
The Energy Regulatory Commission's 30% renewable generation target by 2037 compels utility-scale battery procurement for frequency regulation and solar firming. Grid code compliance mandates shape product certification pathways for systems interconnecting at distribution voltage levels. Manufacturing estates in the Eastern Economic Corridor present underpenetrated behind-the-meter demand for peak demand charge management.
Vietnam
State utility EVN's technical standards for frequency response segment supplier eligibility by response time thresholds, accelerating demand for advanced battery management systems. Wholesale market design limitations constrain energy arbitrage revenue streams outside grid stabilization services. Salt dome geology in the southern provinces enables pilot funding for compressed air seasonal storage beyond lithium-ion economics.
Singapore
Port electrification programs and urban regenerative braking deployments absorb supercapacitor production volumes for shallow-discharge cycling applications. The city-state's grid reliability standards drive procurement of fast-response frequency regulation assets. Research institutes including A*STAR anchor solid-state battery prototyping pipelines targeting future electric bus validations.
Philippines
Island grid reliability failures drive distributed battery adoption across provincial archipelago regions where backup power investment outweighs lifecycle economics. The Department of Energy mandates grid code compliance for battery energy storage systems interconnecting at distribution voltage levels. Export processing zones present commercial behind-the-meter opportunities for peak demand charge management.
ASEAN Energy Storage Devices Market Competitive Environment
Joint venture formation dominates the current landscape as foreign cell manufacturers respond to Indonesia's local content mandates. The vendor base stratifies between integrated platform providers with captive service networks and component specialists supplying cells or power conversion hardware. Three archetypes prevail: Chinese-Korean cell producers with regional manufacturing footprints, Japanese industrial conglomerates with project development capabilities, and European system integrators bundling long-term service agreements. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with suppliers racing to localize production ahead of procurement timeline acceleration.
Within the integrated platform tier, Contemporary Amperex Technology Co. Limited and BYD Co. Ltd exemplify the Chinese manufacturing archetype with regional production positioning, while LG Chem Ltd represents Korean cathode technology specialization. These three anchors occupy positions across the premium-to-standard spectrum based on their respective high-nickel versus iron phosphate chemistry portfolios. Wartsila Oyj Abp and General Electric sit within the European-North American system integration tier, bundling engineering-procurement-construction contracts with extended performance warranties that state utilities increasingly mandate.
| Leading Market Players |
|---|
| GS Yuasa Corporation |
| Wartsila Oyj Abp |
| BYD Co. Ltd |
| SEC Battery Company |
| NGK Insulators Ltd |
| Contemporary Amperex Technology Co. Limited |
| LG Chem Ltd |
| NEC Corporation |
| General Electric |
| Others |
Value Chain & Pricing Dynamics
Electrochemical engineering talent concentration in China's Fujian and Jiangsu provinces compresses cell production labor costs, widening the pricing-tier spread between premium high-nickel cathode systems and standardized lithium iron phosphate platforms across ASEAN utility procurements.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility drives three-tier pricing structure across premium, standard, and economy levels. Premium tier absorbs high-nickel cathode R&D premiums and extended warranty bundling, while economy tier competes on pack-level cost per kilowatt-hour. Price differentiation hinges on certification grade against IEC 62933 and after-sales service coverage. Pricing pressure stems from raw material swings above 40% annually, compressing margins most acutely in the standard tier. Commercial and industrial buyers exhibit highest price sensitivity due to behind-the-meter ROI thresholds, whereas state utilities prioritize availability warranties over upfront cost.
Supply Chain Analysis
Workforce availability constraints in Indonesia's Batang and Karawang industrial zones extend project timelines for foreign cathode suppliers establishing joint venture manufacturing. Cell production concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Chinese chemical hubs. The supply chain draws from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability from shipping disruptions through the Strait of Malacca elevates inventory carrying costs for ASEAN buyers. Distribution runs through engineering-procurement-construction contractors bundling 15-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN energy storage procurement has shifted toward premium specifications as state utilities mandate guaranteed degradation curves and availability warranties, marking a late-cycle quality transition away from component-only transactions.
For Market Incumbents: Lock in service network density across Thailand's Eastern Economic Corridor and Vietnam's northern industrial provinces to defend against integrated platform competitors. Deepen backward integration into cathode precursor processing to satisfy Indonesia's 40% local content thresholds. Prioritize battery management system firmware certification cycles to compress 18-24 month grid code compliance timelines. For New Entrants and Emerging Players: Thailand's ERC renewable targets open a window for behind-the-meter commercial and industrial peak shaving deployments in manufacturing estates. Target Philippines export processing zones where grid reliability failures drive backup power investment with shorter payback horizons. Enter through power purchase agreement structures bundling storage with solar firming to bypass utility procurement committee consolidation. For Investors and Strategic Acquirers: Chinese-Korean cell producers with regional manufacturing footprints are the most active acquirer in this space, consolidating joint venture positions ahead of procurement acceleration. Target mid-cap system integrators with captive service networks and existing IEC 62933 certification pathways. Watch for lithium carbonate price stabilization as the inflection signal for long-term contract repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | Indonesia's Ministry of Energy and Mineral Resources mandates 40% domestic value-add for cell production eligibility. |
| Battery Management System Certification | Vietnam's EVN technical standards segment supplier eligibility by response time thresholds. |
| Integrated EPC Bundling | Thailand's state utilities consolidate awards under 15-year service agreements displacing component sales. |
| Cathode Precursor Processing | Foreign suppliers must localize chemical processing to maintain procurement eligibility under domestic manufacturing regulations. |
| Supercapacitor Port Electrification | Singapore's shallow-discharge cycling programs create million-cycle durability demand outside lithium-ion economics. |
Study Parameters
Coverage spans Indonesia, Thailand, Vietnam, Singapore, and the Philippines, with primary inputs from each market combined with secondary validation. The study triangulates bottom-up project pipelines with top-down utility procurement forecasts through interviews with PLN planning officers, EVN grid operators, ERC regulatory affairs leads, and EPC contractors executing Java-Bali interconnection upgrades. Secondary sources include IEA renewable integration reports, ASEAN power development plans, IEC 62933 certification databases, and customs data on cell import volumes.
Granularity-level modeling disaggregates revenue by product type, technology chemistry, end user contract structure, and application service category across the projection horizon. The analytical framework derives CAGRs from utility procurement timeline acceleration, renewable penetration curves, and local content enforcement trajectories. Industry-specific inputs include PLN distribution network upgrade schedules, Thailand's 30% renewable target compliance pathways, and Vietnam's frequency response standard tiering.
Revisions become necessary when lithium carbonate price volatility exceeds historical bands or when Indonesia's Ministry of Energy and Mineral Resources modifies local content enforcement thresholds. Forecasts reflect assumptions on joint venture formation timelines, grid code harmonization progress, and supercapacitor pilot funding continuity. Material deviation in raw material cost trajectories or regulatory enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Energy Storage Software Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Power Bank Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Long-Duration Energy Storage Market